
 Enterprise Mobility in Retail Market | 2026-2036
Enterprise Mobility in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Mobility in Retail Market Analysis
Cloud-native architecture is repositioning legacy on-premises retail infrastructure as merchants seek elastic compute for seasonal demand spikes. SAP SE leverages vertical integration across ERP and mobility middleware to sustain enterprise wallet share. Microsoft Corporation anchors cloud-based deployment pipelines through Azure Stack integrations. Zebra Technologies dominates ruggedized handheld manufacturing for warehouse and floor operations.
Enterprise mobility in retail encompasses software platforms, endpoint hardware, and network services that enable distributed store associates, warehouse staff, and delivery personnel to access corporate applications, inventory systems, and customer data through smartphones, tablets, and wearables. These systems typically integrate mobile device management protocols, zero-trust security frameworks, and API-driven application layers to synchronize real-time transactions across distributed retail footprints. Cloud-based deployment models are capturing the fastest expansion as retailers abandon capital-intensive server farms for consumption-based SaaS arrangements. Mobile device management solutions concentrate margin pools through recurring license structures, while security solutions command premium pricing amid escalating breach liabilities in payment card environments.
FCC guidelines govern wireless spectrum allocation for in-store IoT and handheld connectivity across US retail estates, while GDPR and the EU AI Act impose data residency and algorithmic transparency mandates on European operations. PCI DSS compliance requirements from the payment card industry further shape endpoint encryption standards and mobile payment terminal certifications. Stakeholders must weigh sovereign cloud requirements against latency-sensitive edge computing architectures as regulatory fragmentation deepens across major retail markets.
Market Dynamics
Cloud-native architecture is forcing a wholesale migration away from capital-intensive on-premises retail infrastructure toward consumption-based SaaS models that elasticize compute for seasonal demand spikes.
Growth Catalysts
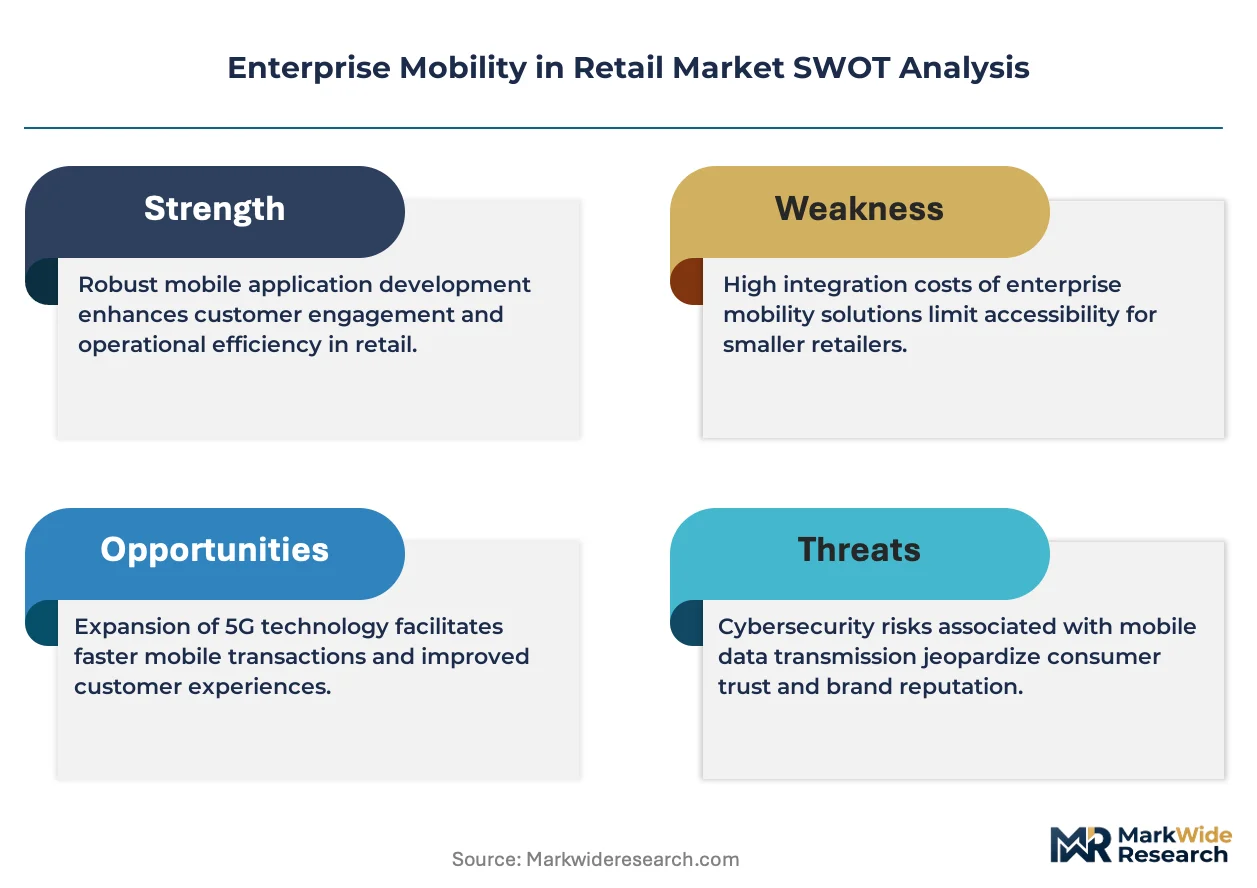
- EU AI Act compliance mandates:Algorithmic transparency requirements in European retail operations are accelerating investments in encrypted endpoint architectures and audit-ready mobility platforms.
- Specialty grocery workforce expansion:Mobile-first deployment strategies across high-touch food retail formats are driving unified endpoint management adoption for distributed store associates.
- Germany's retail technology corridor:Concentrated demand around Munich and Berlin is anchoring enterprise mobility solution development and localized vendor support infrastructure.
Market Restraints
- PCI DSS certification timelines:Payment card industry compliance requirements for mobile payment terminals impose extended validation cycles that delay deployment schedules.
- Semiconductor supply concentration:Ruggedized handheld processor fabrication depends on concentrated East Asian foundry capacity, creating vulnerability to geopolitical disruption.
- Legacy ERP integration friction:Proprietary middleware protocols in established retail systems resist API-driven synchronization with modern mobility platforms.
Strategic Opportunities
- Warehouse wearables convergence:Integration of voice-directed picking with augmented reality overlays is opening new efficiency layers in fulfillment center operations.
- Sovereign cloud mandates:GDPR data residency requirements are creating differentiated demand for EU-hosted mobility infrastructure with localized processing.
- Last-mile delivery unification:Gig-economy courier fleets represent an underpenetrated endpoint category for consolidated device management and route optimization.
Industry Challenges
- Zero-trust architecture skills scarcity:Implementation of continuous verification frameworks requires cybersecurity talent that retail IT organizations struggle to attract.
- Multi-vendor endpoint fragmentation:Heterogeneous device ecosystems complicate unified security policy enforcement and software update orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Mobility in Retail Market |
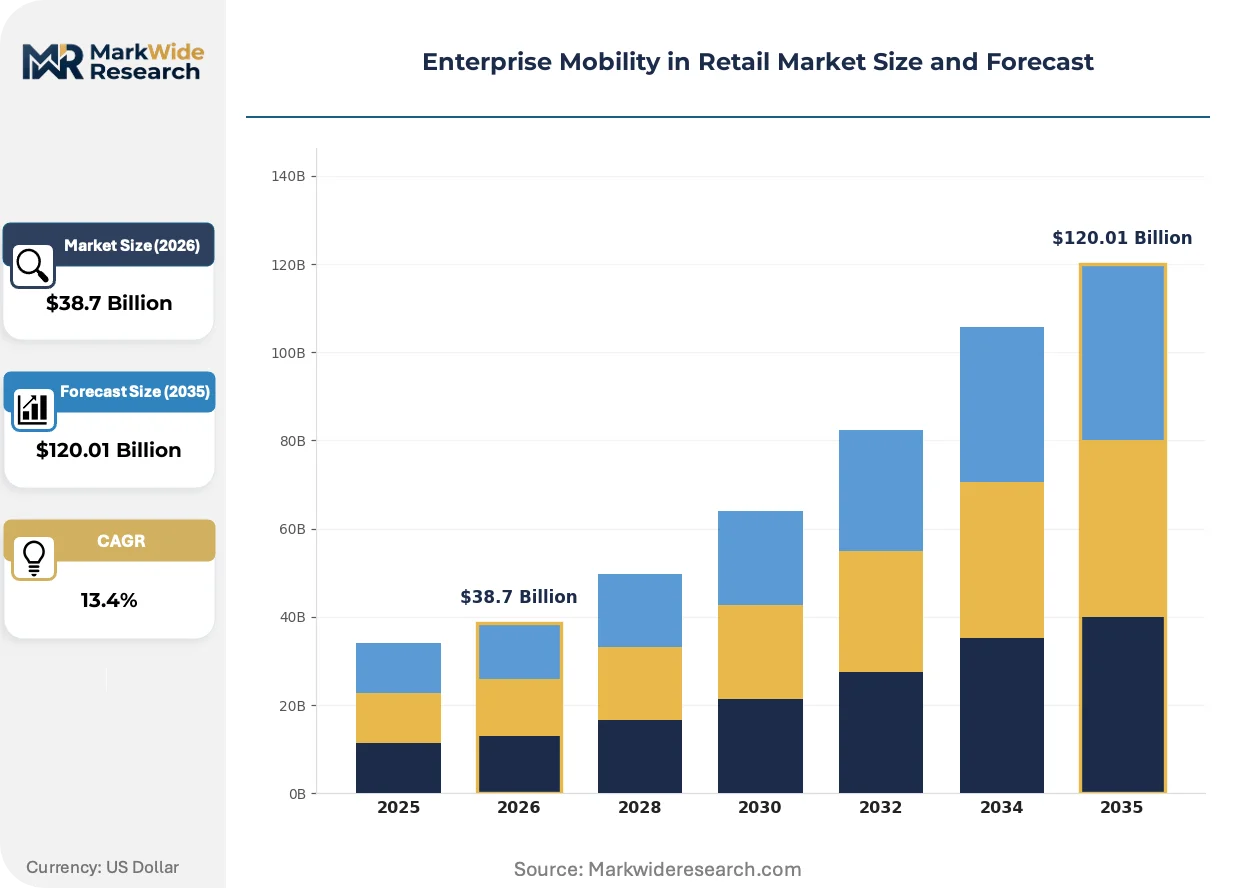
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $120.01 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual End User: Large Retail Chains, Small and Medium Enterprises, E-Commerce Platforms, Franchise Stores Solution Type: Mobile Device Management, Mobile Application Development, Communication Tools, Security Solutions Service Model: Managed Services, Professional Services, Training Services, Consulting Services |
| Companies Covered | SAP SE, VMware Inc., IBM Corporation, Salesforce, Citrix Systems Inc., Microsoft Corporation, Oracle Corporation, Zebra Technologies, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Mobility in Retail Market Emerging Trajectories
Edge computing architectures are compressing latency for real-time inventory visibility while API-driven application layers are decoupling front-end mobility experiences from back-end systems.
5G private network deployments are electrifying in-store connectivity for high-density IoT sensor arrays and streaming video analytics. Mass-market apparel retailers with complex floor plans are adopting these networks fastest. The technology is electrifying competitive positioning by enabling sub-10-millisecond response times for augmented reality fitting room applications.
GDPR Article 35 data protection impact assessments are mandating algorithmic audit trails for workforce management applications processing EU employee data. Retailers must document automated decision-making logic in scheduling and performance systems. German and French grocery chains are most affected, deploying consent management modules and localization controls.
Subscription-based mobility-as-a-service contracts are displacing perpetual license purchases among mid-market specialty retailers. Hardware refresh cycles bundle with MDM software and security services into single operational expenditure lines. This shift is most visible in Nordic markets where retailers prioritize balance sheet flexibility over asset ownership.
Enterprise Mobility in Retail Market Segmentation
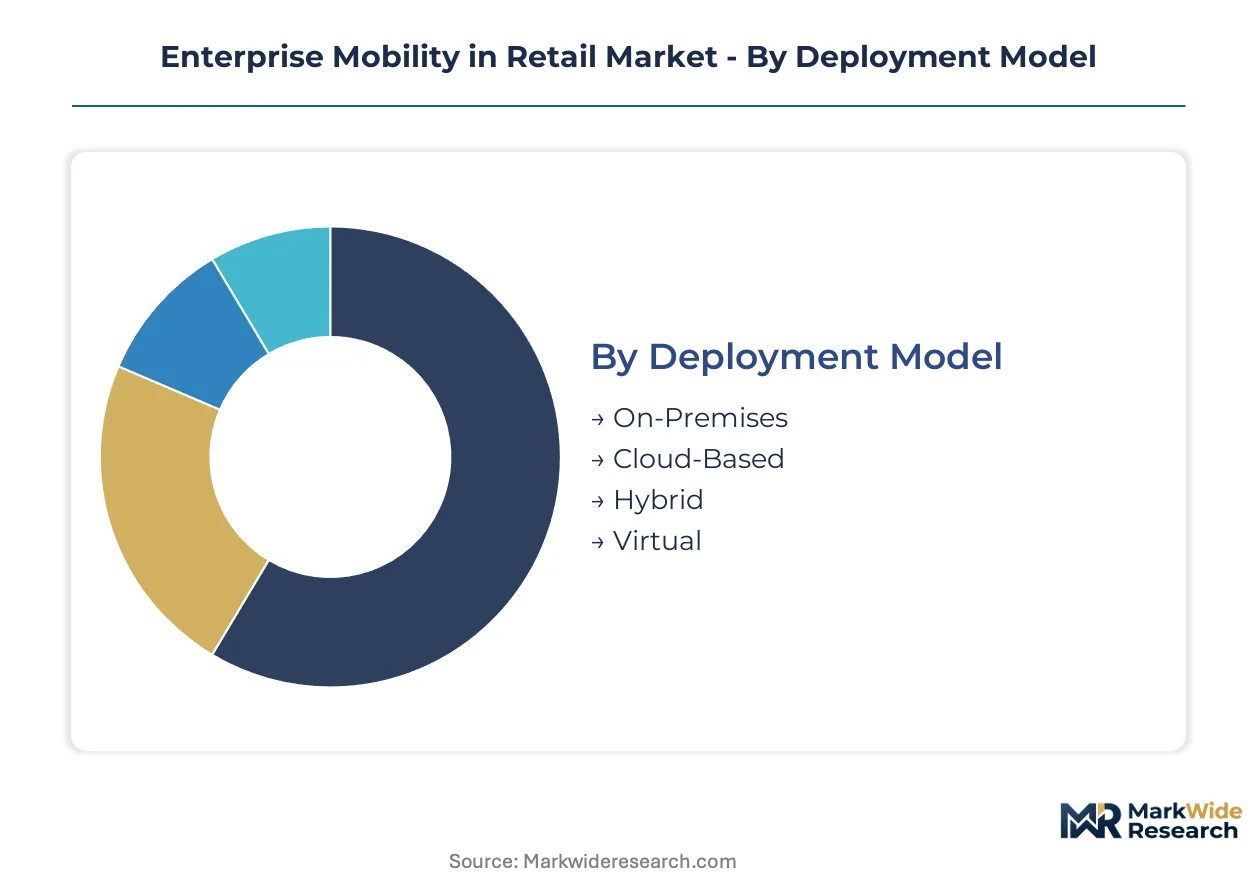
Enterprise mobility architectures fragment across deployment topologies, user scale, solution stacks, and service delivery modes. Each dimension imposes distinct procurement criteria and margin structures on vendors competing for retail technology budgets.
Deployment Model:
Standardization dominates at the infrastructure layer while customization intensifies at the application tier across deployment architectures.
- Cloud-Based:Multi-tenant SaaS platforms with elastic compute provisioning handle seasonal traffic surges without capital expenditure. German grocery chains around Munich and Berlin anchor concentrated demand here, driven by GDPR data residency requirements and the EU AI Act's algorithmic audit mandates.
- Hybrid:Split workloads maintain sensitive transaction processing on local nodes while customer-facing applications scale through public cloud. PCI DSS compliance timelines favor this architecture for mid-market retailers seeking certification flexibility without full on-premises burden.
- On-Premises:Dedicated server farms persist in legacy ERP environments with proprietary middleware protocols resisting API migration.
- Virtual:Containerized application layers abstract hardware dependencies for rapid endpoint provisioning across distributed store footprints.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations.
End User:
Procurement sophistication scales with organizational complexity and technology maturity across retail formats.
- Large Retail Chains:Enterprise-grade unified endpoint management spanning thousands of distributed associates, warehouse staff, and delivery personnel. Mass-market apparel retailers with complex floor plans drive 5G private network integration for augmented reality fitting room applications.
- E-Commerce Platforms:API-driven mobile application layers synchronize gig-economy courier fleets with real-time inventory visibility. Last-mile delivery unification represents underpenetrated endpoint density for consolidated device management.
- Small and Medium Enterprises:Subscription-based mobility-as-a-service contracts displace perpetual licenses, bundling hardware refresh with MDM software into single operational expenditure lines.
- Franchise Stores:Heterogeneous device ecosystems complicate unified security policy enforcement across independently operated locations.
Revenue concentration sits with Large Retail Chains. E-Commerce Platforms are climbing the fastest.
Solution Type:
Margin pools concentrate in recurring license structures and premium-priced security layers.
- Security Solutions:Zero-trust frameworks with continuous verification protocols command premium pricing amid escalating breach liabilities in payment card environments. Zero-trust architecture skills scarcity constrains implementation velocity.
- Mobile Device Management:Centralized policy orchestration, software update distribution, and remote wipe capabilities for heterogeneous smartphone, tablet, and wearable fleets. Recurring license structures dominate revenue recognition.
- Mobile Application Development:API-driven front-end experiences decoupled from legacy ERP back-ends through middleware integration.
- Communication Tools:Voice-directed picking integration with warehouse wearables enables augmented reality overlay efficiency in fulfillment centers.
Security Solutions capture the highest margin per endpoint. Mobile Device Management holds the largest installed base.
Service Model:
Delivery economics shift from project-based professional fees toward recurring managed service relationships.
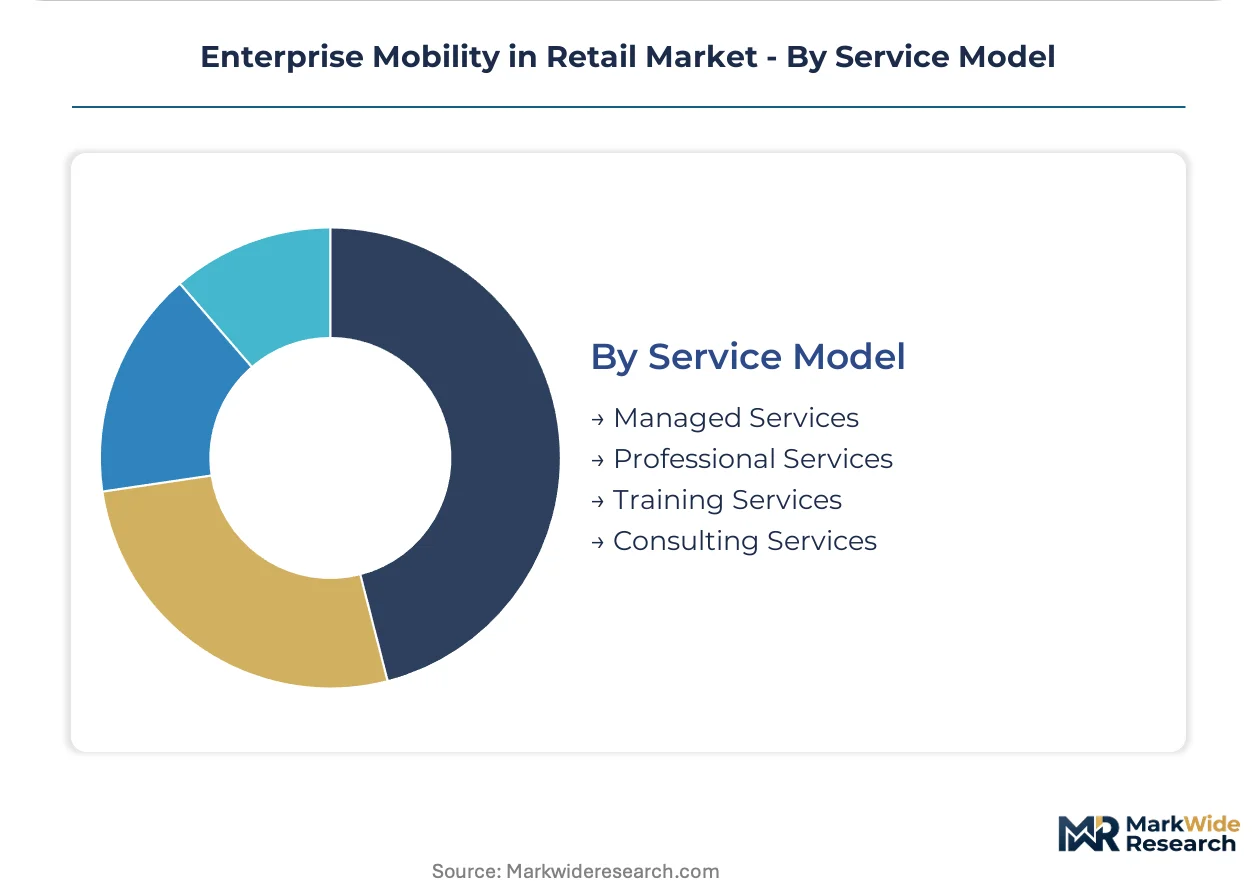
- Managed Services:Outsourced endpoint monitoring, patch management, and security operations center functions with subscription-based pricing. Nordic markets show the strongest preference for balance sheet flexibility over asset ownership.
- Professional Services:Custom integration of mobility platforms with proprietary ERP middleware and legacy inventory systems.
- Training Services:Workforce enablement for zero-trust architecture implementation and continuous verification framework operation.
- Consulting Services:GDPR Article 35 data protection impact assessments and algorithmic audit trail documentation for automated workforce management systems.
Managed Services account for the majority of recurring revenue. Professional Services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail technology corridor around Munich and Berlin anchors concentrated demand for enterprise mobility infrastructure, with specialty grocery chains and mass-market apparel retailers driving unified endpoint management adoption across the forecast period.
United States
Mass-market apparel retailers with complex floor plans are deploying 5G private networks for augmented reality fitting room applications. FCC guidelines govern wireless spectrum allocation for in-store IoT and handheld connectivity. The Pacific Northwest and Southeast regions concentrate cloud-native migration projects among mid-market specialty retailers.
Germany
Specialty grocery chains are expanding mobile workforce deployments with algorithmic transparency requirements under the EU AI Act. GDPR Article 35 data protection impact assessments mandate audit trails for workforce management applications. Munich and Berlin anchor the retail technology corridor where localized vendor support infrastructure is deepening.
United Kingdom
Subscription-based mobility-as-a-service contracts are displacing perpetual licenses among mid-market specialty retailers prioritizing balance sheet flexibility. The country's data protection framework enforces strict endpoint encryption standards for payment card environments. London and the Southeast concentrate managed services procurement for distributed store footprints.
France
German and French grocery chains are deploying consent management modules and localization controls for automated workforce scheduling systems. CNIL oversight reinforces GDPR algorithmic audit requirements for employee data processing. The Île-de-France region anchors enterprise mobility solution development for EU-hosted infrastructure with localized processing.
Japan
Cloud-based deployment models are capturing expansion as retailers abandon capital-intensive server farms for consumption-based SaaS arrangements. METI industrial policy supports edge computing architectures for real-time inventory visibility. The Kanto region around Tokyo concentrates ruggedized handheld procurement for warehouse and floor operations.
Enterprise Mobility in Retail Market Vendor Landscape
Global majors compete with regional champions across cloud infrastructure and endpoint hardware dimensions, producing a tiered structure where ERP-integrated platforms, cloud-native pipelines, and ruggedized device manufacturers occupy distinct margin pools. Consolidation pressure intensifies as retailers demand unified stacks spanning device management, security, and application layers. Two strategic archetypes dominate: vertically integrated software-hardware bundles and specialized point-solution vendors. Competitive moves center on backward integration into middleware protocols and geographic expansion through localized support infrastructure.
Within the integrated platform tier, SAP SE and Microsoft Corporation exemplify contrasting approaches to enterprise wallet share, with the former leveraging ERP-mobility vertical integration and the latter anchoring cloud-based deployment pipelines. Zebra Technologies occupies a position among ruggedized hardware specialists dominating warehouse and floor operations. These three anchors illustrate how vendor selection splits between comprehensive stack providers and dedicated endpoint manufacturers.
| Leading Market Players |
|---|
| SAP SE |
| VMware Inc. |
| IBM Corporation |
| Salesforce |
| Citrix Systems Inc. |
| Microsoft Corporation |
| Oracle Corporation |
| Zebra Technologies |
| Cisco Systems |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up mobility-as-a-service specialists anchor pricing discipline through subscription bundling that compresses hardware margins while securing recurring software revenue streams across German and Nordic retail estates.
Pricing Analysis
Input-cost pass-through from concentrated East Asian semiconductor fabrication feeds into ruggedized handheld pricing, with three-tier pricing structure across premium, standard, and economy levels differentiating by IP67 certification grade and after-sales service bundling. SaaS-tiered subscription models capture mid-market specialty retailers seeking balance sheet flexibility, while perpetual license holdouts among legacy ERP users show least price sensitivity. Cost compression in standard-tier devices is intensifying because foundry capacity constraints limit component availability.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific to EU distribution hubs complicates just-in-time delivery commitments for Munich and Berlin technology corridors. Ruggedized handheld manufacturing draws from Taiwan, South Korea, and China for processor and display components, with single-source vulnerability concentrated in advanced chipset fabrication. Distribution runs through vendor-managed inventory programs at major European logistics nodes, with localized assembly in Germany mitigating tariff exposure from transatlantic component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where GDPR data residency requirements in Germany and France impose cost premiums that Nordic subscription-based models circumvent through balance-sheet-flexible procurement structures.
For Market Incumbents: Extend cloud-native platform consolidation to capture mid-market retailers abandoning capital-intensive server farms, while backward integration into zero-trust security frameworks addresses skills scarcity constraining implementation velocity. SAP SE and Microsoft Corporation should deepen API-driven middleware control to resist point-solution disintermediation from emerging cloud-native specialists. For New Entrants and Emerging Players: EU AI Act algorithmic transparency mandates in Germany and France open a window for audit-ready mobility platforms with built-in consent management modules. Last-mile delivery unification for gig-economy courier fleets represents the most penetrable endpoint density, with route-optimization bundling as the primary go-to-market angle against fragmented device management incumbents. For Investors and Strategic Acquirers: Cloud infrastructure hyperscalers are the most active acquirer in this space, targeting API-driven application layer specialists that decouple front-end mobility from legacy ERP back-ends. Mid-cap vendors with EU-hosted sovereign cloud capabilities offer the strongest acquisition profile over the coming decade, with 5G private network deployment velocity serving as the critical inflection indicator for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Security Integration | PCI DSS compliance requirements from payment card industry mandate continuous verification frameworks for mobile payment terminals. |
| EU Sovereign Cloud Deployment | GDPR Article 35 data protection impact assessments require localized processing infrastructure for German grocery chains. |
| 5G Private Network Buildout | FCC spectrum allocation guidelines enable sub-10-millisecond response times for augmented reality fitting room applications in US apparel retail. |
| Warehousing Wearables Convergence | Voice-directed picking integration with augmented reality overlays unlocks efficiency layers in fulfillment center operations. |
| API-Driven Middleware Development | SAP SE leverages ERP-mobility vertical integration to sustain enterprise wallet share against cloud-native pipeline competitors. |
Methodological Framework
Bottom-up retail workforce modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with retail CIOs, store operations directors, MDM platform engineers, and hyperscaler solution architects combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory filings. Triangulation across deployment model, organization size, vertical specialization, and regional adoption patterns ensures segment-level accuracy.
Historical trendline analysis of cloud migration velocity and SaaS subscription penetration established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include deployment topology, end-user scale, solution stack composition, and service delivery mode, with CAGRs derived from elasticity coefficients for seasonal demand spikes and compliance-driven replacement cycles. EU AI Act implementation timelines and PCI DSS certification friction served as industry-specific forecast inputs.
Revisions become necessary when semiconductor supply disruptions, sovereign cloud mandate expansions, or zero-trust skills scarcity intensification materialize beyond baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Digital Kiosk Market
Retail Technology
E-Retail Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Self-Service Market
Retail Technology
Self-Checkout System Market