
 Smart Shopping Cart Market | 2026-2036
Smart Shopping Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Shopping Cart Market Insights
Supermarket checkout lanes is tilting toward autonomous scanning as labor costs and queue abandonment pressure conventional formats. Amazon leverages its Just Walk Out licensing model to extend computer vision infrastructure beyond proprietary stores into third-party retail footprints. Caper anchors its position through deep vertical integration into cart hardware and edge-computing modules, controlling both device manufacturing and firmware stacks. Shopic competes via clip-on retrofit solutions that minimize capital outlay for mid-sized grocery chains.
A smart shopping cart integrates multi-sensor arrays—weight scales, cameras, RFID readers, and Bluetooth beacons—into a mobile platform that automates item recognition, tallying, and payment during the shopping journey. The system eliminates stationary checkout bottlenecks while capturing real-time basket-level data for inventory and promotion optimization. Computer vision technology leads deployment volumes due to declining camera module costs and improving edge-AI inference accuracy on low-power processors. Self-checkout application dominates current installations, though personalized promotions represents the fastest-growing segment as retailers monetize basket-level behavioral data. Supermarkets occupy the largest end-user share, while warehouse clubs present concentrated margin pools given their higher transaction values and membership-driven repeat visitation.
The EU AI Act and GDPR impose algorithmic accountability and data minimization requirements on customer-tracking systems deployed in European retail environments. The FCC governs wireless spectrum allocation for cart connectivity protocols in the United States, while state-level biometric privacy laws in Illinois and California constrain facial recognition deployments. Stakeholders must monitor evolving compliance thresholds for AI transparency and consumer consent mechanisms as regulatory fragmentation across jurisdictions complicates scalable platform design.
Market Dynamics
Labor cost inflation across US supermarket chains is accelerating autonomous checkout deployment, while edge-AI inference cost curves are collapsing the hardware barrier to cart-scale computer vision.
Growth Catalysts
- EU AI Act compliance mandates:European retailers face algorithmic transparency requirements that favor explainable computer vision architectures over black-box alternatives, creating procurement pull for certified systems.
- RFID-vision sensor fusion:Hybrid recognition stacks combining camera arrays with passive RFID tags are improving fresh-produce identification accuracy where pure vision fails, expanding addressable SKU coverage.
- Mid-sized grocery chains:Regional operators with 50-200 locations represent concentrated deployment demand as they seek parity with national competitors without full-store retrofit costs.
Market Restraints
- Camera module supply concentration:Image sensor fabrication for edge-AI applications concentrates among East Asian foundries, exposing hardware vendors to geopolitical supply disruptions and capacity allocation constraints.
- Illinois BIPA biometric restrictions:State-level biometric privacy laws constrain facial recognition deployment for customer analytics, forcing architecture redesigns for national platform scalability.
- Stationary self-checkout substitution:Fixed-location scan-and-go terminals at lower per-lane capex compete for the same labor-reduction budget, particularly in smaller format stores.
Strategic Opportunities
- Warehouse club penetration:Costco and Sam's Club formats with high transaction values and membership data integration present margin-rich deployment targets underserved by current vendor priorities.
- Personalized promotion monetization:Real-time basket-level behavioral data enables dynamic pricing and targeted offers, creating recurring software revenue streams beyond hardware sales.
- India organized retail expansion:Reliance Retail and Tata-owned supermarket chains are modernizing supply chains, creating first-mover advantage for cart-scale automation in emerging organized grocery.
Industry Challenges
- Edge-AI firmware talent scarcity:Embedded computer vision optimization for low-power ARM processors requires specialized skill sets concentrated among semiconductor vendors and autonomous vehicle spinouts.
- POS integration complexity:Legacy supermarket transaction systems with decades-old payment protocol stacks demand custom middleware development for seamless cart-to-checkout data handoff.
- GDPR consent mechanism design:Continuous visual tracking of shoppers requires granular opt-in frameworks that preserve functionality while meeting European data minimization standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Shopping Cart Market |
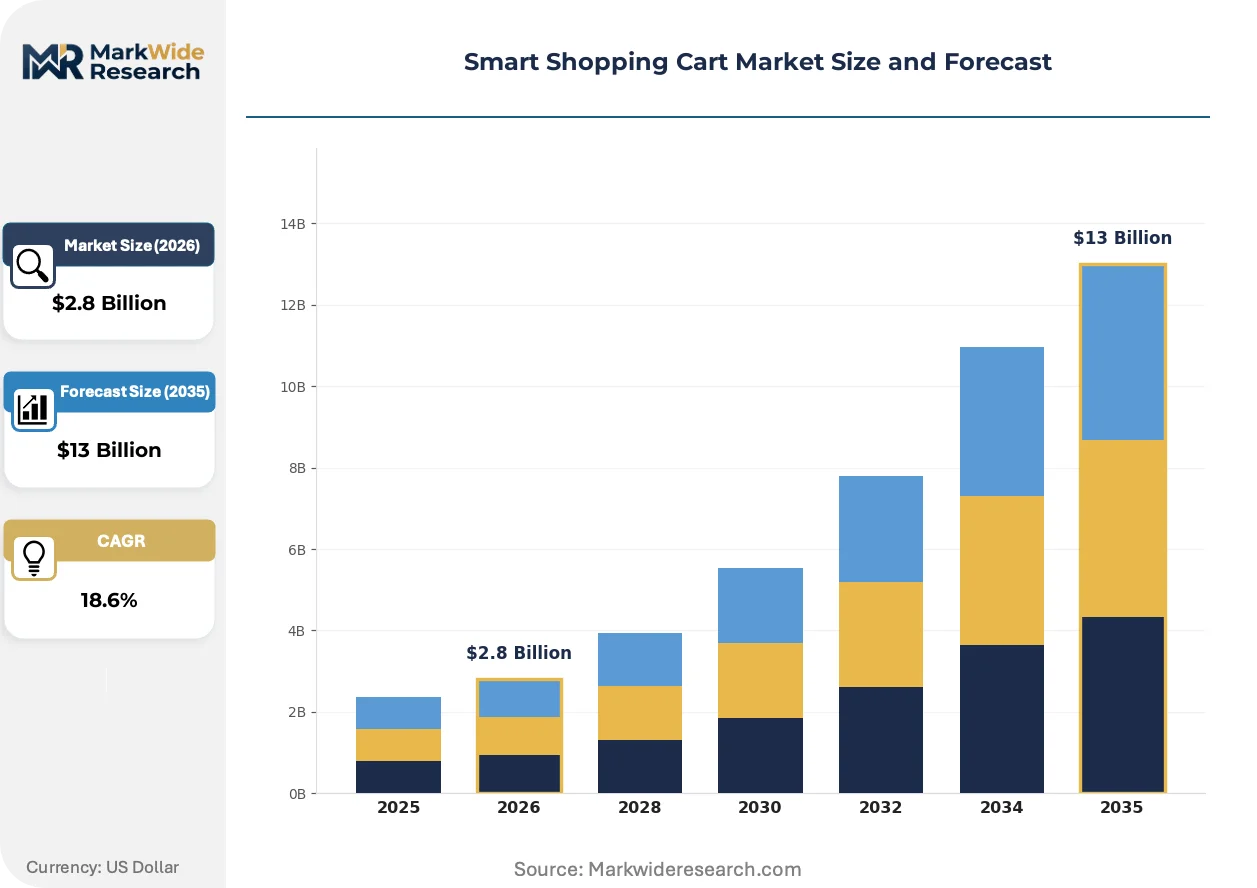
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Computer Vision, Weight Sensors, Barcode Scanning, AI Algorithms, Bluetooth Application: Self-Checkout, Inventory Management, Customer Analytics, Personalized Promotions, Contactless Payments, Shopping Assistance End User: Supermarkets, Hypermarkets, Convenience Stores, Specialty Stores, Warehouse Clubs, Drugstores Connectivity: Wi-Fi, 5G, NFC, Zigbee, Bluetooth Low Energy, LoRaWAN |
| Companies Covered | Caper, Amazon, Instacart, Shopic, SuperHii, Retail AI, Cust2Mate, Veeve, Shekel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Shopping Cart Market Trends and Innovations
Computer vision inference at the cart edge is collapsing the cost structure of real-time item recognition, while regulatory pressure on algorithmic accountability is reshaping vendor architecture choices.
Multi-sensor weight-scale arrays are collapsing the distinction between vision-only and RFID-dominant recognition systems. Regional grocers in the US Midwest are piloting these hybrid stacks for fresh produce sections where barcode coverage fails. The convergence is compressing hardware vendor margins while expanding total addressable SKU coverage beyond packaged goods.
The EU AI Act's risk-classification framework for biometric identification systems is forcing explainable AI module disclosure. European deployments now require interpretable decision trees for item recognition algorithms, favoring vendors with in-house model transparency tooling. German supermarket chains are demanding algorithmic audit trails as a procurement prerequisite, shifting competitive advantage toward vertically integrated software-hardware stacks.
Outcome-based hardware leasing is displacing upfront capex purchases among capital-constrained mid-market grocers. Third-party logistics providers are inserting themselves as fleet operators, bearing sensor maintenance and software update burdens. This model is concentrating in the United Kingdom where supermarket margin pressure from discounters limits discretionary technology investment.
Smart Shopping Cart Market Segmentation
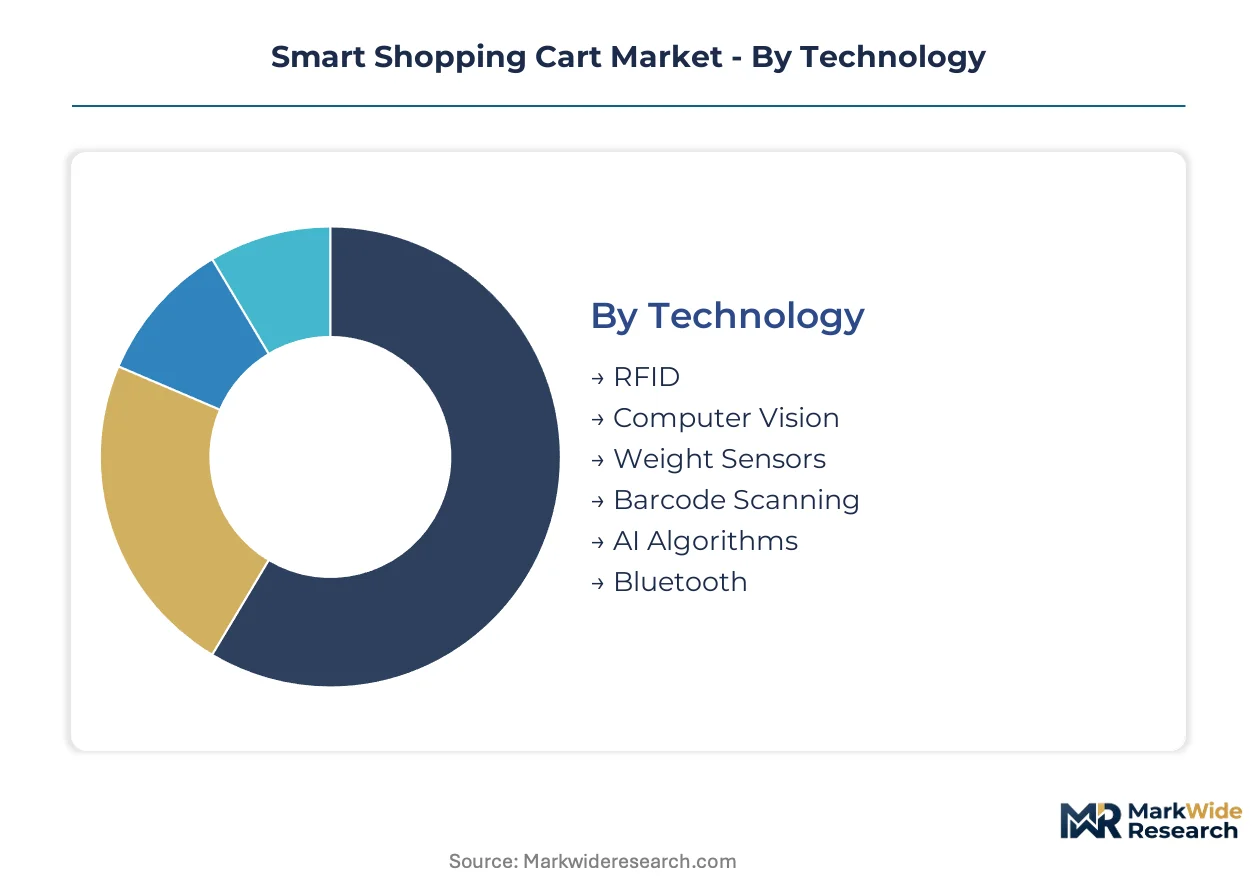
Smart shopping cart technology fragments across recognition modalities, retail formats, and network protocols. Each segmentation axis carries distinct capex profiles, integration complexity, and data governance requirements that shape procurement decisions.
Technology:
Mature scanning methods anchor current deployments while emerging AI-native stacks reshape vendor roadmaps.
- Computer Vision:Multi-camera arrays with edge-AI inference engines perform real-time item recognition without barcode dependency. Demand concentrates in United States supermarket chains seeking labor cost reduction, constrained by Illinois BIPA biometric restrictions on customer facial analytics.
- RFID:Passive tag readers integrated into cart chassis enable bulk scanning of tagged merchandise. European retailers under EU AI Act compliance mandates favor RFID-vision hybrids for algorithmic transparency and audit trail requirements.
- Weight Sensors:Load-cell arrays detect item additions and removals via mass differential.
- Barcode Scanning:Legacy laser or imager modules for manual item verification.
- AI Algorithms:Neural network stacks for sensor fusion and predictive basket analysis.
- Bluetooth:Short-range protocols for beacon-triggered location services.
Computer Vision handles the majority of throughput; AI Algorithms is the fastest mover on share.
Application:
Operational priorities shift from transaction automation toward behavioral monetization.
- Self-Checkout:End-to-end payment automation eliminating stationary lane queues. United States regional grocers with 50-200 locations deploy this as parity play against national competitors.
- Personalized Promotions:Real-time basket composition triggers dynamic pricing and targeted offers. Warehouse clubs in North America monetize membership data integration for margin expansion.
- Inventory Management:Shelf-edge discrepancy detection via cart-mounted sensors.
- Customer Analytics:Path tracking and dwell-time measurement for planogram optimization.
- Contactless Payments:Embedded NFC and QR code settlement.
- Shopping Assistance:Wayfinding and product location services.
Self-Checkout captures the dominant deployment volume; Personalized Promotions is expanding most quickly as retailers seek recurring software revenue.
End User:
Format scale and transaction velocity dictate sensor configuration and fleet economics.
- Supermarkets:Full-size grocery operators with 20,000+ SKUs and high foot traffic. United States chains accelerate pilot-to-rollout timelines as labor cost inflation compresses payback periods.
- Warehouse Clubs:Membership-driven formats with bulk transactions and repeat visitation patterns. Costco and Sam's Club present concentrated margin pools underserved by current vendor priorities.
- Hypermarkets:Big-box general merchandise plus grocery combinations.
- Convenience Stores:Small-format urban locations with limited basket sizes.
- Specialty Stores:Narrow-assortment retailers with premium positioning.
- Drugstores:Pharmacy-led formats with regulated product categories.
Supermarkets absorb the bulk of installed base; Warehouse Clubs is gaining share fastest on transaction value density.
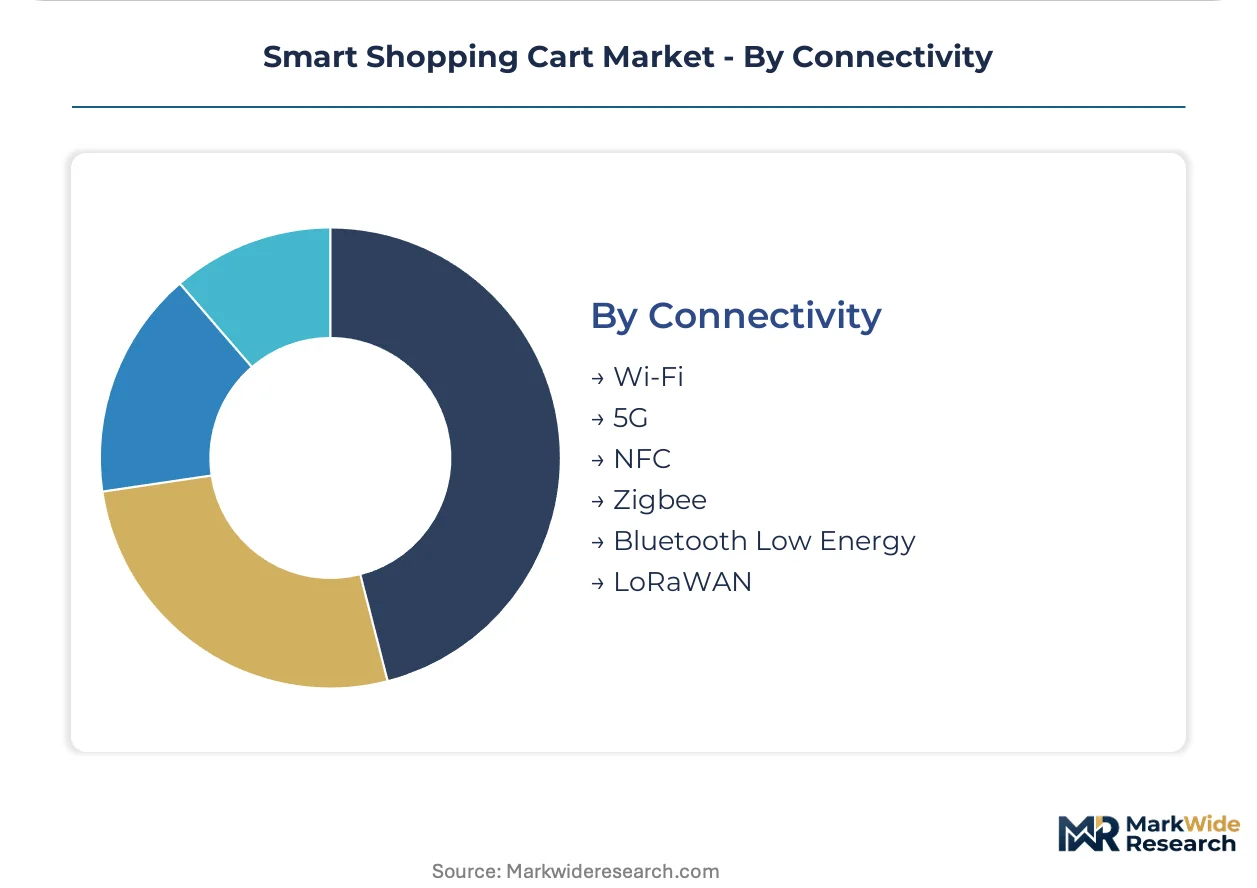
Connectivity:
Network selection trades bandwidth requirements against power consumption and infrastructure availability.
- Wi-Fi:High-throughput local area networking for video upload and software updates. Mature retail IT environments in North America standardize on this for indoor coverage reliability.
- 5G:Cellular low-latency links enabling cloud-heavy inference offloading. Emerging deployments in India organized retail expansion leverage this where fixed infrastructure is sparse.
- NFC:Proximity pairing for payment and device authentication.
- Zigbee:Mesh networking for sensor array synchronization.
- Bluetooth Low Energy:Ultra-low-power beacon and peripheral communication.
- LoRaWAN:Long-range low-bitrate protocols for parking lot and perimeter tracking.
Wi-Fi carries the majority of data traffic; 5G is climbing the fastest on edge-computing offload architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum allocation for wireless cart connectivity and state-level biometric privacy frameworks are accelerating deployment variance across national markets. Retail automation procurement concentrates where labor cost inflation intersects with permissive algorithmic regulation.
United States
Regional grocers with 50-200 locations are piloting computer vision carts to match national chain automation levels. Illinois BIPA restricts facial recognition analytics, forcing architecture redesigns for cross-state platform scalability. California retailers in the Bay Area and Los Angeles metro are testing hybrid RFID-vision stacks for fresh produce sections.
Germany
Supermarket chains under EU AI Act risk-classification mandates are demanding algorithmic audit trails for biometric identification systems. EFSA data governance guidelines intersect with GDPR consent frameworks for continuous shopper tracking. Retail automation clusters in the Rhine-Ruhr and Munich-Stuttgart corridors are prioritizing explainable AI procurement.
China
Organized retail expansion by Alibaba and JD.com subsidiaries is creating concentrated demand for edge-AI cart infrastructure. MIIT standards for wireless device certification shape connectivity module selection. Smart retail pilots in Shanghai and Shenzhen are integrating cart-scale automation with existing mobile payment ecosystems.
United Kingdom
Supermarket margin compression from German discounters is limiting discretionary technology investment, favoring outcome-based hardware leasing models. The Information Commissioner's Office enforces GDPR-aligned consent mechanisms for visual tracking systems. London and Southeast England retail clusters are experimenting with third-party logistics providers as fleet operators.
India
Reliance Retail and Tata-owned supermarket chains are modernizing supply chains, creating first-mover opportunity for cart-scale automation in emerging organized grocery. TRAI spectrum policy governs wireless connectivity for in-store device networks. Bangalore and Mumbai retail corridors are testing 5G-enabled edge-computing offload where fixed infrastructure remains sparse.
Smart Shopping Cart Market Competitive Landscape
On the supply side, the industry is bifurcating between vertically integrated hardware-software stacks and modular retrofit specialists. Tier-one vendors control cart manufacturing, firmware development, and cloud analytics platforms as a unified offering. Tier-two competitors clip sensor arrays onto existing cart fleets, minimizing capital outlay for mid-market retailers. Dominant competitive moves include technology licensing partnerships with cloud infrastructure providers and strategic alliances with regional logistics operators for fleet-as-a-service deployment.
Within the integrated hardware tier, Caper anchors positioning through captive control over device manufacturing and edge-computing modules. Amazon extends its Just Walk Out licensing model beyond proprietary stores into third-party retail footprints, exemplifying platform-scale distribution. Shopic occupies the retrofit-specialist vector, offering clip-on solutions that reduce upfront capital requirements for regional grocery chains with constrained technology budgets.
| Leading Market Players |
|---|
| Caper |
| Amazon |
| Instacart |
| Shopic |
| SuperHii |
| Retail AI |
| Cust2Mate |
| Veeve |
| Shekel |
| Others |
Pricing and Supply Chain Analysis
East Asian image sensor foundries concentrating CMOS fabrication for edge-AI applications capture disproportionate margin upstream, while downstream pricing power accrues to supermarket chains with fleet-scale deployment leverage and outcome-based leasing negotiators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers bundling explainable AI certification and predictive maintenance while economy tiers strip out sensor fusion capabilities. Price differentiation hinges on computer vision accuracy certification and after-sales firmware update commitments. Cost compression in mid-market hardware is intensifying because retrofit clip-on vendors are collapsing entry barriers. Regional grocery chains with 50-200 locations exhibit highest price sensitivity, whereas warehouse club operators prioritize total cost of ownership over unit capex.
Supply Chain Analysis
Taiwanese and South Korean EMS providers hold concentrated contract-manufacturing capacity for edge-computing modules and camera array assembly. Component sourcing draws from Chinese PCB fabrication, Japanese precision optics, and German load-cell engineering. Single-source vulnerability in ARM-processor allocation from semiconductor vendors exposes hardware vendors to capacity rationing. Distribution runs through direct OEM relationships with tier-one retailers and third-party logistics fleet operators in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping vendor viability as interoperability standards and ecosystem consolidation favor unified hardware-software stacks over modular point solutions.
For Market Incumbents: Pre-empt margin erosion from retrofit specialists by deepening in-house production of edge-AI firmware stacks and securing exclusive POS integration middleware contracts with legacy supermarket chains. Vertical control over sensor calibration and cloud analytics platforms preserves pricing power against clip-on competitors.
For New Entrants and Emerging Players: Pursue warehouse club deployments in North America, where transaction value density and membership data integration create margin-rich opportunities underserved by current vendor priorities. White-space exists in 5G-enabled edge-computing offload architectures for Indian organized retail expansion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed retrofit specialists possessing established grocery chain relationships but lacking firmware development capabilities. Long-term viability favors vertically integrated stacks with algorithmic transparency tooling for EU AI Act compliance. Monitor Illinois BIPA enforcement patterns as signal for national scalability constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Certification Investment | EU AI Act audit trail requirements favor vendors with in-house model transparency tooling. |
| Hybrid Sensor Fusion Development | RFID-vision weight-scale convergence expands fresh-produce SKU coverage beyond packaged goods. |
| Outcome-Based Fleet Leasing Expansion | UK supermarket margin compression from German discounters drives third-party logistics operator partnerships. |
| POS Middleware Integration | Legacy payment protocol stacks demand custom development for seamless cart-to-checkout data handoff. |
| 5G Edge-Computing Architecture Deployment | Indian organized retail expansion leverages cellular offload where fixed infrastructure remains sparse. |
Research Methodology
Operator-level perspectives from supermarket technology procurement officers, edge-AI firmware engineers, retail logistics fleet managers, and grocery chain operations executives anchored the qualitative base. Primary interview insights combined with secondary validation from FCC spectrum allocation filings, EU AI Act implementation guidance, supermarket chain SEC 10-K technology expenditure disclosures, and customs records for image sensor import flows. Bottom-up unit deployment estimates triangulated against top-down retail automation capex aggregates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across recognition modality, retail format scale, and regional regulatory cluster. CAGRs derived from weighted-average technology diffusion curves and supermarket labor cost inflation assumptions. Edge-AI inference cost decline trajectories and camera module pricing trends served as hardware penetration inputs.
Macroeconomic conditions sit as an overlay; deviation in supermarket employment cost indices and East Asian semiconductor capacity allocation would shift the trajectory. Forecasts reflect documented assumptions on EU AI Act enforcement timing and Illinois BIPA litigation patterns. Cross-checking against FCC equipment authorization databases and retail technology trade show announcement flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
US Retail Recon Software Market
Retail Technology
Global Smart Retail Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Cash Register Machines Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Self-Service Market
Retail Technology
Smart Shelf Market
Retail Technology
Ticket Machine Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Global Kiosk Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Smart Shelves Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Digital Kiosk Market
Retail Technology
Retail Sourcing and Procurement Market