
 Data-Driven Retail Solution Market | 2026-2036
Data-Driven Retail Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Data-Driven Retail Solution Market Outlook
The United States is fragmenting as cloud providers and enterprise software vendors expand regional data center capacity to serve latency-sensitive retail workloads. Microsoft leverages its Azure infrastructure to anchor large-format grocery chains requiring real-time inventory synchronization. SAP SE competes through specialized ERP modules that dominate European fashion retail planning workflows. Teradata Corporation sustains its position in on-premise big-data warehousing for electronics retailers with strict data residency requirements.
Data-driven retail solutions integrate predictive analytics engines, IoT sensor feeds, and cloud-native architectures to automate merchandising decisions across physical and digital storefronts. These systems process transaction streams, footfall patterns, and supply chain signals to generate demand forecasts with sub-hour refresh cycles. Customer analytics captures the largest margin pool as retailers prioritize lifetime-value modeling over transactional reporting. Machine learning within pricing optimization represents the fastest-expanding technology segment as dynamic markdown engines displace static seasonal calendars.
The EU AI Act, GDPR, and ISO 27001 collectively shape product roadmaps by mandating explainable algorithms, consent-based data retention, and certified information-security management for cross-border retail analytics. The Federal Trade Commission in the United States enforces consumer-protection standards that constrain opaque behavioral targeting in e-commerce personalization. Stakeholders must monitor evolving algorithmic-accountability frameworks as jurisdictions race to define liability boundaries for autonomous pricing decisions.
Market Dynamics
Machine learning is collapsing the refresh cycles of demand forecasting from weekly batches to sub-hourly inference, compressing merchandising decision windows and forcing infrastructure upgrades across grocery, fashion, and electronics retail.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated pricing systems must now provide explainable decision trails, creating upgrade demand for compliant analytics platforms in European supermarkets and fashion chains.
- IoT sensor density in perishables cold chains:Real-time spoilage monitoring drives predictive markdown engines that cut waste by double-digit percentages in large-format grocery operations.
- Cloud data center expansion:Microsoft, Amazon, and Google are building regional capacity in Germany, France, and the Netherlands to serve latency-sensitive inventory synchronization workloads.
Market Restraints
- GDPR consent-based data retention:Cross-border customer analytics face operational friction as EU member states interpret lawful basis requirements differently, complicating unified data lake architectures.
- On-premise legacy warehouse lock-in:Electronics retailers with strict data residency requirements maintain Teradata and Oracle installations that resist cloud migration despite higher total cost of ownership.
- AI/ML talent scarcity:Retailers compete with financial services and technology vendors for data scientists capable of productionizing demand forecasting models at scale.
Strategic Opportunities
- India's fragmented kirana store digitization:Local language voice interfaces and low-bandwidth mobile analytics can capture the country's twelve million independent retailers currently underserved by enterprise platforms.
- Fashion rental and resale circularity:Reverse logistics analytics and authentication AI create new revenue streams for European luxury and mid-market apparel brands facing sustainability disclosure requirements.
- Edge computing convergence with computer vision:Shelf-mounted cameras running on-device inference enable real-time planogram compliance without cloud round-trips, cutting bandwidth costs for high-SKU-density formats.
Industry Challenges
- ISO 27001 certification timelines:Cross-border retail analytics vendors face six-to-twelve month audit cycles that delay enterprise customer onboarding and compress sales velocity.
- ERP integration complexity:SAP and Oracle legacy modules require custom API development to ingest real-time IoT feeds, inflating implementation costs and extending project timelines.
- Algorithmic accountability liability:Jurisdictions including the United States, Germany, and Singapore are drafting divergent standards for autonomous pricing errors, creating compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data-Driven Retail Solution Market |
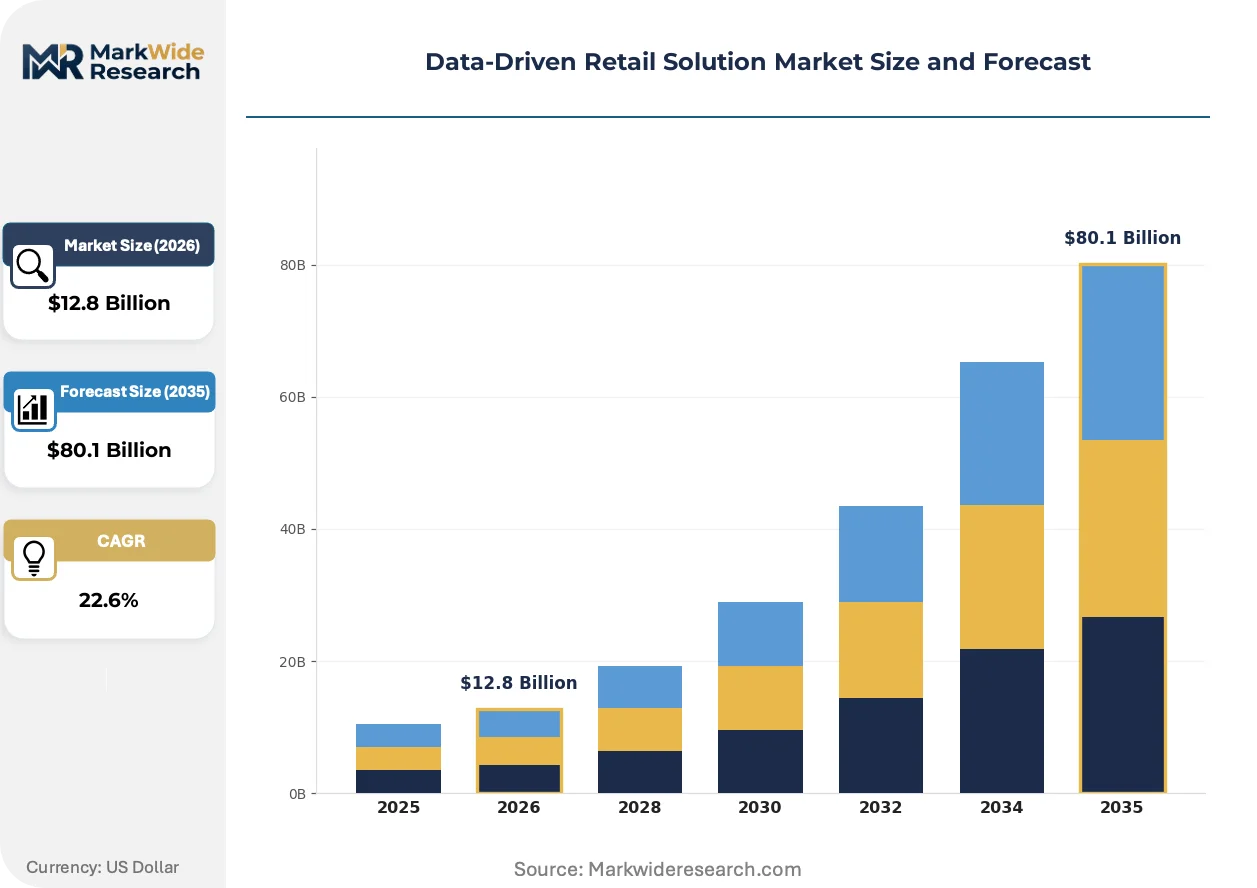
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $80.1 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Customer Analytics, Inventory Management, Pricing Optimization, Sales Forecasting End User: Supermarkets, E-Commerce, Fashion Retailers, Electronics Stores Technology: Artificial Intelligence, Machine Learning, Big Data, Cloud Computing Distribution Channel: Online Sales, Direct Sales, Partnerships, Resellers |
| Companies Covered | Microsoft, IBM, Oracle, SAP SE, Salesforce, Adobe, Tata Consultancy Services Limited, Teradata Corporation, RetailNext Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data-Driven Retail Solution Market Strategic Shifts
Retail analytics is shifting from retrospective reporting to anticipatory orchestration, with three forces compressing decision latency, tightening compliance boundaries, and rewiring buyer-vendor relationships.
Edge-deployed computer vision is collapsing the gap between physical shelf events and system awareness. Cameras with on-device neural processing detect stockouts, misplaced items, and competitor pricing within seconds rather than hours. Mass-market grocery chains in the United Kingdom and South Korea are deploying these systems across high-traffic categories, eliminating the labor cost of manual shelf audits while generating training data for predictive replenishment models.
Regulators in Brussels have finalized algorithmic accountability requirements under the EU AI Act that classify dynamic pricing engines as high-risk automated decision systems. Retailers operating in France, Germany, and Italy must now maintain technical documentation, human oversight protocols, and bias monitoring for markdown optimization tools. Compliance investments are diverting analytics budgets from model accuracy improvements toward audit trail infrastructure and legal review.
Merchandise planning teams are compressing vendor evaluation cycles from annual RFPs to continuous pilot programs. Buyers in United States sporting goods and home improvement segments now demand ninety-day proof-of-concept deployments with guaranteed forecast accuracy benchmarks before committing to multi-year contracts. This pattern forces analytics vendors to absorb upfront implementation costs and shifts commercial risk toward solution providers.
Data-Driven Retail Solution Market Segmentation
Retail analytics platforms fragment across multiple technical and commercial dimensions. Vendors must align product architecture with specific workload latency requirements, regulatory exposure, and buyer procurement maturity.
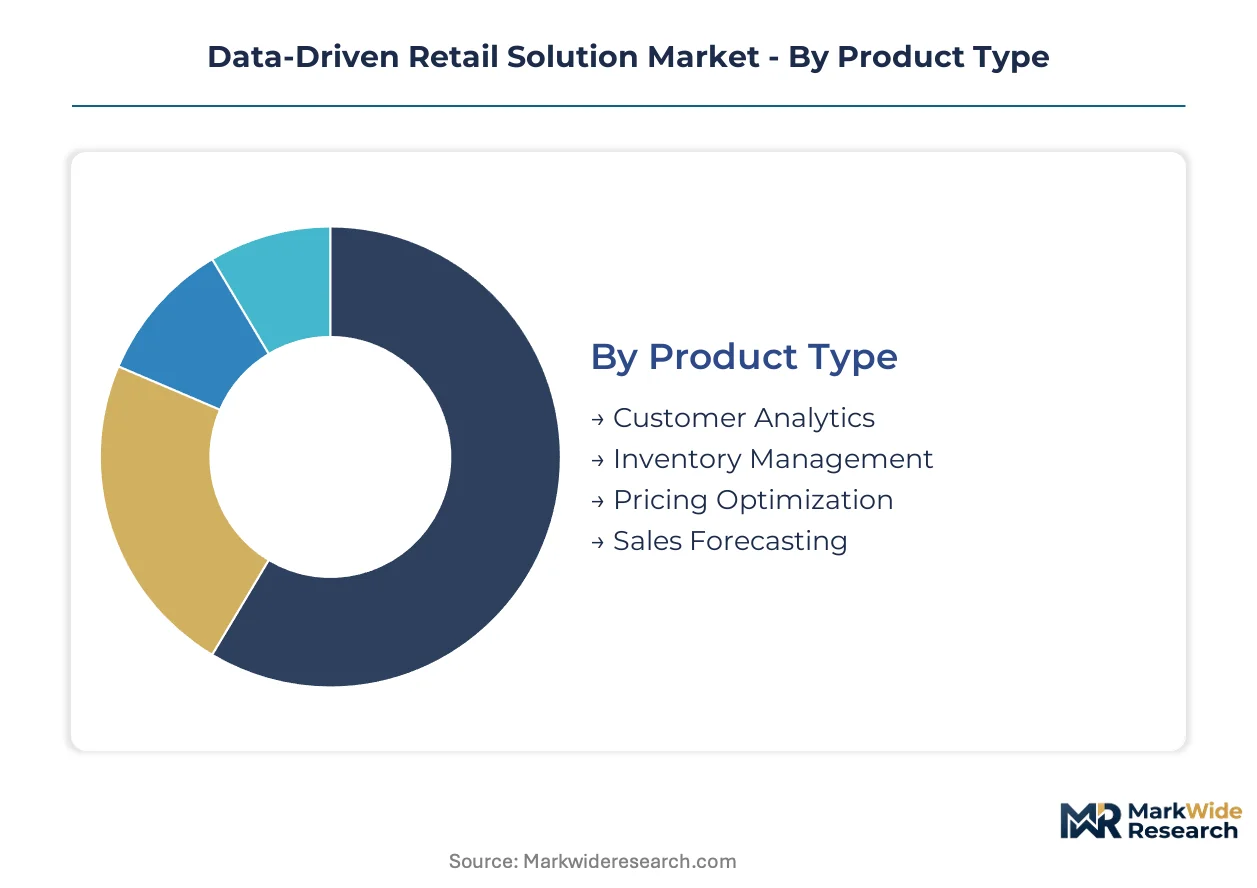
Product Type:
Mature demand forecasting tools coexist with emerging autonomous pricing engines as retailers balance proven ROI against competitive differentiation.
- Customer Analytics:Lifetime-value modeling engines process transaction histories, web behavior, and loyalty signals to predict churn probability and next-best-action recommendations. Demand concentrates in United States e-commerce operations where the FTC constrains opaque behavioral targeting, forcing explainable model architectures.
- Pricing Optimization:Dynamic markdown engines ingest competitor price feeds, inventory aging curves, and demand elasticity coefficients to automate discount timing and depth. European supermarkets deploy these systems under EU AI Act transparency mandates that require auditable decision trails for high-risk automated pricing.
- Inventory Management:Real-time stock positioning systems balance shelf availability against working capital constraints.
- Sales Forecasting:Statistical models projecting revenue trajectories across product hierarchies and geographic clusters.
Customer Analytics handles the majority of throughput; Pricing Optimization is expanding most quickly as static seasonal calendars yield to algorithmic markdown engines.
End User:
Volume concentration tilts toward grocery and digital-native retail while fashion and electronics segments exhibit divergent data residency requirements.
- Supermarkets:Large-format grocery chains deploy shelf-mounted computer vision and IoT cold-chain sensors to synchronize perishables replenishment with real-time spoilage risk. United Kingdom and South Korean operators lead deployment density, cutting waste through predictive markdown automation.
- E-Commerce:Digital-native retailers operate cloud-native personalization stacks with sub-second inference latency for recommendation engines. These buyers prioritize continuous A/B testing infrastructure and real-time customer journey orchestration across mobile and web touchpoints.
- Fashion Retailers:Seasonal demand volatility drives specialized size-pack optimization and markdown cadence tools.
- Electronics Stores:Strict data residency requirements sustain on-premise deployments despite higher total cost of ownership.
Supermarkets anchor current procurement volume; E-Commerce is climbing the fastest on technology refresh cycles.
Technology:
Deployment patterns separate proven statistical methods from frontier deep-learning architectures based on data infrastructure maturity and talent availability.
- Machine Learning:Gradient-boosted demand models and neural pricing engines collapse forecasting refresh cycles from weekly batches to sub-hourly inference. Grocery chains in Germany and France upgrade infrastructure to serve these latency-sensitive workloads under tightened EU AI Act compliance timelines.
- Cloud Computing:Elastic compute and managed ML platforms enable rapid model experimentation without capital-intensive hardware procurement. Microsoft, Amazon, and Google expand regional data center capacity to capture retail workloads requiring low-latency inventory synchronization.
- Artificial Intelligence:Autonomous decision systems for merchandising and customer engagement.
- Big Data:Distributed storage and processing architectures for petabyte-scale transaction archives.
Cloud Computing captures the dominant share of new infrastructure spend; Machine Learning is gaining share fastest as production model deployment accelerates.
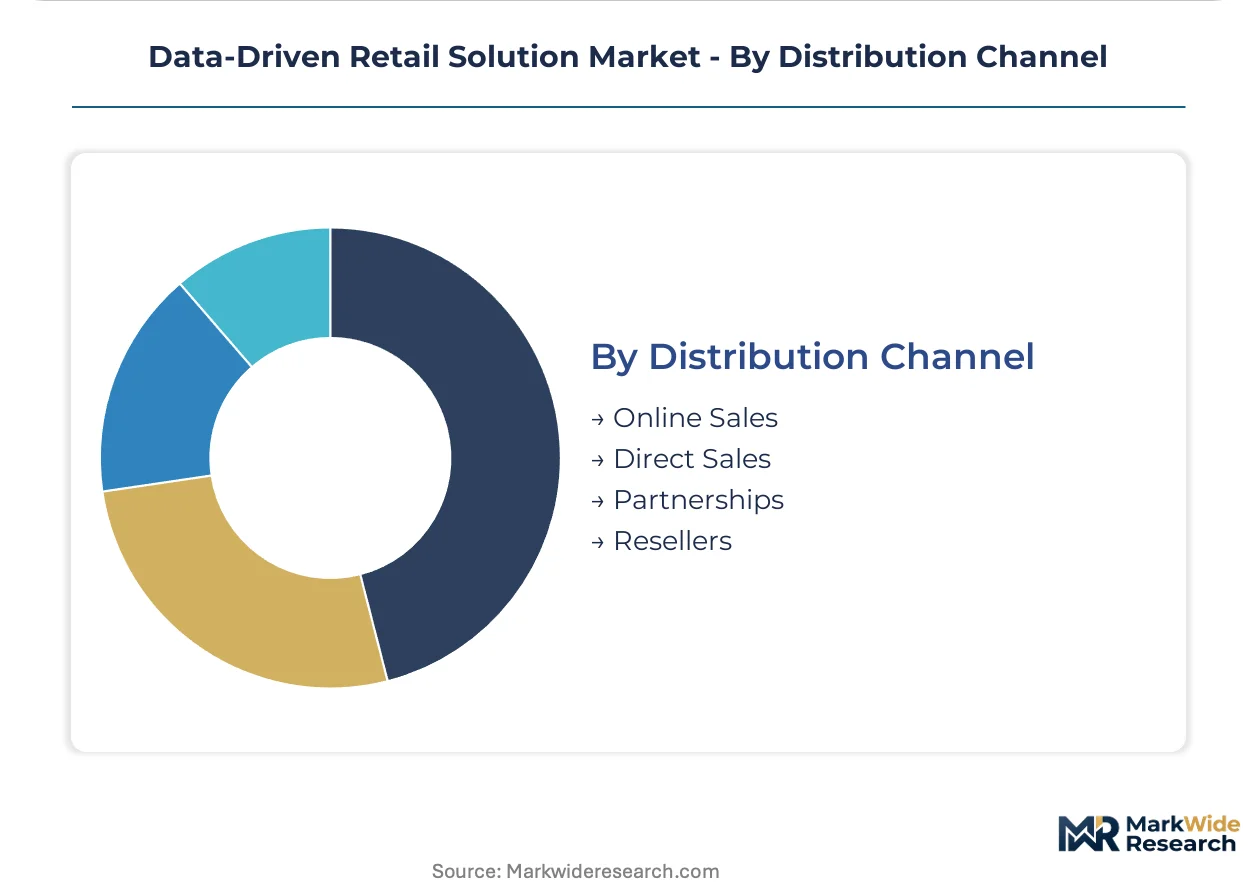
Distribution Channel:
Route-to-market strategies diverge between enterprise direct engagement and ecosystem-mediated access to mid-market buyers.
- Direct Sales:Enterprise field teams engage multinational retail chains with complex integration requirements and extended procurement cycles. SAP and Oracle cultivate these relationships through specialized ERP modules that dominate European fashion retail planning workflows.
- Partnerships:Strategic alliances with systems integrators and cloud hyperscalers accelerate time-to-value for buyers lacking internal data engineering capacity. These arrangements shift implementation risk toward vendors while expanding addressable market reach.
- Online Sales:Self-service procurement of standardized analytics modules through vendor marketplaces.
- Resellers:Regional value-added distributors serving language-specific market segments.
Direct Sales manages the largest contract value concentration; Partnerships is the fastest mover on deal velocity as cloud marketplaces mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States retailers prioritize real-time personalization infrastructure while European operators navigate algorithmic transparency mandates. Asian markets emphasize cost-efficient digitization of fragmented traditional trade.
United States
Cloud hyperscalers anchor retail IT procurement as Walmart and Target demand sub-second inventory synchronization. The FTC enforces consumer-protection standards that constrain opaque behavioral targeting in e-commerce personalization. Seattle and San Francisco Bay Area clusters concentrate vendor engineering talent for demand forecasting platforms.
Germany
EU AI Act compliance timelines accelerate infrastructure upgrades for algorithmic pricing transparency. The Federal Cartel Office scrutinizes automated markdown engines for competitive fairness. Berlin and Munich host specialized ERP integrators serving fashion retail planning workflows.
United Kingdom
Tesco and Sainsbury's deploy shelf-mounted computer vision for real-time planogram compliance. The Information Commissioner's Office enforces GDPR consent requirements for customer analytics data lakes. London anchors fintech-retail convergence ventures targeting unified commerce platforms.
India
Twelve million kirana stores drive demand for low-bandwidth mobile analytics and voice interfaces in local languages. The Digital India program subsidizes cloud adoption for small retailers. Bangalore and Mumbai clusters host systems integrators adapting enterprise platforms for fragmented traditional trade.
South Korea
Emart and Lotte Mart lead deployment density for IoT cold-chain spoilage monitoring. The Ministry of Trade, Industry and Energy funds edge computing pilots for in-store computer vision. Seoul metropolitan retailers compress merchandising decision windows through sub-hourly demand forecasting refresh cycles.
Data-Driven Retail Solution Market Competitive Environment
Capability concentration sits with specialized analytics vendors; scale advantage sits with cloud hyperscalers and enterprise software incumbents. The market structures around three tiers: infrastructure platforms providing elastic compute, application specialists delivering vertical-specific forecasting modules, and systems integrators bridging legacy ERP to modern data pipelines. Consolidation pressure intensifies as procurement teams demand bundled analytics-infrastructure offerings. Partnership velocity accelerates between cloud providers and boutique forecasting shops.
Within the enterprise software tier, Microsoft exemplifies infrastructure-led expansion through Azure retail workloads, while SAP SE occupies a position as the European fashion planning incumbent. Teradata Corporation represents the on-premise data warehousing archetype serving electronics retailers with strict data residency requirements.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Oracle |
| SAP SE |
| Salesforce |
| Adobe |
| Tata Consultancy Services Limited |
| Teradata Corporation |
| RetailNext Inc. |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber-optic cable routes connecting Seattle to Tokyo and Singapore carry the bulk of real-time retail data traffic, with bandwidth cost differentials between these corridors directly shaping where cloud providers concentrate compute capacity and how analytics vendors tier subscription pricing across customer segments.
Pricing Analysis
Geographic price spreads of forty to sixty percent separate North American enterprise deployments from equivalent configurations in Southeast Asia, reflecting differential labor costs for implementation services and localized regulatory compliance overhead. The dominant structure is tiered SaaS subscription, with pricing stratifying across premium, standard, and economy tiers based on data volume throughput and model refresh frequency. Price differentiation hinges on ISO 27001 certification status and geographic data residency guarantees. Pricing pressure stems from hyperscaler marketplace commoditization of baseline forecasting modules. Mid-market grocery chains exhibit highest price sensitivity; multinational luxury retailers show lowest.
Supply Chain Analysis
Export control regimes under the U.S. Commerce Department's Entity List restrictions limit advanced GPU shipments to certain cloud regions, constraining where training-intensive neural pricing engines can deploy. Hardware supply concentrates in Taiwan, South Korea, and the United States for edge inference accelerators. Software components draw from open-source ML frameworks, proprietary optimization libraries, and specialized computer vision models. Single-source vulnerability sits with NVIDIA's dominance in training silicon. Distribution runs through direct enterprise sales for large contracts, hyperscaler marketplaces for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough as retailers accelerate IT modernization budgets following post-pandemic inventory destocking cycles, with replenishment analytics representing the first recovery category.
For Market Incumbents: Entrench position through backward integration into edge hardware manufacturing, capturing margin from shelf-mounted camera deployments while locking out pure-software challengers. Deepen API standardization with SAP and Oracle legacy ERP modules to inflate switching costs for enterprise accounts. The threat is hyperscaler vertical integration of forecasting tools into base cloud subscriptions. For New Entrants and Emerging Players: India's twelve million kirana stores with voice-first, low-bandwidth analytics requirements represent the most penetrable entry point for platform-native challengers unburdened by legacy codebases. European mid-market fashion retailers facing EU AI Act compliance deadlines without internal data science teams offer second-tier opportunity. Go-to-market should route through mobile network operator bundles, leveraging existing small-business trust relationships. For Investors and Strategic Acquirers: The EU AI Act's high-risk system classification reshapes the acquisition landscape by rendering non-compliant target pipelines unviable for cross-border rollup strategies. Long-term viability favors vendors with certified information-security management and explainable model architectures already deployed. The signal to watch is enforcement velocity by national regulators in Germany and France, which will determine compliance cost trajectories and competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Integration | On-device inference cuts cloud round-trip latency for real-time shelf analytics at Tesco and Emart. |
| EU AI Act Compliance Certification | Technical documentation and bias monitoring capabilities unlock procurement at Carrefour and Ahold Delhaize. |
| Hyperscaler Marketplace Listing | Azure and AWS marketplace presence accelerates mid-market customer acquisition without field sales overhead. |
| Legacy ERP API Development | Native SAP and Oracle connectors reduce implementation timelines for European fashion retail planning workflows. |
| Voice-First Mobile Analytics | Local language interfaces capture India's kirana store segment currently underserved by enterprise platforms. |
Study Parameters
The analysis maps customer analytics, pricing optimization, inventory management, and sales forecasting modules, each validated through chief technology officers at grocery and fashion retailers, cloud infrastructure procurement officers, systems integration specialists, and regulatory compliance leads. Primary interviews triangulated against secondary sources including SEC filings from Microsoft and SAP, hyperscaler capex disclosures, EU AI Act implementation guidance, and retail IT spending surveys from industry associations. Bottom-up deployment estimates and top-down market sizing converged through iterative reconciliation.
Assumptions held fixed include current EU AI Act enforcement timelines, existing cloud data center geographic footprints, and prevailing data residency interpretations across member states. Variables included retailer IT budget elasticity, edge computing adoption velocity, and talent availability for production ML engineering. Segmentation modeled deployment model, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical technology adoption patterns, with inputs from IoT sensor deployment rates and dynamic pricing engine penetration benchmarks.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, cloud infrastructure pricing, or cross-border data transfer policy would shift the trajectory. Forecasts reflect documented assumptions without forward-looking guarantees. Material shifts in EU AI Act enforcement stringency or hyperscaler competitive dynamics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Smart Shelves Market
Retail Technology
Self-Service Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
AR in Retail Market
Retail Technology
Cash Register Machines Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Global Kiosk Market
Retail Technology
Smart Shelf Market
Retail Technology
Connected Retail Market
Retail Technology
Ticket Machine Market
Retail Technology
Self-Checkout System Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Self-Checkout in Retail Market