
 E-Retail Market | 2026-2036
E-Retail Market Size, Share, and Industry Trends Forecast 2026-2036
E-Retail Market Intelligence
Last-mile logistics talent is rotating from pure delivery execution into inventory forecasting and warehouse robotics maintenance, tightening labor pools in dense urban fulfillment zones. Amazon leverages its captive air cargo and sortation network to sustain next-day coverage across North American metros. JD.com anchors same-day performance through owned warehouse automation and direct delivery workforce control. Alibaba Group competes via ecosystem bundling of commerce, cloud, and financial services across Southeast Asian marketplaces.
E-retail denotes the digital sale and fulfillment of goods through internet-connected storefronts, relying on integrated payment gateways, inventory management systems, and algorithmic recommendation engines that process consumer behavioral signals in real time. Its commercial purpose centers on collapsing geographic distance between distributed inventory and atomized demand while reducing marginal transaction costs versus physical retail. Electronics and apparel product categories currently generate the densest margin pools due to return-rate management complexity and size-variant logistics. Mobile app and social commerce distribution channels represent the fastest-expanding demand capture mechanisms, particularly where super-app architectures merge content consumption with instant checkout. Luxury and premium pricing tiers concentrate customer lifetime value, though economy and value tiers absorb the majority of transaction volume across emerging-market platforms.
FDA oversight of direct-to-consumer prescription and wellness products shapes permissible e-retail assortment depth in the United States, while China's SAMR enforces anti-monopoly and data security compliance on domestic platform operators. The EU's Digital Services Act and GDPR collectively mandate algorithmic transparency and consumer data rights that increase operational compliance expenditure for cross-border sellers. Stakeholders must monitor evolving interoperability requirements between marketplace platforms and independent merchant systems as regulatory fragmentation deepens.
Market Dynamics
Urban logistics density and UPI payment penetration in India are compressing customer acquisition costs below levels seen in mature Western markets, redrawing competitive investment priorities across Asia-Pacific fulfillment networks.
Growth Catalysts
- India's UPI infrastructure:Real-time payment settlement at zero merchant discount rate eliminates friction in checkout completion. Digital wallet penetration in tier-2 and tier-3 cities accelerates first-time online purchasing.
- Warehouse robotics maintenance talent pipelines:Specialized vocational programs in Singapore and South Korea feed automation deployment in regional fulfillment centers. Labor productivity gains compound through reduced pick-and-pack cycle times.
- EU Digital Services Act compliance investments:Algorithmic transparency mandates force platform operators to document recommendation engine logic. Merchants gain audit rights over ranking methodologies, reducing arbitrary visibility loss.
Market Restraints
- China SAMR data localization requirements:Cross-border data transfer restrictions impose redundant server infrastructure costs on multinational sellers. Compliance expenditure scales with transaction volume in Chinese marketplaces.
- Last-mile labor pool tightening:Dense urban fulfillment zones in São Paulo and Mexico City face courier attrition as workers rotate into inventory forecasting roles. Wage pressure transmits directly to per-unit delivery economics.
- Return-rate complexity in apparel:Size-variant logistics and reverse supply chain handling consume margin pools that electronics categories retain. Free return policies become unsustainable below certain average order values.
Strategic Opportunities
- Social commerce integration in Indonesia:Super-app architectures merging content consumption with instant checkout capture demand from entertainment-anchored user sessions. Live-streaming commerce penetration remains below China's saturation level.
- FDA direct-to-consumer prescription pathways:Regulatory clarity on telehealth-fulfilled pharmaceutical shipments opens assortment depth in wellness categories. Pharmacy benefit managers face disintermediation pressure.
- Cloud-financial services bundling:Convergence of merchant lending, payment processing, and inventory analytics creates switching costs for small sellers. Ecosystem lock-in compounds through working capital access.
Industry Challenges
- GDPR algorithmic audit readiness:Documentation of real-time recommendation engine decision trees requires engineering headcount that mid-market platforms struggle to recruit. Compliance timelines compress against enforcement escalation.
- Legacy warehouse management system integration:Robotics automation layers atop decades-old inventory databases create synchronization failures. Order-picking accuracy degrades during peak demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Retail Market |
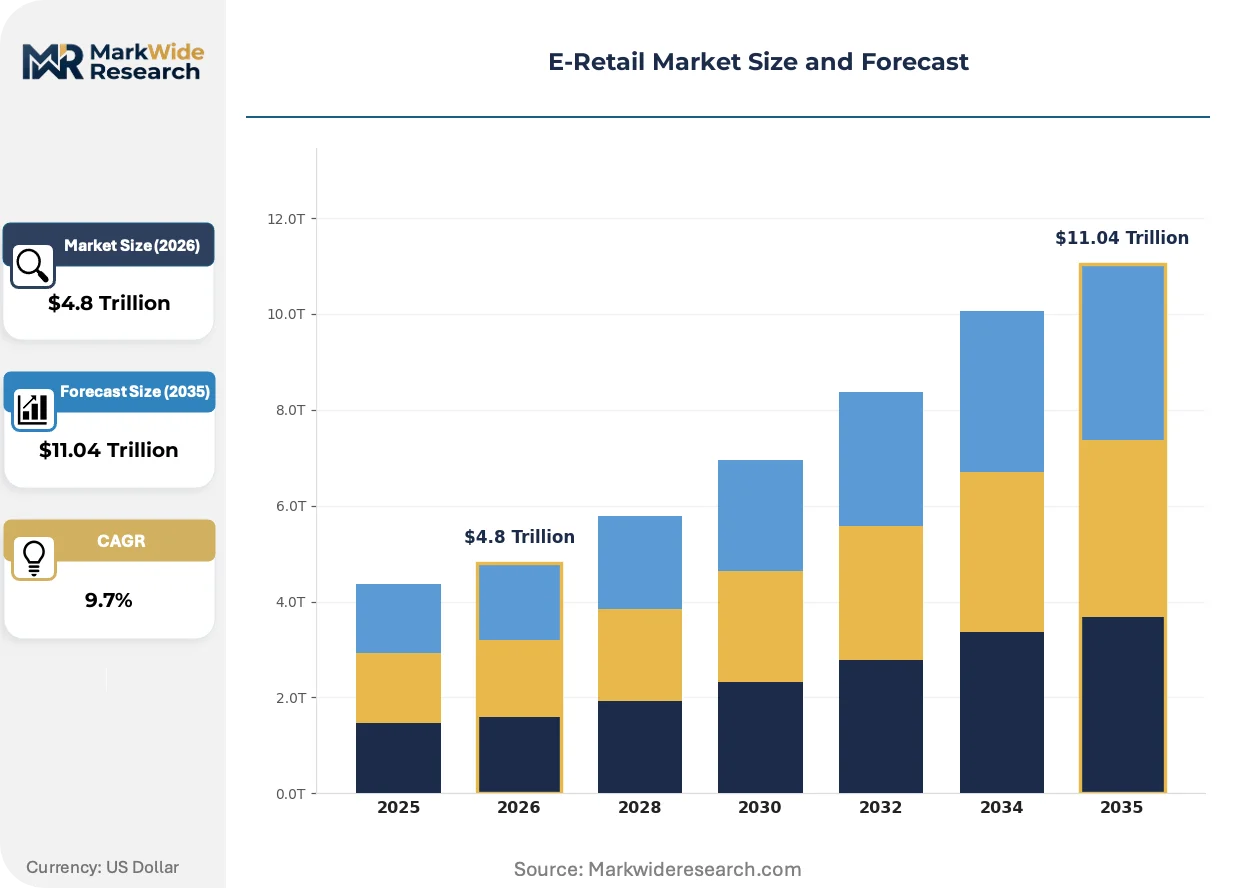
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $11.04 Trillion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Apparel, Home & Kitchen, Beauty & Personal Care, Books, Sports Equipment Pricing Tier: Luxury, Premium, Mid-Range, Economy, Value Distribution Channel: Direct-to-Consumer Website, Marketplace, Mobile App, Social Commerce, Affiliate Platforms Customer Type: Individual Consumers, Small Businesses, Freelancers, Educational Institutions |
| Companies Covered | Shopify, JD.com, Amazon, MercadoLibre, Shopee, Alibaba Group, Pinduoduo, Temu, Walmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Retail Market Strategic Shifts & Innovations
Algorithmic personalization and regulatory transparency mandates are forcing platform operators to rebuild core infrastructure around auditable decision systems rather than opaque optimization engines.
Generative AI recommendation engines are decomposing traditional collaborative filtering architectures in high-velocity apparel and electronics categories. Large language models parse natural-language product reviews to surface contextual matches that matrix factorization misses. Early adopters in Southeast Asian marketplaces report session duration compression without conversion rate sacrifice.
China's SAMR anti-monopoly enforcement is mandating interoperability between dominant platforms and independent merchant systems. Data portability obligations require standardized API architectures that reduce switching costs for sellers. Domestic operators are responding by deepening financial services integration to retain merchant stickiness through capital access rather than technical friction.
Live-streaming commerce formats are displacing static product pages in discretionary purchase categories across Indonesia and Vietnam. Influencer-hosted sessions merge entertainment consumption with impulse checkout through embedded payment triggers. Merchant procurement of influencer inventory slots now consumes marketing budgets previously allocated to search advertising in Jakarta and Ho Chi Minh City clusters.
E-Retail Market Segmentation
E-retail segmentation reveals how inventory velocity, margin capture, and compliance burden distribute across product categories and buyer profiles. Structural differences in return handling, payment integration, and regulatory exposure create divergent investment requirements for platform operators and merchant sellers.
Product Category:
FDA oversight of direct-to-consumer wellness shipments and China's SAMR data governance rules impose category-specific compliance architectures that reshape permissible assortment depth and cross-border fulfillment economics.
- Electronics:High-value SKUs with standardized specifications minimize return-rate friction. India's urban logistics density and UPI penetration concentrate demand for smartphones and accessories in tier-2 and tier-3 city clusters where first-time online purchasing accelerates.
- Apparel:Size-variant logistics and reverse supply chain complexity consume margin pools through elevated return handling costs. Free return policies become unsustainable below certain average order values, forcing merchants toward fit-prediction algorithms and virtual try-on overlays.
- Home & Kitchen:Bulky fulfillment requirements favor marketplace platforms with captive warehousing networks.
- Beauty & Personal Care:FDA and EMA ingredient disclosure mandates shape permissible cross-border assortment.
- Books:Low-margin, high-velocity category with minimal return friction.
- Sports Equipment:Seasonal demand spikes strain inventory forecasting accuracy.
Electronics handles the majority of throughput; Beauty & Personal Care is climbing the fastest on share as telehealth-fulfilled wellness categories expand regulatory clarity.
Pricing Tier:
Customer lifetime value concentration and transaction volume absorption split sharply across tiers, with luxury segments generating disproportionate margin contribution despite smaller unit bases.
- Luxury:Authenticity verification infrastructure and white-glove fulfillment protocols dominate operational design. EU Digital Services Act algorithmic transparency mandates force documentation of recommendation engine logic that luxury merchants leverage to audit visibility allocation.
- Premium:Brand equity protection requires controlled distribution architectures that resist marketplace dilution. SAMR anti-monopoly enforcement in China mandates interoperability that reduces technical switching costs for premium sellers seeking direct-to-consumer migration.
- Mid-Range:Highest competitive intensity with compressed differentiation vectors.
- Economy:Volume absorption concentrated in emerging-market mobile commerce.
- Value:Thin margins demand extreme logistics efficiency and minimal return tolerance.
Value tier absorbs the greatest transaction volume; Premium is expanding most quickly as brand-controlled distribution gains share against marketplace dependency.
Distribution Channel:
Super-app architectures and regulatory fragmentation around data portability are redrawing channel economics, with owned-platform control becoming a defensive priority for margin retention.
- Direct-to-Consumer Website:Merchant-controlled data assets and first-party behavioral signals enable personalization depth that marketplace dependence forecloses. GDPR algorithmic audit requirements impose documentation burdens that mid-market operators struggle to resource.
- Marketplace:Aggregated demand density and captive logistics networks lower customer acquisition costs. China's SAMR data localization requirements impose redundant server infrastructure costs that scale with transaction volume.
- Mobile App:Push notification permission rates and native checkout friction determine conversion efficiency.
- Social Commerce:Live-streaming formats in Indonesia and Vietnam merge entertainment consumption with impulse purchase triggers.
- Affiliate Platforms:Commission stacking and attribution complexity erode merchant margin.
Marketplace channels handle the majority of throughput; Social Commerce is gaining share fastest as influencer-hosted sessions displace static product pages.
Customer Type:
Procurement scale and payment integration requirements diverge sharply, with institutional buyers demanding invoice workflows and credit terms that consumer-centric platforms must retrofit.
- Individual Consumers:Real-time payment settlement through India's UPI infrastructure eliminates checkout friction at zero merchant discount rate. Behavioral signal capture enables recommendation engine personalization that compresses session duration without conversion sacrifice.
- Small Businesses:Working capital access and inventory analytics integration create ecosystem stickiness. Cloud-financial services bundling raises switching costs through merchant lending and payment processing convergence.
- Freelancers:Irregular income patterns favor pay-later and installment options.
- Educational Institutions:Bulk procurement workflows and tax-exempt documentation requirements.
Individual Consumers handle the majority of throughput; Small Businesses are expanding most quickly as B2B marketplace penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. India's mobile-first shoppers prioritize UPI-enabled instant checkout, while German buyers demand algorithmic transparency under EU mandates. China's ecosystem bundling creates stickiness through financial services integration that Western markets rarely replicate.
United States
FDA oversight of direct-to-consumer prescription shipments and wellness categories expands permissible assortment depth. Telehealth-fulfilled pharmaceutical pathways clarify regulatory boundaries for platform operators. Seattle and San Francisco Bay Area clusters concentrate logistics automation R&D and captive air cargo network deployment.
China
SAMR anti-monopoly enforcement mandates interoperability between dominant platforms and independent merchant systems, reducing technical switching costs. Data localization requirements impose redundant server infrastructure expenditure scaling with transaction volume. Yangtze River Delta and Pearl River Delta urban clusters anchor same-day fulfillment through owned warehouse automation and direct delivery workforce control.
Germany
GDPR algorithmic audit requirements and EU Digital Services Act transparency mandates force documentation of recommendation engine decision trees. Engineering headcount scarcity compresses compliance timelines for mid-market platforms. Berlin and Munich logistics hubs face last-mile labor pool tightening as workers rotate into inventory forecasting and robotics maintenance roles.
India
UPI payment penetration at zero merchant discount rate eliminates checkout friction, compressing customer acquisition costs below mature Western market levels. RBI oversight of digital wallet infrastructure and merchant lending creates regulatory scaffolding for ecosystem expansion. Mumbai and Bangalore urban logistics density enables tier-2 and tier-3 city demand capture at structurally lower economics.
Brazil
São Paulo's dense urban fulfillment zones experience courier attrition as delivery talent migrates into warehouse robotics maintenance and demand forecasting functions. ANVISA pharmaceutical shipment regulations shape cross-border wellness assortment boundaries. The city's last-mile wage pressure transmits directly to per-unit delivery economics, accelerating automation investment.
E-Retail Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale-driven platforms commanding captive logistics networks while niche operators concentrate on category-specific fulfillment optimization. The upper tier consolidates around ecosystem bundling of commerce, cloud, and financial services. Mid-tier specialists differentiate through social commerce integration and influencer-hosted live-streaming formats. Dominant competitive moves include M&A to secure logistics density and strategic partnerships to embed payment infrastructure into super-app architectures.
Within the integrated platform tier, Amazon and JD.com exemplify divergent fulfillment philosophies—captive air cargo networks versus owned warehouse automation—while Alibaba Group anchors ecosystem bundling across Southeast Asian marketplaces. MercadoLibre occupies a position representing regional density specialists who consolidate Latin American logistics infrastructure. These three companies illustrate how geographic origin and corporate structure shape competitive archetype selection without dictating specific strategic outcomes.
| Leading Market Players |
|---|
| Shopify |
| JD.com |
| Amazon |
| MercadoLibre |
| Shopee |
| Alibaba Group |
| Pinduoduo |
| Temu |
| Walmart |
| Others |
Cost & Logistics Intelligence
Forty-five-day inventory turns in tier-1 fulfillment centers compress working capital cycles while amplifying pricing power for platforms with captive warehouse networks. This velocity differential separates operators who can absorb return-handling costs from merchants forced into discounting to liquidate stale stock.
Pricing Analysis
Contract structures bifurcate between long-term offtake agreements with enterprise sellers and spot-market pricing for seasonal inventory. Three-tier pricing stratification across luxury, mid-range, and value tiers reflects brand equity and fulfillment service bundling rather than pure product differentiation. Cost compression in the value tier intensifies as UPI-enabled zero-merchant-discount transactions eliminate payment processor margin recovery. Small business buyers exhibit highest price sensitivity due to working capital constraints, while luxury segments absorb premium logistics fees without volume erosion.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Los Angeles trade lane transmit directly into inbound logistics cost volatility for cross-border sellers. Manufacturing concentration in China, Vietnam, and Bangladesh feeds apparel and electronics assortment depth, while semiconductor inputs for consumer electronics draw from Taiwan and South Korea. Single-source vulnerability in automated warehouse robotics components creates fulfillment capacity risk during demand spikes. Distribution runs through hub-and-spoke networks anchored in owned sortation facilities, with last-mile density determining final-mile economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-streaming commerce integration represents a high-growth disruption as super-app architectures merge content consumption with instant checkout, compressing traditional search-based discovery funnels.
For Market Incumbents: Secure captive logistics density in India and Southeast Asia before competitor network effects harden. Consolidate warehouse robotics maintenance talent pipelines through vocational partnerships in Singapore and South Korea. Defend against social commerce disintermediation by embedding payment infrastructure into entertainment-anchored user sessions. For New Entrants and Emerging Players: Differentiate on algorithmic transparency compliance as EU Digital Services Act mandates create documentation burdens that mid-market platforms struggle to resource. Target tier-2 and tier-3 Indian city clusters where UPI penetration enables structurally lower customer acquisition economics than saturated Western metros. Pursue influencer-hosted live-streaming formats in Indonesia and Vietnam where penetration remains below Chinese saturation levels. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because ecosystem bundling of commerce, cloud, and financial services creates switching costs that resist unbundling. Acquisition targets should concentrate on regional logistics specialists with dense urban fulfillment footprints in underpenetrated emerging markets. Monitor SAMR interoperability enforcement escalation as a signal for merchant migration timing toward independent direct-to-consumer infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Robotics Deployment | Owned automation in Yangtze River Delta facilities compresses pick-and-pack cycle times below third-party logistics benchmarks. |
| UPI Payment Infrastructure Integration | Zero-merchant-discount settlement in Indian tier-2 cities eliminates checkout friction for first-time online purchasers. |
| Live-Streaming Commerce Platform Launch | Super-app architectures in Jakarta and Ho Chi Minh City merge entertainment consumption with impulse purchase triggers. |
| Algorithmic Transparency Compliance Investment | EU Digital Services Act documentation requirements force rebuild of recommendation engine architectures around auditable decision systems. |
| Captive Air Cargo Network Expansion | Seattle and San Francisco Bay Area clusters enable next-day coverage across North American metros without carrier dependency. |
Research Approach
A spread of perspectives from fulfillment network operators, merchant category managers, logistics automation engineers, and regulatory compliance leads converged on the working assumptions driving this analysis. Primary interviews with warehouse robotics maintenance specialists and UPI infrastructure architects supplemented secondary validation through customs trade data, SEC filings of listed platform operators, RBI digital payment disclosures, and EU regulatory impact assessments. Bottom-up transaction volume modeling and top-down macroeconomic sizing triangulated on segment-level estimates.
Segmentation dimensions modeled include product category velocity, pricing tier margin structure, distribution channel control architecture, and customer type procurement scale across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated urban logistics density metrics, payment infrastructure penetration curves, and algorithmic transparency compliance cost curves.
Material uncertainties — SAMR enforcement escalation, GDPR audit timeline compression, last-mile labor pool rotation rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about interoperability mandate implementation pace and UPI geographic expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Global Smart Retail Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
Self-Checkout System Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Ticket Machine Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Connected Retail Market
Retail Technology
Global Kiosk Market
Retail Technology
AR in Retail Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Cash Register Machines Market