
 Supplier Management Market | 2026-2036
Supplier Management Market Size, Share, and Industry Trends Forecast 2026-2036
Supplier Management Market Analytics
Enterprise-grade supplier governance is rotating toward integrated risk-performance suites. SAP Ariba leverages its procurement network density to anchor cloud-based supplier onboarding workflows across Fortune 500 accounts. Ivalua sustains R&D intensity in configurable supplier scorecard architectures, while Zycus competes through AI-native spend classification that extends into third-party risk monitoring.
Supplier management encompasses the systematic governance, evaluation, and collaboration frameworks that enterprises deploy to oversee vendor relationships across sourcing, compliance, and performance dimensions. Core platforms integrate real-time supplier data feeds, automated risk scoring algorithms, and contract lifecycle management protocols to reduce supply chain disruption exposure and procurement cost leakage. Cloud-based deployment leads functionality adoption as manufacturers and retail chains migrate from legacy ERP modules to API-first supplier networks. Supplier performance management represents the fastest-expanding functionality segment, driven by mandatory ESG disclosure requirements and tier-n visibility mandates. Large corporations occupy the deepest margin pools, though mid-market penetration is accelerating through modular SaaS pricing.
The EU AI Act, GDPR, and REACH frameworks compel European enterprises to embed algorithmic audit trails and chemical compliance verification into supplier onboarding portals. The US FDA and EPA impose parallel documentation requirements for healthcare and industrial supply bases, shaping platform feature roadmaps on both continents. Stakeholders must monitor how cross-border data-localization rules fragment supplier information architectures and force region-specific instance deployment.
Market Dynamics
Automotive OEM procurement teams are accelerating platform adoption to manage tiered supplier networks, compressing onboarding cycles and forcing real-time visibility mandates across multi-tier supply chains.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers embed automated risk-scoring modules into supplier governance portals to satisfy algorithmic audit requirements.
- Tier-n visibility imperatives:Automotive and aerospace OEMs demand sub-tier supplier data feeds to preempt disruption exposure from distant network nodes.
- ESG disclosure frameworks:CSRD and REACH obligations compel enterprises to deploy supplier performance management for carbon and chemical compliance verification.
Market Restraints
- Cross-border data localization:Fragmented sovereignty rules force redundant instance deployment, inflating cloud infrastructure costs for multinational deployments.
- Legacy ERP entrenchment:SAP and Oracle module stickiness creates integration friction, delaying API-first migration timelines.
- Specialized talent scarcity:Shortage of procurement technologists fluent in both supplier operations and machine learning pipelines constrains platform optimization.
Strategic Opportunities
- Mid-market SaaS penetration:Modular pricing architectures unlock German Mittelstand manufacturers previously excluded from enterprise-grade governance tools.
- AI-native spend classification:Convergence of natural language processing and procurement analytics creates automated supplier risk monitoring capabilities.
- Healthcare supplier governance:FDA documentation requirements for medical device supply chains drive specialized compliance module demand.
Industry Challenges
- API standardization gaps:Heterogeneous data formats across supplier tiers impede real-time integration, requiring costly middleware development.
- Certification timeline compression:Accelerated ESG audit cycles strain supplier assessment bandwidth, creating backlog risks in onboarding queues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplier Management Market |
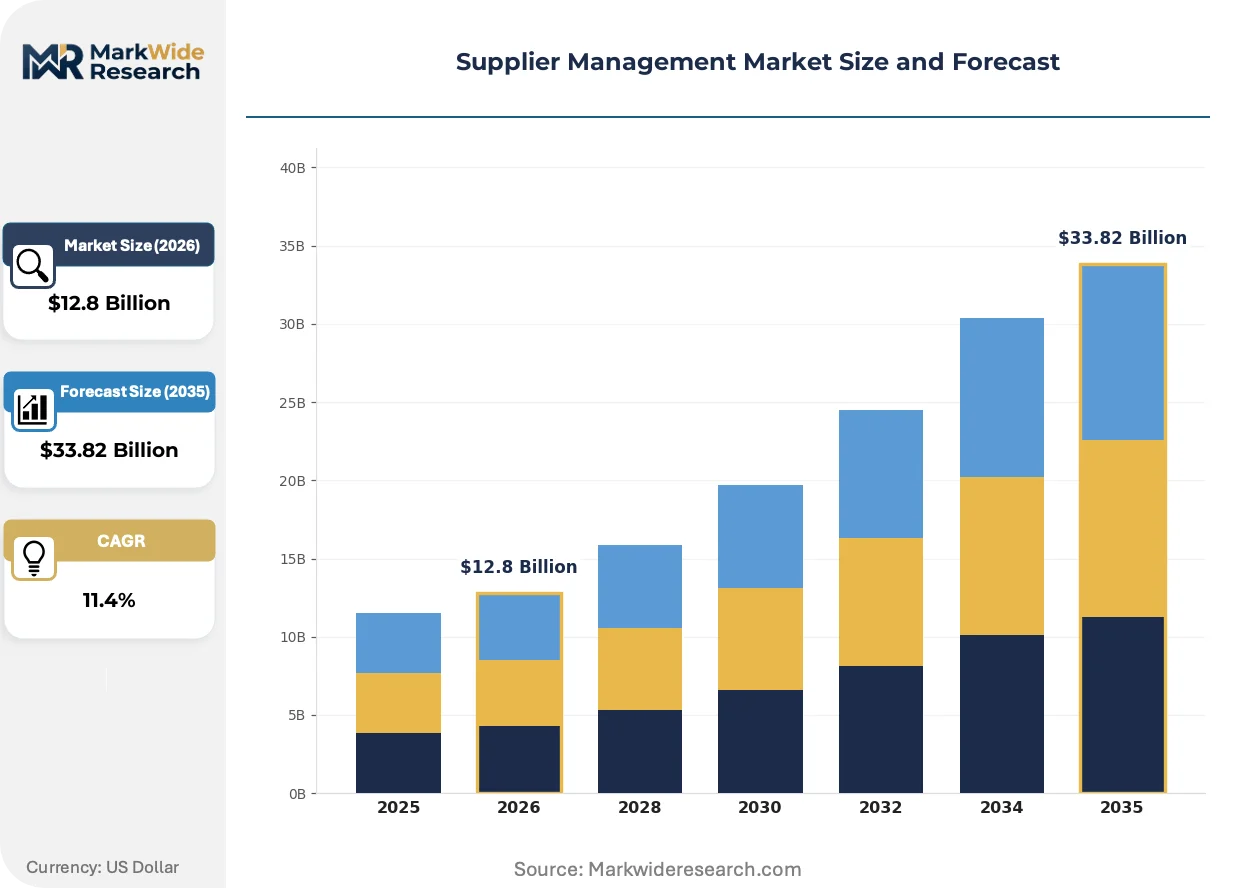
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Industry Vertical: Manufacturing, Retail, Healthcare, BFSI Functionality: Procurement, Risk Management, Supplier Performance, Contract Management Size: Small Enterprises, Medium Enterprises, Large Corporations, Global Firms |
| Companies Covered | GEP SMART, Kodiak Hub, SAP Ariba, Jaggaer, Zycus, Coupa, Ivalua, Basware, Oracle Procurement Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplier Management Market Evolving Landscape
Supplier management platforms are rotating toward integrated risk-performance suites, embedding AI-driven analytics directly into procurement workflows rather than operating as standalone modules.
Graph-based supplier network mapping is displacing static spreadsheet inventories. The technology constructs dynamic relationship models across tiered vendor ecosystems. Automotive OEMs in Germany and industrial conglomerates in France deploy these tools at enterprise scale. Real-time disruption propagation modeling is displacing reactive incident response in procurement planning cycles.
REACH chemical compliance verification is reshaping European onboarding protocols. The framework mandates substance-of-very-high-concern tracking across supplier declarations. German chemical and automotive manufacturers face the steepest documentation burdens. Platform vendors respond with automated bill-of-materials parsing and regulatory update feeds.
Consolidated supplier scorecards are compressing vendor evaluation cycles. Procurement teams replace discrete annual assessments with continuous performance dashboards. This pattern concentrates most visibly in US healthcare and European automotive verticals. Buyers now weight ESG metrics equally with cost and delivery reliability in qualification decisions.
Supplier Management Market Segmentation
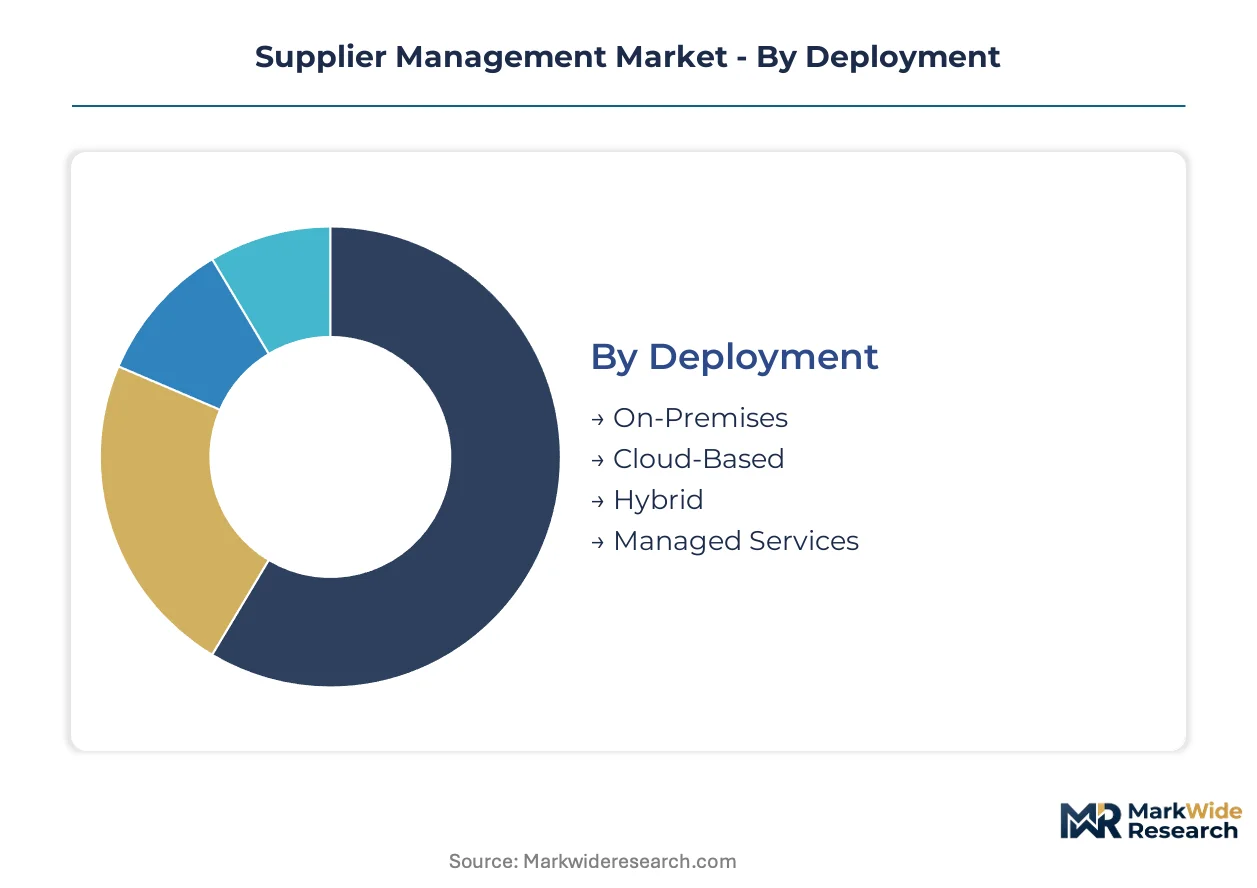
Supplier management platforms fragment across deployment architectures, enterprise scale, and functional depth. Procurement teams select configurations based on regulatory exposure, IT legacy constraints, and tier-n visibility requirements.
Deployment:
Cloud-based solutions flow through direct vendor sales and systems integrator channels, while on-premises deployments rely heavily on value-added resellers with ERP integration expertise.
- Cloud-Based:Multi-tenant SaaS architectures enable API-first supplier network connectivity with automatic compliance patch deployment. German automotive OEMs and French industrial conglomerates concentrate demand here, driven by EU AI Act audit trail mandates and the need for real-time sub-tier data feeds without infrastructure ownership.
- On-Premises:Single-tenant installations behind corporate firewalls preserve data sovereignty for defense and critical infrastructure supply chains. Demand concentrates in US healthcare networks subject to HIPAA constraints and European chemical manufacturers navigating REACH substance tracking, where data localization requirements override cloud migration economics.
- Hybrid:Split architectures isolate sensitive supplier risk data on-premises while routing transactional procurement workflows through cloud interfaces.
- Managed Services:Outsourced platform administration with dedicated supplier onboarding teams appeals to mid-market manufacturers lacking procurement technologists.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest as sovereignty rules fragment deployment strategies.
Industry Vertical:
Manufacturing commands the deepest functionality investment, while healthcare and BFSI drive specialized compliance module development at premium price tiers.
- Manufacturing:Tiered supplier networks in automotive, aerospace, and industrial equipment demand graph-based relationship mapping and automated bill-of-materials parsing. German OEMs anchor this segment, compressing onboarding cycles through integrated risk-performance suites that REACH mandates have made non-negotiable.
- Healthcare:FDA documentation requirements for medical device supply chains and pharmaceutical ingredient provenance create specialized governance workflows. US hospital networks and European medical technology manufacturers concentrate demand, where supplier qualification now incorporates continuous ESG dashboard monitoring alongside traditional quality audits.
- Retail:Private-label sourcing networks and direct-to-manufacturer procurement drive modular SaaS adoption for margin-sensitive apparel and consumer goods chains.
- BFSI:Third-party risk frameworks for critical technology vendors and outsourced service providers shape procurement governance in banking and insurance.
Manufacturing captures the largest revenue pool. Healthcare is expanding most quickly on regulatory tailwinds.
Functionality:
Risk Management and Supplier Performance modules command premium pricing, while Procurement and Contract Management anchor platform stickiness through ERP integration depth.
- Supplier Performance:Continuous scorecard architectures replace annual assessments with real-time ESG, delivery, and quality metrics. European automotive and US healthcare verticals concentrate adoption, where CSRD disclosure obligations and FDA supplier qualification requirements have elevated performance tracking to board-level visibility.
- Risk Management:Automated risk-scoring algorithms with algorithmic audit trails address EU AI Act compliance and tier-n disruption propagation modeling. German chemical manufacturers and French aerospace suppliers anchor demand, embedding REACH substance verification and geopolitical risk feeds into onboarding portals.
- Procurement:Source-to-pay workflow automation with spend classification analytics remains the entry-point functionality for mid-market penetration.
- Contract Management:Lifecycle protocol enforcement with automated renewal triggers and compliance clause extraction secures long-term platform retention.
Procurement holds the widest installed base. Supplier Performance is gaining share fastest on ESG disclosure mandates.
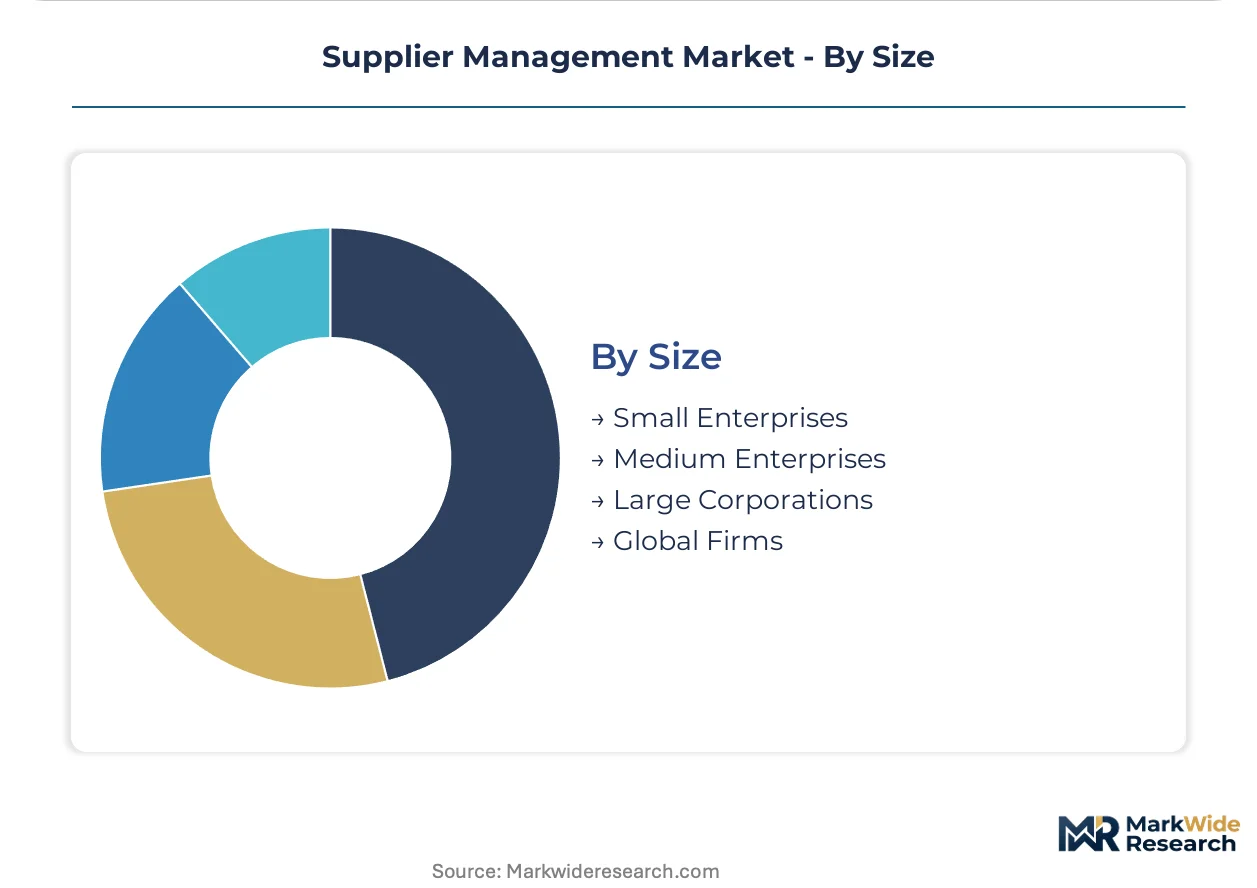
Size:
Large Corporations and Global Firms deploy enterprise suites through direct vendor relationships, while Small and Medium Enterprises access modular functionality via self-service portals and partner-led implementations.
- Large Corporations:Multi-entity deployments with federated supplier master data and regional instance orchestration. German industrial conglomerates and US healthcare systems anchor this tier, where cross-border data localization rules force redundant infrastructure and specialized compliance modules for REACH, FDA, and GDPR simultaneously.
- Global Firms:Standardized supplier governance across 50+ country operations with centralized risk intelligence and localized onboarding portals. Demand concentrates in automotive OEMs with tiered supplier networks spanning Germany, China, Mexico, and the US, where real-time visibility mandates require API-first architectures.
- Medium Enterprises:Modular SaaS pricing unlocks German Mittelstand manufacturers and US regional healthcare networks previously excluded from enterprise-grade tools.
- Small Enterprises:Lightweight supplier databases with basic qualification workflows serve niche manufacturers and specialty retailers.
Large Corporations dominate current spending. Medium Enterprises show the steepest expansion trajectory as modular pricing democratizes access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy manufacturing economies drive supplier management platform imports, while service-oriented economies generate outbound SaaS solutions. Trade flows concentrate procurement technology toward industrial clusters with complex tiered supply chains.
United States
Healthcare networks and automotive OEMs deploy cloud-based governance portals to manage FDA-mandated supplier documentation. HIPAA constraints push hospital systems toward hybrid architectures that isolate sensitive risk data. Detroit-area automotive headquarters anchor multi-tier visibility deployments for North American supply chains.
Germany
Industrial conglomerates and Mittelstand manufacturers compress supplier onboarding cycles through REACH-compliant automated verification. EU AI Act audit trail requirements accelerate risk-scoring module adoption across automotive and chemical sectors. Stuttgart and Munich clusters concentrate demand for integrated performance suites.
China
Domestic EV manufacturers and electronics assemblers demand real-time sub-tier data feeds to preempt disruption from distant network nodes. MIIT data-localization rules force on-premise or sovereign cloud deployments for critical supply chain infrastructure. Shenzhen and Shanghai anchor the largest regional deployment bases for tier-n visibility tools.
Japan
Automotive and precision equipment manufacturers migrate from legacy keiretsu coordination models to API-first supplier networks. METI supply chain resilience initiatives accelerate platform adoption for semiconductor and battery material sourcing. Nagoya and Osaka industrial corridors concentrate governance tool deployment.
India
Pharmaceutical exporters and automotive component manufacturers deploy modular SaaS pricing to qualify for EU and US regulatory markets. CDSCO documentation requirements for active pharmaceutical ingredients shape specialized compliance workflows. Gujarat and Maharashtra pharmaceutical clusters drive fastest regional adoption.
Supplier Management Market Competitive Landscape
Concentration sits with procurement-suite incumbents and cloud-native specialists. Enterprise software conglomerates leverage ERP integration depth to anchor supplier governance modules within broader source-to-pay ecosystems. Independent vendors compete through AI-native architectures and configurable scorecard flexibility. Dominant competitive moves include API-first platform expansion and vertical-specific compliance module development.
Within the enterprise-suite tier, SAP Ariba and Oracle Procurement Cloud represent integrated procurement network density. Ivalua exemplifies configurable supplier scorecard architectures for complex manufacturing environments. Zycus occupies a position at the AI-native intersection of spend classification and automated risk monitoring.
| Leading Market Players |
|---|
| GEP SMART |
| Kodiak Hub |
| SAP Ariba |
| Jaggaer |
| Zycus |
| Coupa |
| Ivalua |
| Basware |
| Oracle Procurement Cloud |
| Others |
Value Network & Pricing Analysis
Long-term SaaS subscription contracts anchor enterprise supplier management deployments, locking in multi-year revenue visibility for vendors while securing procurement teams against price volatility during platform migration cycles. German automotive OEMs and US healthcare networks favor these structures to insulate budget planning from GDPR compliance cost spikes and FDA audit preparation expenses.
Pricing Analysis
Industrial OEM buyers anchor tiered subscription pricing across cloud-based supplier governance platforms. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 multi-entity deployments from mid-market modular access and basic supplier database tools. Price differentiation rests on API integration depth, REACH compliance module inclusion, and dedicated onboarding support tiers. Cost compression in the mid-market SaaS tier is intensifying because modular competitors are undercutting legacy ERP bundling. Small enterprises exhibit highest price sensitivity, while global firms with cross-border data localization requirements show lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
API standardization gaps across heterogeneous supplier data formats constitute a critical chokepoint delaying real-time integration timelines for tier-n visibility deployments. Platform development concentrates in the United States, Germany, and India, with US vendors anchoring healthcare compliance modules and German specialists dominating REACH-enabled chemical verification tools. Raw material dependencies span cloud infrastructure from hyperscale providers, specialized machine learning talent pipelines, and regulatory content feeds from ECHA and FDA databases. Single-source vulnerability runs through concentrated hyperscaler cloud capacity for multi-tenant SaaS architectures. Distribution runs through direct vendor sales to large corporations, systems integrator channels for ERP-integrated deployments, and value-added resellers serving on-premises installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The supplier management sector rewards organizations that command scarce procurement technologist talent capable of bridging machine learning pipelines with vendor operations expertise. Platform vendors and enterprise buyers alike face capability gaps in algorithmic audit trail engineering and sub-tier data architecture design.
For Market Incumbents: Compound platform stickiness through deeper ERP integration moats and preemptive API standardization investments that freeze out modular competitors. Defend against AI-native spend classification entrants by accelerating algorithmic audit trail features for EU AI Act compliance. Prioritize vertical integration into specialized compliance content feeds from ECHA and FDA databases to create switching costs. For New Entrants and Emerging Players: Lead with AI-native risk-scoring architectures targeting German Mittelstand manufacturers excluded from enterprise pricing tiers. White-space concentration sits in mid-market healthcare networks requiring HIPAA-compliant hybrid deployments and Indian pharmaceutical exporters seeking CDSCO-aligned qualification workflows. Go-to-market traction demands modular pricing with rapid REACH verification module deployment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-specific compliance module developers with embedded regulatory content partnerships. Long-term viability over the next decade hinges on platform consolidation around API-first architectures capable of spanning fragmented data localization requirements. Acquisition targets should demonstrate proven tier-n visibility deployments in automotive or aerospace supply chains. The signal to watch is accelerated ESG audit cycle compression creating backlog risks in supplier onboarding queues.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Expansion | Enables real-time sub-tier data feeds for German automotive OEMs managing REACH compliance across multi-tier networks. |
| Vertical Compliance Module Development | Embedding FDA documentation workflows captures US healthcare procurement budgets shifting from legacy ERP modules. |
| AI-Native Risk Classification | Automated spend classification with natural language processing extends platform value into third-party risk monitoring. |
| Hybrid Deployment Architecture | Split cloud-on-premise configurations address HIPAA constraints and MIIT data localization rules simultaneously. |
| Mid-Market SaaS Penetration | Modular pricing unlocks German Mittelstand manufacturers previously excluded from enterprise governance tools. |
Research Methodology
Cross-validation between primary procurement executive interviews and secondary regulatory filing analysis anchors the qualitative findings in this supplier management sector assessment. Conversations with Chief Procurement Officers, supplier governance platform product managers, ERP integration specialists, and ESG compliance directors informed capability-scarcity and competitive positioning assessments. Secondary validation drew from SEC 10-K disclosures, ECHA substance-of-concern update feeds, FDA supplier documentation guidance, and hyperscaler cloud infrastructure capex reports. Bottom-up deployment estimates triangulated against top-down procurement technology spending benchmarks.
Sensitivity analysis across deployment model adoption curves, regulatory timeline acceleration scenarios, and mid-market penetration rates shaped the forecast framework. Segmentation dimensions modeled include cloud versus on-premise architecture, enterprise scale tier, functional module depth, and vertical regulatory exposure intensity. CAGRs were derived from deployment velocity indicators and compliance mandate enforcement timelines. Industry-specific forecast inputs encompass EU AI Act audit trail implementation pace and REACH substance tracking expansion scope.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or cloud infrastructure cost stability would require recalibration. Forecasts reflect documented assumptions regarding procurement team digitalization readiness and API standardization progress across supplier tiers. Practitioners should keep alternative scenarios live as cross-border data localization rule fragmentation and ESG audit cycle compression evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Proactive Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Workforce Management Market
Enterprise Services
Field Service Management Market
Enterprise Services
North America Contingent Workforce Management Market