
 Mobile Enterprise Application Market | 2026-2036
Mobile Enterprise Application Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Enterprise Application Market Intelligence
The capability gap between integrated platform suites and specialized point solutions is reorganizing the competitive landscape. SAP SE leverages its deep ERP integration to dominate the manufacturing and supply chain sectors. Salesforce, Inc. specializes in cloud-native CRM and sales force automation applications. Apple Inc. controls the hardware and OS ecosystem, influencing app development standards and security protocols for its devices.
Mobile enterprise applications are software programs designed for business functions on portable devices like smartphones and tablets. These applications require secure API connections to backend corporate systems and often use containerization to separate business and personal data. Cloud-based deployment models now lead the market over on-premises solutions due to scalability and lower upfront costs. Within solution types, Customer Relationship Management and Enterprise Resource Planning applications represent the largest and most mature segments.
Data privacy regulations like the EU's GDPR and the US's HIPAA heavily influence application design, dictating data handling and storage protocols. In parallel, data sovereignty laws in countries such as China and India compel developers to consider localized cloud infrastructure and data residency. Stakeholders must navigate the trade-offs between deploying best-of-breed specialized apps and maintaining a standardized, secure, and integrated platform.
Market Dynamics
The global proliferation of 5G network infrastructure is the central force expanding the functional scope of mobile enterprise applications. This higher bandwidth and lower latency enables more data-intensive, real-time functionalities for field operations and logistics, especially within major hubs in the United States and Germany.
Growth Catalysts
- 5G Network Deployment:The ongoing global rollout of 5G connectivity provides the high-speed, low-latency foundation required for complex, data-rich applications in sectors like transportation and logistics.
- Remote Work Models:Widespread adoption of remote and hybrid work structures necessitates secure, high-performance mobile applications that extend corporate systems like ERP and CRM to employees outside the office.
- Digitalization Mandates:Government initiatives in countries like India and across the EU are pushing for digital transformation in regulated industries, compelling firms to adopt mobile solutions for compliance and reporting.
Market Restraints
- Legacy System Integration:The complexity and cost of securely connecting mobile applications to aging, on-premises backend systems like mainframe databases create significant development and maintenance hurdles.
- Data Sovereignty Laws:Regulations in China and India requiring local data storage increase infrastructure costs and architectural complexity for multinational corporations deploying standardized global applications.
- API Security Vulnerabilities:A reliance on APIs to connect mobile front-ends with corporate back-ends introduces a significant attack surface, with insecure APIs posing a primary risk for data breaches.
Strategic Opportunities
- Underpenetrated Sectors in Southeast Asia:The manufacturing and logistics sectors in emerging economies like Vietnam and Indonesia present significant white space for mobile ERP and supply chain management applications.
- Specialized Field Service Apps:There is a growing opportunity for industry-specific applications for field service technicians, particularly in utilities and telecommunications, integrating augmented reality for remote assistance.
- AI and ML Integration:Embedding artificial intelligence and machine learning into mobile CRM and sales apps can provide predictive analytics and next-best-action recommendations, creating significant value.
Industry Challenges
- Cybersecurity Skills Gap:A persistent shortage of skilled cybersecurity professionals who specialize in mobile application and API security creates a major operational risk for enterprises deploying these solutions.
- Platform Fragmentation:Developing and maintaining applications that provide a consistent user experience and security posture across both Apple's iOS and Google's Android ecosystems is a significant technical and financial challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Enterprise Application Market |
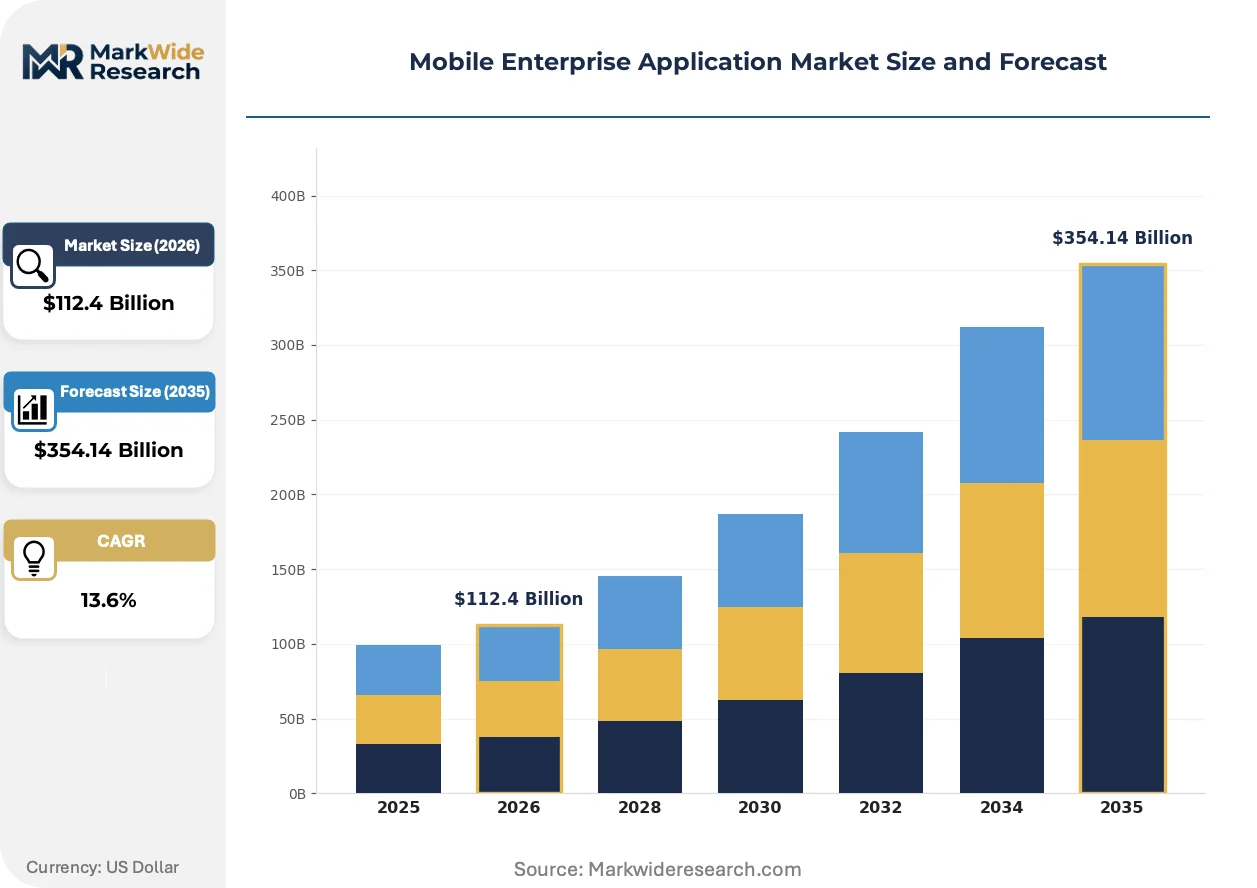
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $354.14 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Customer Relationship Management, Enterprise Resource Planning, Supply Chain Management, Human Capital Management, Content Management Use Case: Field Service Management, Inventory Tracking, Workforce Collaboration, Mobile Payments, Asset Management End User Industry: Manufacturing, Transportation & Logistics, Energy & Utilities, Telecommunications, Education |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, Salesforce, Inc., Google LLC, Apple Inc., HP Enterprise Company, Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Enterprise Application Market Strategic Shifts & Innovations
The competitive landscape is being reorganized by the architectural choice between integrated platform suites from vendors like SAP SE and specialized, best-of-breed point solutions. This decision fundamentally impacts data security, user experience, and total cost of ownership for enterprises.
Containerization technology isolates enterprise applications and their data from personal apps on an employee's device. This approach is rapidly being adopted by organizations in regulated sectors like finance and healthcare to enable bring-your-own-device policies. The use of containers is fragmenting the monolithic security model, allowing for more granular, app-specific security controls rather than device-level lockdown.
Regulations like the European Union's General Data Protection Regulation (GDPR) impose strict rules on personal data handling. This forces developers to build privacy-by-design principles directly into mobile enterprise applications, impacting UI and data flow architecture. The financial services and healthcare sectors, which must also comply with rules like HIPAA in the US, are most affected.
A definitive shift from on-premises deployment to cloud-based, Software-as-a-Service (SaaS) models is altering enterprise software acquisition. Organizations are moving away from large, upfront capital expenditures toward subscription-based operational expenses for greater scalability and lower initial costs. This trend is most visible in the CRM and sales force automation segments, particularly among small and medium-sized enterprises.
Mobile Enterprise Application Market Segmentation
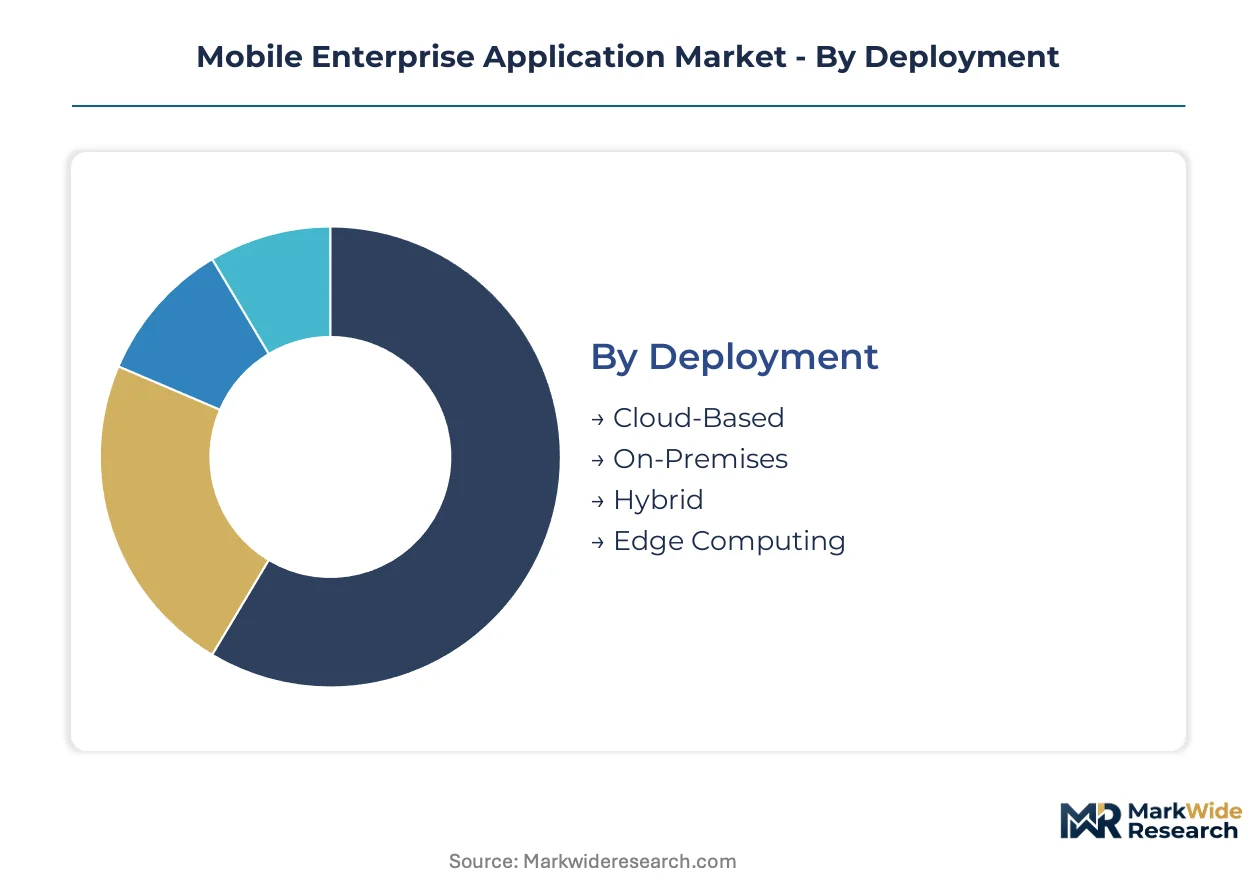
Understanding the Mobile Enterprise Application Market through segmentation reveals distinct demand patterns and competitive dynamics. Each segment reflects unique operational requirements and technological dependencies, influencing adoption rates and solution development across diverse business functions.
Deployment:
The deployment landscape faces significant substitution pressure, particularly as cloud-based models displace traditional on-premises solutions due to their inherent scalability and cost efficiencies.
- Cloud-Based:These solutions are hosted remotely by a third-party provider, accessed via the internet, and offer flexible scalability and reduced upfront infrastructure costs. Demand concentrates in small and medium-sized enterprises seeking operational expenditure models and rapid deployment in the United States.
- On-Premises:Applications installed and run on an organization's internal servers and infrastructure provide maximum control over data and customization. Enterprises with stringent data security requirements or complex legacy system integrations, particularly in Germany, continue to utilize this model.
- Hybrid:This model combines elements of both cloud and on-premises deployments, allowing organizations to maintain sensitive data on-site while leveraging cloud flexibility for other functions. Organizations balancing regulatory compliance with agile development often adopt hybrid approaches.
- Edge Computing:Data processing occurs closer to the data source, reducing latency and bandwidth usage, which is critical for real-time field operations and remote monitoring. Adoption is increasing in industrial automation and logistics sectors, especially for field operations in Germany.
On-Premises deployment anchors the volume base while Edge Computing gains share at the steepest rate.
Solution Type:
Solution types differentiate by their core application focus, ranging from customer engagement to internal resource management, each addressing specific business process needs.
- Customer Relationship Management:These applications manage and analyze customer interactions and data throughout the customer lifecycle, improving business relationships and assisting in customer retention. Demand for mobile CRM is strong within sales and service teams, particularly across the United States.
- Enterprise Resource Planning:Integrated software systems manage core business processes, including financials, human resources, manufacturing, and supply chain operations. Large manufacturing and logistics firms in Germany drive significant ERP mobile adoption for real-time operational visibility.
- Supply Chain Management:Applications that manage the flow of goods, data, and finances related to a product or service, from raw materials to delivery. These solutions are critical for optimizing logistics in the transportation sector.
- Human Capital Management:Software designed to manage an organization's human resources, including payroll, benefits, talent acquisition, and performance management. Mobile HCM supports remote workforce management and employee self-service.
- Content Management:Systems that organize and store digital content, enabling collaboration and efficient information sharing across mobile devices. These applications support mobile document access and team collaboration.
Customer Relationship Management and Enterprise Resource Planning applications collectively dominate the solution type segment.
Use Case:
Use cases contribute varying levels of operational volume, with some directly impacting field productivity and others streamlining back-office functions.
- Field Service Management:Applications that optimize the scheduling, dispatching, and execution of field service tasks, often including real-time communication and access to customer data. Utilities and telecommunications companies in the United States rely heavily on these tools.
- Inventory Tracking:Solutions that monitor and manage stock levels, locations, and movements of goods within a supply chain, often utilizing barcode or RFID scanning. Manufacturing and retail sectors use these applications for real-time stock visibility.
- Workforce Collaboration:Tools that facilitate communication, task management, and document sharing among employees, enhancing team productivity regardless of physical location. Remote and hybrid work models drive adoption across various industries globally.
- Mobile Payments:Applications enabling secure financial transactions through mobile devices, ranging from point-of-sale systems to in-app purchases. The retail and hospitality sectors are key adopters of these solutions.
- Asset Management:Software used to track and manage an organization's physical assets, including their location, maintenance schedules, and depreciation. This use case is vital for industries with extensive equipment, such as energy and logistics.
Field Service Management remains a high-volume use case, while Mobile Payments is emerging as a critical growth area.
End User Industry:
End-user industries exhibit distinct geographical adoption patterns, influenced by regional economic structures and regulatory environments.
- Manufacturing:This sector utilizes mobile enterprise applications for production monitoring, quality control, and supply chain visibility across factory floors and logistics networks. Major manufacturing hubs in Germany are significant adopters.
- Transportation & Logistics:Mobile applications optimize route planning, fleet management, delivery tracking, and warehouse operations, crucial for efficient global supply chains. This industry is a primary growth engine for the market, particularly in the United States.
- Energy & Utilities:Applications support field workforce management, asset inspection, and remote monitoring of infrastructure for power, water, and gas networks. These solutions enhance operational safety and efficiency.
- Telecommunications:Mobile enterprise applications facilitate network management, customer service, and field technician support for telecommunications providers. The global rollout of 5G networks drives new application requirements.
- Education:Institutions use mobile applications for campus management, student engagement, and remote learning platforms. These solutions support administrative tasks and educational content delivery.
The Transportation & Logistics sector is a major consumer of mobile enterprise applications, while the Telecommunications industry shows consistent expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for mobile enterprise applications exhibits asymmetry, with established vendors commanding higher rates in mature markets. Conversely, emerging economies prioritize cost-effective, scalable solutions for rapid digital transformation. This dynamic influences investment and development strategies across different regions.
United States
Demand for mobile CRM and field service applications is strong across the United States. HIPAA regulations drive secure data handling requirements for healthcare mobile solutions. Silicon Valley and other tech hubs like Austin and Seattle foster innovation in cloud-based mobile application development.
Germany
Manufacturing and logistics firms in Germany drive significant mobile ERP adoption for real-time operational visibility. GDPR mandates stringent data privacy and protection for all mobile enterprise applications. Industrial clusters in Bavaria and North Rhine-Westphalia are at the forefront of adopting edge computing for field operations.
China
Digitalization mandates and the vast manufacturing sector in China propel mobile application usage. Data sovereignty laws in China compel developers to consider localized cloud infrastructure and data residency. Major economic zones like the Yangtze River Delta concentrate demand for supply chain management and manufacturing execution systems.
India
Government initiatives and a large remote workforce in India necessitate secure, high-performance mobile applications. India's PLI scheme encourages local manufacturing, boosting demand for mobile-enabled production management tools. Technology centers in Bangalore and Hyderabad are developing localized solutions for various enterprise functions.
Vietnam
Underpenetrated manufacturing and logistics sectors in Vietnam present significant opportunities for mobile ERP and supply chain management. The Vietnamese government actively promotes digital transformation across industries. Ho Chi Minh City and Hanoi are emerging as centers for adopting mobile solutions to optimize logistics and field operations.
Mobile Enterprise Application Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the mobile enterprise application market. The market structure exhibits a tiered consolidation, with established software giants at the top and specialized niche players addressing specific industry needs. Strategic archetypes include integrated platform providers, cloud-native specialists, and hardware ecosystem controllers. Portfolio diversification and strategic partnerships are dominant competitive moves among these entities.
Specialized cloud-native providers, such as Salesforce, Inc., exemplify innovation in customer relationship management and sales force automation applications, offering flexible, subscription-based models. These companies often focus on user experience and rapid deployment within their specific domains. Integrated platform vendors like SAP SE leverage deep enterprise resource planning integration to anchor their position in manufacturing and supply chain sectors, providing comprehensive, end-to-end solutions for complex business processes. Meanwhile, Apple Inc. controls a significant hardware and operating system ecosystem, influencing app development standards and security protocols across its device base, thereby shaping the mobile application landscape for its users.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Salesforce, Inc. |
| Google LLC |
| Apple Inc. |
| HP Enterprise Company |
| Adobe Inc. |
| Others |
Cost & Logistics Intelligence
Subscription-based contracts lock in predictable revenue streams for vendors and offer scalable access for enterprises to mobile application services. These agreements ensure continuous feature updates and technical support, influencing long-term customer relationships.
Pricing Analysis
Configured-to-order pricing commands a premium for specialized mobile enterprise applications, contrasting with more standardized offerings. The dominant pricing structure remains subscription-based SaaS-tiered models, offering predictable operational expenses for businesses. Customization levels and comprehensive after-sales service, including integration support, drive significant price differentiation, particularly for large enterprises. Pricing softness emerges for off-the-shelf solutions due to intense competition among cloud-native providers, impacting small and medium-sized enterprises.
Supply Chain Analysis
The limited availability of specialized cybersecurity professionals underpins a critical supply chain risk for mobile enterprise application development. Geographic concentration of core development talent centers in the United States, Germany, and India. Key dependencies include robust cloud infrastructure services from hyperscalers and advanced API security tools, while platform fragmentation creates architectural complexity. Distribution runs through cloud-based SaaS platforms, enabling rapid deployment and continuous updates globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile enterprise application market is experiencing a significant buyer-power shift, driven by the increasing consolidation of enterprise IT budgets towards integrated platform suites. This trend forces vendors to offer more comprehensive solutions to meet evolving client demands.
For Market Incumbents:Shield core market share against specialized point solutions by deepening ERP and CRM integration capabilities. SAP SE and Oracle Corporation must invest in advanced API security and containerization features to address data privacy regulations like GDPR. This strategy mitigates the threat of niche cloud-native specialists eroding market presence within manufacturing and supply chain sectors. Expanding partnerships with hardware ecosystem controllers like Apple Inc. can also enhance device-level security and user experience for enterprise clients.
For New Entrants and Emerging Players:Unaddressed service-layer gaps exist in localized cloud infrastructure for data sovereignty compliance, particularly in markets like China and India. New entrants can target underpenetrated sectors in Southeast Asia, focusing on mobile ERP for manufacturing and logistics. A strong go-to-market angle involves offering industry-specific solutions with embedded AI/ML for predictive analytics, especially for field service management in utilities. This approach leverages agility to capture segments where large incumbents move slower.
For Investors and Strategic Acquirers:Cloud-native specialized application developers with strong intellectual property in AI/ML integration represent attractive acquisition targets for long-term growth. The market offers sustained viability over the next decade as digital transformation initiatives continue across industries. Investors should seek firms demonstrating proven expertise in API security and compliance with data privacy regulations like HIPAA. A key signal to watch is the increasing adoption rate of augmented reality in field service applications, indicating readiness for advanced mobile solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Expansion | Deepens competitive moats for integrated suites like SAP SE by offering end-to-end business process coverage. |
| AI/ML Feature Development | Provides predictive analytics and next-best-action recommendations, enhancing value for mobile CRM and sales applications. |
| Geographic Market Entry in Southeast Asia | Captures white space in manufacturing and logistics sectors within emerging economies like Vietnam and Indonesia. |
| Enhanced API Security Protocols | Mitigates data breach risks and addresses compliance requirements for sensitive corporate data connections. |
| Containerization Technology Adoption | Enables secure BYOD policies and granular app-specific security controls for regulated industries. |
Research Approach
The analysis maps mobile CRM, ERP, SCM, HCM, and Content Management sub-sectors, each validated through primary interviews with CTOs, IT procurement officers, and enterprise mobility managers. This approach combines insights from industry stakeholders with secondary validation from SEC 10-K filings and technology journals. Bottom-up data aggregation and top-down market sizing ensure robust triangulation of findings.
Consistency checks against external benchmarks validated the volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including deployment model, solution type, use case, end-user industry, and organization size. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Key forecast inputs included global 5G network expansion rates and remote work adoption statistics.
Underlying assumptions cover a stable regulatory environment and sustained digital transformation initiatives, with deviation risk concentrated in unforeseen geopolitical shifts. Forecasts reflect these assumptions, but rapid technological disruptions could alter market trajectories. Practitioners should keep alternative scenarios live as global economic conditions and technological innovation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Online Corporate Meeting Services Market