
 Global Managed Infrastructure Service Market | 2026-2036
Global Managed Infrastructure Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed Infrastructure Service Market Foresight
Market Context
Modular service bundling is consolidating buyer choice as enterprises shift from point solutions to integrated infrastructure platforms. IBM leverages its hybrid cloud consulting depth to anchor large enterprise migrations. Amazon Web Services competes through extensive global data center presence and native tooling integration. Microsoft differentiates by embedding managed infrastructure within broader productivity and enterprise software ecosystems.
Technical Definition and Segments
Managed infrastructure service denotes the ongoing remote operation, monitoring, maintenance, and optimization of an organization's compute, storage, network, and security infrastructure by a third-party provider, typically governed by service-level agreements specifying uptime thresholds, response times, and security compliance parameters. Hybrid cloud deployment models now capture the fastest expansion as enterprises balance latency-sensitive workloads on-premises with elastic burst capacity in public cloud environments. Security management services command premium pricing due to escalating regulatory complexity and specialized talent scarcity. Network management remains the most mature segment, with margin pools shifting toward software-defined orchestration and zero-trust architecture implementations.
Regulatory Framework
The EU AI Act, GDPR, and NIS2 Directive collectively reshape demand by mandating algorithmic transparency, data sovereignty, and critical infrastructure resilience across European operations. The SEC's cybersecurity disclosure rules and HIPAA requirements in the United States impose parallel compliance burdens that drive outsourcing to specialized managed service providers. Stakeholders must monitor emerging sector-specific certification requirements as regulators in India, Japan, and Brazil develop localized frameworks that could fragment service delivery standards and increase operational complexity for multinational providers.
Market Dynamics
Hybrid cloud orchestration platforms are compressing infrastructure decision cycles as enterprises abandon multi-year capital planning for consumption-based operational models. The shift from ownership to outcome-based service consumption rewrites procurement authority and vendor selection criteria across IT organizations.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for high-risk AI systems force financial services and healthcare providers to outsource security-hardened infrastructure operations to specialized managed service providers with established audit trails.
- Edge computing proliferation:Latency-sensitive manufacturing automation and autonomous vehicle development in Germany, Japan, and the United States demands localized compute infrastructure that enterprise IT teams cannot operationally support at scale.
- Critical talent scarcity:Specialized cybersecurity and cloud architecture skills concentrate in Bangalore, Dublin, and Singapore, making remote managed service delivery more cost-effective than internal capability building for most mid-market enterprises.
Market Restraints
- Input cost volatility:Energy prices and semiconductor component costs for server and networking equipment fluctuate unpredictably, compressing margins for fixed-price managed infrastructure contracts.
- Supply concentration risk:Hyperscale cloud infrastructure depends on a limited set of Taiwan-based semiconductor foundries and Oregon-based memory suppliers, creating geographic vulnerability in hardware refresh cycles.
- Data sovereignty friction:Conflicting localization requirements between India's data protection framework, China's cybersecurity law, and EU GDPR create operational complexity for multinational managed service architectures.
Strategic Opportunities
- Brazilian market underpenetration:Latin America's second-largest economy shows managed infrastructure penetration rates below one-third of North American levels, with local banking and agribusiness verticals actively seeking sovereign cloud partnerships.
- AI workload optimization services:GPU cluster management and model training pipeline orchestration represent emerging high-margin service layers as enterprises deploy generative AI without internal infrastructure expertise.
- Converged security-operations bundles:Integration of extended detection and response with infrastructure management creates defensible positioning against point-solution security vendors.
Industry Challenges
- Multi-cloud skill fragmentation:Certified architects fluent in AWS, Azure, and Google Cloud Platform simultaneously command compensation premiums that erode service provider margins.
- Technical debt integration:Decades-old mainframe and proprietary Unix environments in insurance and government sectors resist standard automation tooling, requiring costly custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed Infrastructure Service Market |
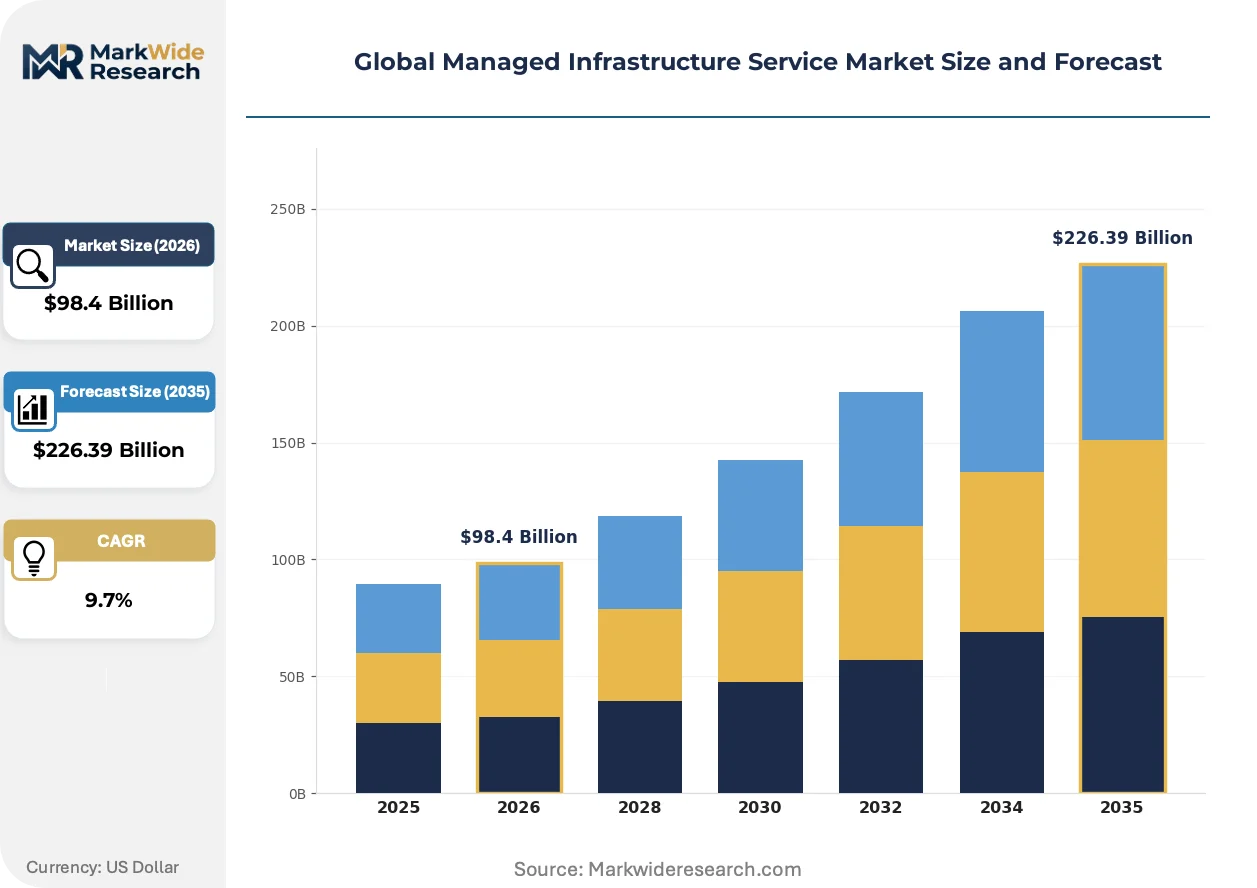
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $226.39 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Server Management, Storage Management, Security Management, Database Administration Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises, Multi-Cloud End User: Telecommunications Providers, Manufacturing Firms, Educational Institutions, Financial Services Firms, Government Agencies Pricing Model: Subscription-Based, Pay-As-You-Go, Tiered Pricing, Per Device, Flat Rate |
| Companies Covered | IBM, Amazon Web Services, Microsoft, Google Cloud, Oracle, Fujitsu, Cisco Systems, Hewlett Packard Enterprise, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed Infrastructure Service Market Shifts & Advancements
Infrastructure abstraction layers are dissolving traditional boundaries between compute, storage, and network management, forcing service providers to reassemble capabilities around workload outcomes rather than technology domains. This architectural convergence redefines competitive differentiation and pricing architecture.
Software-defined infrastructure is unifying previously siloed resource pools through programmable control planes that automate provisioning across on-premises, colocation, and public cloud environments. Financial services firms in London and Singapore are adopting these platforms most aggressively, compressing deployment timelines from months to days. The technology is unifying procurement decisions that previously fragmented across separate server, storage, and networking vendor relationships.
The EU NIS2 Directive mandates operational resilience reporting and incident notification timelines for critical infrastructure operators across member states. Managed service providers must now embed continuous compliance monitoring and automated evidence collection into standard service delivery. Energy utilities and transportation operators in Germany and France represent the most affected segments, accelerating outsourcing to providers with pre-built regulatory tooling.
Enterprise buyers are consolidating vendor relationships around integrated platform contracts that bundle infrastructure, security, and application management under unified service level agreements. This behavior shift displaces point-solution procurement that previously fragmented across dozens of specialized providers. Healthcare systems in the United States and manufacturing conglomerates in Japan demonstrate this consolidation most visibly, prioritizing accountability concentration over best-of-breed component selection.
Global Managed Infrastructure Service Market Segmentation
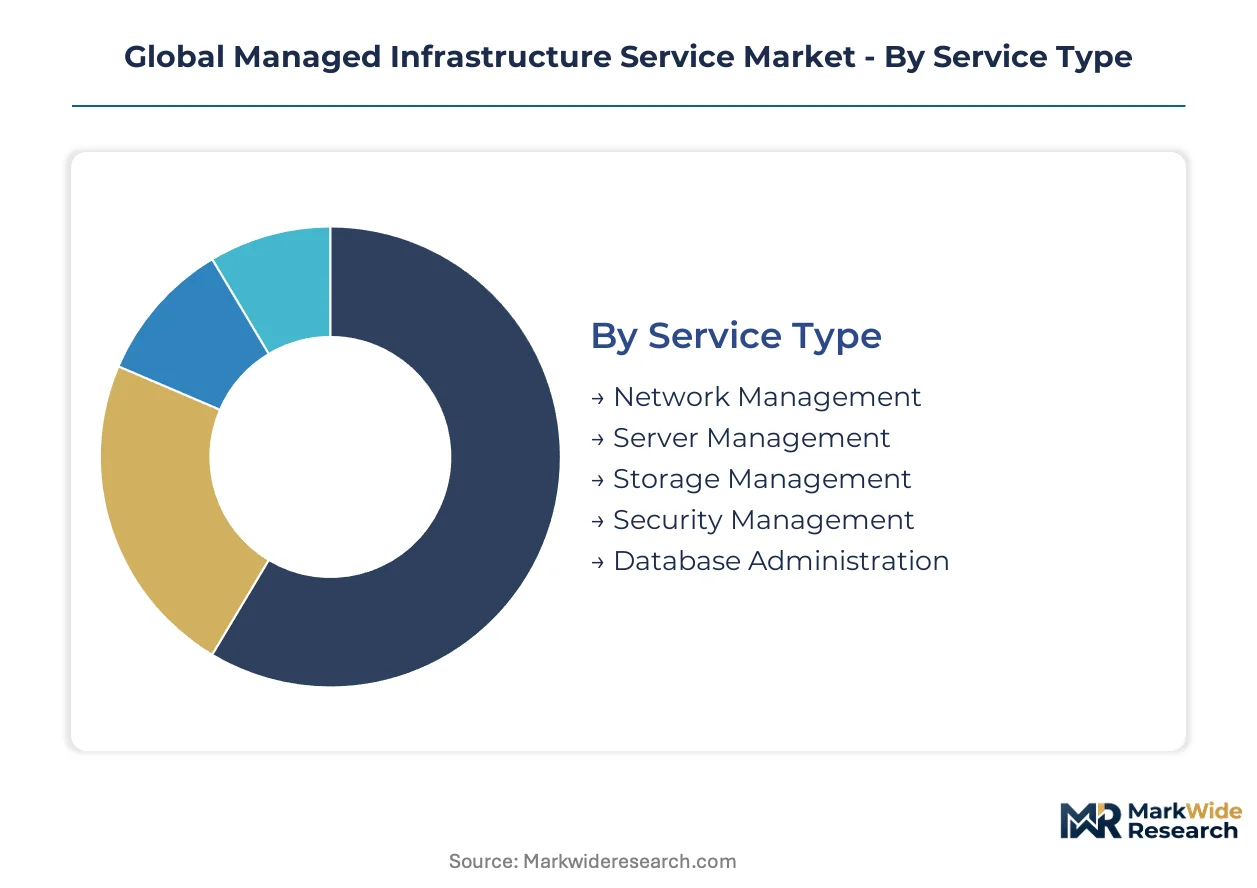
Segmentation in managed infrastructure services reveals how procurement authority, technical requirements, and compliance burdens reshape vendor selection criteria. Service providers must align delivery architectures with distinct operational rhythms across deployment models and end-user verticals.
Service Type:
Integration depth varies sharply across service types, with standalone monitoring tools coexisting alongside deeply embedded security automation stacks that permeate every infrastructure layer.
- Security Management:Continuous threat detection, identity governance, and compliance evidence collection operate as embedded functions across all infrastructure tiers. Financial services firms in Germany and the United States concentrate demand here, driven by SEC cybersecurity disclosure mandates and EU AI Act algorithmic transparency requirements.
- Network Management:Software-defined orchestration and zero-trust architecture implementations now dominate this mature segment. Manufacturing conglomerates in Japan prioritize latency-optimized connectivity for industrial automation, compressing procurement cycles from multi-year frameworks to consumption-based agreements.
- Server Management:Remote provisioning, patch orchestration, and capacity optimization for physical and virtual compute resources.
- Storage Management:Tiered data lifecycle governance across on-premises arrays and cloud object stores.
- Database Administration:Performance tuning, backup orchestration, and query optimization for relational and NoSQL environments.
Volume placements concentrate in Network Management; the faster expansion belongs to Security Management.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models that dominate mid-market procurement.
- Hybrid Cloud:Workload portability between on-premises infrastructure and public cloud burst capacity demands sophisticated orchestration platforms. Enterprises in Singapore and India adopt this model most aggressively, balancing data sovereignty requirements with elastic scalability for seasonal demand spikes.
- Multi-Cloud:Deliberate distribution across AWS, Azure, and Google Cloud Platform mitigates vendor lock-in while introducing operational complexity. Technology firms in Ireland and the Netherlands lead adoption, driven by regulatory pressure to avoid single-provider concentration risk.
- Private Cloud:Dedicated infrastructure environments serving single-tenant compliance and performance requirements.
- Public Cloud:Shared infrastructure resources with standardized service tiers and rapid provisioning.
- On-Premises:Fully captive infrastructure retained for latency-sensitive or classified workloads.
Procurement volume clusters in Hybrid Cloud deployments; Multi-Cloud architectures are climbing the fastest as sovereignty concerns intensify.
End User:
Application-specific requirements dictate service packaging, with regulated verticals demanding embedded compliance tooling that generalist providers cannot replicate.
- Financial Services Firms:Algorithmic trading infrastructure, real-time risk calculation clusters, and audit-ready compliance documentation define service specifications. Banks in Brazil and asset managers in Switzerland outsource most aggressively, confronting Basel III operational resilience mandates and local data protection frameworks simultaneously.
- Government Agencies:Classified workload isolation, supply chain attestation, and incident response protocols impose stringent provider qualification. Defense and civilian operators in France and Germany accelerate outsourcing under NIS2 Directive timelines, favoring vendors with pre-certified sovereign cloud architectures.
- Telecommunications Providers:5G core network management and edge compute orchestration for subscriber-facing services.
- Manufacturing Firms:Industrial IoT connectivity, predictive maintenance platforms, and OT-IT convergence security.
- Educational Institutions:Research computing clusters, learning management system hosting, and campus network operations.
Revenue concentration sits with Financial Services Firms; Government Agencies show the steepest expansion trajectory as NIS2 enforcement deadlines approach.
Pricing Model:
Customer type and contract maturity determine pricing architecture, with enterprise procurement teams negotiating outcome-based structures that displace traditional unit economics.
- Subscription-Based:Fixed monthly or annual fees for defined service scopes and SLA guarantees. Healthcare systems in the United States prefer this predictability for budget planning, embedding HIPAA compliance costs into contracted rates.
- Pay-As-You-Go:Consumption-metered billing tied to actual resource utilization and incident volume. E-commerce platforms in India and SaaS providers in Singapore favor this elasticity, aligning infrastructure costs with revenue volatility.
- Tiered Pricing:Bronze-silver-gold service levels with escalating response times and support channels.
- Per Device:Endpoint-counted billing for workstation, server, and network appliance management.
- Flat Rate:Unlimited service scope within defined infrastructure boundaries for simple procurement.
Contract volume aggregates under Subscription-Based terms; Pay-As-You-Go is gaining share fastest among cloud-native enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service delivery capacity concentrates in technology hubs across Germany, the United States, and India while enterprise consumption spreads through financial centers in Singapore, Switzerland, and Brazil. Regulatory divergence between data sovereignty regimes fragments operational architectures for multinational providers.
United States
Financial services firms in New York and Chicago drive security-hardened infrastructure outsourcing to meet SEC cybersecurity disclosure mandates. Healthcare systems across the Midwest embed HIPAA compliance costs into multi-year managed service contracts. The Dallas-Fort Worth metroplex anchors hyperscale data center expansion for latency-sensitive trading infrastructure.
Germany
Industrial automation manufacturers in Bavaria demand localized edge compute for predictive maintenance platforms under NIS2 Directive operational resilience timelines. Frankfurt's banking cluster sources sovereign cloud partnerships to satisfy Bundesbank audit requirements. Stuttgart's automotive engineering centers deploy hybrid cloud orchestration for simulation workload burst capacity.
India
Bangalore's technology corridor exports remote infrastructure management to mid-market enterprises globally, capitalizing on certified cloud architecture talent scarcity. Mumbai's financial institutions adopt subscription-based pricing for budget predictability under evolving RBI data localization guidelines. Hyderabad's pharmaceutical manufacturers integrate compliance monitoring for US FDA audit readiness.
Singapore
Wealth management firms in the central business district procure multi-cloud architectures to mitigate vendor concentration risk under Monetary Authority of Singapore operational resilience standards. The Jurong Lake District anchors maritime logistics platform modernization. Fintech startups in One-North favor pay-as-you-go consumption models aligned with revenue volatility.
Brazil
São Paulo's banking sector accelerates sovereign cloud partnerships under LGPD data protection enforcement, with penetration rates trailing North American benchmarks by two-thirds. Agribusiness conglomerates in Mato Grosso seek localized infrastructure for supply chain traceability platforms. The federal government's digital transformation agenda creates procurement opportunities for compliance-embedded service bundles.
Global Managed Infrastructure Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service portfolios. Hyperscale cloud providers anchor premium pricing through native tooling integration while systems integrators capture migration complexity premiums. Three archetypes dominate: full-stack platform vendors, security-centric specialists, and regional compliance experts. Consolidation pressures intensify as enterprise buyers demand unified accountability, driving partnership formations between hardware manufacturers and software orchestration layers.
Within the full-stack platform tier, IBM leverages hybrid cloud consulting depth to anchor large enterprise migrations, while Amazon Web Services competes through extensive global data center presence. Microsoft occupies a distinct position by embedding managed infrastructure within productivity and enterprise software ecosystems, creating switching cost advantages. These three exemplify how vertical integration into adjacent software layers reshapes competitive positioning.
| Leading Market Players |
|---|
| IBM |
| Amazon Web Services |
| Microsoft |
| Google Cloud |
| Oracle |
| Fujitsu |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon neutrality mandates for data center operations gate qualified supply access and premium-tier pricing for managed infrastructure providers. Buyers seeking sovereign cloud partnerships in Germany and Singapore now embed energy efficiency certifications as non-negotiable procurement criteria, bifurcating the vendor base between compliant premium operators and excluded commodity players.
Pricing Analysis
Margin tightening in security-hardened tiers reflects specialized talent scarcity and continuous compliance monitoring costs. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by certification level (ISO 27001, SOC 2 Type II) and embedded regulatory tooling depth. Cost-down pressure on standard tiers accelerates because hyperscale cloud providers absorb infrastructure overhead at scale. Financial services firms in Switzerland show least price sensitivity; mid-market manufacturers in Brazil exhibit highest elasticity.
Supply Chain Analysis
India's domestic-content guidelines for government cloud procurement reshape sourcing patterns for multinational providers seeking public sector contracts. Hardware supply draws from Taiwan semiconductor foundries, Oregon memory suppliers, and Malaysian server assembly facilities. Critical dependencies span advanced GPUs, high-bandwidth memory modules, and specialized network processors. Single-source vulnerability concentrates in Taiwan-based foundry capacity. Distribution runs through direct enterprise sales, systems integrator partnerships, and hyperscale marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Managed Infrastructure Service Market operates as a cost-of-compliance story where EU AI Act algorithmic transparency mandates erect barrier-to-entry moats favoring providers with pre-built audit infrastructure.
For Market Incumbents: Lock in enterprise relationships through NIS2 Directive pre-certification bundles that emerging competitors cannot replicate without multi-year investment. Deepen backward integration into sovereign cloud hardware supply chains to defend against hyperscale provider margin compression. Prioritize Frankfurt and Singapore delivery capacity to capture financial services demand concentration. For New Entrants and Emerging Players: Capture Brazilian agribusiness and banking verticals where managed infrastructure penetration trails North American benchmarks by two-thirds. Target GPU cluster management services for generative AI deployments as enterprises lack internal infrastructure expertise. Lead with pay-as-you-go consumption models aligned with local revenue volatility. For Investors and Strategic Acquirers: NIS2 Directive enforcement deadline acceleration is the leading indicator that government agency outsourcing velocity will steepen across Germany and France. Five-to-ten year viability favors providers with embedded compliance tooling over point-solution infrastructure vendors. Monitor sovereign cloud partnership announcements between hyperscalers and national telecom operators as inflection signals for market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Enables data residency compliance for Bundesbank-audited Frankfurt banking clusters. |
| AI Workload Optimization Service Launch | Captures GPU cluster management demand from generative AI deployments without internal expertise. |
| Security-Operations Bundle Integration | Creates defensible positioning against CrowdStrike and SentinelOne point-solution encroachment. |
| Edge Compute Orchestration Platform | Supports Bavarian industrial automation latency requirements under NIS2 operational resilience timelines. |
| Multi-Cloud Certification Investment | Addresses AWS-Azure-Google Cloud skill fragmentation eroding service provider margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with CIOs, cloud procurement officers, managed service delivery leads, and compliance audit specialists combined with secondary validation from SEC cybersecurity disclosures, EU AI Act implementation guidance, and hyperscaler capex reports. Bottom-up service provider revenue triangulation against top-down enterprise IT spending estimates established analytical boundaries.
Data-stream reconciliation across deployment model, end-user vertical, pricing architecture, and regional regulatory cluster segmentation enabled projection modeling. CAGRs derived from elasticity-adjusted adoption curves and compliance deadline acceleration effects. Industry-specific forecast inputs incorporated NIS2 enforcement timeline shifts and sovereign cloud partnership formation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply concentration disruptions and divergent data sovereignty enforcement across India, Brazil, and ASEAN markets. Forecasts reflect documented assumptions without guarantee of realization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
Supplier Management Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Field Service Management Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market