
 Global Intranet As a Service Market | 2026-2036
Global Intranet As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intranet As a Service Market Outlook
GDPR enforcement is expanding the cost-of-entry calculus for intranet vendors serving European enterprises. Microsoft leverages its Azure sovereign cloud architecture to sustain compliance-led contracts with German automotive and French pharmaceutical clients. Google competes through Workspace-integrated intranet modules that anchor real-time collaboration for distributed knowledge workers. Simpplr differentiates via AI-powered content personalization that dominates employee engagement metrics in North American financial services deployments.
Intranet As a Service denotes cloud-hosted digital workplace platforms that deliver internal communications, document management, and social collaboration through multi-tenant architectures with guaranteed uptime parameters and API-based extensibility. These systems centralize policy distribution, self-service HR functions, and executive messaging to reduce email volume and accelerate information discovery across geographically dispersed organizations. Subscription Services capture recurring revenue streams with the highest margin profiles, while Managed Services generate sticky multi-year engagements as enterprises outsource platform administration and security patching. Hybrid Cloud deployments are gaining traction among healthcare and financial verticals where patient records and trading data must remain on-premises while non-sensitive modules shift to public infrastructure.
The EU AI Act, GDPR, and ISO 27001 framework collectively reshape product roadmaps by mandating algorithmic transparency, data residency controls, and certified information security management across intranet deployments. FDA 21 CFR Part 11 in the United States imposes additional validation requirements on intranet systems handling electronic records in pharmaceutical manufacturing environments. Stakeholders must monitor how emerging sovereign data laws in India, Brazil, and Saudi Arabia fragment hosting architectures and force localization investments that alter vendor economics and partnership structures.
Market Dynamics
Cloud-native architectures are displacing legacy on-premises SharePoint deployments as enterprises seek API extensibility and guaranteed uptime SLAs. The EU AI Act and GDPR compliance requirements are accelerating vendor consolidation around managed service models with embedded data governance.
Growth Catalysts
- GDPR enforcement expansion:European enterprises face escalating penalties for data residency violations, pushing procurement toward intranet vendors with certified EU sovereign hosting. German automotive conglomerates anchor this demand shift.
- Healthcare workflow unification:Cloud-based employee portals consolidate clinical documentation, shift scheduling, and policy distribution. Hospital systems in the United States prioritize HIPAA-compliant platforms with FDA 21 CFR Part 11 validation.
- Generative AI integration:Natural language interfaces automate content tagging and semantic search across document repositories. Financial services firms deploy these capabilities to reduce information discovery friction.
Market Restraints
- Data localization mandates:India's emerging sovereign data laws and Brazil's LGPD amendments fragment hosting architectures. Vendors must establish in-country infrastructure, compressing margins and extending deployment timelines.
- Legacy system entrenchment:Industrial conglomerates in Germany maintain decades-old SharePoint customizations with deep ERP integrations. Migration costs and business continuity risks delay platform replacement decisions.
- Skills scarcity in cloud security architecture:Enterprises lack internal expertise to configure zero-trust access controls and encryption key management. This dependency inflates managed service premiums and extends vendor lock-in.
Strategic Opportunities
- Saudi Arabia's digital transformation mandates:Vision 2030 initiatives require modern workplace platforms for public sector and state-owned enterprises. SFDA compliance frameworks create entry barriers favoring established vendors with regional hosting partnerships.
- AI-powered content personalization:Behavioral analytics engines tailor executive communications and HR self-service interfaces to individual roles. North American financial services deployments demonstrate measurable engagement metric improvements.
- Hybrid cloud orchestration:Healthcare providers in the United States deploy patient record modules on-premises while shifting non-sensitive collaboration tools to public infrastructure. This architecture satisfies HIPAA constraints while capturing cloud elasticity.
Industry Challenges
- Algorithmic transparency compliance:The EU AI Act mandates explainability for AI-driven content recommendations. Engineering teams must retrofit black-box personalization engines with auditable decision trails, extending product development cycles.
- Multi-tenant security isolation:Shared infrastructure architectures face escalating scrutiny from financial services regulators. Demonstrating tenant-boundary integrity across ISO 27001 and SOC 2 frameworks consumes substantial audit resources.
- Cross-border data transfer complexity:Schrems II rulings invalidated Privacy Shield mechanisms. Intranet vendors must implement Standard Contractual Clauses with supplementary technical measures for EU-US data flows, complicating roadmap prioritization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intranet As a Service Market |
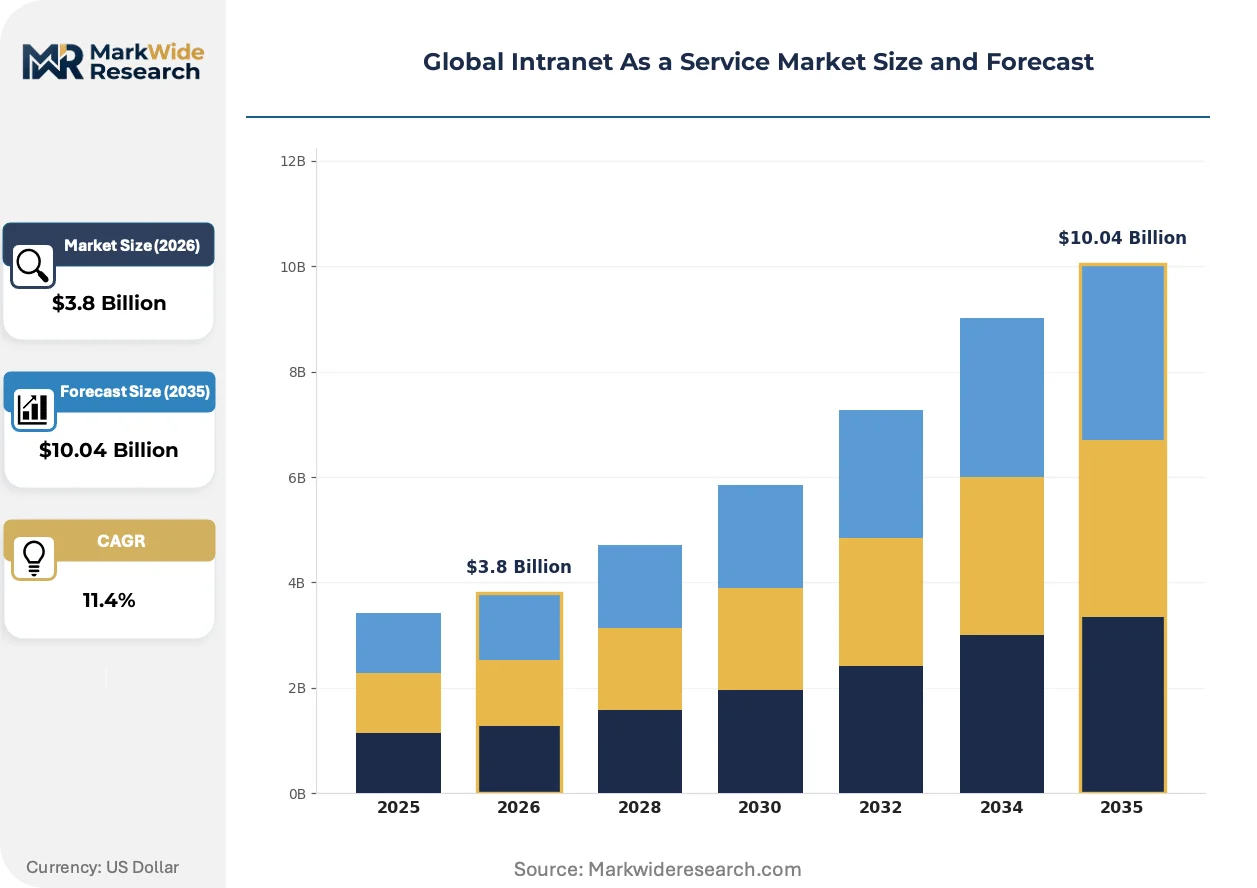
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Subscription Services, Consulting Services, Training Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Financial Services, Manufacturing, Retail |
| Companies Covered | Microsoft, Google, Attollo Intranet, Simpplr, LumApps, Slack Technologies, Happeo, Unily, Jive Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intranet As a Service Market Strategic Shifts
Artificial intelligence is embedding into core platform functions, transforming static document repositories into adaptive knowledge systems. Regulatory pressure is simultaneously reshaping architectural decisions around data residency and algorithmic accountability.
Natural language processing engines are integrating semantic search and automated content classification into intranet platforms. Healthcare providers in Germany deploy these capabilities to surface clinical protocols across distributed hospital networks. The technology is integrating previously siloed knowledge bases, compressing information retrieval cycles from minutes to seconds.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on AI-enabled intranet features. High-risk deployments—those affecting employee evaluation or access to opportunities—require conformity assessments and CE marking. Pharmaceutical manufacturers in France and automotive suppliers in Germany are restructuring product roadmaps to segregate AI modules for independent audit.
Enterprise buying committees are consolidating vendor relationships around integrated workspace suites rather than standalone intranet point solutions. IT procurement teams in the United States prioritize platforms with native integration into existing identity providers and collaboration tools. This pattern concentrates contract value with vendors offering broad ecosystem connectivity, marginalizing specialized intranet-only providers.
Global Intranet As a Service Market Segmentation
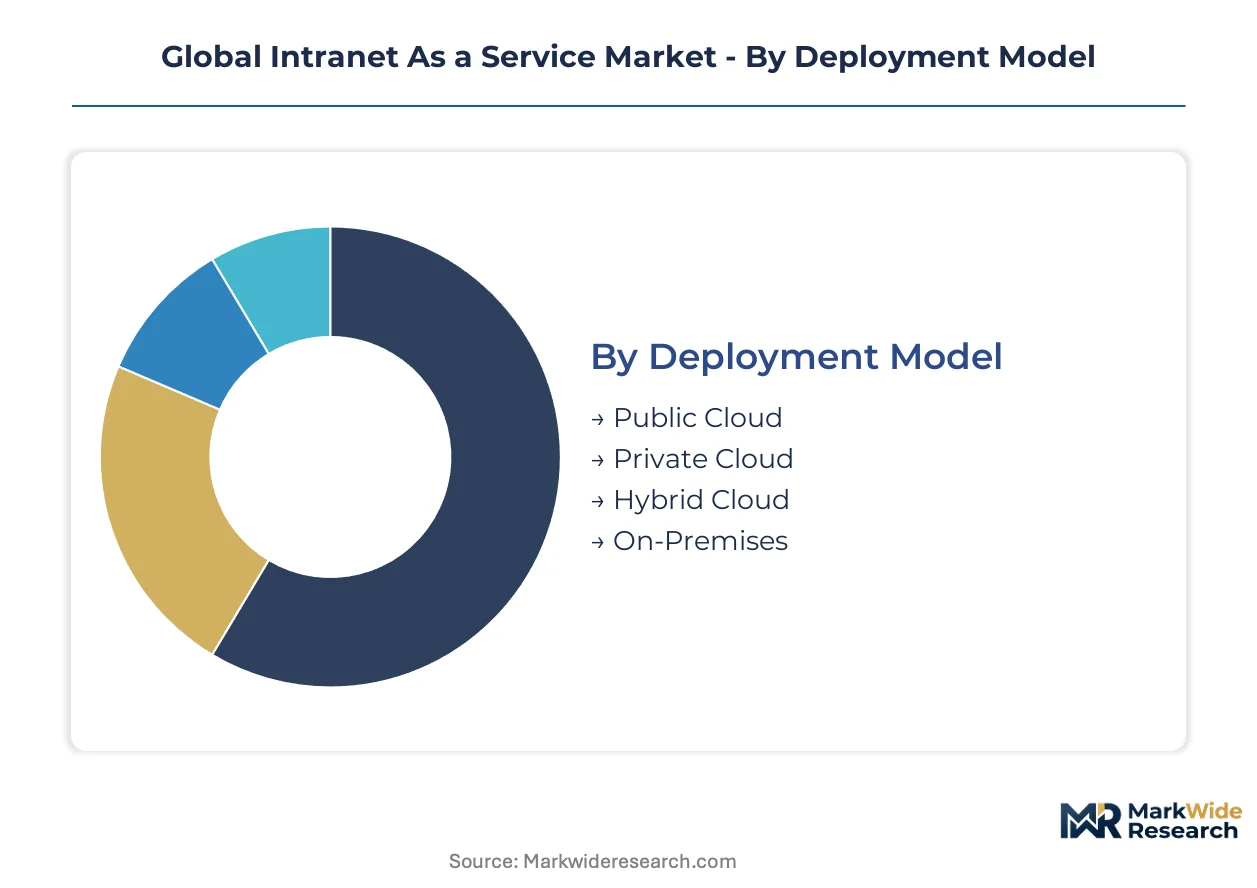
Intranet As a Service deployments fragment across infrastructure sovereignty requirements and procurement sophistication levels. Vendors calibrate delivery models to match data residency mandates, internal IT capabilities, and vertical-specific compliance burdens.
Deployment Model:
The customization-to-standardization spectrum spans fully controlled on-premises stacks to multi-tenant public infrastructure, with hybrid architectures occupying the middle ground for regulated workloads.
- Public Cloud:Multi-tenant SaaS architectures deliver elastic scaling and API extensibility through shared infrastructure. German automotive suppliers and French pharmaceutical manufacturers prioritize these deployments for non-sensitive collaboration modules under GDPR-compliant EU sovereign hosting.
- Hybrid Cloud:Split architectures maintain patient records or trading data on-premises while shifting general collaboration to public infrastructure. Healthcare systems in the United States deploy this model to satisfy HIPAA constraints without sacrificing cloud agility for administrative functions.
- Private Cloud:Single-tenant dedicated environments serve defense contractors and financial institutions requiring complete infrastructure isolation.
- On-Premises:Legacy installations persist in industrial conglomerates with deep ERP integrations and decades-old SharePoint customizations.
Most installed capacity flows through Public Cloud deployments. Expansion is steepest in Hybrid Cloud configurations.
Service Type:
Revenue concentration tilts toward recurring streams versus project-based engagements, with premium margins attaching to outsourced platform administration.
- Subscription Services:Recurring SaaS licenses generate the highest margin profiles through automated provisioning and minimal incremental delivery cost. North American financial services firms anchor demand for tiered seat-based pricing with guaranteed uptime SLAs.
- Managed Services:Multi-year outsourcing contracts cover platform administration, security patching, and compliance documentation. European enterprises facing EU AI Act and GDPR complexity drive procurement toward vendors embedding certified data governance.
- Consulting Services:Migration planning and legacy system integration engagements support SharePoint replacement initiatives.
- Training Services:Change management and user adoption programs accompany large-scale rollout deployments.
Subscription Services capture the dominant revenue share. Managed Services are climbing the fastest as compliance burdens intensify.
End User:
Procurement sophistication and security clearance requirements create distinct service tiers across organizational scale and sector.
- Large Enterprises:Complex governance needs and multi-national footprints demand federated identity management and regional data residency controls. Industrial conglomerates in Germany replace legacy environments with API-extensible platforms.
- Government Agencies:Classified information handling and sovereign data mandates require air-gapped or certified cloud environments. Saudi Vision 2030 initiatives and UAE digital transformation programs anchor public sector demand.
- SMEs:Standardized SaaS configurations with rapid deployment templates serve resource-constrained IT departments.
- Educational Institutions:Federated campus networks and student data privacy requirements shape procurement specifications.
Large Enterprises absorb the majority of vendor capacity. Government Agencies show the steepest expansion trajectory amid sovereign cloud investments.
Industry Vertical:
Regulatory density and workflow complexity determine platform configuration requirements across sectors.
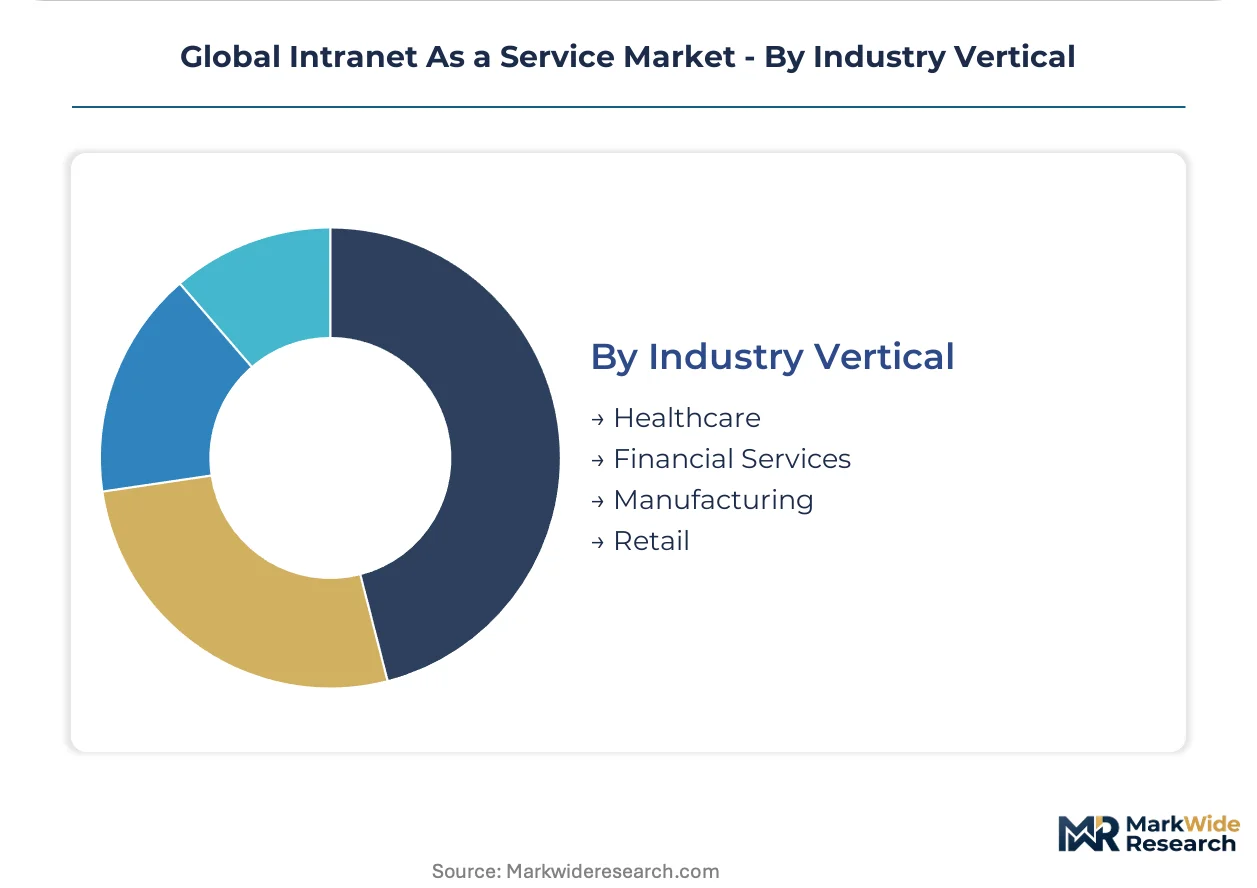
- Healthcare:HIPAA compliance and FDA 21 CFR Part 11 validation requirements dominate procurement criteria. Hospital systems in the United States prioritize platforms integrating clinical documentation, shift scheduling, and policy distribution.
- Financial Services:SOC 2 and ISO 27001 frameworks mandate multi-tenant security isolation and audit trail capabilities. Behavioral analytics engines for AI-powered content personalization demonstrate measurable engagement improvements in North American deployments.
- Manufacturing:ERP integration depth and shop-floor connectivity requirements shape platform selection.
- Retail:Distributed workforce coordination and seasonal staffing flexibility drive functional priorities.
Healthcare carries the largest installed base. Financial Services is gaining share fastest through AI-enabled personalization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in Seattle, Bangalore, and Tel Aviv anchor cloud platform development. These concentrations shape regional deployment patterns and vendor partnership structures.
United States
Hospital systems in Texas and California accelerate cloud-based employee portal adoption to unify clinical workflows. FDA 21 CFR Part 11 validation requirements dominate procurement criteria for pharmaceutical manufacturers in New Jersey and Massachusetts. Financial services firms in New York deploy AI-powered content personalization to reduce information discovery friction.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg replace legacy SharePoint environments with API-extensible platforms. GDPR enforcement and the EU AI Act push procurement toward vendors with certified EU sovereign hosting. Automotive suppliers in Stuttgart anchor demand for managed service deployments with embedded data governance.
United Kingdom
Financial services firms in London prioritize platforms with SOC 2 and ISO 27001 certification for multi-tenant security isolation. The Financial Conduct Authority's operational resilience requirements shape vendor selection for banking infrastructure. Fintech clusters in Manchester and Edinburgh drive demand for real-time collaboration tools.
India
IT services hubs in Bengaluru and Hyderabad generate demand for cloud-native intranet platforms supporting distributed knowledge workers. Emerging sovereign data laws under the Digital Personal Data Protection Act fragment hosting architectures. Global capability centers in Pune and Chennai require localized infrastructure investments.
Saudi Arabia
Vision 2030 initiatives mandate modern workplace platforms for public sector and state-owned enterprises in Riyadh. SFDA compliance frameworks create entry barriers favoring established vendors with regional hosting partnerships. NEOM development anchors large-scale digital workplace deployments.
Global Intranet As a Service Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across deployment models and compliance tiers. The vendor base organizes around three strategic archetypes: hyperscale cloud providers with sovereign hosting capabilities, vertical specialists targeting regulated industries, and workspace-integrated collaboration platforms. Consolidation pressures intensify as enterprise buying committees favor integrated suites over standalone point solutions. Strategic partnerships with regional hosting providers and compliance certification acquisitions represent dominant competitive moves.
Among hyperscale providers, Microsoft and Google occupy positions anchoring ecosystem-integrated deployments. Simpplr exemplifies the AI-native specialist archetype, sitting within the vertical-focused tier targeting engagement metric optimization in regulated sectors.
| Leading Market Players |
|---|
| Microsoft |
| Attollo Intranet |
| Simpplr |
| LumApps |
| Slack Technologies |
| Happeo |
| Unily |
| Jive Software |
| Others |
Value Chain & Pricing Dynamics
GDPR-mandated data residency requirements are compressing vendor margins as European enterprises demand EU sovereign hosting infrastructure. Supply chains must reconfigure around certified regional data centers, elevating delivery costs for compliance-heavy deployments.
Pricing Analysis
Bundled managed service offerings command premiums over unbundled SaaS licenses as compliance documentation and security patching shift to vendor responsibility. Pricing stratifies across premium, standard, and economy tiers based on uptime SLA guarantees and AI feature depth. Cost compression in the standard tier is intensifying because hyperscale providers leverage existing cloud infrastructure. SMEs exhibit highest price sensitivity, while German automotive conglomerates prioritize compliance certification over cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from Fortune 500 deployments, while regional hosting partnerships serve sovereign data mandates. Engineering talent concentrates in the United States, India, and Israel, anchoring platform development pipelines. Infrastructure provisioning draws from specialized data center operators in Germany, Ireland, and Singapore. Single-source vulnerability in AI model training data creates supply chain exposure. Distribution runs through certified managed service providers for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement committees consolidate around integrated workspace suites with embedded compliance certification. Demand is shifting toward premium specifications that bundle AI governance documentation and sovereign hosting guarantees.
For Market Incumbents: Anchor multi-year contract renewals through embedded managed service offerings that outsource EU AI Act compliance documentation. Invest in ISO 27001 and SOC 2 certification maintenance to defend against emerging vertical specialists. Deepen backward integration into regional hosting infrastructure to capture margin from data localization mandates. For New Entrants and Emerging Players: Regional hosting partners in Saudi Arabia and India provide the fastest path to sovereign compliance certification without capital-intensive infrastructure buildout. Target mid-market healthcare providers in the United States seeking HIPAA-compliant platforms with rapid deployment templates. Lead with AI-powered content personalization as a differentiated wedge against legacy SharePoint environments. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing pre-certified compliance frameworks for pharmaceutical and automotive sectors. Long-term viability hinges on ability to sustain multi-tenant security isolation investments across escalating regulatory scrutiny. Monitor FDA 21 CFR Part 11 validation pipeline velocity as an inflection indicator for healthcare vertical penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding into Microsoft 365 and Google Workspace ecosystems captures procurement committee consolidation. |
| Strategic Partnership | Regional hosting alliances in Germany and Saudi Arabia satisfy GDPR and SFDA sovereign data mandates. |
| Acquisition of Specialist Firm | AI-native personalization engines from financial services deployments accelerate engagement metric differentiation. |
| Geographic Expansion | Localized infrastructure in India and Brazil addresses emerging data protection act fragmentation. |
| Product Launch | Hybrid cloud orchestration modules capture healthcare demand for on-premises patient record isolation. |
Study Parameters
Direct dialogue with CTOs, IT procurement officers, platform engineers, and compliance specialists grounds qualitative assessment in operational reality. Secondary validation draws from SEC filings, hyperscaler capex disclosures, EU regulatory submissions, and hospital procurement databases. Bottom-up deployment tracking and top-down market sizing triangulate volume estimates across the analysis window.
Segment-level outputs reflect modeling across deployment model, organization scale, vertical compliance burden, and regional adoption intensity. CAGRs derive from trend extrapolation anchored in documented contract values and seat-based pricing trajectories. AI feature penetration rates and sovereign hosting investment cycles inform trajectory assumptions throughout the forecast period.
Revisions become necessary when data localization mandates expand to additional geographies or when Schrems II rulings invalidate established cross-border transfer mechanisms. Forecasts reflect assumptions around regulatory enforcement intensity and cloud migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Proactive Services Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Consumer Technical Support Services Market