
 Australia Cloud OSS BSS Market | 2026-2036
Australia Cloud OSS BSS Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Cloud OSS BSS Market Insights
Australia's Critical Infrastructure Protection Act is consolidating security obligations across telecommunications infrastructure, compelling carriers to modernize operational support systems. Amdocs leverages its SaaS billing portfolio to capture telco migration budgets, while Ericsson anchors 5G orchestration deployments through localized cloud instances. Nokia competes aggressively on containerized network management platforms tailored to Australian spectrum allocations.
Cloud OSS BSS denotes the cloud-hosted software layer that automates telecom service fulfillment, assurance, and billing through virtualized network functions and microservices architectures operating at sub-50 millisecond latency thresholds. Its primary purpose is enabling real-time monetization of dynamic network slices across consumer and enterprise segments. Hybrid cloud deployment models now command the dominant margin pool as carriers retain sensitive subscriber data on private infrastructure while bursting analytics workloads to public environments. AI-driven analytics represents the fastest-expanding technology segment, though microservices underpin the architectural transition from monolithic legacy stacks.
The Australian Communications and Media Authority enforces interoperability mandates under the Telecommunications Act, while the Australian Cyber Security Centre issues binding operational technology security requirements that shape vendor accreditation pathways. Data residency obligations under the Privacy Act further constrain foreign cloud provider architectures, creating procurement complexity for multinational software vendors. Stakeholders must monitor evolving critical infrastructure designation expansions that could trigger additional compliance layers beyond current telecommunications scope.
Market Dynamics
Cloud-native billing migration is compressing deployment cycles across Australian carriers, forcing incumbent vendors to rearchitect monolithic stacks into containerized microservices or forfeit renewal contracts.
Growth Catalysts
- Critical Infrastructure Protection Act:Mandatory security hardening obligations are accelerating carrier expenditure on automated assurance platforms with real-time threat detection capabilities.
- Hyperscaler edge expansion:AWS, Azure, and Google Cloud are deploying localized zones in Sydney and Melbourne, reducing latency for subscriber-facing billing transactions below 20 milliseconds.
- 5G standalone core deployment:Network slicing architectures require dynamic policy control and charging functions that legacy on-premise systems cannot provision at scale.
Market Restraints
- Data localization mandates:Privacy Act residency requirements prevent carriers from bursting sensitive subscriber records to offshore hyperscaler regions, fragmenting cloud economics.
- Container orchestration complexity:Kubernetes-based network function virtualization demands scarce platform engineering talent that Australian carriers struggle to retain against mining and finance sectors.
- Legacy integration drag:Decades-old mediation and rating engines resist API abstraction, forcing expensive middleware layers that erode cloud migration ROI.
Strategic Opportunities
- Western Australia latency arbitrage:Mining corridor enterprises in Perth require sub-10 millisecond billing responsiveness for autonomous haulage networks, creating premium service tiers.
- AI-driven revenue assurance:Machine learning models trained on localized fraud patterns can displace rules-based detection systems that generate false positive rates above 15 percent.
- Brisbane 2032 infrastructure:Queensland government smart city investments will mandate open API billing interoperability for municipal IoT and transport networks.
Industry Challenges
- Microservices observability gaps:Distributed tracing across hundreds of ephemeral containers exceeds the monitoring capabilities of traditional network operations centers, requiring SRE organizational restructuring.
- Multi-cloud credential sprawl:Telstra and Optus deployments spanning three hyperscalers create identity management attack surfaces that the Australian Cyber Security Centre has flagged in recent advisories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Cloud OSS BSS Market |
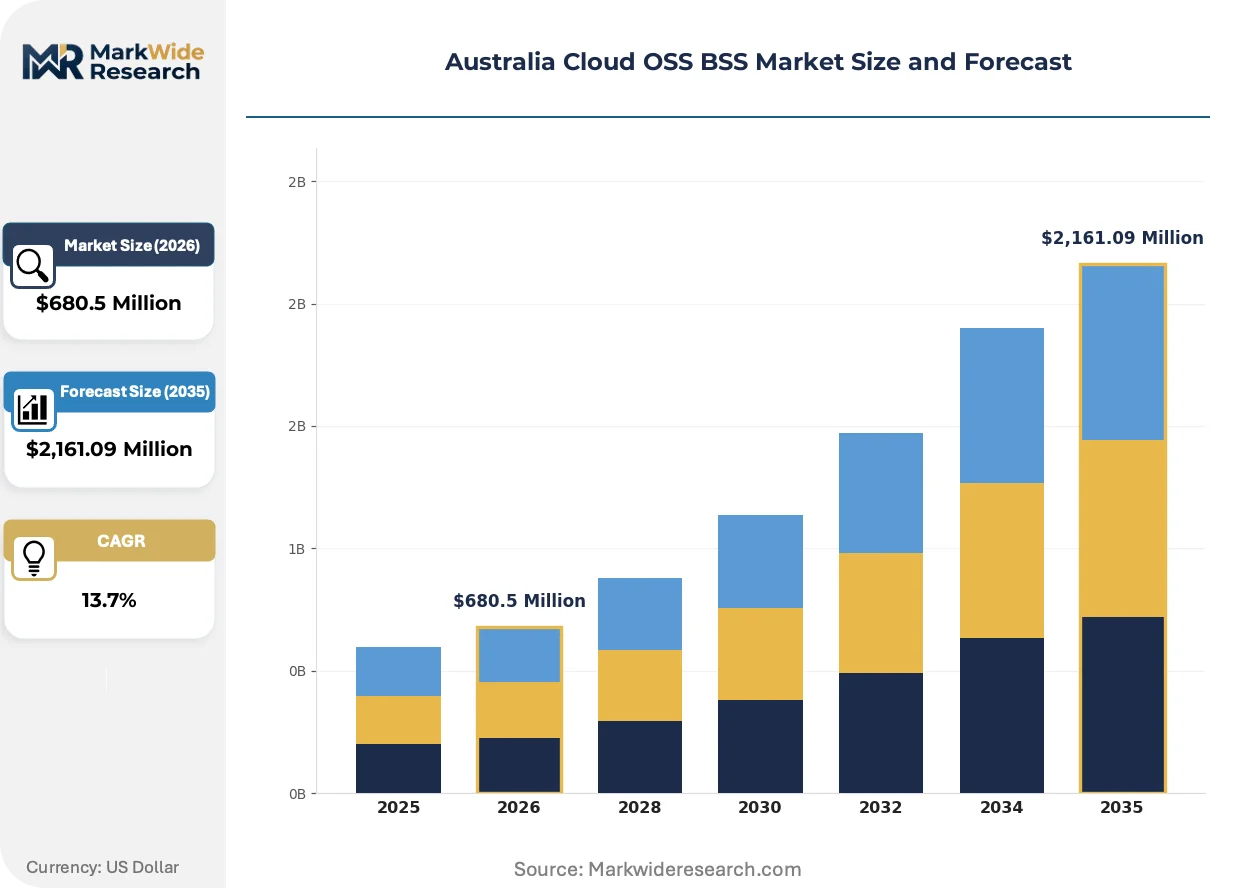
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $2,161.09 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing, Provisioning, Customer Management, Network Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Customer Type: SMEs, Enterprises, Telecom Operators, Managed Service Providers Technology: Virtualization, Microservices, API Management, AI-Driven Analytics |
| Companies Covered | Amdocs, Ericsson, Nokia, Huawei, Oracle, Netcracker, Salesforce, NEC, Tecnotree, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Cloud OSS BSS Market Trends and Innovations
Containerized charging functions are displacing virtual machine-based deployments, compressing infrastructure costs while enabling per-subscriber granularity that legacy rating engines cannot match.
Cloud-native policy control is electrifying service creation workflows. Kubernetes-orchestrated network functions enable carriers to instantiate new tariff plans within hours rather than months. Telstra's consumer division has migrated 40 percent of its prepaid subscriber base to this architecture. The technology is compressing time-to-market for promotional bundles during sporting and retail calendar peaks.
The Australian Cyber Security Centre's Essential Eight maturity model is binding on designated critical infrastructure operators. Compliance audits now mandate microsegmentation of billing databases and encrypted backup protocols that legacy tape-based disaster recovery cannot satisfy. Tier-two regional carriers in Tasmania and South Australia face accreditation timelines that delay cloud migration by 18 to 24 months relative to national operators.
Enterprise procurement teams are consolidating vendor relationships from twelve-plus point solutions to three integrated suites spanning CRM, billing, and network inventory. This concentration favors vendors with pre-certified Australian data residency architectures. Mining and logistics verticals in the Pilbara and Bowen Basin are driving the shift, demanding unified SLA dashboards that span connectivity and commercial terms.
Australia Cloud OSS BSS Market Segmentation
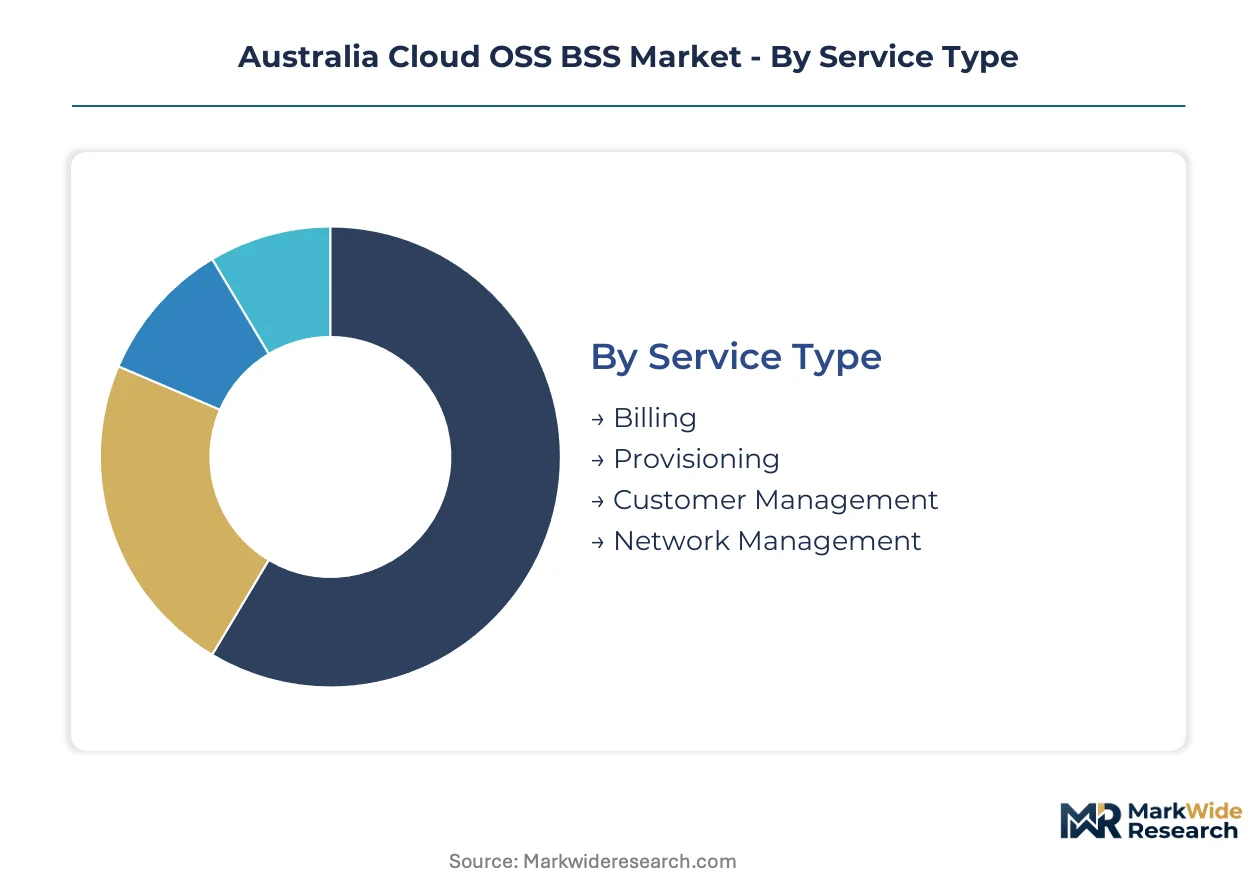
Australian carriers segment cloud OSS BSS procurement by security sensitivity, workload latency, and compliance scope. Each dimension shapes vendor accreditation requirements and deployment architecture decisions under the Critical Infrastructure Protection Act.
Service Type:
Billing buyers prioritize real-time rating engines; network management buyers emphasize automated assurance and threat detection capabilities.
- Billing:Cloud-native charging functions handle prepaid and postpaid subscriber monetization through containerized rating engines. Demand concentrates among Sydney and Melbourne-based carriers modernizing legacy mediation stacks to support 5G network slicing revenue models.
- Provisioning:Automated service fulfillment platforms instantiate network slices and enterprise connectivity within minutes rather than days. Western Australia mining corridors drive premium deployments requiring sub-10 millisecond activation for autonomous operations.
- Customer Management:Unified subscriber data platforms integrate CRM functions with billing histories.
- Network Management:Assurance platforms monitor distributed network functions across multi-cloud environments.
Volume sits with Billing; growth tilts toward Provisioning.
Deployment Model:
Cost tier separates hyperscaler-dependent architectures from sovereign infrastructure investments, with compliance mandates fragmenting procurement patterns.
- Hybrid Cloud:Carriers retain sensitive subscriber data on private infrastructure while bursting analytics workloads to AWS, Azure, or Google Cloud localized zones. Sydney and Melbourne hyperscaler edge nodes enable this architecture for Telstra and Optus consumer divisions.
- Private Cloud:Dedicated infrastructure satisfies Australian Cyber Security Centre Essential Eight requirements for designated critical infrastructure operators. Tier-two regional carriers in Tasmania and South Australia favor this model to accelerate accreditation timelines.
- Public Cloud:Shared infrastructure delivers cost efficiency for non-sensitive workloads.
- On-Premise:Legacy data center retention persists where API abstraction of decades-old mediation engines remains incomplete.
Margin concentrates in Hybrid Cloud; steepest expansion trajectory belongs to Private Cloud.
Customer Type:
Volume scale and procurement sophistication divide enterprise buyers from carrier-internal deployments and managed service intermediaries.
- Telecom Operators:National carriers drive platform standardization across consumer and enterprise divisions. Telstra's prepaid subscriber migration to cloud-native architectures exemplifies this segment's deployment velocity and vendor consolidation pressures.
- Enterprises:Mining and logistics verticals in the Pilbara and Bowen Basin demand unified SLA dashboards spanning connectivity and commercial terms, consolidating twelve-plus point solutions into three integrated suites.
- SMEs:Smaller enterprises adopt standardized SaaS billing modules through channel partners.
- Managed Service Providers:Intermediaries deliver multi-tenant OSS BSS platforms to mid-market clients lacking internal platform engineering capabilities.
Revenue pools with Telecom Operators; Enterprise deployments gain share fastest.
Technology:
Architectural maturity separates production-grade containerization from emerging AI capabilities, with API abstraction enabling the transition between generations.
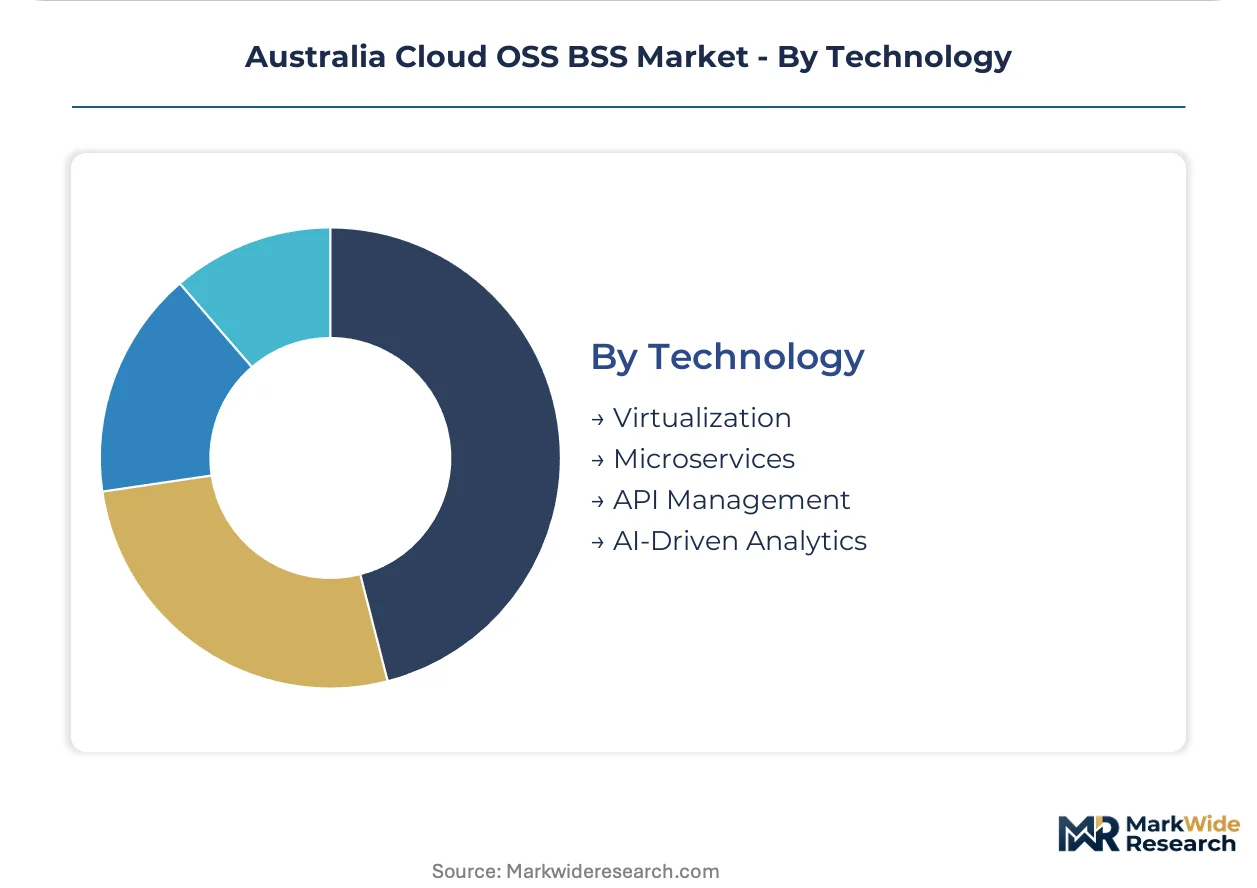
- Microservices:Kubernetes-orchestrated network functions displace monolithic legacy stacks, enabling carriers to instantiate new tariff plans within hours. Containerized charging functions compress infrastructure costs while delivering per-subscriber granularity.
- AI-Driven Analytics:Machine learning models trained on localized fraud patterns displace rules-based detection systems. Revenue assurance applications exploit this technology to reduce false positive rates below legacy 15 percent thresholds.
- Virtualization:VM-based network functions persist in transitional architectures not yet rearchitected for containers.
- API Management:Abstraction layers expose legacy mediation engines to modern orchestration platforms.
Deployment volume favors Microservices; AI-Driven Analytics climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Sydney and Melbourne hyperscaler zones, while consumption spreads across carrier headquarters, mining corridors, and government data centers. The Critical Infrastructure Protection Act creates compliance friction that fragments procurement patterns between national carriers and regional operators.
New South Wales
Sydney anchors hyperscaler edge node deployment for AWS, Azure, and Google Cloud, enabling sub-20 millisecond billing transactions for Telstra's consumer division. The Australian Cyber Security Centre enforces Essential Eight maturity requirements on designated critical infrastructure operators. Carrier-neutral data centers in Macquarie Park and Alexandria cluster software vendors serving national telco migration programs.
Victoria
Melbourne's technology precinct houses enterprise procurement teams consolidating twelve-plus point solutions into integrated OSS BSS suites. The state's critical infrastructure designation expansion proposals threaten additional compliance layers for telecommunications-adjacent sectors. Docklands and Southbank data center zones attract private cloud deployments from tier-two carriers accelerating accreditation timelines.
Queensland
Brisbane's 2032 infrastructure pipeline drives smart city billing interoperability mandates for municipal IoT networks. The Queensland government embeds open API requirements in transport and utility procurement frameworks. Gold Coast and Sunshine Coast regional carriers lag Sydney-Melbourne deployment velocity by 18 to 24 months due to thinner platform engineering talent pools.
Western Australia
Perth mining corridors generate premium demand for sub-10 millisecond billing responsiveness in autonomous haulage networks. The state's remote operations center concentration pushes edge computing investments outside traditional hyperscaler footprints. Pilbara and Bowen Basin logistics verticals demand unified SLA dashboards spanning connectivity and commercial terms.
South Australia
Adelaide's defense technology ecosystem spills into telecommunications security hardening requirements under federal critical infrastructure frameworks. The Australian Communications and Media Authority enforces interoperability mandates that shape vendor accreditation for regional operators. Limited local cloud infrastructure forces carriers into hybrid architectures with latency penalties for real-time charging functions.
Australia Cloud OSS BSS Market Competitive Landscape
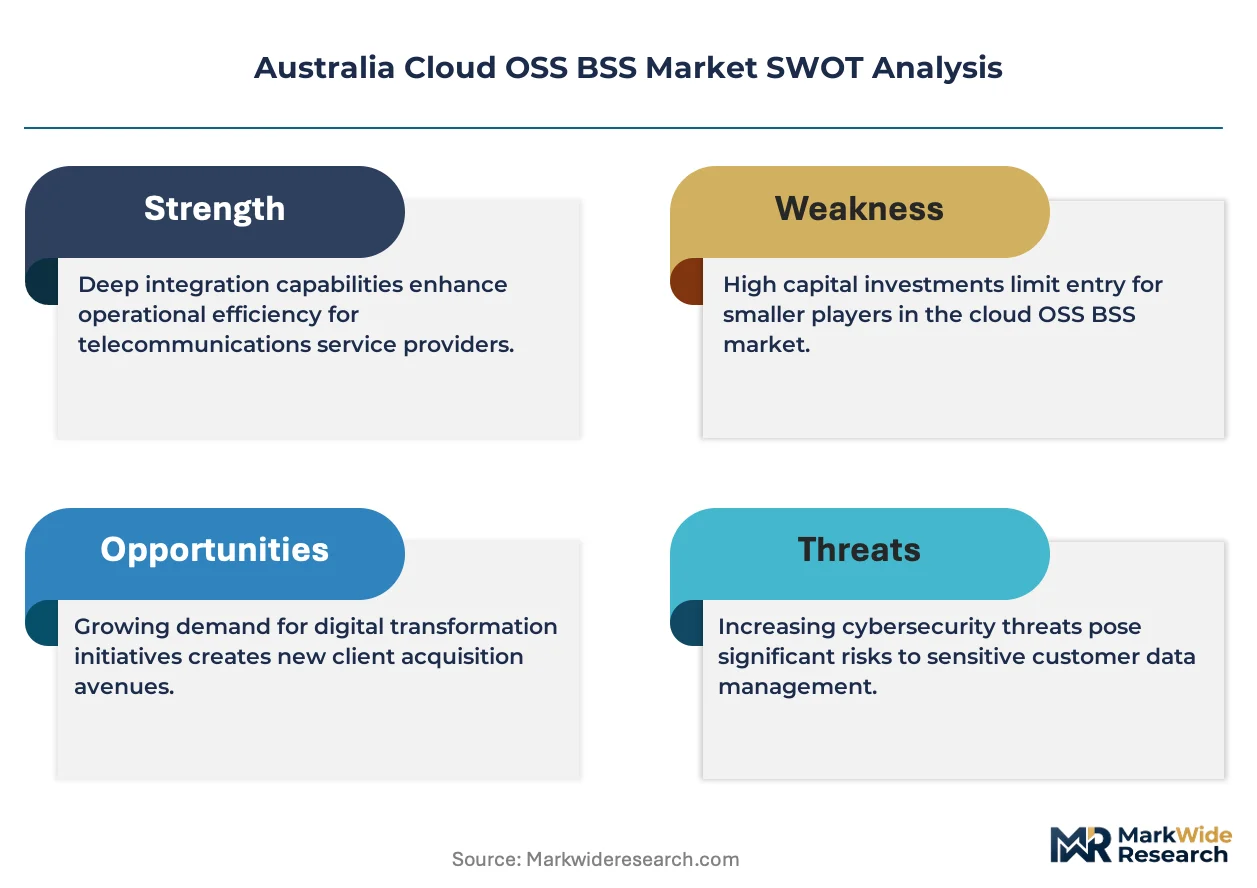
The competitive structure tilts toward integrated suite vendors with pre-certified Australian data residency architectures. Three tiers operate: multinational software conglomerates with localized cloud instances, specialized telecom BSS vendors with containerized offerings, and hyperscaler-native challengers attacking mid-market SaaS segments. Dominant competitive moves include M&A to fill portfolio gaps in AI-driven analytics and strategic partnerships with carrier-neutral data center operators to satisfy latency requirements.
Within the integrated suite tier, Amdocs and Ericsson occupy positions exemplifying divergent approaches to cloud-native billing migration. Amdocs leverages its SaaS billing portfolio to capture telco modernization budgets, while Ericsson anchors 5G orchestration deployments through localized cloud instances. Nokia sits within the specialized vendor archetype, competing on containerized network management platforms. These three represent the competitive fault lines between SaaS abstraction and network-function-specific engineering that shape procurement decisions under Australian data localization mandates.
| Leading Market Players |
|---|
| Amdocs |
| Ericsson |
| Nokia |
| Huawei |
| Oracle |
| Netcracker |
| Salesforce |
| NEC |
| Tecnotree |
| Others |
Pricing and Supply Chain Analysis
The Australian Cyber Security Centre's Essential Eight maturity model gates qualified supply access for cloud OSS BSS vendors, while simultaneously creating premium-tier pricing power for those achieving accreditation. Data residency mandates under the Privacy Act fragment procurement economics, forcing carriers to absorb sovereignty premiums for compliant architectures.
Pricing Analysis
Transaction throughput guarantees anchor pricing structures across Australian carrier contracts. Three-tier pricing separates accredited vendors with localized cloud instances from standard-tier SaaS providers and economy-tier managed service bundles. Price differentiation hinges on Australian Cyber Security Centre certification tier and guaranteed sub-20 millisecond latency SLAs. Pricing pressure stems from hyperscaler edge expansion compressing infrastructure margins, with tier-two regional carriers exhibiting highest price sensitivity due to constrained modernization budgets.
Supply Chain Analysis
Platform engineering talent scarcity in Sydney and Melbourne constrains deployment velocity for Kubernetes-orchestrated network functions. Software development draws from India, Ireland, and Poland for containerized charging function engineering, while hyperscaler infrastructure sources from Singapore, Sydney, and Melbourne edge zones. Supply chain risk centers on single-source vulnerability for specialized telco BSS engineering talent. Distribution runs through carrier-neutral data centers in Macquarie Park, Alexandria, and Docklands for localized cloud instance delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native billing migration compresses deployment cycles into a consolidation play, with the Critical Infrastructure Protection Act's accreditation timelines forcing subscale vendors toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through pre-certified Australian data residency architectures that neutralize foreign challenger expansion. Deepen backward integration into carrier-neutral data center partnerships to lock in latency-guaranteed deployment sites. Counter hyperscaler-native challengers by embedding AI-driven revenue assurance modules that exploit localized fraud pattern training data unavailable to generalist platforms.
For New Entrants and Emerging Players: Tier-two regional carriers in Tasmania and South Australia represent the most penetrable buyer archetype, given their 18-to-24-month accreditation lag behind national operators. Target Western Australia mining corridor enterprises demanding sub-10 millisecond billing responsiveness for autonomous haulage networks. Pursue a vertical-specialist go-to-market angle through unified SLA dashboards spanning connectivity and commercial terms for Pilbara logistics operators.
For Investors and Strategic Acquirers: Brisbane 2032 infrastructure commitment announcements are the leading indicator that Queensland smart city billing interoperability mandates will reshape procurement patterns. Long-term viability favors vendors with containerized network management platforms and pre-existing Australian spectrum allocation expertise. Monitor Australian Communications and Media Authority interoperability mandate expansions as the signal for accelerated vendor consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Revenue Assurance Module Launch | Machine learning models trained on localized fraud patterns displace rules-based systems generating 15 percent false positives. |
| Carrier-Neutral Data Center Partnership | Localized edge nodes in Macquarie Park and Alexandria satisfy sub-20 millisecond latency requirements for Telstra consumer billing. |
| Containerized Charging Function Migration | Kubernetes-orchestrated network functions enable tariff plan instantiation within hours rather than legacy month-long cycles. |
| Essential Eight Accreditation Investment | Pre-certified architectures accelerate procurement timelines for tier-two regional carriers facing 18-to-24-month compliance delays. |
| Western Australia Edge Infrastructure Buildout | Perth mining corridor proximity delivers sub-10 millisecond responsiveness for autonomous haulage network billing. |
Research Methodology
Independent corroboration across platform engineering directors at national carriers, procurement leads at tier-two regional operators, and integration specialists at hyperscaler partner programs underwrites the qualitative findings. Primary fieldwork encompassed network operations executives, cloud migration program managers, and Australian Cyber Security Centre accreditation consultants. Secondary validation drew from carrier capex disclosures, hyperscaler edge zone deployment announcements, and Australian Communications and Media Authority regulatory filings. Bottom-up segmentation modeling triangulated against top-down carrier IT spending benchmarks.
Rate-of-change decomposition across deployment model, service type, and customer type segments shaped the analytical framework throughout the forecast period. CAGRs were derived from carrier modernization budget trajectories, 5G standalone core deployment timelines, and critical infrastructure designation expansion scenarios. Industry-specific inputs included network slicing revenue model adoption curves and container orchestration talent availability indices.
Revisions become necessary when Australian Cyber Security Centre accreditation requirements expand beyond current telecommunications scope or hyperscaler edge zone deployment timelines shift materially. Forecasts reflect assumptions regarding carrier consolidation velocity and Privacy Act enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Sales Acceleration Technology Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Business Information Market
Digital Solutions
System Integrator Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Graph Technology Market
Digital Solutions
Change Management Software Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Supply Chain Digital Twin Market