
 UK High Performance Computing Market | 2026-2036
UK High Performance Computing Market Size, Share, and Industry Trends Forecast 2026-2036
UK High Performance Computing Market Insights
Arm-based processors are repositioning system economics in UK HPC procurement as energy efficiency becomes a primary selection criterion. Hewlett Packard Enterprise Development LP leverages its Cray architecture lineage to anchor supercomputer installations at UK research councils. NVIDIA Corporation dominates GPU-accelerated workloads through its Grace-Hopper platform deployments. Intel Corporation sustains x86 presence via its Xeon Max series with high-bandwidth memory integration.
High performance computing encompasses parallel processing systems operating at petaflop-scale throughput, typically employing thousands of interconnected nodes with InfiniBand or high-speed Ethernet fabrics for low-latency message passing. These systems execute computationally intensive simulations in climate modeling, molecular dynamics, and cryptographic analysis that standard servers cannot complete within viable timeframes. Cloud-based deployment is capturing fastest growth as UK universities and startups seek elastic capacity without capital-intensive infrastructure commitments. Supercomputers remain the margin-rich segment where sovereign contracts from UK Research and Innovation and defense agencies sustain premium pricing. On-premises installations retain dominance in classified defense simulations where data residency requirements preclude external hosting.
The UK National Quantum Strategy and UKRI funding frameworks shape procurement priorities for exascale-ready systems, while the National Cyber Security Centre mandates supply chain assurance for critical compute infrastructure. BSI standards for energy efficiency in data centers constrain system design choices and favor liquid-cooled architectures. Stakeholders must weigh sovereign capability investment against cloud flexibility as UK-EU research collaboration frameworks evolve and funding access rules shift.
Market Dynamics
Arm-based processor architectures are compressing energy-per-flop economics and forcing procurement committees to rewrite technical evaluation scorecards across UK research councils and financial services firms.
Growth Catalysts
- UK National Quantum Strategy:Sovereign compute infrastructure mandates direct public capital toward exascale-ready system procurement at UK Research and Innovation facilities.
- Real-time risk analytics:Financial services firms in the City of London deploy GPU-accelerated clusters for counterparty credit simulations and regulatory stress testing.
- Golden Triangle concentration:Research demand clusters across Oxford, Cambridge, and London create dense fiber interconnect networks that lower latency for distributed HPC workloads.
Market Restraints
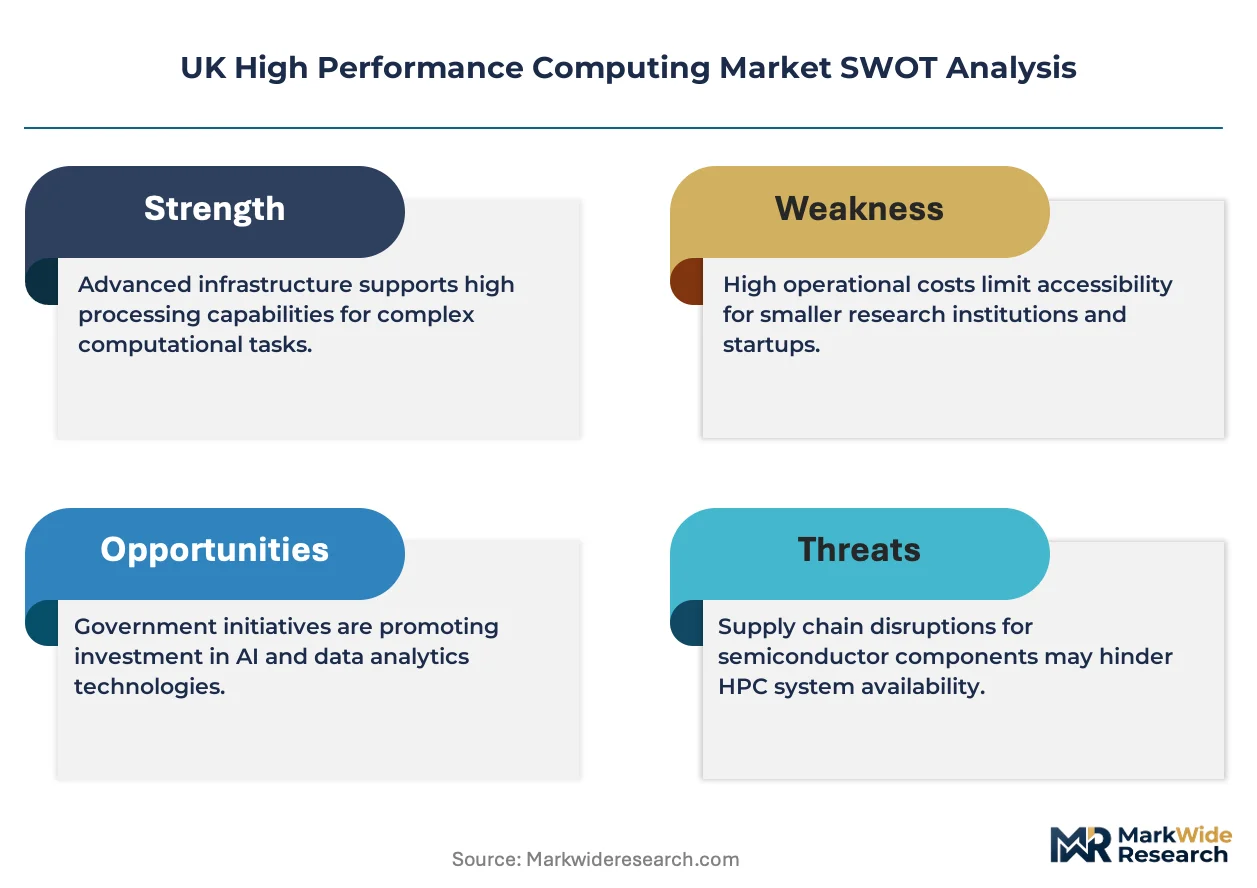
- GPU supply concentration:Advanced accelerator fabrication depends on single-source foundry capacity in East Asia, creating procurement vulnerability for UK system integrators.
- Liquid cooling infrastructure capex:BSI energy efficiency standards mandate immersion or direct-to-chip cooling retrofits that double facility preparation costs.
- Classified workload data residency:National Cyber Security Centre supply chain assurance requirements prevent defense agencies from accessing elastic cloud capacity for sensitive simulations.
Strategic Opportunities
- Cloud-based deployment elasticity:Universities and startups access petaflop-scale bursts without capital-intensive infrastructure commitments through pay-per-flop models.
- Quantum-classical hybrid integration:Convergence of quantum processing units with conventional HPC schedulers creates new algorithm development verticals for cryptography and materials science.
- Scotland and Northern England:Underpenetrated regions outside the Golden Triangle offer greenfield colocation sites with renewable energy access and lower land costs.
Industry Challenges
- Parallel programming expertise scarcity:MPI and OpenMP optimization skills concentrate among aging specialist cohorts, constraining code modernization for next-generation architectures.
- Legacy Fortran codebase integration:Decades of academic simulation software requires costly refactoring to exploit vector accelerators and heterogeneous memory hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK High Performance Computing Market |
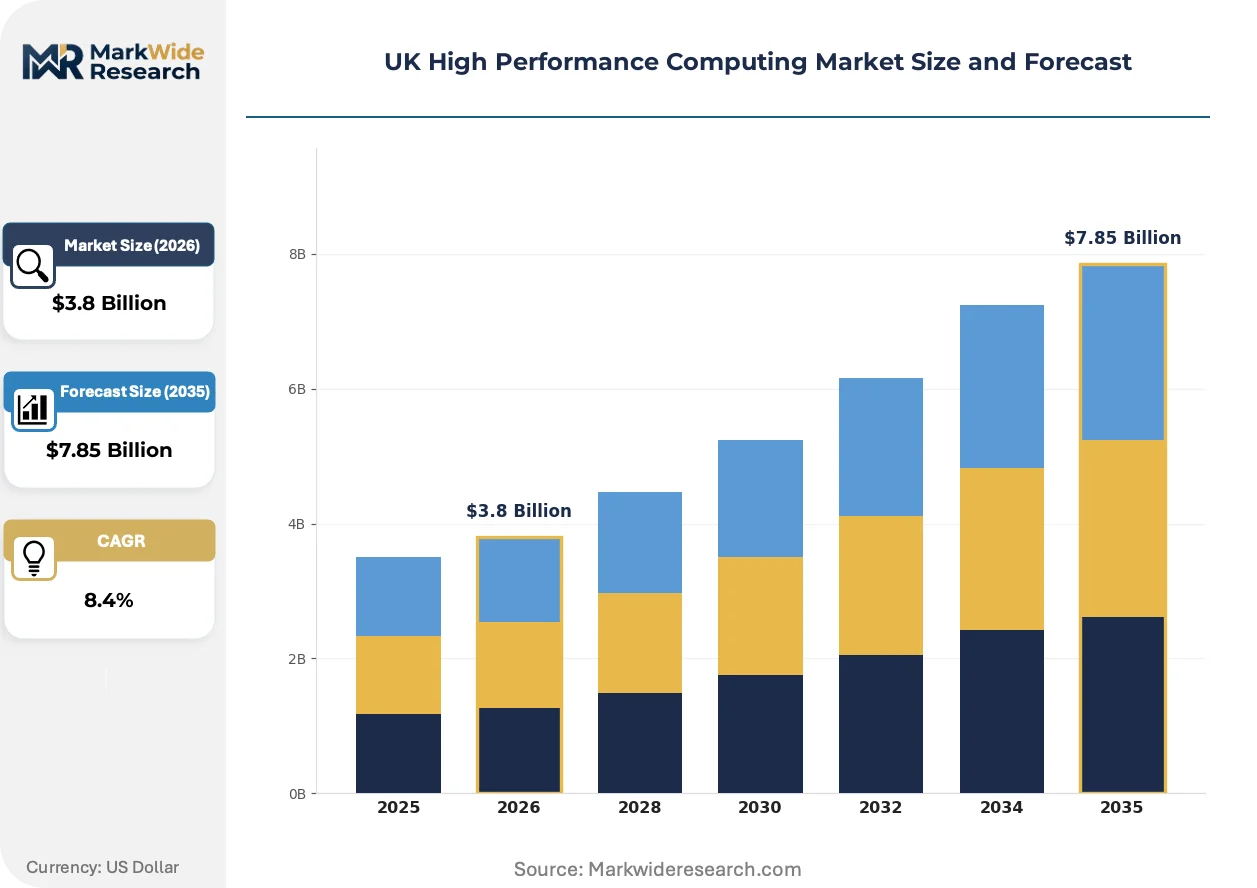
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Colocation Solution Type: Compute Clusters, Vector Processors, Grid Computing, Supercomputers Use Case: Scientific Research, Financial Modeling, Weather Forecasting, Defense Simulations End User: Academic Institutions, Financial Firms, Meteorological Agencies, Military Organizations |
| Companies Covered | Hewlett Packard Enterprise Development LP, Intel Corporation, Microsoft Corp., ATOS SE, Fujitsu Limited, NVIDIA Corporation, Dell Technologies Inc., Lenovo Group Ltd., NEC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK High Performance Computing Market Trends and Innovations
Processor heterogeneity and software-defined infrastructure are dismantling the x86-InfiniBand monoculture that dominated UK supercomputer procurement for two decades.
Arm Neoverse-based server processors are expanding into UK HPC procurement portfolios as energy efficiency becomes a primary selection criterion. Research councils at Edinburgh and Bristol evaluate Graviton and ThunderX3 deployments for throughput-oriented workloads. This architecture is expanding into segments previously reserved for Intel Xeon installations, compressing incumbent pricing power.
BSI standards for data center energy efficiency constrain system design choices and favor liquid-cooled architectures over traditional air-handling units. Facility operators must retrofit existing halls or construct purpose-built immersion tanks. Universities with aging estates face difficult capital allocation decisions between compute capacity and infrastructure overhaul.
Consumption patterns among UK startups and mid-tier engineering firms favor fractional supercomputer access through national tiered-service schemes. The Edinburgh Parallel Computing Centre and STFC Hartree Centre displace in-house cluster procurement for organizations lacking dedicated facilities management. This behavior concentrates most visible in aerospace supply chain SMEs seeking crash simulation capacity without hardware ownership.
UK High Performance Computing Market Segmentation
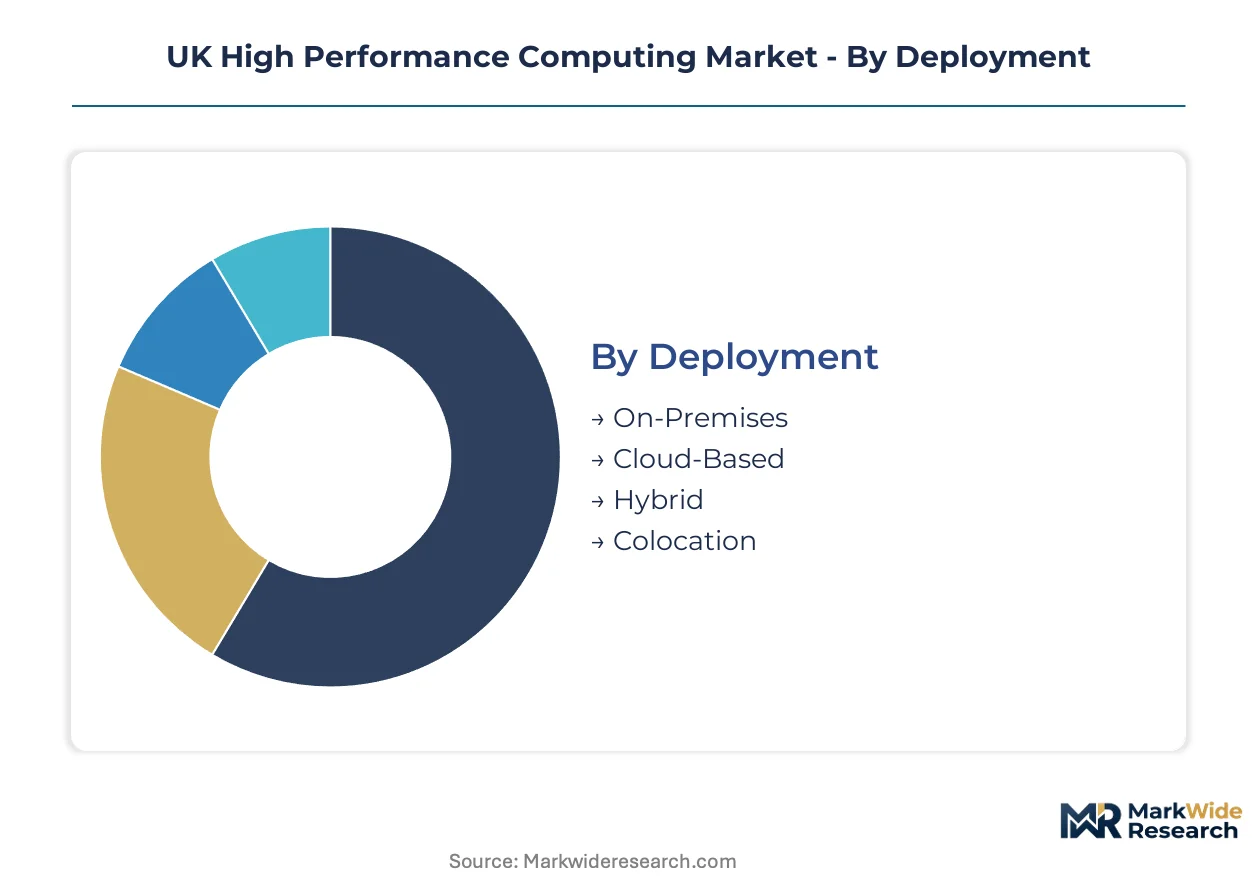
HPC procurement patterns in the UK diverge sharply across deployment models and institutional buyer types. Segmentation reveals how sovereign funding constraints, classified data requirements, and elastic compute needs reshape vendor engagement strategies across research councils and commercial enterprises.
Deployment:
Cost tier separates buyers most distinctly, with capital availability determining infrastructure control levels.
- On-Premises:Dedicated facilities with full hardware ownership and facility management responsibility. UK defense agencies and GCHQ-affiliated laboratories mandate this model under National Cyber Security Centre supply chain assurance rules that prohibit external data handling.
- Cloud-Based:Pay-per-flop access to elastic capacity without depreciation risk. Startups across London's Tech Corridor and mid-tier engineering firms access petaflop bursts through AWS, Azure, and UKRI-negotiated frameworks, displacing capital-intensive cluster procurement.
- Hybrid:Split workloads across owned infrastructure and burst capacity. University research groups baseline steady-state simulations locally while spiking to cloud for parameter sweeps during grant-funded project windows.
- Colocation:Rented rack space in third-party facilities with shared power and cooling infrastructure. Scotland's greenfield data centers attract HPC tenants seeking renewable energy sourcing and BSI-compliant liquid cooling without facility construction.
On-Premises leads volumes today; Cloud-Based is gaining share fastest.
Solution Type:
Application intensity and parallelization requirements drive architectural selection.
- Compute Clusters:Distributed x86 or Arm-based nodes with high-speed interconnects for embarrassingly parallel workloads. Financial services firms in the City deploy these for overnight risk calculations and regulatory stress testing at throughput-optimized price points.
- Vector Processors:SIMD-optimized architectures accelerating matrix operations. Weather forecasting centers at the Met Office exploit these for ensemble prediction systems requiring single-instruction multiple-data parallelism across atmospheric grid cells.
- Grid Computing:Federated resource aggregation across geographically dispersed sites. The UK National Grid Service connects university departments for opportunistic cycle harvesting from idle desktop pools.
- Supercomputers:Tightly integrated petaflop-scale systems with proprietary interconnects and accelerated nodes. UKRI's Archer2 and planned exascale procurements anchor this segment with sovereign funding sustaining premium vendor margins.
Compute Clusters dominate commercial procurement; Supercomputers capture the highest absolute spending per installation.
Use Case:
Computational complexity and data classification boundaries segment demand.
- Scientific Research:Molecular dynamics, genomics, and materials simulation across UK Research and Innovation facilities. Cambridge and Oxford laboratories drive GPU-accelerated procurement for cryo-EM structure determination and quantum chemistry.
- Financial Modeling:Counterparty credit simulations, derivative pricing, and real-time market risk. Regulatory mandates from the Prudential Regulation Authority force Tier-1 banks toward sub-millisecond latency clusters.
- Weather Forecasting:Numerical weather prediction and climate projection at kilometer-scale resolution. The Met Office's unified model codebase constrains hardware selection to vendor architectures with validated Fortran compiler optimizations.
- Defense Simulations:Nuclear stockpile stewardship, electromagnetic signatures, and cryptographic analysis. Ministry of Defence facilities at Aldermaston and Corsham operate air-gapped systems under strict data residency protocols.
Scientific Research absorbs the largest aggregate capacity; Financial Modeling shows steepest expansion trajectory.
End User:
Funding stability and procurement autonomy shape vendor relationships.
- Academic Institutions:Universities accessing HPC through national tiered-service schemes or modest departmental clusters. Edinburgh Parallel Computing Centre and STFC Hartree Centre displace in-house ownership for organizations lacking dedicated facilities staff.
- Financial Firms:Investment banks, hedge funds, and insurers with proprietary risk infrastructure. JPMorgan, Goldman Sachs, and Barclays London operations maintain on-premises GPU farms for latency-sensitive trading analytics.
- Meteorological Agencies:The Met Office as sole UK operational weather service with dedicated supercomputer procurement. Long-term government funding cycles enable multi-year vendor roadmaps and co-development partnerships.
- Military Organizations:Ministry of Defence and intelligence community with classified workload requirements. Sovereign capability mandates exclude commercial cloud for sensitive simulations, preserving on-premises vendor margins.
Academic Institutions represent the broadest user base; Financial Firms command the highest per-seat spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Triangle corridor spanning London, Oxford, and Cambridge anchors UK HPC demand through dense research institution clustering and fiber interconnect networks that minimize latency for distributed workloads.
London and the Southeast
Financial services firms in the City deploy GPU-accelerated clusters for real-time counterparty credit simulations and regulatory stress testing mandated by the Prudential Regulation Authority. The National Cyber Security Centre enforces supply chain assurance rules that constrain procurement options for defense-adjacent workloads. Imperial College London and University College London operate substantial on-premises installations for molecular dynamics and materials science research.
Scotland
The Edinburgh Parallel Computing Centre and University of Glasgow drive academic HPC consumption for climate modeling and genomics applications. UK Research and Innovation funding frameworks prioritize exascale-ready system procurement at Edinburgh facilities. Scotland's greenfield data centers attract colocation tenants seeking renewable energy sourcing and BSI-compliant liquid cooling infrastructure without facility construction costs.
North England
The STFC Hartree Centre near Manchester displaces in-house cluster procurement for aerospace supply chain SMEs seeking crash simulation capacity. Underpenetrated regions outside the Golden Triangle offer lower land costs and access to renewable generation. The University of Manchester's graphene research programs sustain demand for GPU-accelerated materials simulation workloads.
Wales
Cardiff University and Swansea University access national tiered-service schemes rather than maintaining dedicated facilities management staff. Welsh Government innovation funding supports quantum-classical hybrid integration projects aligned with the UK National Quantum Strategy. Limited on-premises infrastructure creates dependency on cloud-based deployment elasticity for research groups.
UK High Performance Computing Market Competitive Landscape
Global majors compete with regional champions across architecture specialization and sovereign contract access. The vendor base organizes around three tiers: integrated system vendors with Cray architecture lineage, chip designers controlling accelerator supply, and cloud hyperscalers offering elastic capacity. Consolidation pressure intensifies as UKRI procurement committees rewrite technical evaluation scorecards to favor energy efficiency metrics. Dominant competitive moves include strategic partnerships for quantum-classical integration and vertical integration into liquid-cooled facility design.
Within the integrated system tier, Hewlett Packard Enterprise Development LP occupies a position anchored by supercomputer installations at UK research councils, while NVIDIA Corporation exemplifies accelerator dominance through Grace-Hopper platform deployments. Intel Corporation represents the incumbent x86 architecture defending presence via Xeon Max series integration. These three entities collectively illustrate how procurement decisions increasingly hinge on energy-per-flop economics rather than raw performance benchmarks.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Development LP |
| Intel Corporation |
| Microsoft Corp. |
| ATOS SE |
| Fujitsu Limited |
| NVIDIA Corporation |
| Dell Technologies Inc. |
| Lenovo Group Ltd. |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Performance-per-watt divergence between liquid-cooled exascale systems and air-cooled commodity clusters manifests in procurement scorecards that weight energy efficiency alongside raw compute, compressing margins for legacy x86 vendors while rewarding Arm-based architectures with premium positioning in UK Research and Innovation tenders.
Pricing Analysis
Accelerator chip costs pass through directly to system integrators, with NVIDIA Grace-Hopper platforms commanding substantial premiums over CPU-only configurations. Pricing stratifies across sovereign supercomputer contracts, university tiered-service subscriptions, and pay-per-flop cloud bursts. Cost compression in mid-tier compute clusters intensifies as Arm Neoverse deployments displace Intel Xeon installations. Financial services firms exhibit lowest price sensitivity, prioritizing sub-millisecond latency over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing for advanced GPU and CPU fabrication, constraining UK system integrators' procurement flexibility. Component sourcing draws from Taiwan, South Korea, and the United States for logic chips, memory modules, and high-bandwidth interconnects. Tariff exposure on East Asian semiconductor imports threatens cost predictability for exascale system builds. Distribution runs through direct vendor relationships with UK Research and Innovation and defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in liquid-cooled facility integration and quantum-classical hybrid system architectures, where sovereign funding premiums offset infrastructure retrofit costs.
For Market Incumbents: To counter Arm-based architecture displacement, anchor x86 market share through Xeon Max series deployments with high-bandwidth memory integration at UK defense facilities. Deepen backward integration into liquid-cooled chassis design to capture facility construction budgets alongside compute hardware sales. For New Entrants and Emerging Players: Begin with colocation services in Scotland's greenfield data centers, targeting aerospace supply chain SMEs displaced from in-house cluster ownership. Capture share through renewable energy sourcing guarantees and BSI-compliant immersion cooling without upfront facility capital. For Investors and Strategic Acquirers: Consolidation pressure builds where parallel programming expertise scarcity constrains code modernization for next-generation architectures. Long-term viability favors vertically integrated specialists with captive compiler optimization teams. Watch for UK-EU research collaboration framework shifts as inflection signals for sovereign funding access.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Classical Hybrid Integration | Positions vendors for UK National Quantum Strategy procurement mandates at Edinburgh and Bristol facilities. |
| Liquid-Cooled Facility Partnership | Captures BSI energy efficiency compliance budgets alongside traditional hardware sales to university estates. |
| Arm Architecture Certification | Unlocks UKRI scorecard preferences for energy-per-watt metrics in exascale-ready system tenders. |
| National Tiered-Service Expansion | Displaces capital-intensive cluster ownership among Golden Triangle startups through pay-per-flop elasticity. |
| Defense Supply Chain Assurance | Satisfies National Cyber Security Centre mandates that exclude commercial cloud for classified simulations. |
Research Methodology
Direct dialogue with HPC procurement officers at UK Research and Innovation facilities, facilities directors at university data centers, and risk infrastructure leads at City of London financial firms grounded qualitative assessments in operational reality. Secondary validation drew from UKRI funding framework disclosures, BSI energy efficiency standard publications, National Cyber Security Centre supply chain assurance guidelines, and hyperscaler capex announcements. Bottom-up installation tracking across research councils and defense laboratories triangulated against top-down market sizing.
Installed capacity projections across the analysis window reflect segment-specific adoption curves for on-premises, cloud-based, hybrid, and colocation deployment models. Modeled dimensions encompass solution type, use case intensity, and end-user funding stability. CAGRs derive from elasticity-adjusted procurement forecasts incorporating sovereign budget cycles and cloud migration velocity. Quantum-classical integration timelines and BSI liquid cooling mandate compliance schedules informed scenario weighting.
Several conditions sit outside the modeled scope, including unforeseen UK-EU research collaboration disruptions, East Asian foundry capacity constraints, and abrupt shifts in Prudential Regulation Authority risk calculation mandates. Forecasts reflect documented assumptions about funding continuity and technology transition rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Social Computing Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
System Integrator Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Business Information Market