
 Crop Management Software Market | 2026-2036
Crop Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Management Software Market Insights
EU Green Deal compliance is broadening the cost-of-entry calculus for crop management software vendors serving European farms. Deere & Company leverages its integrated precision agriculture hardware-software stack to anchor premium positioning in North American row-crop markets. Trimble Inc. competes through specialized GNSS-guided field operations technology that sustains pricing power in geospatial-dependent applications. AGCO Corporation navigates fragmented farm sizes across Eastern Europe by extending modular cloud-based tools that reduce upfront capital barriers.
Crop management software encompasses digital platforms that collect, process, and act upon agronomic data through sensors, satellite imagery, and algorithmic analytics to optimize planting, irrigation, fertilization, and harvest decisions. These systems typically integrate field-level telemetry with weather APIs and enterprise resource planning modules to transform raw agricultural data into executable farm operations. Precision Agriculture dominates current deployment value due to sensor hardware bundling and subscription lock-in effects, while Cloud-Based delivery represents the fastest-expanding deployment mode as rural broadband infrastructure improves. Analytics Tools command concentrated margin pools because farmers pay premium rates for yield-forecasting algorithms that demonstrate direct return on input expenditures.
EPA water-quality regulations in the United States and REACH chemical-tracking obligations in Europe are forcing software vendors to build nutrient-runoff monitoring and pesticide-application logging into core platform architecture. India's FSSAI traceability mandates and the country's PLI scheme for agricultural technology are reshaping product roadmaps for vendors targeting South Asian export-oriented farming cooperatives. Stakeholders must monitor how carbon-credit verification standards crystallize into mandatory data formats, as this will determine which platform ecosystems capture the compliance-layer value in agricultural software.
Market Dynamics
Precision agriculture platforms are consolidating farm-level data streams into unified command layers, compressing decision cycles from seasonal to real-time intervals as sensor density and rural broadband penetration accelerate simultaneously.
Growth Catalysts
- EU Green Deal compliance mandates:The Farm to Fork strategy tightens sustainability reporting obligations, forcing European agricultural producers to adopt digital traceability systems for nutrient management and carbon accounting.
- Brazilian agribusiness scaling:Large-scale farming cooperatives across Mato Grosso and the Cerrado belt are deploying satellite-guided variable-rate application systems to optimize input costs on soybean and corn operations.
- Cloud-based delivery expansion:Modular SaaS architectures reduce upfront capital barriers for mid-sized farms, accelerating subscription adoption as rural fiber and 5G fixed-wireless infrastructure reaches previously underserved agricultural counties.
Market Restraints
- Hardware-sensor cost concentration:Soil moisture probes, multispectral cameras, and RTK-GNSS receivers remain concentrated among specialty semiconductor foundries, creating input cost volatility for platform vendors bundling physical telemetry layers.
- Interoperability fragmentation:Proprietary data formats from Deere, Trimble, and AGCO equipment lock agronomic datasets into siloed ecosystems, forcing farms to maintain redundant software licenses or accept incomplete field analytics.
- Legacy system integration friction:Decades-old farm management information systems lack API-ready architectures, requiring expensive middleware development to connect modern cloud platforms with on-premise accounting and inventory databases.
Strategic Opportunities
- India FSSAI traceability mandates:Export-oriented farming cooperatives must digitize pesticide application logs and harvest batch records, creating demand for compliance-integrated crop management platforms serving South Asian contract farming arrangements.
- Carbon-credit verification standardization:Emerging protocols for agricultural carbon sequestration measurement reward farms with verified digital field records, positioning software vendors to capture compliance-layer value through automated data formatting for credit registries.
- Drone-satellite imagery convergence:Fusion of sub-meter satellite constellations with autonomous UAV scouting missions enables daily field monitoring at costs below manned aerial surveys, opening premium service tiers for high-value specialty crop operations.
Industry Challenges
- Agronomic data science talent scarcity:Platforms require interdisciplinary teams combining machine learning engineering with crop physiology expertise, but university programs produce insufficient graduates fluent in both computational and biological domains.
- Cybersecurity certification timelines:Farm operations software handling financial transactions and food safety records must achieve SOC 2 and ISO 27001 attestations, extending sales cycles by six to twelve months for vendors without existing enterprise security infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Management Software Market |
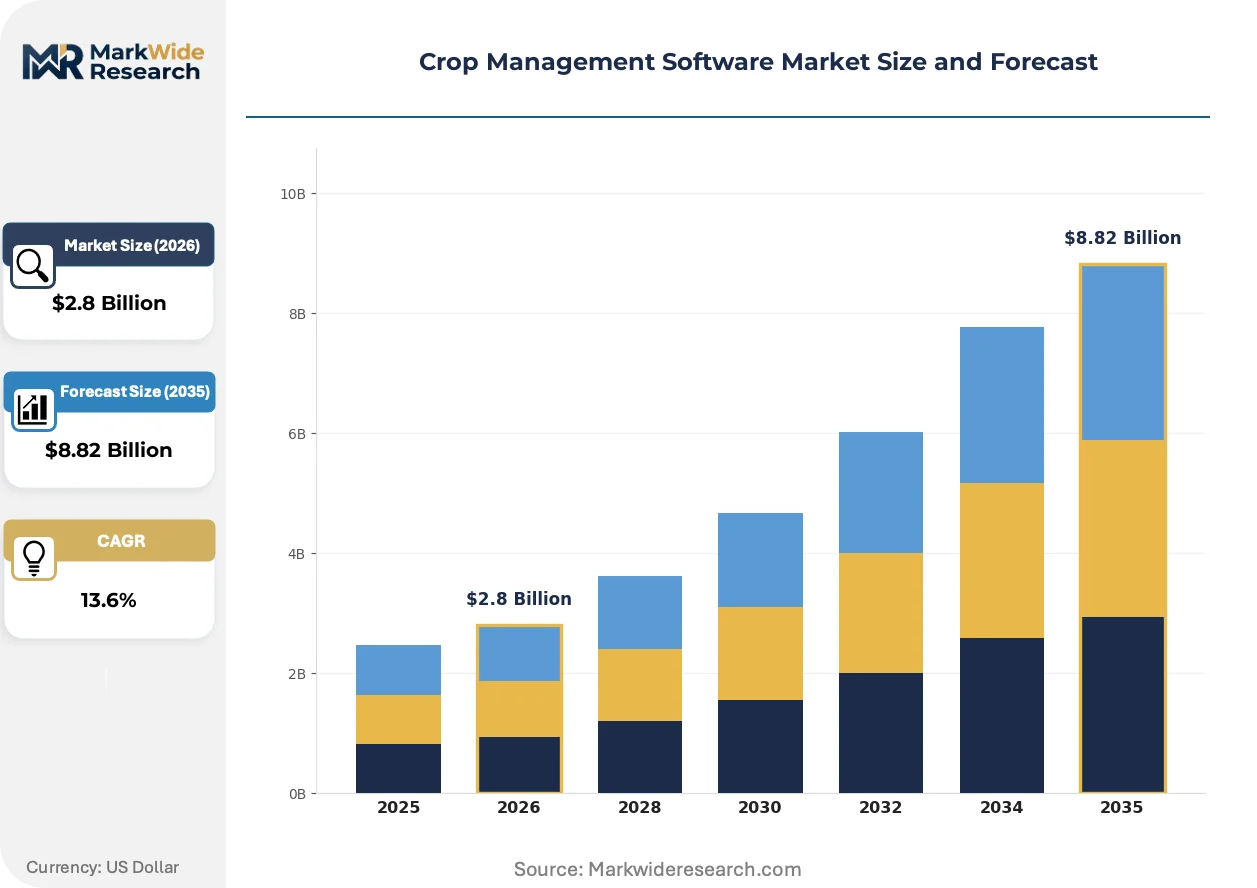
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Farm Management, Precision Agriculture, Crop Monitoring, Livestock Management End Use Industry: Agriculture, Horticulture, Greenhouse, Forestry Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Application Feature: Analytics Tools, Data Integration, Weather Forecasting, Financial Management |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Bayer AG, CNH Industrial N.V., BASF SE, Farmers Edge Inc., Agrivi, AgriERP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Management Software Market Trends and Innovations
Algorithmic decision support is migrating from retrospective yield analysis to predictive intervention systems, compressing the latency between data capture and executable field recommendations as edge computing deployments reach rural telemetry networks.
Multispectral and thermal imaging sensors mounted on autonomous ground robots and aerial platforms are integrating directly with irrigation valve controllers and variable-rate spreaders, creating closed-loop systems that adjust water and nutrient delivery without human intervention. Large-scale corn and soybean operations in Iowa and Illinois are deploying these integrated sensor-actuator chains across ten-thousand-acre footprints, reducing input waste while maintaining yield targets. The structural consequence is a compression of agronomic service margins as hardware-software bundles displace independent crop consulting relationships.
EPA water-quality regulations under the Clean Water Act are mandating documented nutrient management plans for concentrated animal feeding operations and adjacent row-crop producers, forcing software vendors to embed runoff modeling and buffer-zone calculation modules into core platform architecture. Vendors serving the Chesapeake Bay watershed and Upper Mississippi River basin face the most acute compliance pressure, with state environmental agencies rejecting paper-based reporting in favor of machine-readable XML submissions directly from certified farm management systems.
Consolidated grain elevators and food processors are unbundling after-sales agronomic support from input supply contracts, instead procuring digital advisory services through competitive RFP processes that prioritize API interoperability with their own enterprise ERP systems. This procurement evolution displaces the traditional bundled model where seed-chemical distributors provided free or subsidized software as a loyalty mechanism. The shift is most visible in the US Corn Belt, where cooperative grain handlers now require real-time yield forecast feeds to optimize logistics scheduling and storage capacity planning.
Crop Management Software Market Segmentation
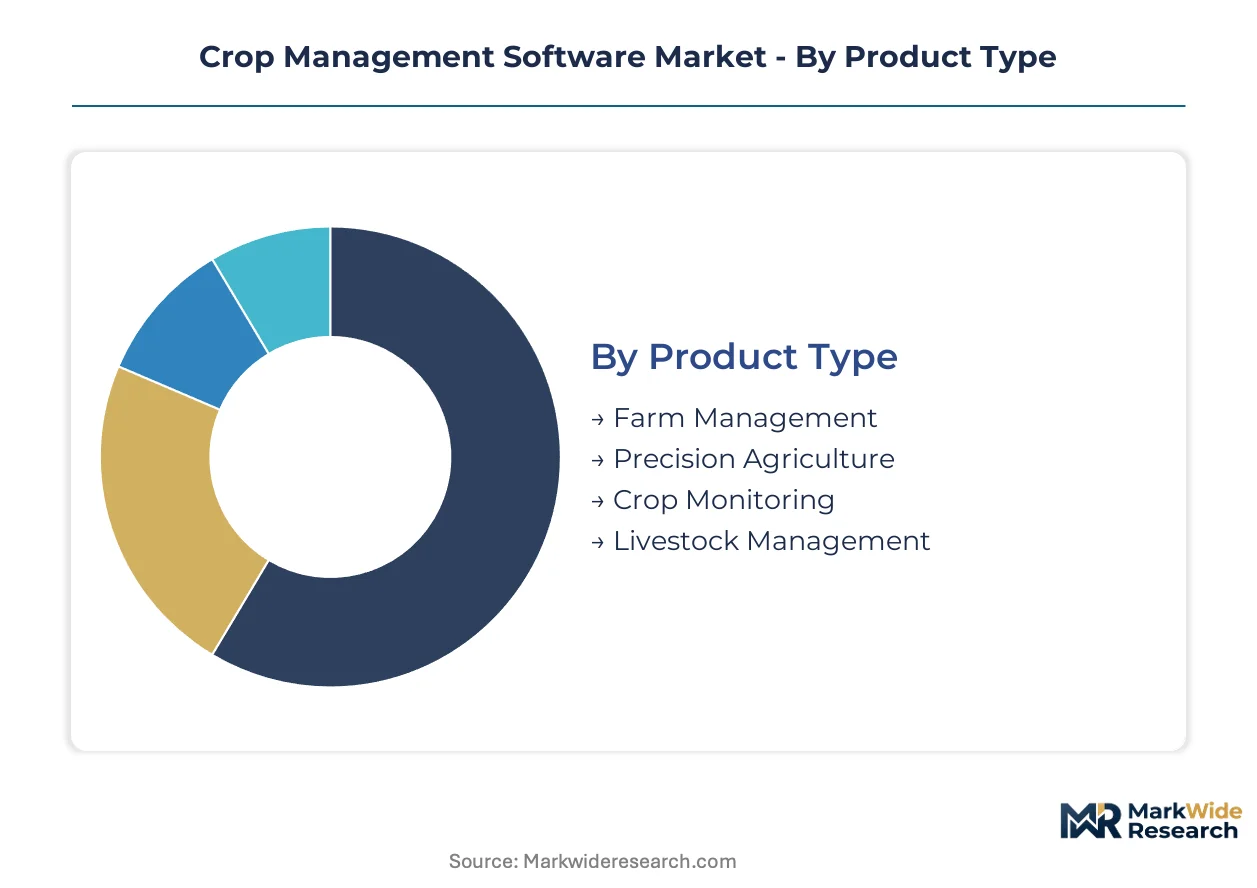
Segmentation in crop management software reflects divergent farm-scale economics and regulatory exposure. Large commercial operations prioritize precision agriculture bundles with sensor hardware lock-in, while smaller holdings favor modular cloud deployments that minimize capital commitment. Regulatory mandates in the EU, Brazil, and India are reshaping feature priorities across all product tiers.
Product Type:
Standardization dominates farm management platforms, whereas precision agriculture demands extensive customization around crop-specific sensor configurations and variable-rate application protocols.
- Farm Management:Core platforms integrating accounting, inventory, and labor scheduling for diversified operations. Demand concentrates among mid-sized Midwestern US grain farms consolidating legacy paper records ahead of EPA nutrient management deadlines.
- Precision Agriculture:Sensor-integrated systems combining RTK-GNSS guidance, multispectral imaging, and algorithmic input optimization. Brazilian soybean cooperatives in Mato Grosso are deploying these systems across twenty-thousand-hectare blocks to compress fertilizer application windows during narrow weather intervals.
- Crop Monitoring:Satellite and drone-based field surveillance platforms with pest pressure and irrigation stress alerts.
- Livestock Management:Herd health tracking, feed optimization, and regulatory compliance modules for integrated crop-livestock operations.
Most installed capacity flows through Farm Management. Expansion is steepest in Precision Agriculture.
End Use Industry:
Volume concentration sits with broadacre commodity production, while margin capture favors controlled-environment horticulture where input precision directly determines per-unit profitability.
- Agriculture:Row-crop and small-grain operations managing field-scale variability through telemetry networks. Iowa and Illinois corn producers are retrofitting ten-year-old equipment with aftermarket CAN-bus data loggers to meet cooperative elevator requirements for real-time yield forecasting.
- Horticulture:Specialty crop operations optimizing irrigation and nutrient delivery for high-value produce. California Central Valley almond and pistachio growers are deploying soil moisture sensor arrays with automated valve control to comply with Sustainable Groundwater Management Act pumping restrictions.
- Greenhouse:Climate-controlled cultivation environments with integrated HVAC, lighting, and fertigation automation.
- Forestry:Plantation management, harvest logistics, and carbon sequestration monitoring for timber investment vehicles.
Agriculture carries the heaviest deployment base. Horticulture is gaining share fastest as water stress intensifies across major growing regions.
Deployment:
Cloud architectures are displacing on-premise installations as rural broadband penetration reaches previously underserved agricultural counties, though hybrid models persist where intermittent connectivity threatens critical field operations.
- Cloud-Based:SaaS platforms with browser and mobile access, automatic updates, and API-ready integration. Eastern European contract farming operations are adopting these systems to satisfy EU Common Agricultural Policy digital reporting requirements without dedicated IT staffing.
- On-Premise:Locally installed software with full data sovereignty and offline functionality. Australian broadacre wheatbelt stations with unreliable cellular coverage maintain these installations for core record-keeping during planting and harvest windows.
- Hybrid:Synchronized local and cloud storage with conflict-resolution protocols for intermittent connectivity.
- Mobile Application:Smartphone-native field data capture with offline form submission and GPS tagging.
Cloud-Based deployment hosts the majority of new subscriptions. Mobile Application shows the steepest expansion trajectory among specialty crop scouting services.
Feature:
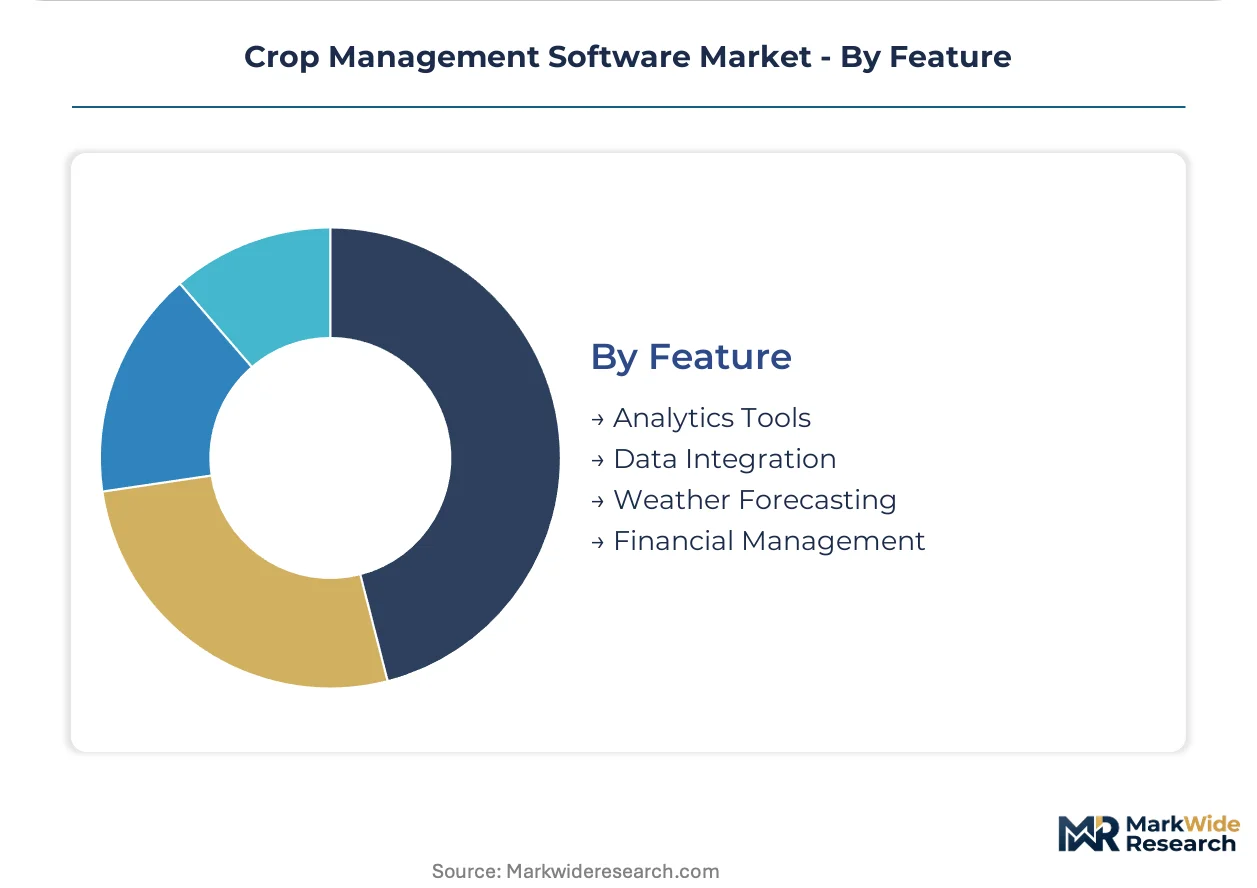
Margin pools concentrate in analytics capabilities that demonstrate direct return on input expenditure, while weather forecasting and financial modules face commoditization from free alternative providers.
- Analytics Tools:Machine learning models for yield prediction, input optimization, and prescription map generation. Large-scale Ukrainian grain exporters are paying premium licensing fees for satellite-derived yield forecasting algorithms that inform forward-contracting decisions six weeks ahead of harvest.
- Data Integration:API connectivity between farm management platforms, equipment telematics, and enterprise ERP systems. US cooperative grain elevators now require these integrations for real-time inventory visibility and logistics scheduling.
- Weather Forecasting:Hyperlocal precipitation and temperature modeling with spray-condition windows and frost alerts.
- Financial Management:Crop budgeting, cash-flow projection, and loan covenant tracking modules.
Analytics Tools command the deepest customer willingness-to-pay. Data Integration is expanding most quickly as procurement digitization accelerates across agricultural value chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture talent clusters concentrate in the US Corn Belt, Brazil's Cerrado frontier, and India's agritech hubs, anchoring software development centers close to large-scale farming operations demanding real-time telemetry integration.
United States
Iowa and Illinois corn-soybean producers drive demand for sensor-integrated variable-rate systems that compress fertilizer application windows. EPA water-quality regulations under the Clean Water Act mandate documented nutrient management plans with machine-readable XML submissions. Chicago-based cooperative grain elevators now require real-time yield forecast feeds to optimize logistics scheduling and storage capacity.
Brazil
Mato Grosso soybean cooperatives deploy satellite-guided input optimization across twenty-thousand-hectare blocks to manage narrow weather intervals. ANVISA traceability protocols and export-oriented phytosanitary requirements force digitization of pesticide application logs. The Cerrado farming belt surrounding Rondonópolis anchors Brazil's fastest-growing precision agriculture software adoption corridor.
Germany
Bavarian and Lower Saxony arable farms face EU Green Deal Farm to Fork sustainability reporting obligations that tighten nutrient management and carbon accounting requirements. REACH chemical-tracking obligations force software vendors to build pesticide-application logging into core platform architecture. The Munich-Stuttgart corridor hosts Europe's densest concentration of agronomic data science and machine learning engineering talent.
India
Punjab and Haryana export-oriented farming cooperatives digitize harvest batch records to satisfy FSSAI traceability mandates for European and Middle Eastern buyers. The national PLI scheme for agricultural technology subsidizes sensor hardware procurement for contract farming arrangements. Bangalore's agritech cluster delivers cloud-based platforms that reduce upfront capital barriers for mid-sized holdings.
Australia
Western Australian wheatbelt stations with unreliable cellular coverage maintain hybrid deployment models for core record-keeping during planting and harvest windows. The country's national agricultural regulator enforces biosecurity documentation standards that favor digitized field records. Perth anchors software development serving broadacre operations across the southwestern grain production zone.
Crop Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Incumbent agricultural machinery manufacturers leverage hardware-software bundling to sustain premium positioning, while modular SaaS vendors capture mid-market share through reduced capital barriers. Strategic archetypes include integrated equipment-software stacks, geospatial-specialized platforms, and cloud-native compliance tools. Competitive intensity concentrates on API interoperability capabilities and carbon-credit verification module development.
Among integrated equipment manufacturers, Deere & Company and AGCO Corporation exemplify the hardware-anchored archetype with bundled precision agriculture ecosystems. Trimble Inc. occupies a specialized position within geospatial-dependent applications. Cloud-native specialists including Farmers Edge Inc. and Agrivi represent the modular SaaS archetype targeting mid-sized farms with subscription-based delivery models that minimize upfront infrastructure investment.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Bayer AG |
| CNH Industrial N.V. |
| BASF SE |
| Farmers Edge Inc. |
| Agrivi |
| AgriERP |
| Others |
Pricing and Supply Chain Analysis
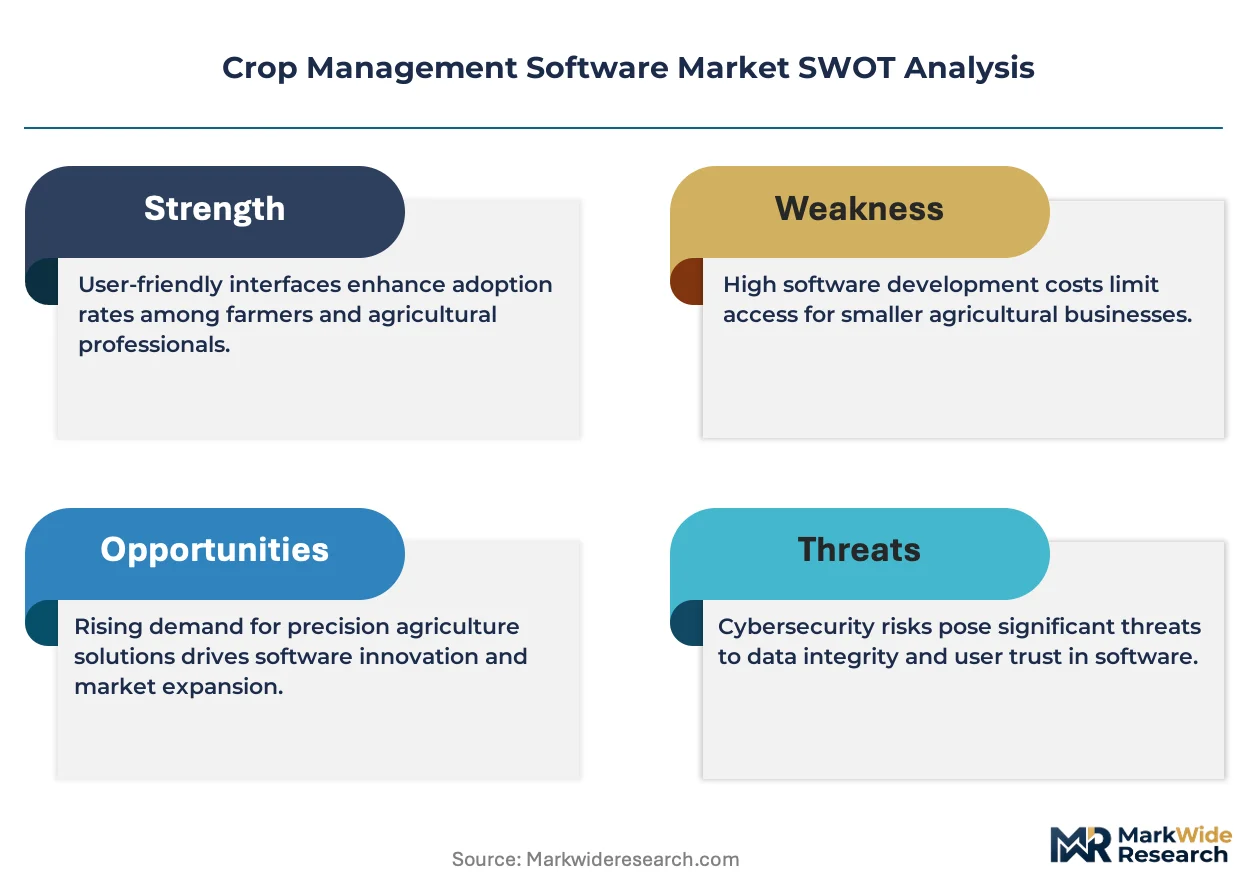
Hardware-software bundling by integrated equipment manufacturers anchors premium pricing power in North American and Brazilian row-crop markets while compressing margins for standalone software vendors competing on subscription economics. This vertical integration choice concentrates supply leverage among Deere, AGCO, and CNH Industrial, forcing modular SaaS providers to compete through API interoperability rather than sensor hardware lock-in.
Pricing Analysis
Bundled precision agriculture packages versus unbundled cloud subscriptions splits the market into two distinct pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects hardware sensor density and algorithmic sophistication tiers, with premium bundles commanding rates justified by RTK-GNSS guidance and multispectral imaging integration. Cost compression in the mid-market tier is intensifying because Brazilian and Indian cooperatives demand modular deployments without upfront capital barriers. Smallholder operations in Eastern Europe exhibit the highest price sensitivity, while large-scale Mato Grosso soybean producers demonstrate lowest sensitivity due to input cost savings from variable-rate application systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated farming cooperatives, while independent software vendors distribute through agricultural retailers and digital marketplaces. Semiconductor fabrication for soil moisture probes and multispectral cameras concentrates in Taiwan, South Korea, and the United States, creating single-source vulnerability for RTK-GNSS receiver chipsets. Cloud infrastructure and data center capacity draws from Ireland, Germany, and Singapore to serve regional latency requirements for real-time field telemetry. Tariff exposure on Chinese-manufactured sensor assemblies threatens margin stability for hardware-bundled platform vendors serving price-sensitive mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed India's PLI-subsidized sensor procurement economics by a factor that rewards platform localization in South Asian agritech clusters.
For Market Incumbents: Lock in hardware-software ecosystem loyalty through proprietary data format architectures that increase switching costs for large-scale farming cooperatives. Deepen backward integration into specialty semiconductor sourcing for RTK-GNSS and multispectral components to defend against input cost volatility from Taiwan and South Korean foundry concentration. Prioritize carbon-credit verification module development ahead of mandatory data format crystallization in EU and North American regulatory frameworks. For New Entrants and Emerging Players: The mid-market price-point gap between Deere's premium precision bundles and basic farm management SaaS creates white-space opportunity for API-native platforms targeting Eastern European contract farming operations. India's FSSAI traceability mandate compliance layer offers the most penetrable segment for cloud-native entrants with modular pesticide-logging architectures. Pursue cooperative grain elevator procurement channels through real-time yield forecast integration that displaces legacy seed-chemical distributor bundled software relationships. For Investors and Strategic Acquirers: Roll-up economics work for geospatial analytics specialists because fragmented agronomic data science talent scarcity prevents organic capability building at scale. Platform consolidation around carbon-credit verification and API interoperability capabilities offers viable five-to-ten-year value creation trajectories. Monitor EPA water-quality regulation enforcement intensity in the Chesapeake Bay watershed and Upper Mississippi River basin as the inflection indicator for compliance-layer software valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Credit Verification Module Development | Captures compliance-layer value as EU and North American regulators crystallize mandatory agricultural carbon sequestration data formats. |
| API Interoperability Certification Investment | Secures procurement eligibility with cooperative grain elevators requiring real-time ERP integration for logistics optimization. |
| Backward Integration into Sensor Hardware | Reduces input cost volatility from Taiwan and South Korean semiconductor foundry concentration for RTK-GNSS components. |
| Geographic Expansion into Indian Agritech Clusters | Leverages PLI scheme subsidies and FSSAI traceability mandates to anchor South Asian market presence. |
| Strategic Partnership with Satellite Constellation Operators | Enables sub-meter imagery fusion with drone scouting missions for daily field monitoring below manned aerial survey costs. |
Research Methodology
Bottom-up farm-scale deployment modeling reconciled against top-down precision agriculture platform vendor tracking forms the analytical core of this study. Primary interviews with agronomic data scientists, cooperative grain elevator procurement officers, agricultural equipment OEM platform engineers, and Indian contract farming cooperative managers combined with secondary validation against SEC 10-K filings, EU Common Agricultural Policy implementation reports, ANVISA traceability protocol documentation, and Brazilian agribusiness trade association deployment surveys. Triangulation between bottom-up sensor installation counts and top-down software licensing revenue estimates ensures segmentation integrity.
Input-output matrix framing connects farm-scale economics variables to platform adoption rates across deployment model, operation size, crop type, integration complexity, and regional regulatory cluster dimensions. CAGRs derive from segmented growth rate reconciliation against macro-level agricultural digitization spending patterns throughout the forecast period. Industry-specific forecast inputs include rural broadband penetration trajectories, EPA water-quality regulation enforcement timelines, and carbon-credit verification standardization progress.
Caveats apply where semiconductor supply constraints, cybersecurity certification timeline extensions, or abrupt regulatory format changes could materially shift the outlook. Forecasts reflect documented assumptions regarding sensor hardware cost curves and cooperative procurement digitization velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Pipeline Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Smart Signage Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Decision Management Applications Market