
 UK Video Analytics Market | 2026-2036
UK Video Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
UK Video Analytics Market Analytics
AI-literate video surveillance engineers is bifurcating the competitive landscape into vendors that can deliver edge-native analytics and legacy integrators struggling with cloud migration. Axis Communications leverages its in-house chipset design to sustain low-latency processing at the camera level. Synectics Plc anchors its position through deep relationships with UK critical infrastructure operators. Bosch Security Systems differentiates via rigorous compliance with British standards for data protection by design.
Video analytics encompasses software algorithms, embedded hardware accelerators, and integrated systems that process live or recorded video streams to detect objects, classify behaviors, and trigger automated responses without continuous human monitoring. These systems typically operate at frame rates of 25-30 fps with latency budgets under 500 milliseconds for real-time alerting in security-critical deployments. Software solutions dominate current revenue as organizations prioritize subscription-based AI model updates over capital-intensive hardware refresh cycles. Edge computing architectures are expanding fastest among technology categories, driven by UK enterprises seeking to minimize bandwidth costs and keep sensitive footage within local jurisdictional boundaries.
The UK Information Commissioner's Office enforces GDPR restrictions on automated facial recognition, compelling vendors to deploy privacy-by-default configurations and explicit consent workflows. The Surveillance Camera Commissioner oversees compliance with the Protection of Freedoms Act 2012, mandating published impact assessments for public space deployments. Stakeholders must weigh the operational gains of deep learning-powered behavior analysis against emerging regulatory constraints on biometric inference and predictive policing algorithms.
Market Dynamics
Edge-native processing architectures are fragmenting procurement patterns across British security infrastructure, as police forces and transport operators bypass traditional centralized systems in favor of camera-level inference.
Growth Catalysts
- Surveillance Camera Code of Practice:Mandatory impact assessments for public space deployments are accelerating replacement cycles among compliant authorities.
- Transport command centers:Manchester's integrated traffic management systems demonstrate operational ROI from real-time congestion analytics.
- GDPR-compliant edge processing:On-device biometric inference eliminates cross-border data transfer risks for sensitive deployments.
Market Restraints
- Silicon supply concentration:GPU and NPU accelerator sourcing remains vulnerable to East Asian foundry bottlenecks.
- Biometric inference restrictions:ICO enforcement of GDPR Article 9 limitations constrains facial recognition deployment scope.
- Legacy coaxial infrastructure:Analog-to-IP migration costs deter refresh cycles in budget-constrained municipal contracts.
Strategic Opportunities
- West Midlands manufacturing clusters:Automotive quality-control applications remain underpenetrated for defect-detection analytics.
- AI Act alignment services:Compliance consulting for EU-facing British exporters creates adjacent revenue streams.
- 5G-integrated edge nodes:Convergence of private cellular networks with video analytics enables mobile deployment scenarios.
Industry Challenges
- Embedded AI engineering scarcity:Camera firmware optimization for ARM-based accelerators requires specialized talent pools.
- Multi-vendor integration complexity:ONVIF Profile M interoperability gaps force custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Video Analytics Market |
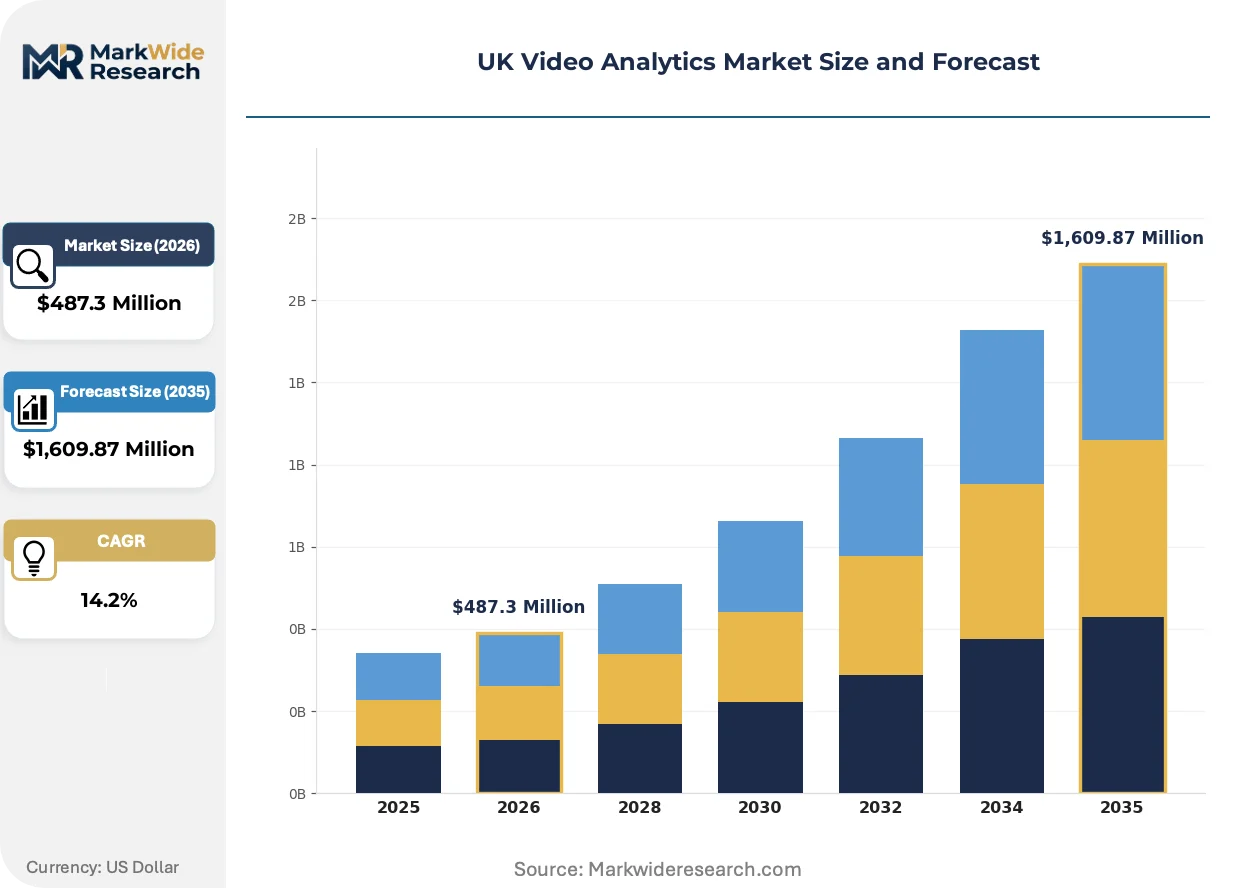
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Solutions, Integrated Systems, Cloud-Based Solutions End User: Retail, Transportation, Banking, Healthcare Application: Surveillance, Traffic Management, People Counting, Behavior Analysis Technology: Machine Learning, Deep Learning, Video Content Analysis, Edge Computing |
| Companies Covered | Axis Communications AB, Synectics Plc, Milestone Systems A/S, Bosch Security Systems, Genetec Inc., IBM Corporation, Honeywell International Inc., Cisco Systems, Inc., Verkada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Video Analytics Market Evolving Landscape
Generative AI training techniques are migrating into video analytics pipelines, compressing model development cycles and expanding detectable behavior categories beyond rule-based systems.
Transformer-based architectures for temporal event understanding are displacing recurrent neural networks in behavior classification tasks. British police pilot programs in Greater London are validating these models for loitering and crowd anomaly detection. The shift is compressing vendor differentiation around proprietary training datasets rather than algorithmic foundations.
The UK Information Commissioner's Office guidance on automated decision-making is tightening consent workflows for biometric deployments. Infrastructure operators must now document lawful basis for each processing purpose. Transport authorities in Manchester and Birmingham are responding by segmenting analytics pipelines between identifiable and anonymized processing tracks.
Subscription-based AI model updates are displacing perpetual licensing in procurement negotiations. Security integrators now bundle continuous retraining services rather than delivering static software versions. This pattern concentrates most visibly in Greater London's smart city frameworks, where multi-year service contracts dominate capital expenditure approvals.
UK Video Analytics Market Segmentation
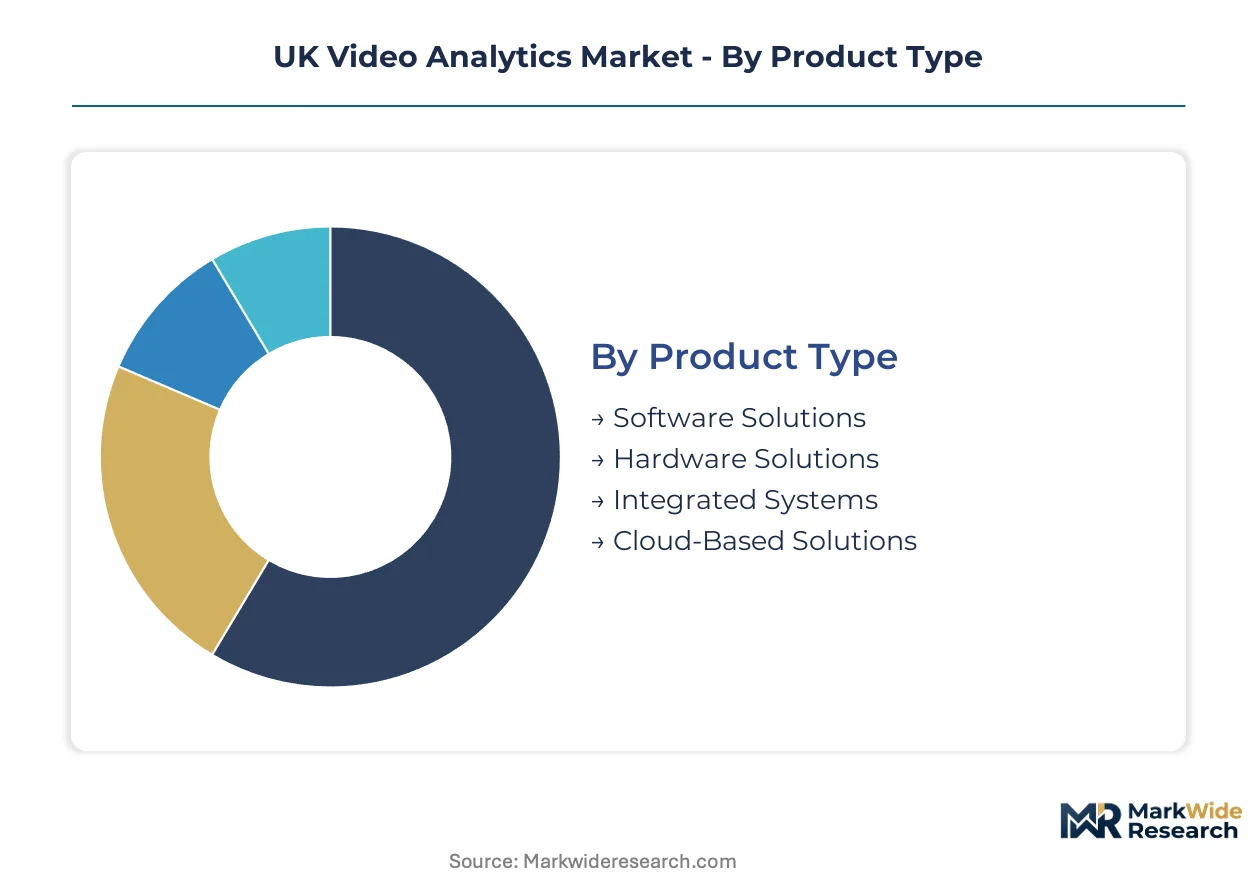
Segmentation in UK video analytics reveals how procurement priorities diverge between compliance-driven public sector buyers and ROI-focused commercial operators. Understanding these splits exposes where vendors can command pricing power versus where standardized solutions dominate.
Product Type:
Margin pools concentrate in software and edge-native hardware, while cloud and integrated systems compete on scale economics rather than premium pricing.
- Software Solutions:Subscription-based AI model updates with continuous retraining services dominate procurement in Greater London smart city frameworks. British transport authorities prioritize perpetual license conversions to recurring revenue models for operational budget alignment.
- Hardware Solutions:Embedded GPU and NPU accelerators with ARM-based firmware optimization command specialist engineering premiums. West Midlands manufacturing clusters drive demand for defect-detection hardware with sub-500 millisecond latency budgets.
- Integrated Systems:Bundled camera-analytics platforms reduce multi-vendor integration complexity for municipal police forces.
- Cloud-Based Solutions:Centralized processing architectures face GDPR cross-border data transfer constraints in sensitive biometric deployments.
Software Solutions holds installed capacity. Edge Computing is rotating up the share rankings.
End User:
Transportation and banking verticals absorb the highest per-camera analytics spend due to regulatory mandates and liability exposure.
- Transportation:Manchester's integrated traffic management systems demonstrate operational ROI from real-time congestion analytics. The Surveillance Camera Code of Practice mandates impact assessments for public space deployments, accelerating compliant refresh cycles among British transport authorities.
- Banking:GDPR Article 9 restrictions on biometric inference compel explicit consent workflows and privacy-by-default configurations. Financial institutions segment analytics pipelines between identifiable and anonymized processing tracks to satisfy ICO enforcement priorities.
- Retail:People counting and queue management applications face compressed margins from commoditized cloud offerings.
- Healthcare:Patient flow optimization and fall detection drive demand, though NHS procurement cycles extend deployment timelines.
Transportation captures the steepest expansion trajectory. Retail is consolidating around standardized platform plays.
Application:
Behavior analysis commands technical premiums while surveillance applications face price pressure from legacy integrators.
- Behavior Analysis:Transformer-based architectures for temporal event understanding displace recurrent neural networks in British police pilot programs. Greater London deployments validate loitering and crowd anomaly detection models, compressing vendor differentiation around proprietary training datasets.
- Surveillance:Automated license plate recognition systems accelerate deployment across British police forces with rigorous compliance to data protection by design standards. The Protection of Freedoms Act 2012 mandates published impact assessments for public space deployments.
- Traffic Management:Real-time congestion analytics demonstrate measurable operational ROI in Manchester and Birmingham command centers.
- People Counting:Occupancy monitoring applications expand in retail and public sector buildings for space utilization optimization.
Behavior Analysis leads technology premiums. Traffic Management is gaining share fastest in municipal budgets.
Technology:
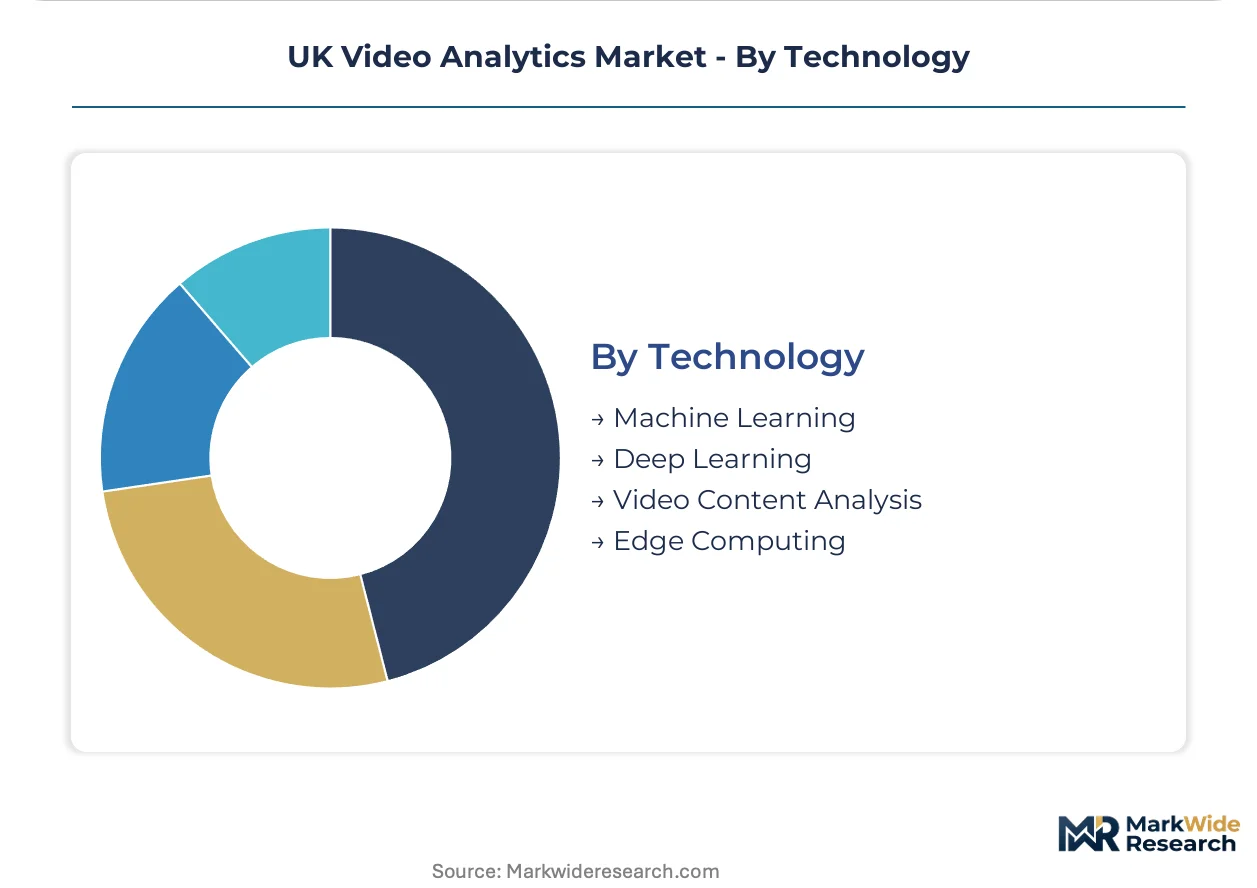
Edge computing architectures expand most quickly as UK enterprises minimize bandwidth costs and maintain jurisdictional control over sensitive footage.
- Edge Computing:On-device biometric inference eliminates cross-border data transfer risks for GDPR-sensitive deployments. Camera-level processing architectures fragment procurement patterns as police forces bypass traditional centralized systems.
- Deep Learning:Generative AI training techniques compress model development cycles and expand detectable behavior categories beyond rule-based systems in Greater London pilot programs.
- Machine Learning:Established algorithms for object detection and classification face margin compression from open-source alternatives.
- Video Content Analysis:Rule-based event detection retains share in legacy infrastructure upgrades where neural network migration costs deter refresh cycles.
Edge Computing anchors forward investment. Deep Learning is climbing the technology adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
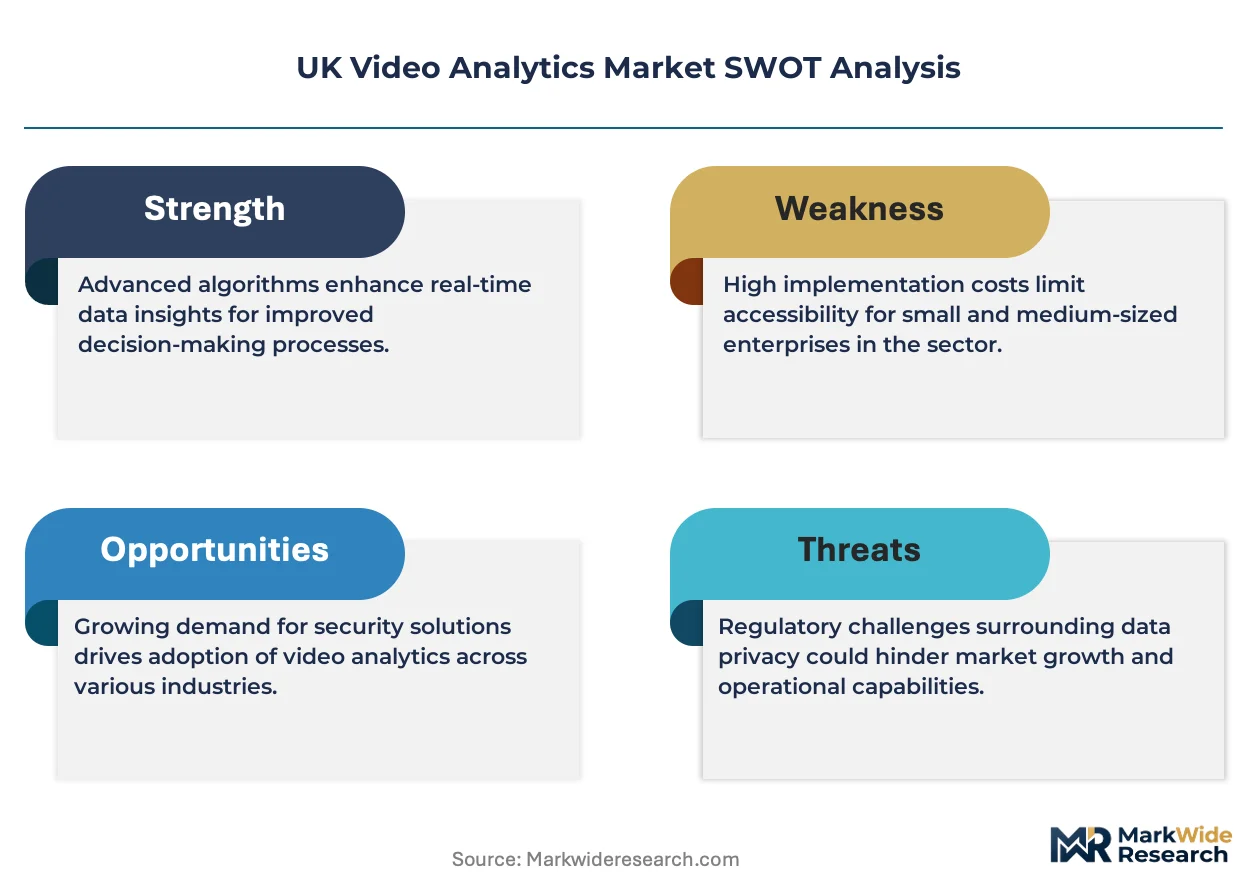
The Information Commissioner's Office anchors the United Kingdom's regulatory environment for video analytics, enforcing GDPR Article 9 restrictions on biometric inference and mandating privacy-by-default configurations across all deployments.
London and the Southeast
Greater London's smart city infrastructure drives the highest concentration of edge-native analytics procurement in the UK. Transport for London mandates GDPR-compliant impact assessments for all public space surveillance under the Surveillance Camera Code of Practice. The Thames Valley and M25 corridor host the densest clustering of banking and critical infrastructure operators deploying behavior analysis systems.
Midlands
West Midlands manufacturing clusters generate specialized demand for defect-detection analytics with sub-500 millisecond latency requirements. Birmingham's integrated transport command centers demonstrate measurable operational ROI from real-time congestion monitoring. The region's automotive supply chain operators are accelerating migration from legacy coaxial infrastructure to IP-based edge processing architectures.
North England
Manchester anchors northern demand through its integrated traffic management systems and police force pilot programs for crowd anomaly detection. The city's procurement patterns favor subscription-based AI model updates over perpetual licensing. Liverpool and Leeds municipal authorities follow Manchester's compliance framework for Surveillance Camera Commissioner oversight.
Scotland
Scottish police forces and transport authorities operate under the UK-wide Protection of Freedoms Act 2012 with additional devolved data protection guidance. Edinburgh and Glasgow concentrate public sector deployment of automated license plate recognition systems. The Scottish Government's digital infrastructure investments prioritize edge computing architectures to minimize cross-border data transfer risks.
Wales and Northern Ireland
Cardiff and Belfast municipal contracts face budget constraints that deter full analog-to-IP migration cycles. Welsh transport authorities leverage Manchester's proven frameworks for congestion analytics deployment. Northern Ireland's critical infrastructure operators maintain deep relationships with UK-wide systems integrators for compliant procurement.
UK Video Analytics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around vendors capable of delivering edge-native analytics and rigorous GDPR compliance. Tier-one players compete through in-house chipset design and direct relationships with UK critical infrastructure operators. Specialist vendors differentiate via sector-specific compliance expertise and localized service capabilities. Dominant competitive moves include strategic partnerships with transport authorities and portfolio diversification into AI Act alignment consulting.
Within the integrated systems tier, Axis Communications AB exemplifies the edge-native processing archetype through its camera-level inference capabilities. Synectics Plc occupies a position representing deep relationships with UK critical infrastructure operators. Bosch Security Systems anchors the compliance-focused segment, exemplifying rigorous adherence to British data protection by design standards.
| Leading Market Players |
|---|
| Axis Communications AB |
| Synectics Plc |
| Milestone Systems A/S |
| Bosch Security Systems |
| Genetec Inc. |
| IBM Corporation |
| Honeywell International Inc. |
| Cisco Systems, Inc. |
| Verkada |
| Others |
Value Network & Pricing Analysis
Camera-level processing scale economies concentrate procurement power among British transport authorities and police forces capable of multi-thousand-unit deployments, compressing price floors for edge-native hardware while elevating service-attach premiums for continuous AI model retraining.
Pricing Analysis
Greater London commands 15-20% hardware premiums over Manchester and Birmingham for identical edge-native camera specifications, reflecting transport authority procurement scale and GDPR compliance consulting bundling. Subscription-based AI model updates with continuous retraining services dominate pricing structures, displacing perpetual licensing across British smart city frameworks. Cost compression in commoditized cloud-based analytics stems from open-source algorithm proliferation, while embedded GPU and NPU accelerators with ARM firmware optimization retain pricing power. Municipal police forces exhibit highest price sensitivity due to budget-constrained analog-to-IP migration cycles; banking and critical infrastructure operators demonstrate lowest sensitivity, prioritizing GDPR-compliant edge processing and sub-500 millisecond latency guarantees.
Supply Chain Analysis
Strategic stockpiling of GPU and NPU accelerators characterizes British critical infrastructure procurement patterns, buffering against East Asian foundry bottlenecks that disrupted camera component availability through 2023-2024. Silicon supply concentrates in Taiwan, South Korea, and mainland China for neural processing units and embedded vision processors, while ARM-based firmware optimization talent pools center on Cambridge and Bristol engineering clusters. Raw material dependencies span silicon wafers, specialized image sensors, and high-bandwidth memory modules. Single-source vulnerability in TSMC advanced node allocation presents structural supply chain risk for low-latency edge inference chips. Distribution runs through UK systems integrators with direct relationships to transport authorities and police forces, bypassing traditional security distributor channels for large-scale municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK video analytics hardware margins are compressing toward service-attach economics, with continuous AI model retraining and GDPR compliance consulting expanding at triple the rate of camera unit sales across Greater London and Manchester procurement frameworks.
For Market Incumbents: Secure firmware optimization capabilities for ARM-based accelerators through captive engineering teams or targeted acquisition of Cambridge-edge embedded AI specialists, defending against cloud-native entrants leveraging open-source model compression. Reinforce channel control by embedding compliance consulting services directly into transport authority and police force procurement contracts, creating switching costs around Surveillance Camera Commissioner impact assessment workflows. For New Entrants and Emerging Players: Differentiate on sector-specific GDPR compliance automation, targeting West Midlands manufacturing clusters where defect-detection analytics remain underpenetrated and procurement cycles favor specialist vendors over integrated platform plays. Pursue white-space expansion through 5G-integrated edge node deployments for mobile traffic management scenarios in Birmingham and Leeds, bypassing entrenched relationships in fixed infrastructure segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-native hardware vendors with in-house chipset design capabilities and established UK critical infrastructure operator relationships over cloud-dependent software pure-plays facing GDPR cross-border data transfer constraints. Long-term viability across the analysis window hinges on AI Act alignment service attach rates and continuous retraining contract renewal rates. Watch for inflection when Manchester and Greater London procurement frameworks mandate explicit consent workflow automation as standard tender requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Hardware Platform Launch | Axis Communications leverages camera-level inference to bypass centralized processing bottlenecks in Transport for London deployments. |
| GDPR Compliance Consulting Integration | Bosch Security Systems bundles privacy-by-default configuration services with hardware sales to satisfy ICO enforcement priorities. |
| Strategic Partnership with Transport Authority | Synectics Plc anchors recurring revenue through multi-year service contracts with Manchester's integrated traffic command center. |
| Acquisition of Embedded AI Specialist | Consolidation of ARM firmware optimization talent pools accelerates time-to-market for sub-500 millisecond latency products. |
| AI Act Alignment Service Development | EU-facing British exporters create adjacent revenue streams through compliance consulting for automated decision-making systems. |
Research Methodology
The analysis maps edge computing architectures, software solutions, hardware accelerators, and integrated systems deployments, each validated through security integrators, transport authority procurement officers, police force technology leads, and embedded AI engineering directors. Primary fieldwork combined structured interviews with UK critical infrastructure operators and channel partners, cross-referenced against secondary validation from SEC filings of listed security technology vendors, UK Home Office procurement disclosures, and Information Commissioner's Office enforcement guidance documents. Bottom-up unit economics for camera deployments and top-down market sizing from vendor revenue disclosures were triangulated to establish segmentation splits.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with edge computing adoption curves and subscription revenue conversion rates stress-tested against Manchester and Greater London smart city framework disclosures. Segmentation dimensions modeled include product type, end-user vertical, application category, and technology architecture, with deployment scale and GDPR compliance tier as cross-cutting variables. CAGRs derived from installed base growth, replacement cycle acceleration under Surveillance Camera Code of Practice mandates, and AI model update attach rate expansion across British transport and banking verticals.
The analysis sits within stated boundaries; outcomes outside sustained UK public sector procurement momentum and stable East Asian semiconductor foundry capacity would require recalibration. Forecasts reflect documented assumptions regarding edge-native processing preference persistence and GDPR enforcement trajectory. Revision becomes warranted when GPU and NPU supply concentration crosses critical disruption thresholds or when ICO biometric inference restrictions expand beyond current Article 9 interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Identity Analytics Market
Analytics
Mobile Apps and Web Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Italy ICT Market
Analytics
Network Analytics Services Market
Analytics
Web Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
Global Streaming Analytics Market
Analytics
Drone Analytics Software Market
Analytics
North America Crowd Analytics Market
Analytics
Europe Operational Intelligence Market
Analytics
App Analytics Tools Market
Analytics
Data Discovery Market
Analytics
Content Analytics and Search Software Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Iraq ICT Market