
 Enterprise Content Management Software Market | 2026-2036
Enterprise Content Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Content Management Software Market Intelligence
Subscription-based content services is consolidating how enterprises procure document infrastructure, shifting capital expenditure to recurring operational models. OpenText leverages deep vertical templates for regulated industries to sustain long-term contract value. Hyland anchors its position through healthcare-specific workflow engines that dominate North American hospital networks. Microsoft SharePoint competes through native integration with productivity suites that control enterprise desktop environments.
Enterprise content management software comprises integrated platforms for capturing, storing, managing, and delivering structured and unstructured information across organizations, typically supporting metadata indexing, full-text search, and role-based access controls with audit trails. Its primary commercial purpose centers on governance, retrieval efficiency, and compliance documentation for regulated operations. Cloud-based deployment leads solution uptake as enterprises prioritize elastic capacity and reduced data center overhead, while document management retains the deepest margin pool due to persistent on-premise legacy footprints in financial and legal sectors. Workflow automation represents the fastest-expanding segment as organizations embed robotic process automation connectors into approval chains.
The EU AI Act and GDPR impose automated decision-making transparency and data residency requirements that directly shape European ECM procurement specifications and vendor qualification criteria. In the United States, SEC recordkeeping rules and HIPAA privacy standards mandate retention architectures that drive demand for tamper-evident storage and granular permission frameworks. Stakeholders must evaluate how emerging algorithmic accountability obligations will alter content classification roadmaps and vendor liability structures.
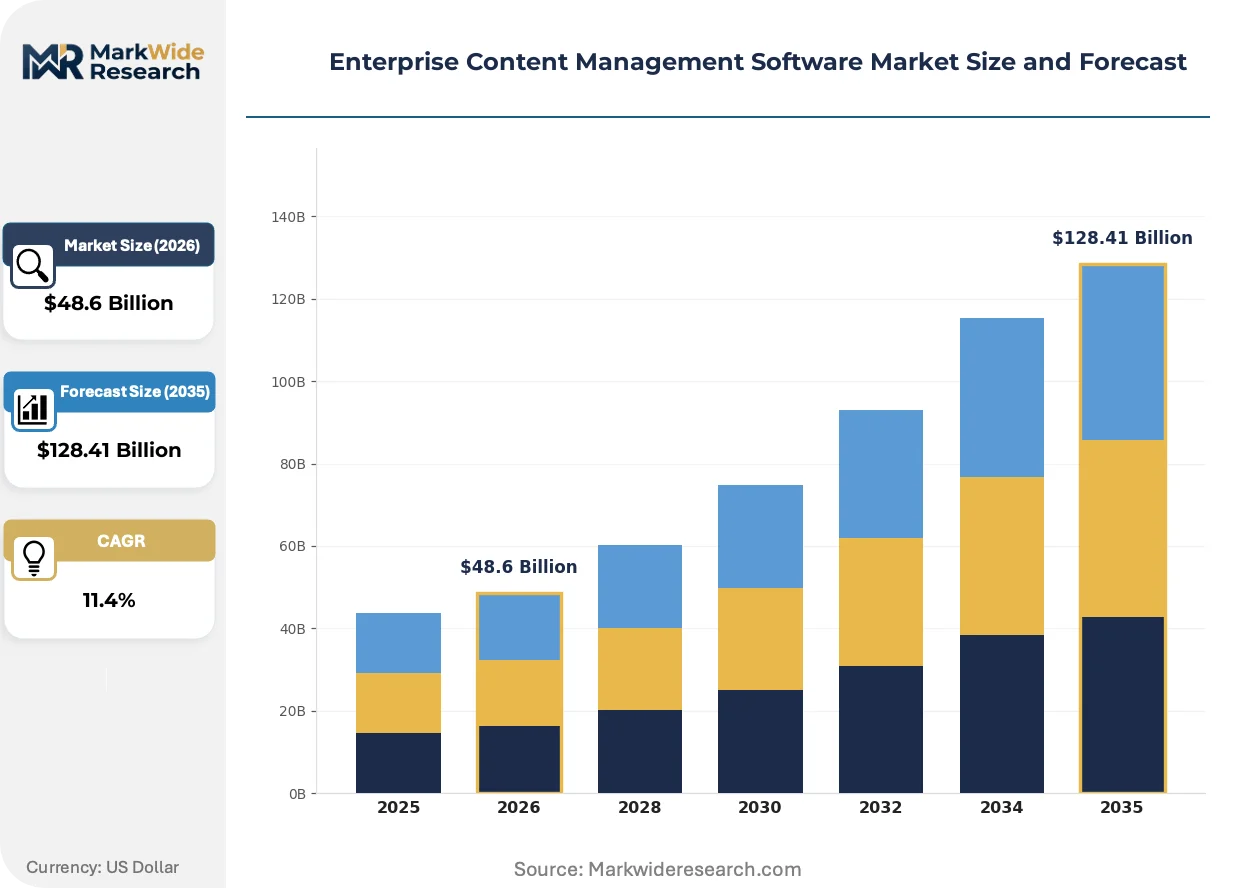
Market Dynamics
Subscription-based content services is consolidating enterprise procurement patterns, shifting capital expenditure to recurring operational models while cloud-native architectures displace on-premise document infrastructure.
Growth Catalysts
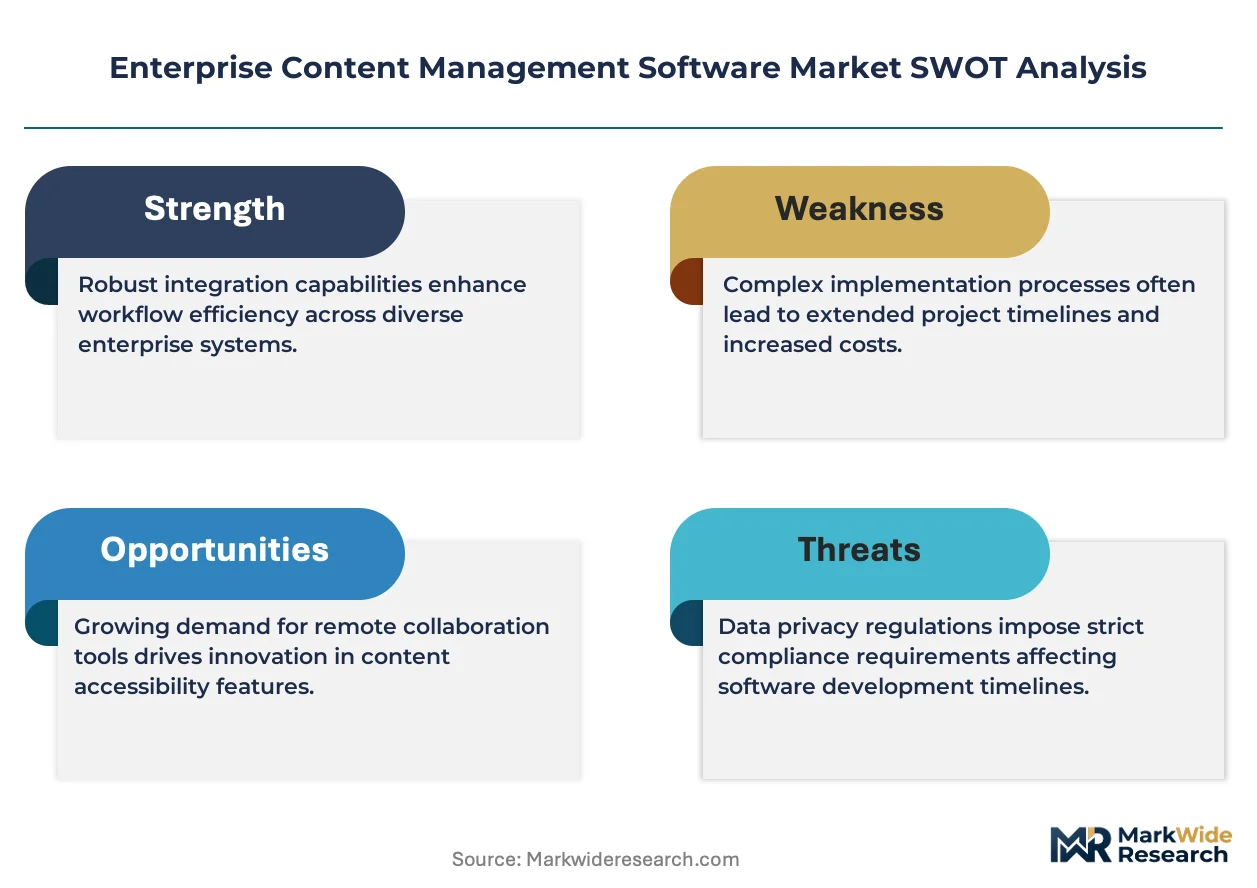
- EU AI Act:Automated decision-making transparency mandates are forcing enterprises to upgrade content classification systems with explainable metadata tagging.
- Healthcare digitization:Hospital networks in the United States are deploying workflow engines to satisfy HIPAA-compliant patient record management.
- Robotic process automation:Financial services firms embed RPA connectors into approval chains, accelerating document routing velocity.
Market Restraints
- Data residency mandates:GDPR localization requirements fragment cloud deployment architectures across European member states.
- Legacy system entrenchment:Financial and legal sectors maintain on-premise document management due to sunk infrastructure costs.
- Skill scarcity:Enterprise architects with hybrid cloud-security expertise command premium compensation, constraining mid-market adoption.
Strategic Opportunities
- Healthcare workflow specialization:North American hospital networks seek vertical-specific engines for clinical document routing.
- Generative AI convergence:Large language models paired with semantic search are opening automated content synthesis applications.
- German cloud demand:Federal data sovereignty requirements create openings for domestic-hosted ECM platforms.
Industry Challenges
- Integration complexity:Enterprises struggle to bridge decades-old document repositories with API-first cloud platforms.
- Certification timelines:EU AI Act conformity assessments delay product roadmaps for automated classification features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Content Management Software Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $128.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Service End User: Large Enterprises, SMEs, Government, Education Solution: Document Management, Workflow Automation, Digital Asset Management, Records Management Feature: Search Functionality, User Permissions, Version Control, Integration Capabilities |
| Companies Covered | Hyland, Xerox DocuShare, OpenText, CoreMedia, Contentstack, Adobe Experience Manager, Sitecore, DocStar, Microsoft SharePoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Content Management Software Market Strategic Shifts & Innovations
Generative AI and semantic search architectures are compressing traditional document retrieval paradigms while regulatory mandates reshape vendor qualification criteria.
Large language model integration is expanding into enterprise content platforms as the core mechanism for automated summarization and contextual query response. Healthcare providers and legal departments are piloting these capabilities at accelerated procurement cycles. The technology is expanding into contract analysis and clinical documentation workflows, compressing hours of manual review into minutes.
The EU AI Act imposes algorithmic accountability obligations on automated content classification systems deployed within European member states. Vendors must now document training data provenance and decision logic for audit trails. Healthcare and financial services procurement specifications in Germany and France are being rewritten to mandate these transparency features.
Outcome-based service contracts are displacing perpetual license models as enterprise buyers demand consumption-aligned pricing. System integrators and managed service providers capture margin from this transition, unbundling implementation from software licensing. This pattern is most visible in United Kingdom financial services and United States federal contracting channels.
Enterprise Content Management Software Market Segmentation
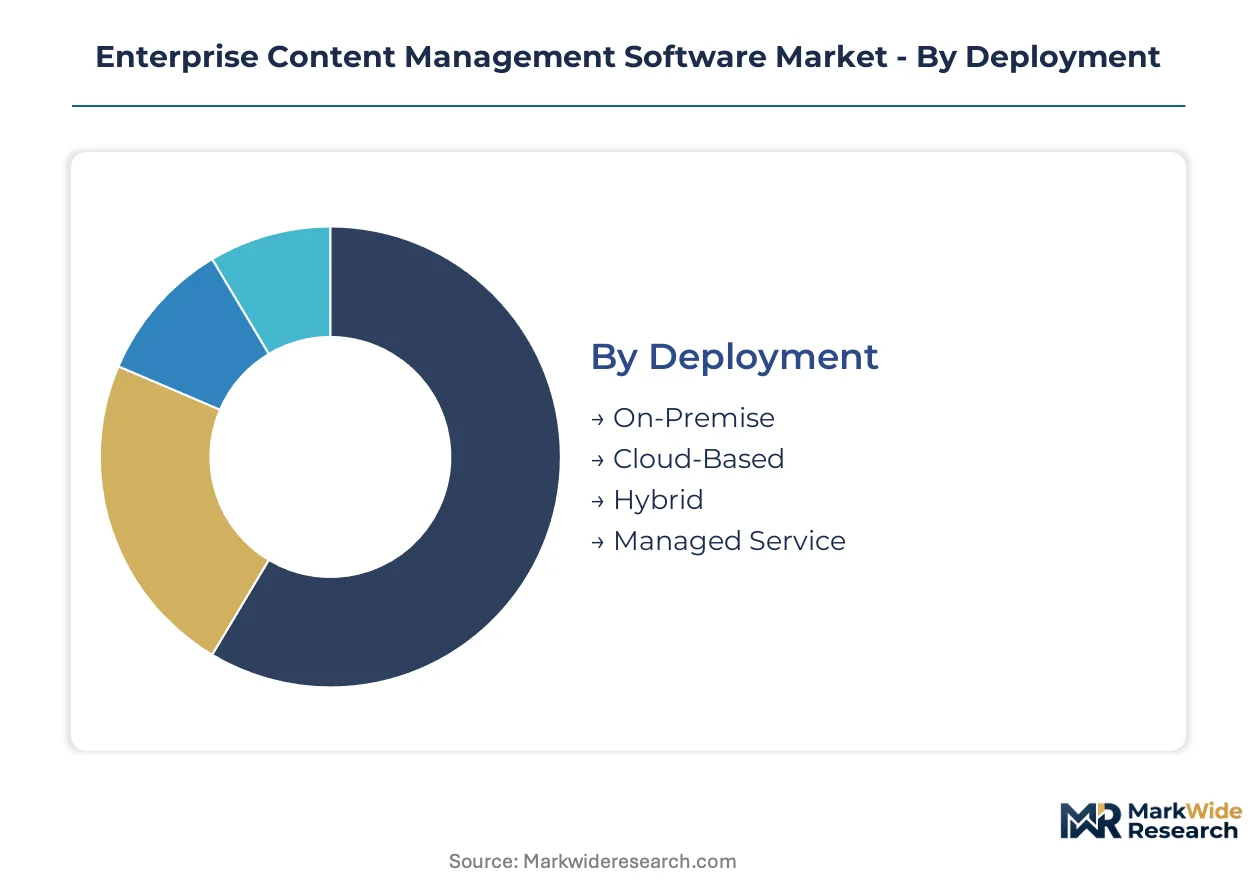
ECM procurement patterns diverge sharply between legacy infrastructure defenders and cloud-native adopters. Deployment mode determines compliance architecture, while end-user scale dictates pricing elasticity and feature depth across vendor portfolios.
Deployment:
Volume concentrates in elastic, low-overhead configurations while premium contracts retain on-premise sovereignty for regulated data.
- Cloud-Based:Elastic capacity architectures dominate new procurement cycles, with German federal data sovereignty requirements driving domestic-hosted platform demand. Healthcare networks in France and the United States accelerate migration to satisfy GDPR and HIPAA audit trail mandates without data center overhead.
- On-Premise:Perpetual license models persist in financial services and legal sectors where sunk infrastructure costs and tamper-evident storage requirements override cloud migration economics. SEC recordkeeping rules and granular permission frameworks sustain demand for air-gapped document repositories.
- Hybrid:Split architectures allow sensitive records to remain on-premise while collaborative workflows migrate to cloud tiers.
- Managed Service:Third-party operational control appeals to mid-market enterprises lacking hybrid cloud-security expertise.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
End User:
Customer scale determines contract structure, with consumption-aligned pricing penetrating mid-market segments previously locked out of enterprise-grade governance tools.
- Large Enterprises:Complex multi-site implementations demand workflow engines with robotic process automation connectors and role-based access controls spanning global operations. Outcome-based service contracts displace perpetual licenses as procurement teams demand usage-aligned pricing.
- SMEs:Subscription-based content services consolidate document infrastructure procurement, shifting capital expenditure to recurring operational models. Native integration with productivity suites controls desktop environment decisions.
- Government:Federal contracting channels in the United States mandate FedRAMP-authorized cloud architectures with granular audit capabilities.
- Education:Budget-constrained institutions prioritize open-source interoperability and campus-wide licensing economies.
Procurement sophistication peaks with Large Enterprises. Fastest feature adoption is climbing among SMEs.
Solution:
Functional depth correlates with regulatory exposure, where document retention mandates create sticky revenue in governance-heavy verticals.
- Document Management:Metadata indexing and full-text search capabilities form the foundational layer for enterprise information governance. Financial and legal sectors maintain the deepest margin pool due to persistent on-premise legacy footprints and compliance documentation requirements.
- Workflow Automation:Robotic process automation connectors embed into approval chains, accelerating document routing velocity across hospital networks and financial services firms. This segment gains share fastest as organizations automate clinical and contract review processes.
- Digital Asset Management:Marketing operations and media enterprises deploy semantic search for rich media cataloging and rights management.
- Records Management:Tamper-evident storage and retention scheduling satisfy EU AI Act transparency mandates for automated classification audit trails.
Revenue concentration favors Document Management. Steepest expansion trajectory belongs to Workflow Automation.
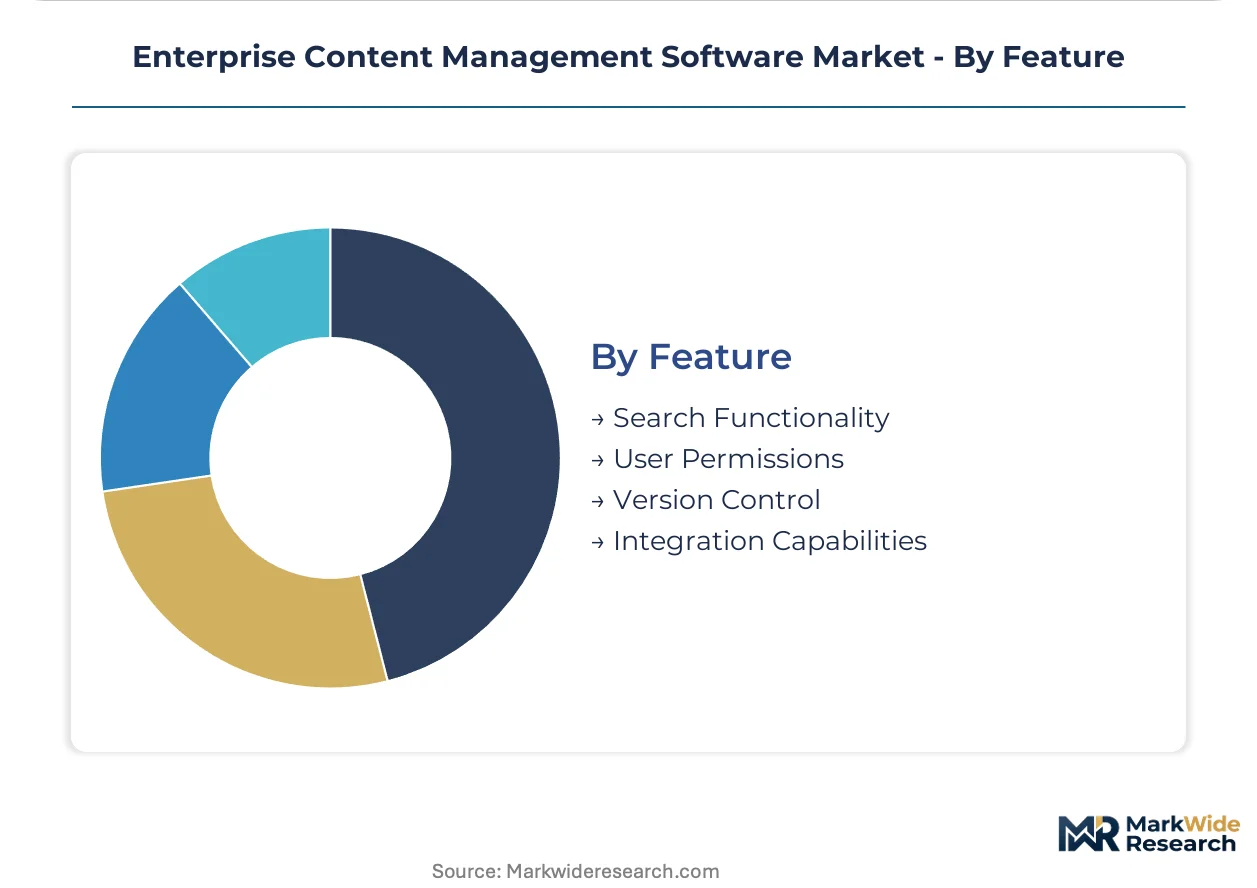
Feature:
Technical capabilities stratify between baseline hygiene factors and differentiated intelligence layers that command pricing premiums.
- Integration Capabilities:API-first connectivity determines platform viability as enterprises bridge decades-old repositories with modern cloud architectures. System integrators capture margin from unbundling implementation from software licensing.
- Search Functionality:Large language model integration enables automated summarization and contextual query response, compressing hours of manual document review into minutes for legal departments and healthcare providers.
- User Permissions:Granular access frameworks satisfy HIPAA privacy standards and GDPR data residency requirements across multi-jurisdictional deployments.
- Version Control:Audit trails and change tracking underpin SEC recordkeeping compliance and EU AI Act algorithmic accountability obligations.
Baseline functionality centers on Version Control. Competitive differentiation is concentrating in Integration Capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in US technology corridors while consumption spreads across regulated European healthcare systems and German federal agencies. Cloud infrastructure deployment patterns diverge sharply between data-sovereignty jurisdictions and open-market adopters.
United States
Hospital networks in Texas and California deploy workflow engines for HIPAA-compliant patient record digitization. SEC recordkeeping rules mandate tamper-evident storage architectures that sustain on-premise document management demand. Healthcare clusters in Boston and Minneapolis accelerate migration to cloud tiers for collaborative clinical workflows.
Germany
Federal data sovereignty requirements drive domestic-hosted platform procurement across Baden-Württemberg manufacturing hubs. GDPR localization mandates fragment cloud deployment architectures between member states. Munich and Frankfurt financial centers maintain hybrid configurations for sensitive records while routing collaborative workflows through certified cloud tiers.
France
Healthcare providers in Île-de-France pilot large language model integration for clinical documentation compression. CNIL enforcement of automated decision-making transparency reshapes procurement specifications for content classification systems. Paris legal departments demand explainable metadata tagging for contract analysis workflows.
United Kingdom
Financial services firms in London embed robotic process automation connectors into document approval chains. Outcome-based service contracts displace perpetual licenses in City of London procurement channels. System integrators capture margin from unbundling implementation from software licensing across Thames Valley technology corridors.
Japan
Manufacturing enterprises in Kanto and Kansai regions prioritize API-first connectivity for bridging legacy repositories with modern cloud architectures. METI guidelines on data governance influence enterprise content platform selection. Tokyo-based system integrators dominate mid-market managed service offerings for hybrid cloud-security expertise.
Enterprise Content Management Software Market Key Industry Players
Capital-heavy platform vendors compete with asset-light vertical specialists across deployment modes and compliance architectures. The vendor base stratifies between consolidated enterprise suites and point-solution specialists. Three archetypes dominate: full-stack incumbents with deep vertical templates, cloud-native challengers with API-first architectures, and managed service providers capturing operational control contracts. M&A activity concentrates on workflow automation capabilities while strategic partnerships bridge legacy system integration gaps.
Within the full-stack incumbent tier, OpenText and Hyland exemplify divergent vertical specialization strategies. Microsoft SharePoint anchors the productivity-suite-integrated archetype through native desktop environment control. Cloud-native challengers including Contentstack and Sitecore occupy positions defined by headless architecture flexibility and composable content infrastructure.
| Leading Market Players |
|---|
| Hyland |
| Xerox DocuShare |
| OpenText |
| CoreMedia |
| Contentstack |
| Adobe Experience Manager |
| Sitecore |
| DocStar |
| Microsoft SharePoint |
| Others |
Cost & Logistics Intelligence
Enterprise architects with hybrid cloud-security expertise in Germany and the United States command premium compensation, widening the spread between managed service pricing tiers and self-hosted deployment costs. Labor scarcity in these markets forces vendors to absorb talent premiums or pass them downstream, compressing margins on mid-market SaaS contracts while sustaining premium pricing for air-gapped sovereign cloud configurations.
Pricing Analysis
Margin tightening in cloud-native tiers reflects the shift from perpetual licenses to consumption-aligned subscription models. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and vertical certification depth. Healthcare and financial services buyers exhibit lowest price sensitivity due to compliance documentation requirements. SMEs drive cost-down pressure through native productivity suite bundling.
Supply Chain Analysis
Hyperscaler infrastructure rests on concentrated data center capacity in the United States, Ireland, and Germany. Cloud compute, storage arrays, and API middleware form the critical input stack. Single-source vulnerability concentrates in German federal hosting certifications. Distribution runs through system integrators unbundling implementation from software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU AI Act conformity assessments delay product roadmaps for automated classification features, forcing subscale vendors toward exit or acquisition.
For Market Incumbents: Hedge against cloud-native challengers by deepening vertical templates for HIPAA-compliant healthcare workflows and FedRAMP-authorized federal architectures. Acquire workflow automation specialists to embed RPA connectors before point-solution vendors capture hospital network procurement. Certification investment in EU AI Act transparency documentation anchors long-term contract value. For New Entrants and Emerging Players: Enter via German federal data sovereignty requirements where domestic-hosted platforms face limited competition from hyperscaler incumbents. Target mid-market manufacturing hubs in Baden-Württemberg seeking hybrid configurations. Position through API-first architectures that bridge decades-old document repositories without full migration. For Investors and Strategic Acquirers: The window for entry favors workflow automation specialists with healthcare-specific clinical routing engines. Long-term viability hinges on vertical depth rather than horizontal platform breadth. Watch CNIL enforcement patterns in France as the signal for EU-wide procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Workflow Acquisition | Healthcare-specific engines dominate North American hospital network procurement cycles. |
| EU AI Act Certification Investment | Transparency documentation mandates reshape German and French vendor qualification criteria. |
| Hybrid Cloud Partnership | System integrators capture margin from unbundling implementation in Thames Valley corridors. |
| Large Language Model Integration | Semantic search capabilities compress legal review timelines for Paris contract analysis workflows. |
| FedRAMP Authorization Pathway | Federal contracting channels mandate granular audit capabilities for United States government demand. |
Research Approach
Multi-period observation of ECM procurement cycles, vendor contract structures, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and hospital procurement databases. Bottom-up deployment mode sizing and top-down vertical spending estimates were triangulated.
Segment-weighting applied deployment mode, organization size, vertical industry, and regional adoption pattern dimensions across the analysis window. CAGRs derived from elasticity-adjusted growth curves incorporating cloud migration velocity and compliance mandate phase-in schedules. Workflow automation penetration rates and RPA connector adoption curves informed solution-level trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged federal certification delays. Forecasts reflect documented assumptions regarding cloud migration economics and talent market tightness. A small set of named triggers—CNIL penalty precedents, FedRAMP authorization backlogs, and German federal procurement rulings—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Global Linux Operating System Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Channel Management Software Market
Software & Services
Computer Software Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Custom Software Development Market
Software & Services
Visitor Identification Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Application Platform Market