
 Europe Electronic Contract Manufacturing and Design Services Market | 2026-2036
Europe Electronic Contract Manufacturing and Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electronic Contract Manufacturing and Design Services Market Intelligence
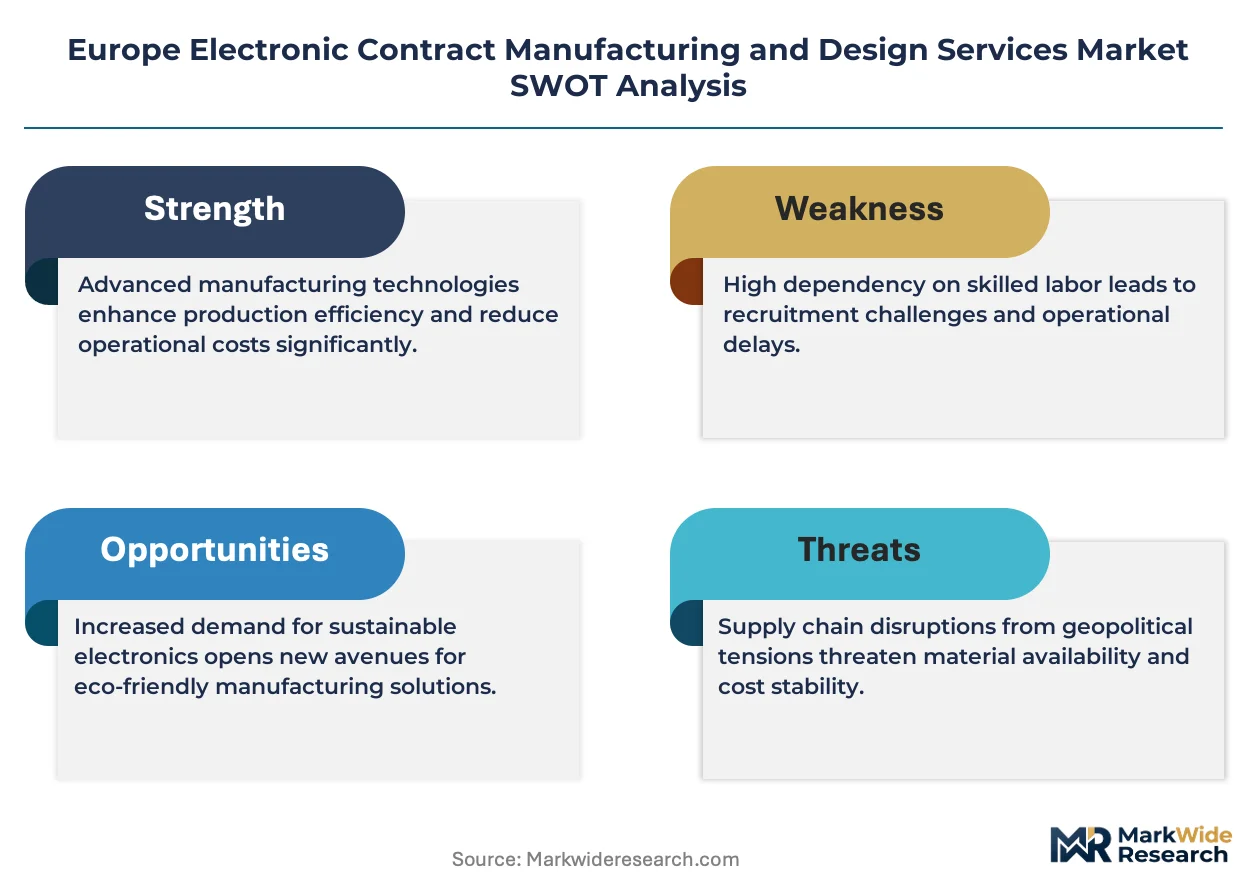
Asset-light manufacturing partnerships and equipment-leasing structures are fragmenting competitive boundaries across European electronics outsourcing. Zollner Elektronik AG leverages its Bavarian production footprint to dominate complex PCB assembly for German automotive Tier-1s. Kitron ASA anchors Nordic medical device supply chains through specialized cleanroom manufacturing in Norway and Sweden. Flex Ltd. competes via embedded systems integration for telecommunications OEMs seeking IoT-ready hardware platforms.
Electronic contract manufacturing and design services encompass the outsourced production, testing, and engineering of printed circuit board assemblies, electromechanical subsystems, and firmware-integrated hardware operating across industrial temperature ranges and EMC compliance classes. These services enable OEMs to convert electronic designs into volume-manufactured products without captive fabrication facilities. PCB Assembly generates the largest revenue pool within service types due to recurring production schedules across automotive and medical verticals. Embedded Systems within technology categories captures expanding margins as robotics and AI Integration demand specialized firmware-hardware co-design capabilities. Medical Devices as an industry vertical sustains premium pricing structures driven by CE marking and MDR compliance requirements.
EMA medical device regulations, REACH substance restrictions, and CE marking directives collectively elevate compliance costs for non-European competitors while reinforcing incumbent advantages. The EU AI Act introduces forthcoming conformity obligations for embedded AI hardware that will reshape design service procurement criteria. Stakeholders must evaluate how dual-use technology export controls and CSRD supply chain disclosure mandates will alter partner selection frameworks for sensitive electronics manufacturing.
Market Dynamics
Asset-light manufacturing partnerships and equipment-leasing structures are fragmenting competitive boundaries across European electronics outsourcing. The EU Green Deal's electrification mandates are pulling automotive OEMs toward outsourced PCB assembly and embedded systems production at unprecedented velocity.
Growth Catalysts
- EU Green Deal electrification mandates:Automotive OEMs across Germany and France are expanding outsourced electronics production to meet accelerated decarbonization timelines. Tier-1 suppliers seek captive capacity for powertrain control modules.
- EMA MDR compliance requirements:Medical device manufacturers are consolidating supplier relationships around European cleanroom-certified partners. CE marking and post-market surveillance obligations favor incumbent regional contract manufacturers.
- Industrial robotics integration:German automotive and logistics OEMs are procuring AI-enabled embedded systems requiring firmware-hardware co-design capabilities. Specialized design services command expanding margins.
Market Restraints
- Semiconductor input cost volatility:Foundry capacity constraints and raw material price swings compress contract manufacturer margins. Memory and advanced node chip shortages disrupt production scheduling.
- Supply concentration in Asian substrate production:European PCB assemblers remain dependent on East Asian laminate and copper-clad suppliers. Geopolitical friction elevates inventory carrying costs.
- REACH substance restriction compliance:ECHA's expanding restricted substance lists force reformulation of solder pastes and conformal coatings. Non-compliant material stocks require write-downs.
Strategic Opportunities
- Poland and Czech Republic industrial zones:Lower-cost manufacturing corridors near German automotive clusters attract PCB assembly investment. Skilled technical labor pools support complex electromechanical integration.
- EU AI Act embedded hardware conformity:Forthcoming obligations for AI-enabled devices will reshape design service procurement criteria. First-mover certification capabilities differentiate service providers.
- Telecommunications IoT-ready platforms:5G infrastructure rollout and industrial sensor networks demand firmware-integrated hardware with EMC compliance. Design-service bundling captures value upstream.
Industry Challenges
- Embedded systems firmware engineering talent scarcity:Specialized co-design capabilities for robotics and AI integration outpace vocational training pipeline output. German industrial clusters compete for limited qualified engineers.
- CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements force contract manufacturers to document Scope 3 emissions and labor practices. Data infrastructure investments strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electronic Contract Manufacturing and Design Services Market |
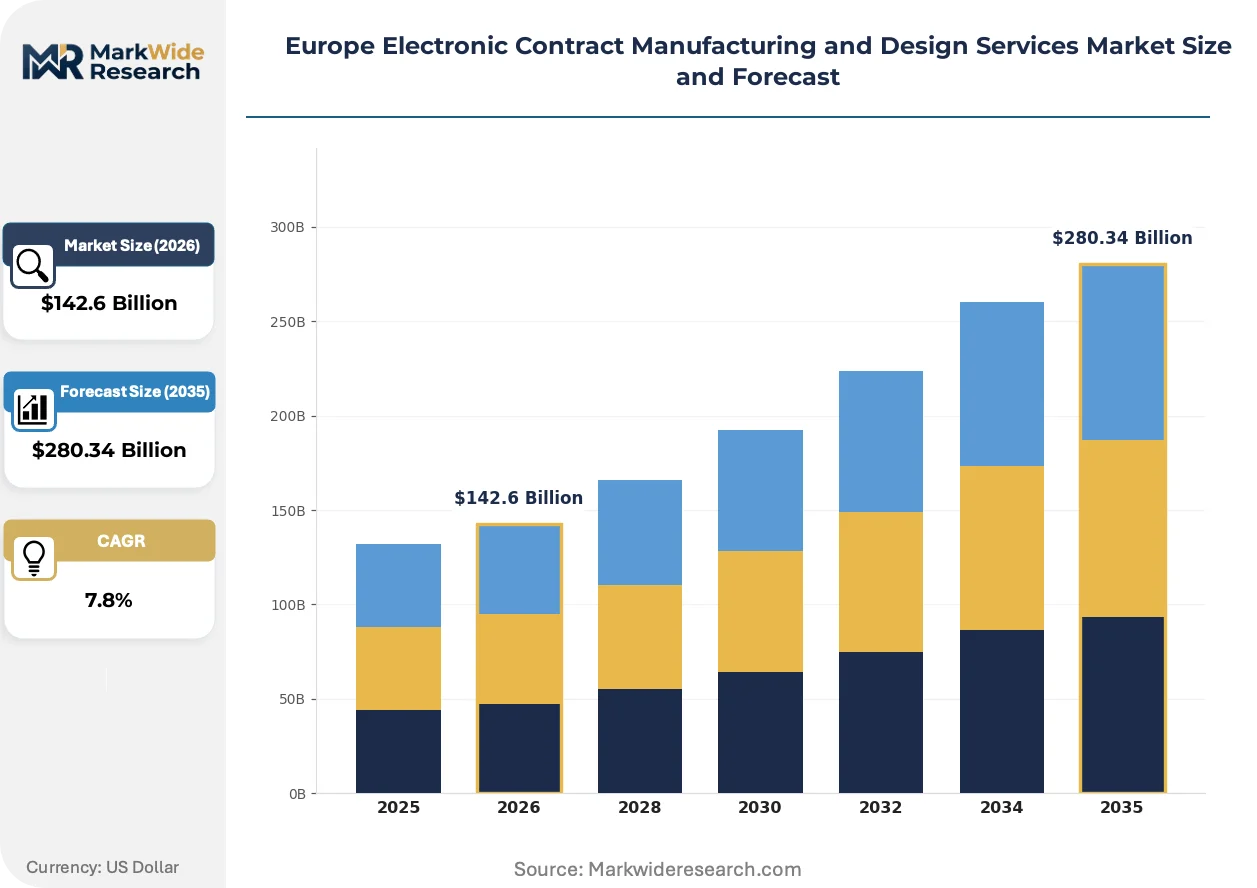
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $280.34 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: PCB Assembly, Functional Testing, Prototyping, Supply Chain Management Industry Vertical: Telecommunications, Consumer Electronics, Medical Devices, Automotive Components Technology: IoT Solutions, Embedded Systems, Robotics, AI Integration End User: OEMs, Tier-1 Suppliers, Startups, Aftermarket Providers |
| Companies Covered | Zollner Elektronik AG, Kitron ASA, Hon Hai Precision Industry Co. Ltd. (Foxconn), Benchmark Electronics, Scanfil, Flex Ltd., Cicor Management AG, Neways, Jabil Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electronic Contract Manufacturing and Design Services Market Strategic Shifts & Innovations
European electronics outsourcing is restructuring around firmware-hardware convergence, regulatory compliance automation, and compressed OEM procurement cycles. Three developments are redefining competitive positioning.
Advanced packaging technologies including system-in-package and fan-out wafer-level packaging are collapsing the traditional boundary between semiconductor fabrication and PCB assembly. German automotive Tier-1s are adopting these formats for autonomous driving sensor modules, compressing supplier tiers from three layers to direct foundry-EMS relationships.
REACH substance restrictions and RoHS recast directives are forcing reformulation of solder alloys and flux chemistries across European production facilities. Industrial consequence includes qualification delays for new material sets. Medical device manufacturers face the steepest compliance curves as MDR biocompatibility requirements intersect with electronics substance bans.
OEM technical sourcing teams are consolidating vendor panels around full-lifecycle design-to-manufacture partners. Discrete component procurement and standalone PCB assembly contracts are yielding to integrated platform development agreements. This concentration is most visible in Nordic medical device supply chains, where cleanroom-certified partners anchor multi-year development programs.
Europe Electronic Contract Manufacturing and Design Services Market Segmentation
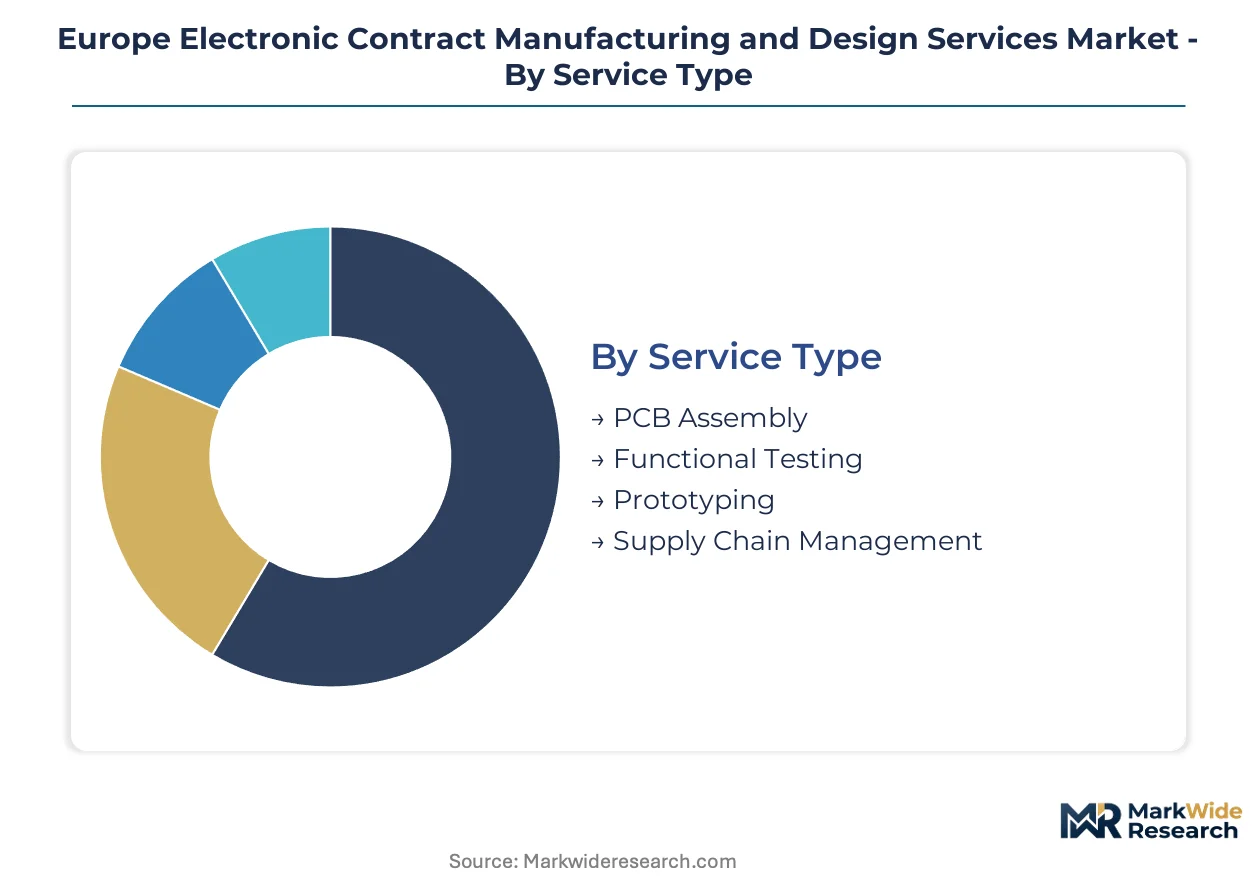
European electronics outsourcing demands precise segment alignment across automotive electrification mandates, medical device compliance curves, and industrial automation procurement cycles. Contract manufacturers configure service portfolios around these divergent technical and regulatory requirements.
Service Type:
Cost tier differentiation separates commoditized volume production from premium engineering-intensive engagements across European manufacturing corridors.
- PCB Assembly:Surface-mount and through-hole soldering operations populate multilayer boards with passive components, ICs, and connectors for automotive control modules. German Tier-1 suppliers in Bavaria and Baden-Württemberg drive recurring production schedules as EU Green Deal electrification timelines compress development cycles.
- Functional Testing:In-circuit, flying probe, and boundary scan verification protocols validate electrical performance across temperature and vibration specifications. Medical device OEMs in Denmark and Sweden require traceable test documentation for CE marking and MDR post-market surveillance obligations.
- Prototyping:Low-volume NPI runs bridge design validation to pilot production for Nordic IoT hardware startups.
- Supply Chain Management:Component sourcing, vendor-managed inventory, and logistics coordination services mitigate semiconductor availability constraints for Polish and Czech manufacturing zones.
PCB Assembly commands the established base. The steepest expansion runs through Functional Testing as regulatory documentation requirements intensify.
Industry Vertical:
Application-specific compliance regimes reshape procurement patterns across European electronics outsourcing.
- Automotive Components:Powertrain control modules, battery management systems, and ADAS sensor assemblies require AEC-Q100 qualified components and ISO 26262 functional safety processes. French and German OEM electrification roadmaps under EU Green Deal mandates pull volume toward specialized EMS partners with IATF 16949 certification.
- Medical Devices:Diagnostic imaging equipment, patient monitoring systems, and surgical robotics demand cleanroom manufacturing environments and biocompatibility testing under MDR and REACH substance restrictions. Norwegian and Swedish contract manufacturers anchor Nordic supply chains through CE-marked production.
- Telecommunications:5G infrastructure and industrial IoT gateway hardware drive embedded systems integration demand across Netherlands and German clusters.
- Consumer Electronics:White goods and wearable devices concentrate in lower-cost Polish assembly corridors serving Western European brands.
Automotive Components commands the established base. Medical Devices climbs the fastest as MDR compliance consolidates supplier relationships around certified European partners.
Technology:
Engineering maturity separates proven integration platforms from emerging firmware-hardware convergence domains.
- Embedded Systems:Microcontroller-based hardware with integrated firmware stacks operate across industrial temperature ranges and EMC compliance classes for German robotics OEMs. Co-design capabilities command premium pricing as automotive and logistics automation demand real-time control architectures.
- AI Integration:Edge inference accelerators and neural network-optimized processors require specialized thermal management and power delivery design. EU AI Act forthcoming conformity obligations will reshape procurement criteria for autonomous driving and predictive maintenance hardware.
- IoT Solutions:Sensor-to-cloud connectivity modules with wireless protocol stacks serve smart building and industrial monitoring applications.
- Robotics:Motor drive electronics and kinematic control systems support collaborative robot deployments across French automotive plants.
Embedded Systems commands the established base. AI Integration gains share fastest as EU AI Act certification requirements create first-mover differentiation.
End User:
Customer scale and technical sophistication determine service bundling and contract structures across European outsourcing relationships.
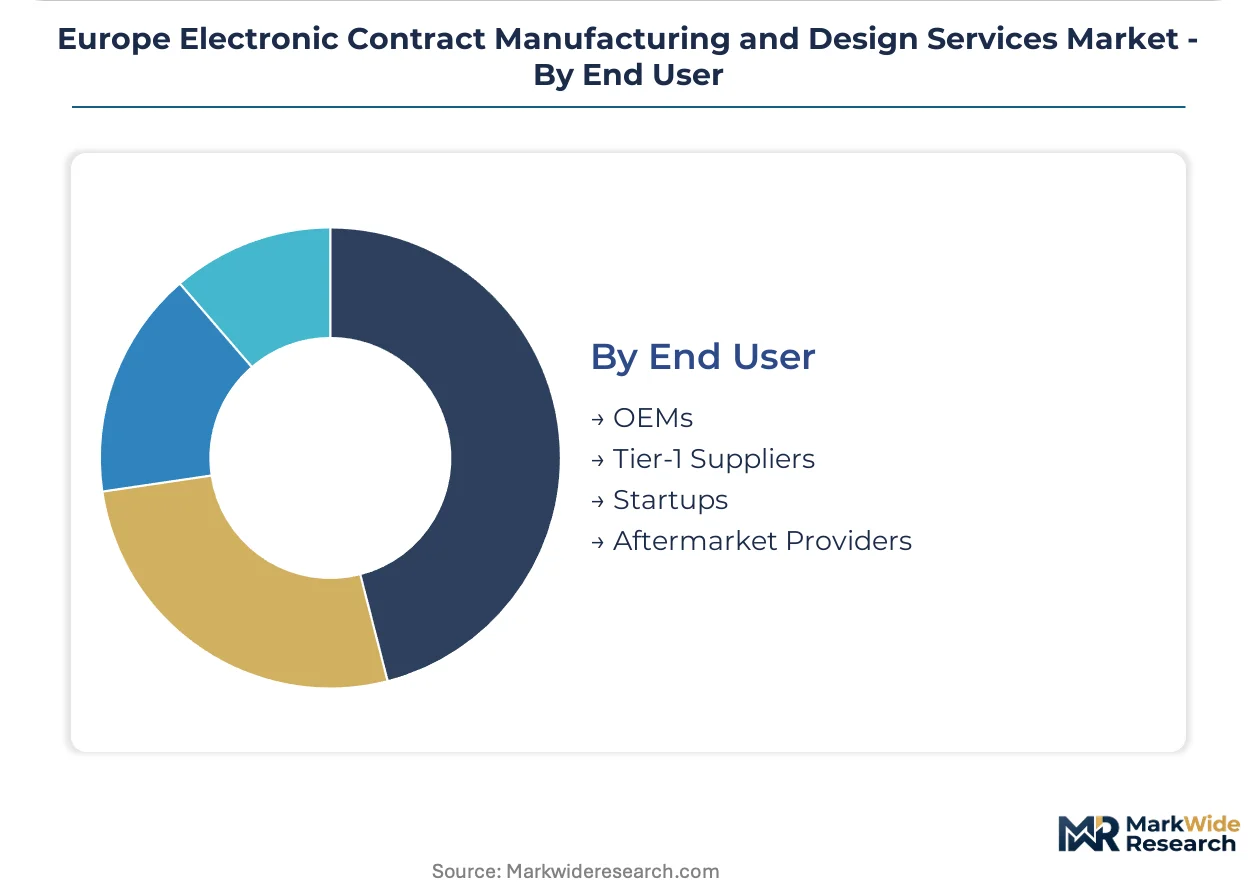
- Tier-1 Suppliers:Bosch, Continental, and Valeo-tier automotive component manufacturers demand captive capacity allocations and direct engineering collaboration for powertrain electrification programs. Long-term agreements with German EMS partners specify yield targets and traceability systems.
- OEMs:Siemens, Philips, and Ericsson-scale manufacturers consolidate vendor panels around full-lifecycle design-to-manufacture partnerships with integrated platform development agreements.
- Startups:Nordic medical device and industrial IoT ventures require flexible NPI pathways and design-for-manufacturing feedback loops.
- Aftermarket Providers:Repair and refurbishment services for industrial electronics concentrate in Eastern European cost-optimized zones.
Tier-1 Suppliers commands the established base. OEMs expands most quickly as procurement teams consolidate around integrated platform partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract manufacturers extract pricing premiums from automotive Tier-1s while Polish assembly corridors compete on cost for consumer electronics. This asymmetry structures procurement patterns across European electronics outsourcing.
Germany
Automotive electrification roadmaps under EU Green Deal mandates pull volume toward Bavarian and Baden-Württemberg industrial clusters. ECHA REACH substance restrictions force reformulation of solder pastes and conformal coatings. Munich and Stuttgart anchor powertrain control module production for Tier-1 suppliers seeking IATF 16949 certified partners.
Poland
Lower-cost manufacturing zones near German automotive clusters attract PCB assembly investment for white goods and industrial electronics. EU cohesion funds support technical workforce development in Silesia and Greater Poland. Wrocław and Poznań concentrate electromechanical integration facilities serving Western European OEMs.
Sweden
Medical device manufacturers consolidate supplier relationships around cleanroom-certified partners to satisfy EMA MDR compliance curves. CE marking and post-market surveillance obligations favor incumbent regional contract manufacturers. Stockholm and Gothenburg anchor Nordic supply chains for diagnostic imaging and surgical robotics.
France
Automotive OEMs expand outsourced electronics production to meet accelerated decarbonization timelines under EU Green Deal mandates. ANSM medical device regulations intersect with REACH substance restrictions for biocompatibility requirements. Paris-Saclay and Grenoble clusters concentrate ADAS sensor module development.
Netherlands
Telecommunications infrastructure and industrial IoT gateway hardware drive embedded systems integration demand across Randstad manufacturing corridors. CSRD supply chain disclosure mandates force contract manufacturers to document Scope 3 emissions. Eindhoven anchors 5G hardware platform development for European telecommunications OEMs.
Europe Electronic Contract Manufacturing and Design Services Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in a fragmented competitive structure. European electronics outsourcing organizes around three strategic archetypes: German automotive-focused Tier-1 captives, Nordic medical device cleanroom specialists, and pan-European scale players with telecommunications embedded systems capabilities. M&A activity concentrates on design service acquisitions, while capacity expansion targets Polish and Czech industrial zones near German demand clusters.
Among Germany-based fabricators, Zollner Elektronik AG exemplifies the automotive Tier-1 captive archetype through its Bavarian production footprint. Kitron ASA represents Nordic medical device supply chain anchoring with specialized cleanroom manufacturing capabilities. Flex Ltd. occupies a position as a pan-European scale player competing via embedded systems integration for telecommunications OEMs. These three companies illustrate the geographic and vertical specialization that structures competitive positioning across European contract manufacturing.
| Leading Market Players |
|---|
| Zollner Elektronik AG |
| Kitron ASA |
| Hon Hai Precision Industry Co. Ltd. (Foxconn) |
| Benchmark Electronics |
| Scanfil |
| Flex Ltd. |
| Cicor Management AG |
| Neways |
| Jabil Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in German automotive PCB assembly corridors drives Tier-1 suppliers toward multi-year capacity reservations, compressing spot-market availability and inflating configured-to-order premiums. Bavarian and Baden-Württemberg fabs run near-full utilization as EU Green Deal electrification mandates pull forward powertrain control module demand.
Pricing Analysis
The customization-premium spread separates standard PCB assembly contracts from embedded systems engagements requiring firmware-hardware co-design. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price differentiation intensifies as REACH substance restrictions force reformulation costs onto mid-tier suppliers. Automotive Tier-1s exhibit lowest price sensitivity due to captive capacity requirements, while consumer electronics OEMs concentrate in Polish economy-tier corridors.
Supply Chain Analysis
Zollner Elektronik AG, Kitron ASA, and Flex Ltd. anchor European contract manufacturing capacity across automotive, medical, and telecommunications verticals. German, Polish, and Czech Republic production zones draw from East Asian laminate and copper-clad substrate suppliers. Single-source vulnerability in advanced node semiconductor inputs rests on Taiwan and South Korea foundry concentration. Distribution runs through direct OEM-EMS relationships consolidated around full-lifecycle platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent European contract manufacturers face substitution pressure from vertically integrated automotive OEMs building captive electronics fabrication. Nearshoring alternatives in North Africa and Southeast Asia threaten regional cost advantages.
For Market Incumbents: Entrench automotive relationships through IATF 16949 certification investments and dedicated Bavarian capacity allocations. Consolidate Nordic medical device supply chains via cleanroom certification expansion in Sweden and Norway. Counter OEM vertical integration threats by embedding design-for-manufacturing engineers directly into Tier-1 development programs. For New Entrants and Emerging Players: Polish and Czech industrial zones near German automotive clusters represent the most penetrable entry point for PCB assembly specialists. Medical device startups in Denmark and Sweden offer white-space demand for flexible NPI pathways. Pursue telecommunications IoT gateway opportunities in Netherlands Randstad corridors through EMC compliance-first positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled embedded systems as EU AI Act conformity investments reshape design service procurement. Long-term viability favors design-capability acquisitions over pure-play assembly capacity. Monitor ECHA REACH substance list expansions as inflection signals for material-qualification cost escalations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Buildout | First-mover conformity capabilities differentiate design service providers for autonomous hardware. |
| Backward Integration into Substrate Supply | Captive laminate sourcing mitigates East Asian supply concentration risks for German PCB assemblers. |
| Cleanroom Capacity Expansion | Norwegian and Swedish MDR-certified facilities anchor premium medical device manufacturing relationships. |
| Design-for-Manufacturing Partnership | Embedded engineering teams at Tier-1 OEMs lock in multi-year platform development agreements. |
| Polish Industrial Zone Investment | Lower-cost corridors near German demand clusters capture consumer electronics assembly migration. |
Research Approach
The analysis maps PCB assembly, embedded systems integration, functional testing, and supply chain management segments, each validated through EMS procurement directors, Tier-1 supplier manufacturing heads, medical device regulatory affairs leads, and telecommunications OEM platform engineers. Primary interview findings triangulate against ECHA substance restriction databases, EU medical device registration filings, automotive production registration data, and EMS capacity utilization disclosures. Bottom-up service-type revenue estimates reconcile with top-down vertical demand projections.
Assumptions held fixed include EU Green Deal electrification mandate timelines, REACH substance restriction enforcement intensity, and EMA MDR compliance curve progression. Variables tested across the modeling period encompass semiconductor input cost trajectories, Polish-Czech labor cost inflation differentials, and EU AI Act implementation pacing. Segmentation dimensions cover service type, industry vertical, technology category, and end-user scale tier. CAGRs derive from volume-demand elasticity modeling against capacity expansion schedules and regulatory compliance cost pass-through rates.
Practitioners should monitor ECHA restricted substance list expansions, foundry capacity allocation announcements, and OEM captive fabrication investment disclosures for early signals of forecast revision. Semiconductor input cost volatility and geopolitical friction in East Asian substrate supply channels represent primary forecast risk factors. Quarterly review of EMS capacity utilization reports and Tier-1 supplier procurement contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Load Balancer Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Data Enrichment Solutions Market