

Mechanical Reciprocating Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Reciprocating Engine Market Insights
ISO 8178 emission certification cycles for reciprocating internal combustion engines is redrawing competitive access across marine and power generation supply chains. Caterpillar leverages its vertical integration into castings and fuel systems to control lead times on large-bore diesels. Cummins anchors its position through modular platform architectures that span 50 kW to 3.5 MW ratings. Wärtsilä differentiates via dual-fuel technology leadership in four-stroke medium-speed engines for LNG-powered vessels.
A mechanical reciprocating engine converts linear piston motion into rotary shaft output through a crankshaft mechanism, with bore diameters ranging from under 100 mm in automotive units to over 960 mm in low-speed two-stroke marine propulsion engines; its primary purpose is delivering reliable shaft power for propulsion, electrical generation, and heavy mobile equipment where torque density and fuel flexibility outweigh pure thermal efficiency. Four-stroke engines occupy the dominant revenue position across power generation and marine auxiliary applications due to their superior brake mean effective pressure and part-load fuel consumption profiles. Turbocharging technology commands the fastest expansion as single-stage and two-stage turbocharger adoption rises to meet IMO NOx Tier III limits without exhaust aftertreatment. Direct injection systems concentrate margin pools in the above-1 MW segment where high-pressure common rail precision justifies premium pricing over mechanical unit injectors.
EPA Tier 4 Final regulations in the United States mandate 90% NOx and particulate reductions from non-road engines above 560 kW, forcing redesigns of fuel injection and exhaust gas recirculation architectures. IMO 2020 sulfur caps and the EU Green Deal's Fit for 55 package are accelerating dual-fuel and methanol-ready engine development for European-flagged vessels and port power. Stakeholders must monitor carbon intensity indicator compliance costs and alternative fuel infrastructure buildout to time capital commitments on engine platforms with twenty-year service lives.
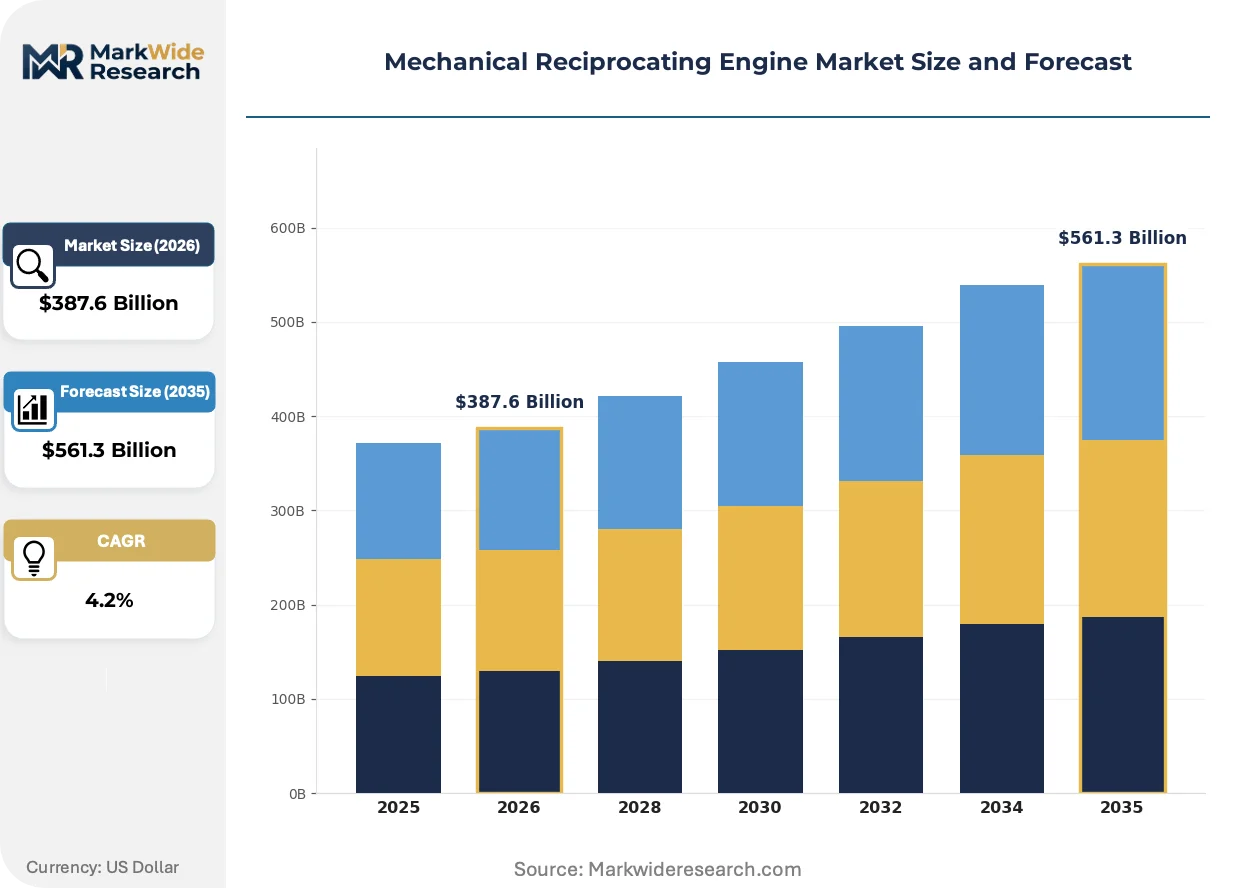
Market Dynamics
Dual-fuel architecture adoption is compressing the traditional diesel-gasoline dichotomy in marine and power generation applications, forcing platform redesigns around methanol and ammonia compatibility.
Growth Catalysts
- IMO NOx Tier III mandates:Marine operators in Chinese and German ports are accelerating engine replacement cycles to comply with nitrogen oxide limits in emission control areas.
- Port electrification infrastructure:Shore power requirements at Hamburg, Shanghai, and Rotterdam terminals are sustaining demand for auxiliary genset engines with rapid-start capabilities.
- Modular turbocharging:Two-stage turbocharger systems are enabling medium-speed engines to meet power density targets without exhaust aftertreatment hardware.
Market Restraints
- Steel and nodular iron casting shortages:Foundry capacity constraints in India and Germany are extending lead times for large-bore engine blocks and crankshafts.
- Dual-fuel premium cost structure:LNG-compatible fuel injection systems carry 25-40% hardware cost premiums over conventional diesel architectures at equivalent power ratings.
- Technical limitation in ammonia combustion:Nitrous oxide formation rates and lubricant compatibility remain unresolved for four-stroke medium-speed ammonia engines.
Strategic Opportunities
- EU Green Deal Fit for 55:Carbon intensity indicator compliance costs are creating aftermarket retrofit demand for engine control system upgrades in European-flagged vessels.
- Methanol bunkering infrastructure:Singapore and Antwerp terminal operators are piloting methanol supply chains that enable methanol-ready engine contracts.
- Remote diagnostics convergence:Integration of crankshaft torsional vibration monitoring with cloud-based predictive maintenance platforms is opening subscription revenue streams for engine OEMs.
Industry Challenges
- Combustion modeling expertise gap:Computational fluid dynamics specialists capable of optimizing alternative fuel injection profiles are concentrated at a handful of European technical universities.
- ISO 8178 certification timelines:Exhaust emission testing across all prescribed duty cycles requires 18-24 months for new engine families, compressing product launch windows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Reciprocating Engine Market Trends and Innovations
Alternative fuel combustion research is decomposing the century-old optimization around petroleum diesel, with development resources rotating toward hydrogen-derived carriers and synthetic e-fuels.
Two-stage turbocharging is decomposing the traditional trade-off between brake mean effective pressure and thermal efficiency in medium-speed engines. Power generation utilities in Germany and India are specifying these architectures for peaking plants requiring rapid load acceptance. The technology is decomposing the market for single-stage turbocharger retrofits by embedding intercooling and variable geometry within factory-delivered packages.
EPA Tier 4 Final and IMO 2020 sulfur regulations are compressing the viable fuel spectrum for non-road and marine engines. Engine manufacturers are redesigning fuel injection systems to handle ultra-low sulfur diesel and distillate alternatives without hardware modification. Chinese engine exporters targeting US construction equipment OEMs are investing in exhaust gas recirculation calibration facilities to maintain market access.
Power-by-the-hour contracting is displacing traditional engine sales in offshore vessel segments. Norwegian and UK North Sea operators are unbundling maintenance from capital expenditure, transferring operational risk to engine suppliers. This shift is most visible in platform supply vessel markets where utilization volatility makes fixed cost structures unsustainable.
Mechanical Reciprocating Engine Market Segmentation
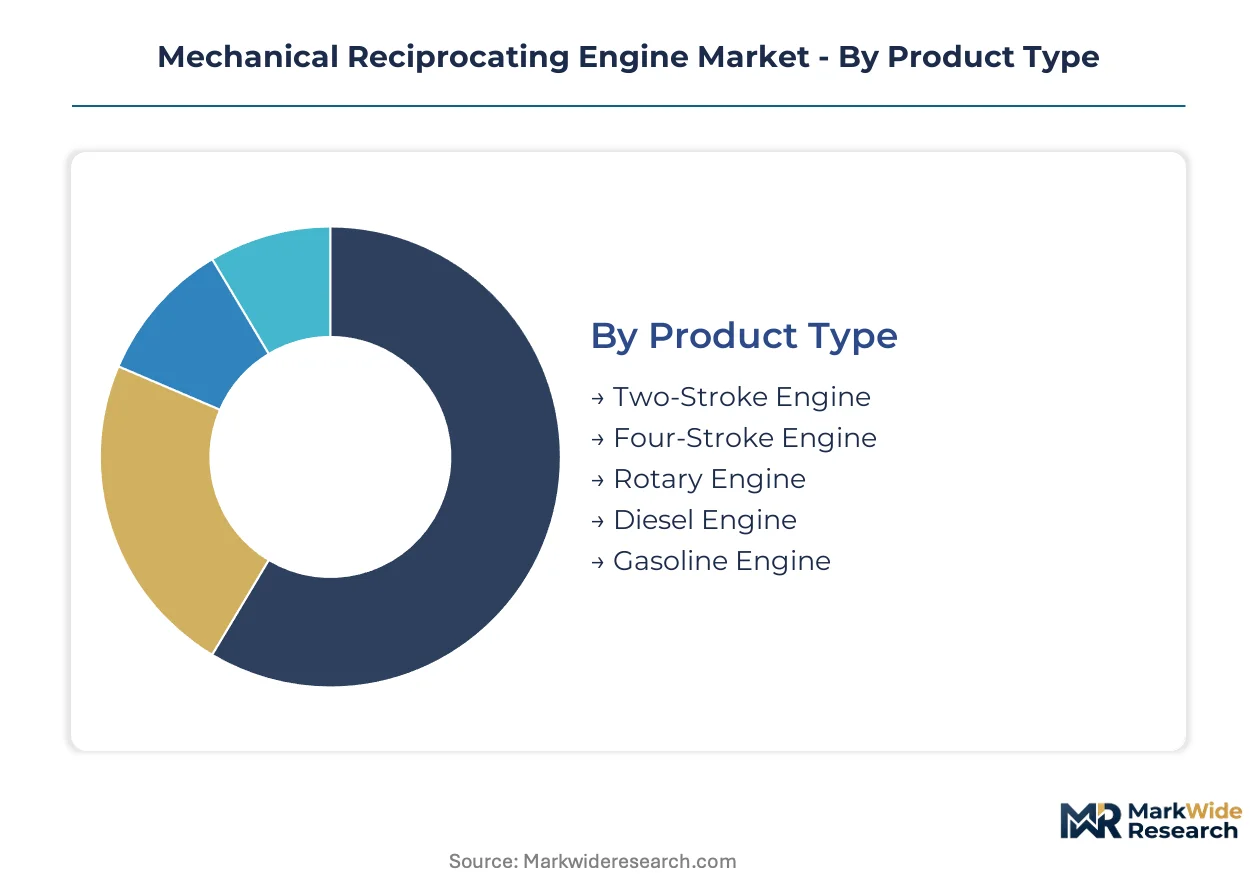
Segmentation in mechanical reciprocating engines reveals how regulatory pressure and fuel transition reshape procurement priorities across power classes. Buyers now specify platforms based on emission zone compliance rather than pure performance metrics.
Product Type:
Electric drivetrains and battery-hybrid systems exert substitution pressure most intensely on small-displacement gasoline architectures, while large-bore marine and stationary engines retain insulation from electrification.
- Four-Stroke Engine:Dominant architecture across medium-speed marine auxiliary and power generation applications. Brake mean effective pressure advantages and superior part-load fuel consumption drive specification at Hamburg and Shanghai port facilities.
- Two-Stroke Engine:Low-speed marine propulsion engines with bore diameters exceeding 960 mm deliver unmatched thermal efficiency for deep-sea cargo vessels. MAN Energy Solutions and WinGD control technology licensing for crosshead designs.
- Rotary Engine:Compact power density suits unmanned aerial systems and range-extender hybrid applications where vibration isolation matters.
- Diesel Engine:Compression-ignition architectures anchor heavy mobile equipment and emergency genset markets requiring fuel flexibility.
- Gasoline Engine:Spark-ignition designs concentrate in light commercial equipment below 75 kW where first cost sensitivity dominates.
Four-stroke engines anchor the volume base while two-stroke marine designs gain share at the steepest rate amid container fleet renewal cycles.
Technology:
Cost tier stratification separates premium architectures with factory-integrated emission compliance from retrofit-dependent legacy installations.
- Turbocharging:Single-stage and two-stage systems enable IMO NOx Tier III compliance without selective catalytic reduction hardware. Wärtsilä and Caterpillar embed variable geometry and intercooling in factory packages for German and Indian peaking plants.
- Direct Injection:High-pressure common rail systems above 1 MW deliver precision fuel metering that justifies hardware premiums over mechanical unit injectors in mining and rail applications.
- Variable Valve Timing:Cam phasing technology improves part-load efficiency in variable-speed generator sets.
- EFI:Electronic fuel injection replaces carburetion in small engines serving construction equipment rental fleets.
- Cylinder Deactivation:Modular firing strategies reduce fuel consumption in lightly loaded prime power applications.
Turbocharging commands the steepest expansion trajectory while direct injection captures the highest margin pools in above-1 MW contracts.
Application:
Volume concentration patterns track industrial cluster geography and port infrastructure investment cycles across coastal manufacturing belts.
- Marine Vessels:Dual-fuel medium-speed engines dominate newbuild contracts for LNG-powered container ships and tankers. IMO 2020 sulfur caps and EU Green Deal carbon intensity indicators drive replacement at Rotterdam and Singapore terminals.
- Power Generation:Peaking plants and distributed generation assets in Germany and India specify rapid-start medium-speed diesels for grid stabilization.
- Construction Equipment:EPA Tier 4 Final compliance forces exhaust gas recirculation and diesel particulate filter integration in excavators above 560 kW.
- Agricultural Machinery:Harvester and tractor engines balance emission compliance with field durability requirements.
- Material Handling:Forklift and port crane engines prioritize transient response for load-lifting cycles.
Marine vessels generate the highest unit values while power generation delivers the most stable recurring demand.
End User:
Customer type determines procurement structure, with capital-intensive operators favoring power-by-the-hour contracts and price-sensitive buyers prioritizing first acquisition cost.
- OEMs:Equipment manufacturers specify engine platforms across multi-year product cycles, locking in fuel system and aftertreatment architectures. Caterpillar and Cummins integrate vertically into castings and electronics to secure supply.
- Power Houses:Utility and independent power producers negotiate long-term service agreements tied to availability guarantees.
- Aftermarket Repair Shops:Independent service networks handle mid-life overhauls and emission retrofit installations.
- Industrial Manufacturers:Captive power users prioritize fuel flexibility for grid-isolated operations.
- Equipment Rental Firms:Fleet operators balance utilization rates against maintenance cost predictability.
OEMs anchor the volume base while power houses expand fastest through unbundled service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO 2020 sulfur caps and EU Green Deal carbon intensity indicators are accelerating engine replacement cycles across major port economies, concentrating procurement in industrial clusters with established bunkering infrastructure and emission control zones.
China
Shanghai and Ningbo port authorities are mandating shore power compatibility for auxiliary gensets on container vessels calling at Yangtze River Delta terminals. The Ministry of Ecology and Environment enforces domestic emission control area standards that mirror IMO NOx Tier III limits. Jiangsu and Shandong provinces host foundry clusters producing large-bore engine blocks for both domestic shipyards and export markets.
Germany
Hamburg terminal operators require rapid-start medium-speed diesels for grid stabilization as renewable penetration destabilizes northern Germany's electricity network. The EU Green Deal Fit for 55 package imposes carbon intensity indicator compliance costs on European-flagged vessels. MAN Energy Solutions and MTU Friedrichshafen anchor engine development in Bavaria and Baden-Württemberg, supplying dual-fuel architectures for methanol-ready newbuilds.
United States
Gulf Coast petrochemical complexes and Great Lakes shipping corridors sustain demand for EPA Tier 4 Final compliant engines above 560 kW. The Environmental Protection Agency mandates 90% NOx and particulate reductions from non-road engines, forcing exhaust gas recirculation redesigns. Caterpillar's manufacturing presence in Illinois and Indiana supports construction equipment OEMs with vertically integrated casting and fuel system production.
India
Captive power users in Gujarat and Maharashtra specify medium-speed diesels for grid-isolated industrial operations where electricity reliability remains erratic. The Central Electricity Authority promotes distributed generation assets to reduce transmission losses across western and southern states. Foundry capacity constraints in Tamil Nadu and Karnataka are extending lead times for nodular iron crankshafts and engine blocks.
Singapore
The Maritime and Port Authority pilots methanol bunkering infrastructure to enable methanol-ready engine contracts for container lines transitioning away from heavy fuel oil. PSA International's terminal investments sustain demand for auxiliary gensets with rapid-start capabilities. Jurong Island's petrochemical cluster generates replacement demand for peaking plant engines as gas turbine maintenance cycles compress.
Mechanical Reciprocating Engine Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and captive manufacturing depth. The market structures around three tiers: integrated conglomerates controlling casting through final assembly, modular platform specialists spanning power ratings, and dual-fuel technology licensors. Consolidation concentrates in marine propulsion where crosshead engine designs require billion-dollar foundry investments. Dominant competitive moves include backward integration into fuel injection systems and strategic partnerships around alternative fuel combustion research.
Among integrated engine manufacturers, Caterpillar, Cummins, and Wärtsilä occupy positions exemplifying distinct competitive archetypes. Caterpillar represents vertical manufacturing depth with in-house production of castings and electronics. Cummins anchors the modular platform approach spanning dispersed power ratings through common architectural elements. Wärtsilä exemplifies dual-fuel technology leadership in four-stroke medium-speed segments. These three sit within a competitive set where technology licensing from MAN Energy Solutions and WinGD shapes low-speed marine propulsion, while MTU Friedrichshafen and Deutz occupy specialized positions in premium auxiliary power.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins |
| Wärtsilä |
| MAN Energy Solutions |
| Rolls-Royce Power Systems |
| General Electric |
| Mitsubishi Heavy Industries |
| MTU Friedrichshafen |
| Deutz |
| Others |
Pricing and Supply Chain Analysis
ISO 8178 emission certification cycles gate both supplier qualification and price differentiation simultaneously, forcing foundries and fuel system manufacturers to absorb eighteen-month validation timelines while OEMs extract premiums for pre-certified architectures over retrofit-dependent alternatives.
Pricing Analysis
Certification level (ISO 8178/EPA Tier 4/IMO Tier III-grade) creates the primary spread across contract tiers, with factory-delivered compliance packages commanding hardware premiums over field-retrofitted installations. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects after-sales bundling intensity and fuel injection precision grades. Cost compression in the economy tier intensifies because Chinese exporters are absorbing exhaust gas recirculation calibration investments to maintain US market access. Construction equipment OEMs exhibit the highest price sensitivity due to first-cost procurement structures, while marine operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Inventory cycles for large-bore crankshafts and nodular iron engine blocks now stretch well beyond traditional planning horizons, with German and Indian foundries operating at effective capacity ceilings. Supply concentrates in China, Germany, and India for castings, while high-pressure common rail fuel systems draw from specialized machining clusters in Japan and Germany. Single-source vulnerability around turbocharger variable geometry mechanisms creates chokepoint exposure when semiconductor content in actuator controls faces allocation constraints. Distribution runs through OEM captive networks for newbuild contracts, while independent aftermarket channels handle mid-life overhauls and emission retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across emission control zones is fragmenting procurement into niche specifications, creating entry points for specialists who can anchor platform architectures around methanol-ready or ammonia-compatible combustion systems without the legacy diesel optimization burden.
For Market Incumbents: Fortify backward integration into fuel injection electronics and casting capacity to defend against lead time volatility threatening availability guarantees. MAN Energy Solutions and WinGD licensing structures already compress margins for crosshead engine technology; deepen captive control over crankshaft machining to offset this pressure. Prioritize dual-fuel platform standardization across marine and power generation ratings to amortize R&D across higher volumes. For New Entrants and Emerging Players: Anchor in methanol-ready auxiliary genset niches at Singapore and Antwerp terminals where bunkering infrastructure pilots are outpacing incumbent platform refresh cycles. Target port electrification retrofit demand for rapid-start medium-speed diesels where established suppliers face ISO 8178 recertification backlogs. Pursue power-by-the-hour contracting structures with North Sea offshore vessel operators to unbundle capital barriers. For Investors and Strategic Acquirers: IMO NOx Tier III enforcement across Chinese and German emission control areas reshapes the acquisition landscape toward dual-fuel technology licensers and predictive diagnostics platforms. Five-to-ten-year viability hinges on alternative fuel combustion expertise concentration at European technical universities. Monitor methanol bunkering throughput at Singapore and Rotterdam as the inflection signal for methanol-ready engine contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Standardization | Enables MAN Energy Solutions and Wärtsilä to amortize methanol combustion R&D across marine and stationary ratings. |
| Backward Integration into Castings | Caterpillar's in-house nodular iron production insulates against German and Indian foundry capacity constraints. |
| Predictive Diagnostics Convergence | Cloud-based crankshaft torsional vibration monitoring opens subscription revenue streams for engine OEMs serving offshore fleets. |
| Alternative Fuel Combustion Licensing | WinGD crosshead technology agreements transfer ammonia-ready architecture risk to shipyard newbuild contracts. |
| Emission Retrofit Service Networks | Independent aftermarket shops capture EU Green Deal carbon intensity indicator upgrade demand from European-flagged vessels. |
Research Methodology
Desk research of customs trade databases, EPA certification filings, and IMO marine engine registration records preceded structured interviews with marine superintendents, power plant engineering managers, foundry operations directors, and fuel injection system procurement leads. Primary fieldwork with Hamburg and Singapore terminal operators validated shore power compatibility specifications and auxiliary genset replacement cycles. Secondary sources included Lloyd's Register engine order databases, Central Electricity Authority distributed generation statistics, and SEC filings from integrated engine manufacturers. Bottom-up unit economics and top-down industrial cluster demand estimates underwent triangulation against disclosed order backlogs.
Variance decomposition across product type, technology tier, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by disclosed contract values for above-1 MW installations. Modeled inputs incorporated IMO emission control area expansion schedules, foundry capacity utilization surveys from German and Indian trade associations, and dual-fuel premium cost structures from equipment procurement tenders.
Material uncertainties — steel and nodular iron casting allocation shocks, ammonia combustion chemistry resolution timelines, and carbon intensity indicator enforcement stringency variations — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.