
 Motorcycle Start Stop Systems Market | 2026-2036
Motorcycle Start Stop Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Start Stop Systems Market Foresight
OEM-grade idle-stop modules is rotating toward higher thermal-cycle durability and CAN-bus integration standards. Robert Bosch leverages its powertrain electronics heritage to anchor European premium motorcycle programs. Denso Corporation sustains Japanese kei-bike and scooter supply relationships through dedicated starter-motor foundries. Hero Motocorp dominates India's 100-125cc commuter segment with indigenized start-stop controllers calibrated for stop-go traffic patterns.
Motorcycle start stop systems combine integrated starter-generators, engine control units, and voltage-stabilized battery management to eliminate fuel consumption during idle phases while maintaining electrical accessory operation; typical systems achieve restart latency below 0.35 seconds through permanent-magnet synchronous motor designs. Fuel injection technology leads installed base volume due to mandatory homologation with engine management electronics, while hybrid systems represent the fastest-growing category as mild-hybrid architectures penetrate 150-300cc displacement tiers. Aftermarket solutions occupy narrower margin pools constrained by warranty voidance risks and calibration complexity, whereas OEM components capture value through bundled telematics integration.
India's CEA enforces start-stop readiness as part of BS-VI idle emission test cycles, while the EU F-Gas Regulation shapes refrigerant-compatible system designs for thermal management modules. Japan's METI subsidizes next-generation starter motor development under automotive component efficiency programs. Stakeholders must monitor battery chemistry transitions from lead-acid to lithium-ion formats and assess whether solid-state cell commercialization redefines system voltage architectures.
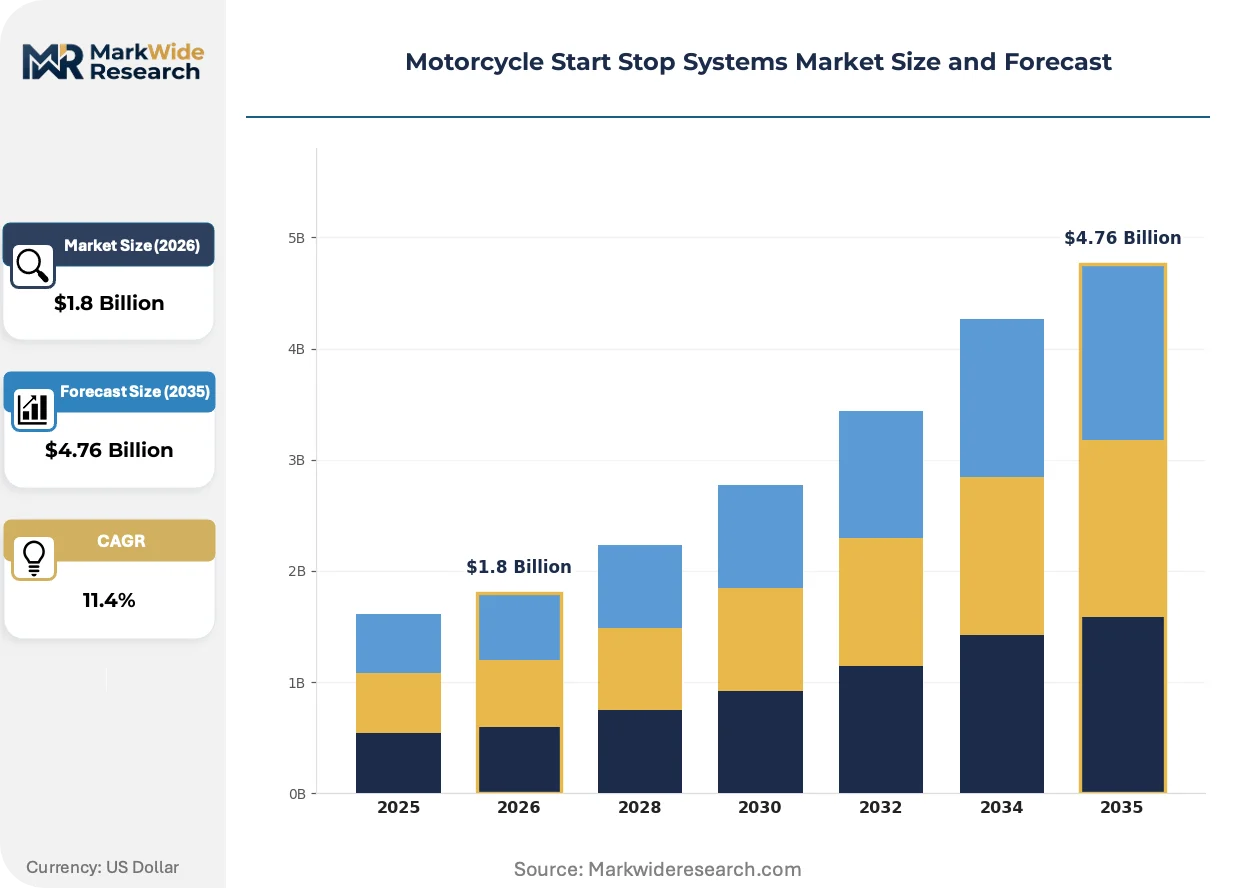
Market Dynamics
India's Bharat Stage VI emission norms have compressed idle-stop technology deployment timelines, forcing motorcycle OEMs to redesign starter-generator architectures and battery management systems for 100-125cc commuter platforms where production volumes concentrate.
Growth Catalysts
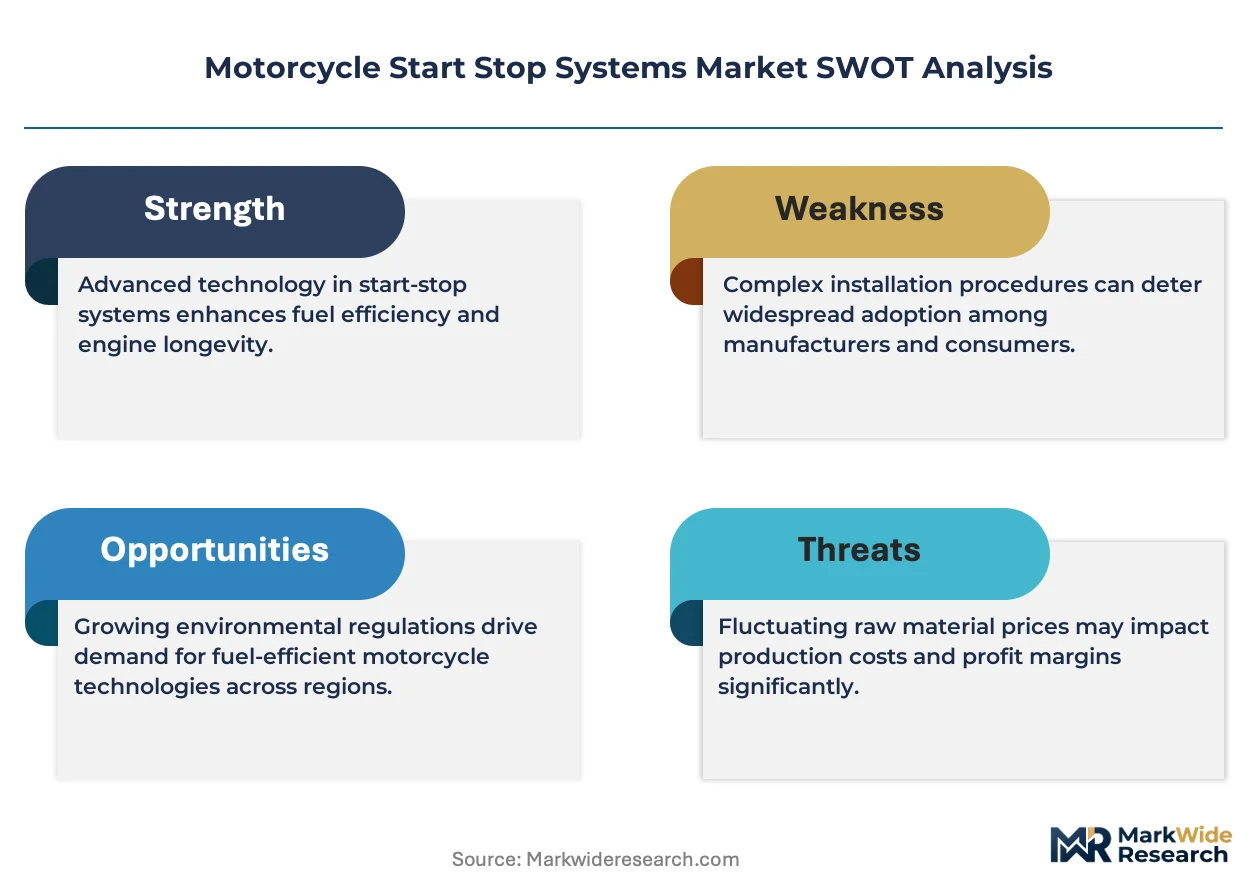
- CEA idle emission test cycles:India's Central Electricity Authority mandates start-stop readiness as part of BS-VI certification, creating regulatory pull-through for integrated starter-generator modules.
- Permanent-magnet synchronous motor designs:Advances in rare-earth magnet topology and thermal management enable restart latency below 0.35 seconds, eliminating rider friction in stop-go traffic.
- Commuter segment volume concentration:India's 100-125cc motorcycle production dominates global unit economics, amortizing start-stop system development costs across millions of annual fitments.
Market Restraints
- Lithium-ion battery cost volatility:Cell chemistry transitions from lead-acid formats face raw material price swings in cobalt and nickel supply chains, pressuring bill-of-materials targets.
- Starter motor foundry concentration:Japanese kei-bike and scooter supply relationships consolidate production in dedicated manufacturing clusters, limiting second-source options for European and Indian OEMs.
- EU F-Gas refrigerant compatibility:Thermal management module designs must accommodate evolving refrigerant standards, adding validation cycles and homologation complexity.
Strategic Opportunities
- 150-300cc mild-hybrid tier:Hybrid system architectures penetrate mid-displacement motorcycles, opening white space between pure combustion and full-electric powertrains.
- Telematics bundling:OEM components capture incremental value through integrated vehicle connectivity, differentiating against aftermarket solutions constrained by warranty voidance risks.
- METI efficiency subsidies:Japan's Ministry of Economy, Trade and Industry funds next-generation starter motor development, accelerating technology maturation for export markets.
Industry Challenges
- CAN-bus integration skill scarcity:Embedded software engineering for powertrain electronics lags demand, stretching development timelines for voltage-stabilized battery management systems.
- Calibration complexity:Idle-stop controllers require traffic-pattern-specific tuning for stop-go environments, demanding localized validation fleets and extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Start Stop Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fuel Injection, Electric Starter, Hybrid Systems, Ignition Systems Product Type: Integrated Systems, Aftermarket Solutions, OEM Components, Performance Kits End User: Motorcycle Manufacturers, Custom Builders, Maintenance Service Providers, Fleet Operators Application: Urban Commuting, Long-Distance Touring, Off-Road Riding, Racing |
| Companies Covered | Hero Motocorp, Honda Motor, Yamaha Motor, Shindengen Electric Manufacturing, Robert Bosch, SKF, TE Connectivity, Denso Corporation, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Start Stop Systems Market Shifts & Advancements
Technology trajectories in motorcycle start-stop systems center on thermal-cycle durability improvements, voltage architecture transitions, and the convergence of powertrain electronics with vehicle connectivity platforms.
Integrated starter-generator hardware is decomposing discrete component boundaries as permanent-magnet synchronous motors merge with engine control units and battery management systems into unified power electronics modules. Premium motorcycle programs in Europe adopt these consolidated architectures first, driven by packaging constraints and weight reduction targets. The technology is decomposing traditional tiered supplier relationships as OEMs demand single-source accountability for restart performance.
India's CEA enforces start-stop readiness through BS-VI idle emission test cycles that measure real-world fuel savings during standardized driving patterns. Motorcycle manufacturers must demonstrate system durability across thermal cycling profiles before homologation approval. The commuter segment faces the steepest compliance curve as volume producers race to retrofit indigenized controllers for stop-go traffic calibration.
Fleet operators and commuter buyers now prioritize total cost of ownership metrics over upfront system pricing, compressing evaluation cycles for fuel-saving technologies. Traditional distribution through independent dealers loses ground to direct OEM channel relationships that bundle telematics and extended warranty coverage. This behavioral pivot concentrates in India's urban corridors where fuel price sensitivity and traffic density maximize idle-stop returns.
Motorcycle Start Stop Systems Market Segmentation
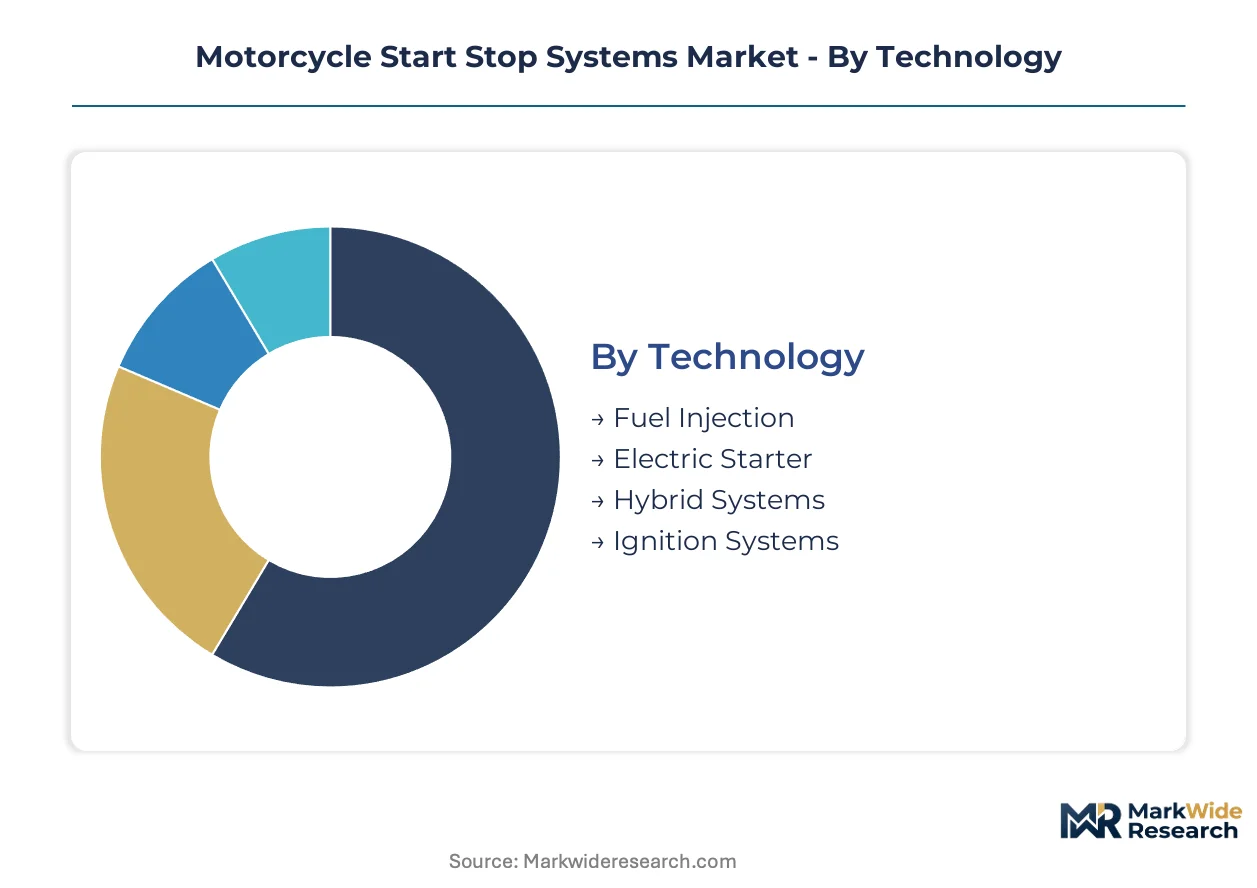
Motorcycle start-stop system segmentation reveals how technology maturity, supply chain position, and end-use intensity fragment margin capture across the value chain. Understanding these divisions exposes where component suppliers can defend pricing power versus where commoditization pressures concentrate.
Technology:
Margin pools concentrate in integrated powertrain electronics where restart latency performance commands premium positioning against discrete component alternatives.
- Fuel Injection:Electronic fuel injection systems incorporate idle-stop logic through shared engine control units, leveraging mandatory BS-VI homologation to bundle functionality without standalone hardware costs. India's commuter segment dominates fitment volumes as OEMs exploit existing ECU architectures to meet CEA emission test cycles.
- Hybrid Systems:Mild-hybrid architectures combining integrated starter-generators with lithium-ion battery packs enable regenerative braking and extended electric-only operation. Demand concentrates in Europe's premium motorcycle tier where 150-300cc displacement categories adopt F-Gas-compliant thermal management for EU regulatory alignment.
- Electric Starter:Conventional starter motor designs serve cost-sensitive platforms where standalone idle-stop modules prove uneconomical.
- Ignition Systems:Spark timing optimization provides rudimentary fuel cut-off during deceleration without full restart capability.
Fuel Injection holds installed capacity across mass-market production. Hybrid Systems are rotating up the share rankings as displacement tiers migrate toward electrified architectures.
Product Type:
Volume economics favor bundled OEM supply relationships over fragmented aftermarket channels where warranty voidance risks constrain price realization.
- OEM Components:Factory-integrated starter-generator modules, voltage-stabilized battery management systems, and CAN-bus-enabled control units ship directly to motorcycle assembly plants. India's Hero Motocorp and comparable volume producers specify indigenized controllers calibrated for stop-go traffic patterns, amortizing development costs across millions of annual fitments.
- Integrated Systems:Unified power electronics modules merging starter motors, ECUs, and battery management into single-source accountability architectures. European premium programs adopt these first driven by packaging constraints and telematics bundling opportunities.
- Aftermarket Solutions:Retrofit kits face narrower margin pools constrained by calibration complexity and dealer warranty limitations.
- Performance Kits:Racing-oriented upgrades prioritize restart speed over fuel economy, serving niche displacement categories.
OEM Components dominate current revenue concentration. Integrated Systems are climbing the fastest as supplier consolidation accelerates.
End User:
Procurement authority fragments across direct manufacturing relationships, specialized customization channels, and service-based maintenance networks with diverging technical requirements.
- Motorcycle Manufacturers:Tier-one OEMs specify system architectures during platform development, locking in multi-year supply agreements for starter-generator foundries and powertrain electronics. India's 100-125cc commuter producers drive the steepest volume concentration.
- Fleet Operators:Urban delivery and shared mobility providers prioritize total cost of ownership metrics, compressing evaluation cycles for fuel-saving technologies in high-idle operating environments.
- Custom Builders:Low-volume specialty fabricators demand modular retrofit compatibility over integrated designs.
- Maintenance Service Providers:Dealer networks face technical skill scarcity for CAN-bus integration and traffic-pattern-specific calibration.
Motorcycle Manufacturers retain procurement dominance. Fleet Operators are gaining share fastest as commercial mobility electrification accelerates.
Application:
Traffic density and stop frequency determine return-on-investment calculus, concentrating technology deployment in urban corridors where idle time fractions maximize fuel savings.
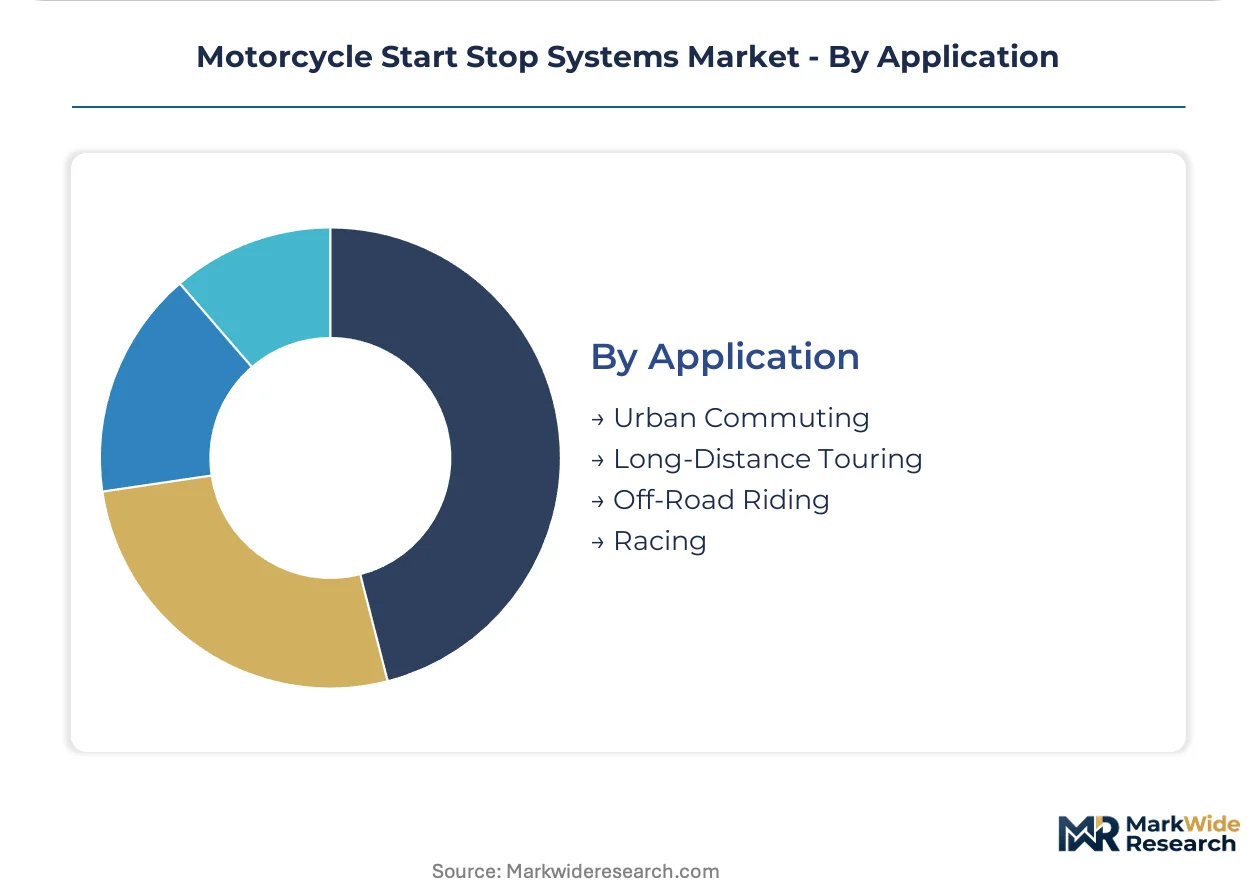
- Urban Commuting:Stop-go traffic patterns in India's metropolitan corridors generate the highest idle-stop cycle frequency, validating system durability through thermal cycling profiles and demonstrating measurable fuel economy gains to price-sensitive buyers.
- Long-Distance Touring:Highway-dominant usage profiles reduce idle-stop activation frequency, limiting value proposition clarity for continuous-operation powertrains.
- Off-Road Riding:Terrain-variable conditions demand robust restart performance across incline angles and temperature extremes.
- Racing:Competition regulations and weight minimization priorities conflict with idle-stop hardware mass penalties.
Urban Commuting anchors current fitment decisions. Long-Distance Touring shows steepest expansion trajectory as mild-hybrid touring platforms enter development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in motorcycle start-stop systems reveal concentrated manufacturing in India and Japan against net-import demand across Europe and North America. Component trade flows track closely to OEM assembly plant locations and domestic emission regulation stringency.
India
Hero Motocorp's 100-125cc commuter production drives integrated starter-generator demand across millions of annual fitments. The CEA mandates start-stop readiness through BS-VI idle emission test cycles, compressing technology deployment timelines for volume producers. Manufacturing clusters in Gurugram and Chennai anchor indigenized controller calibration for stop-go traffic patterns.
Japan
Kei-bike and scooter supply relationships sustain dedicated starter-motor foundry operations serving domestic OEM programs. METI subsidizes next-generation starter motor development under automotive component efficiency programs, accelerating technology maturation for export markets. Industrial concentration in Aichi Prefecture links Denso Corporation's powertrain electronics heritage to kei-vehicle platform integration.
Germany
Premium motorcycle programs adopt consolidated power electronics modules driven by packaging constraints and EU F-Gas refrigerant compatibility requirements. Robert Bosch leverages powertrain electronics heritage to anchor European tier-one supply relationships. Manufacturing in Stuttgart and Nuremberg regions supplies CAN-bus-enabled control units with telematics bundling capabilities.
United States
Harley-Davidson and Indian Motorcycle specifications pull high-displacement starter-generator modules through tier-one automotive supplier channels. EPA fuel economy standards shape idle-stop feature packaging across touring and cruiser segments. Midwest industrial corridors in Wisconsin and Minnesota concentrate final assembly with component sourcing from Mexican maquiladora operations.
China
Domestic motorcycle OEMs accelerate start-stop adoption under dual carbon goals and provincial emission enforcement in Beijing-Tianjin-Hebei and Yangtze River Delta regions. MIIT standards for fuel injection systems create regulatory alignment with idle-stop functionality. Chongqing's motorcycle manufacturing hub concentrates volume production of 150-300cc displacement categories migrating toward mild-hybrid architectures.
Motorcycle Start Stop Systems Market Competitive Landscape
Concentration sits with diversified automotive electronics suppliers holding powertrain heritage across multiple vehicle categories. The supplier base organizes into three functional tiers: integrated powertrain module specialists, discrete component foundries, and telematics-integrated platform providers. Tier-one relationships lock in through multi-year OEM supply agreements spanning starter-generator architectures and voltage-stabilized battery management systems. Competitive moves center on backward integration into rare-earth magnet supply chains and strategic partnerships for lithium-ion cell sourcing.
Within the integrated electronics tier, Robert Bosch and Denso Corporation exemplify archetypes of automotive powertrain heritage extending into motorcycle-specific applications. Continental occupies a position bridging European premium programs with scalable controller platforms. Hero Motocorp represents the OEM-captive integration model, indigenizing start-stop controllers for domestic commuter volume production. These anchors illustrate how supplier consolidation accelerates as OEMs demand single-source accountability for restart performance and thermal-cycle durability validation.
| Leading Market Players |
|---|
| Hero Motocorp |
| Honda Motor |
| Yamaha Motor |
| Shindengen Electric Manufacturing |
| Robert Bosch |
| SKF |
| TE Connectivity |
| Denso Corporation |
| Continental |
| Others |
Supply & Pricing Matrix
Lithium-ion battery chemistry substitution for lead-acid formats is redrawing supply geography toward East Asian cell production centers while compressing pricing economics for integrated starter-generator modules across India's commuter segment.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Motorcycle Start Stop Systems Market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under CEA BS-VI idle emission test cycles and volume scale commitments from Hero Motocorp and comparable volume producers. Pricing pressure stems from cobalt and nickel raw material volatility in lithium-ion supply chains, squeezing bill-of-materials targets for mid-tier integrated systems. Fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny, while European premium motorcycle programs show lowest sensitivity given packaging constraint premiums.
Supply Chain Analysis
Inventory cycles for rare-earth magnet and lithium-ion cell inputs extend lead times for permanent-magnet synchronous motor foundries serving tier-one OEM programs. Manufacturing concentrates in India, Japan, and China, with Denso Corporation's Aichi Prefecture operations and Chongqing's motorcycle hub anchoring regional supply clusters. Raw material dependencies center on neodymium-iron-boron magnets, cobalt-nickel-manganese cathode chemistries, and copper winding stock. Single-source vulnerability in Japanese kei-bike starter-motor foundries limits second-source flexibility for European and Indian OEMs. Distribution runs through direct OEM channel relationships that bundle telematics and extended warranty coverage, displacing independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Motorcycle Start Stop Systems Market sits at a regulatory-driven disruption inflection as India's CEA BS-VI emission mandates force technology deployment across 100-125cc commuter platforms where volume economics concentrate.
For Market Incumbents: Secure backward integration into rare-earth magnet supply chains to defend margin position against cobalt-nickel price volatility in lithium-ion battery architectures. Lock in multi-year OEM supply agreements spanning starter-generator foundries and CAN-bus-enabled control units to preempt emerging telematics-integrated platform providers from capturing telematics bundling value.
For New Entrants and Emerging Players: Anchor in India's 150-300cc mild-hybrid tier where displacement migration creates white space between pure combustion and full-electric powertrains. Target fleet operator procurement channels with outcome-based fuel savings validation protocols that compress evaluation cycles for high-idle urban delivery applications.
For Investors and Strategic Acquirers: The market sits at an early-commercialization phase that favors integrated powertrain module specialists with demonstrated thermal-cycle durability validation. Long-term viability hinges on single-source accountability architectures consolidating starter motors, ECUs, and battery management systems. Watch solid-state cell commercialization timelines as the signal indicating voltage architecture transitions that redefine system design specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captures upstream margin from neodymium-iron-boron price volatility affecting permanent-magnet synchronous motor costs. |
| CAN-Bus Integration Skill Development | Addresses embedded software engineering scarcity stretching voltage-stabilized battery management system timelines. |
| Telematics Bundling Platform Launch | Differentiates OEM components against aftermarket solutions constrained by warranty voidance risks in fleet channels. |
| Traffic-Pattern-Specific Calibration Investment | Enables localized validation fleet deployment for stop-go traffic optimization in India's metropolitan corridors. |
| Lithium-Ion Cell Sourcing Partnership | Secures cobalt-nickel-manganese chemistry supply for hybrid system architectures penetrating 150-300cc tiers. |
Research Methodology
Desk research of customs trade data, MIIT fuel injection system filings, and vehicle production databases preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operator maintenance directors. Primary fieldwork captured calibration complexity constraints and CAN-bus integration skill scarcity through direct stakeholder dialogue. Secondary validation drew from IHS Markit registration data, CEA BS-VI certification records, and METI efficiency program disclosures. Bottom-up unit economics triangulated against top-down market sizing across technology, product type, end user, and application segmentation dimensions.
Variance decomposition across volume and value outputs reflects analytical framework sensitivity to displacement tier migration patterns and regulatory enforcement intensity throughout the forecast period. Segmentation modeling incorporated technology maturity curves, propulsion architecture transitions, content per vehicle trajectories, OEM tier stratification, and regional production cluster dynamics. CAGRs derived from fitted growth curves calibrated to historical fitment rate trajectories and projected BS-VI compliance deadlines. Industry-specific inputs included thermal-cycle durability test protocols and lithium-ion cell chemistry transition timelines.
Material uncertainties — battery chemistry cost volatility, rare-earth export restriction escalations, and embedded software engineering labor market tightness — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding CEA enforcement consistency and METI subsidy continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market