
 Hill-Start Assist System Market | 2026-2036
Hill-Start Assist System Market Size, Share, and Industry Trends Forecast 2026-2036
Hill-Start Assist System Market Foresight
Multi-source procurement is restructuring supply relationships across the hill-start assist system value chain. Robert Bosch GmbH leverages its integrated sensor-actuator platforms to dominate hydraulic and electric system categories. Continental AG anchors European OEM programs through its brake-control module expertise. ZF Friedrichshafen AG competes on mechatronic integration, bundling hill-start assist with transmission control systems for factory-installed applications.
A hill-start assist system is an active vehicle safety mechanism that temporarily maintains brake pressure on inclined surfaces, typically employing wheel-speed sensors, inclinometers, and electronic control units to prevent rollback during throttle engagement. The technology serves commercial and passenger vehicle operators by reducing clutch wear and collision risk on gradients. Passenger vehicles occupy the largest product type segment, though electric vehicles represent the fastest-growing category as regenerative braking architectures demand tighter integration with torque management. Factory-installed systems capture the dominant installation share, while aftermarket providers face margin compression from calibration complexity and proprietary diagnostic requirements.
The EU General Safety Regulation, NHTSA Federal Motor Vehicle Safety Standards, and China's GB/T vehicle safety standards collectively mandate or incentivize hill-start assist fitment across expanding vehicle categories. These frameworks shape demand by elevating baseline safety equipment requirements and restricting market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between braking-system harmonization initiatives and emerging electric vehicle-specific performance thresholds.
Market Dynamics
EU General Safety Regulation mandates are compressing fitment timelines for new vehicle categories, forcing brake-system suppliers to accelerate platform redesigns and recalibrate sensor-actuator integration architectures ahead of 2026 enforcement deadlines.
Growth Catalysts
- Commercial fleet electrification:Electric bus and truck operators in China require hill-start assist systems to manage torque delivery on steep depot ramps, creating dedicated procurement programs.
- REACH compliance deadlines:European brake-fluid formulation rules are accelerating replacement cycles for hydraulic control modules, pulling forward system upgrade investments.
- Gradient sensor miniaturization:MEMS-based inclinometers are reducing ECU packaging requirements, enabling fitment on compact city cars previously excluded from hill-start assist specifications.
Market Restraints
- Semiconductor input volatility:Wheel-speed sensor ASICs face allocation constraints from Taiwanese foundry concentration, inflating module costs and extending OEM lead times.
- Calibration complexity:Proprietary diagnostic protocols from German brake-system suppliers lock independent workshops out of aftermarket installation, shrinking addressable service revenue.
- Regulatory fragmentation:Divergent NHTSA and GB/T testing protocols force dual-validation investments for suppliers serving both US and Chinese OEM programs.
Strategic Opportunities
- India two-wheeler mandate expansion:Proposed BIS safety standards for motorcycles above 125cc would extend hill-start assist requirements to a 22-million-unit annual production base lacking incumbent suppliers.
- Autonomous shuttle integration:Self-driving campus vehicles in US university and corporate deployments require fail-safe gradient hold functions, opening a specification channel outside traditional automotive procurement.
- Software-defined braking:Over-the-air calibration updates are converging with hill-start assist parameter tuning, enabling subscription-based feature activation for dormant hardware.
Industry Challenges
- Embedded systems cybersecurity certification:UN R155 compliance for brake-control ECUs demands penetration-testing capabilities scarce among Tier-2 sensor suppliers.
- Legacy platform integration:12-volt electrical architectures in aging commercial vehicle fleets lack the power stability for next-generation electric hill-start assist actuators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hill-Start Assist System Market |
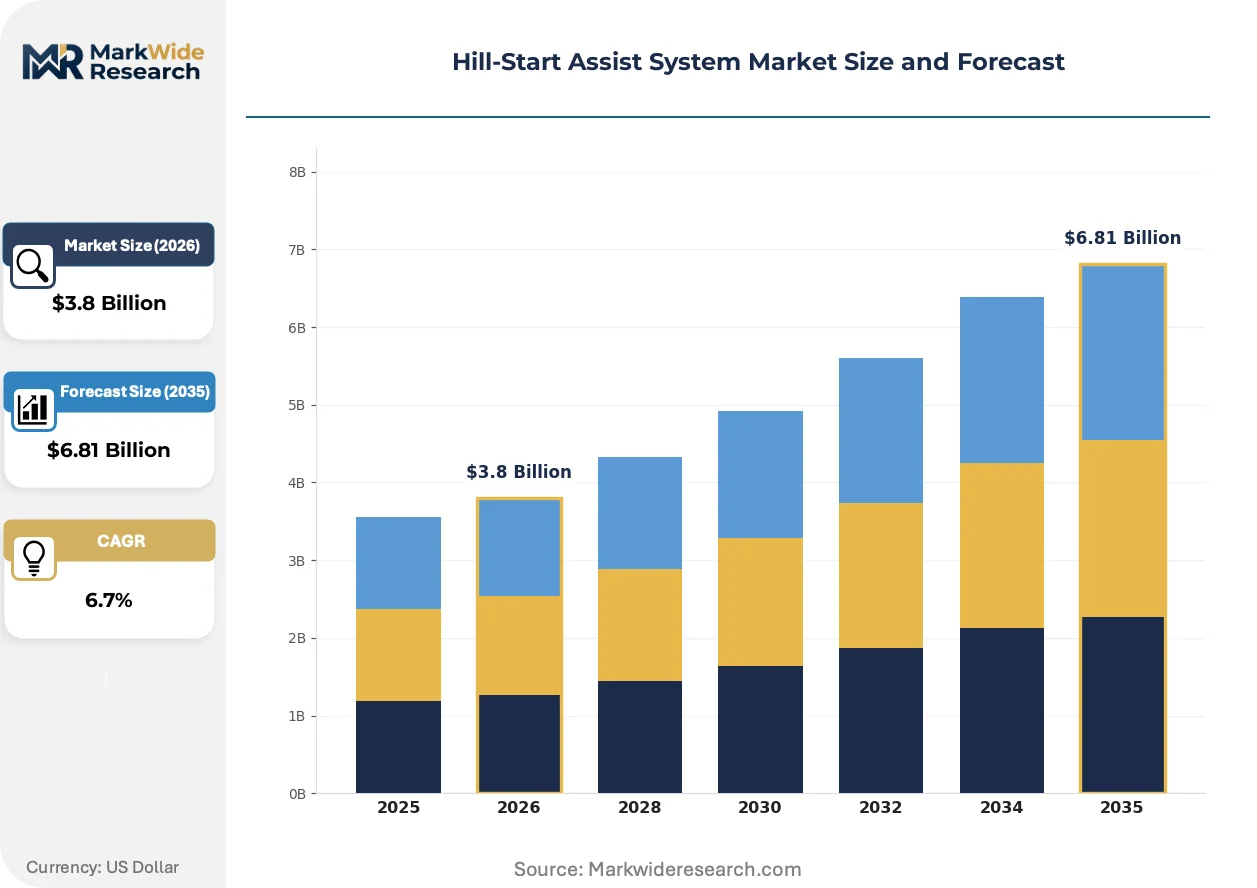
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, SUV Technology: Hydraulic System, Electric System, Pneumatic System, Electronic Control End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Users Installation: Factory Installed, Aftermarket Installed, Integrated, Standalone |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, BorgWarner Inc., Knorr-Bremse AG, HELLA GmbH & Co. KGaA, Aisin Corporation, Murata Manufacturing Co., Ltd., BWI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hill-Start Assist System Market Shifts & Advancements
Brake-by-wire architectures are dissolving the boundary between mechanical and electronic control systems, creating new integration points for hill-start assist functions within centralized vehicle dynamics computers.
Electro-hydraulic brake actuation is converging with hill-start assist pressure modulation, collapsing separate control modules into unified chassis domain controllers. European premium OEMs are adopting these consolidated platforms for 2026 model-year electric vehicles, compressing supplier tier structures and eliminating standalone hill-start assist ECU procurement categories.
The EU General Safety Regulation's expanded fitment requirements for light commercial vehicles are mandating hill-start assist on delivery vans below 3.5 tonnes previously exempt from advanced braking mandates. German fleet operators are pre-ordering compliant vehicles eighteen months ahead of enforcement, pulling forward supplier capacity investments and reshaping Q3-Q4 production scheduling.
Fleet procurement departments are consolidating brake-system sourcing under single-supplier framework agreements, displacing multi-source strategies that previously segmented hydraulic and electronic control awards. This concentration is most visible among US last-mile delivery operators, who are bundling hill-start assist with automatic emergency braking and stability control under unified five-year supply contracts with penalty clauses for non-compliance.
Hill-Start Assist System Market Segmentation
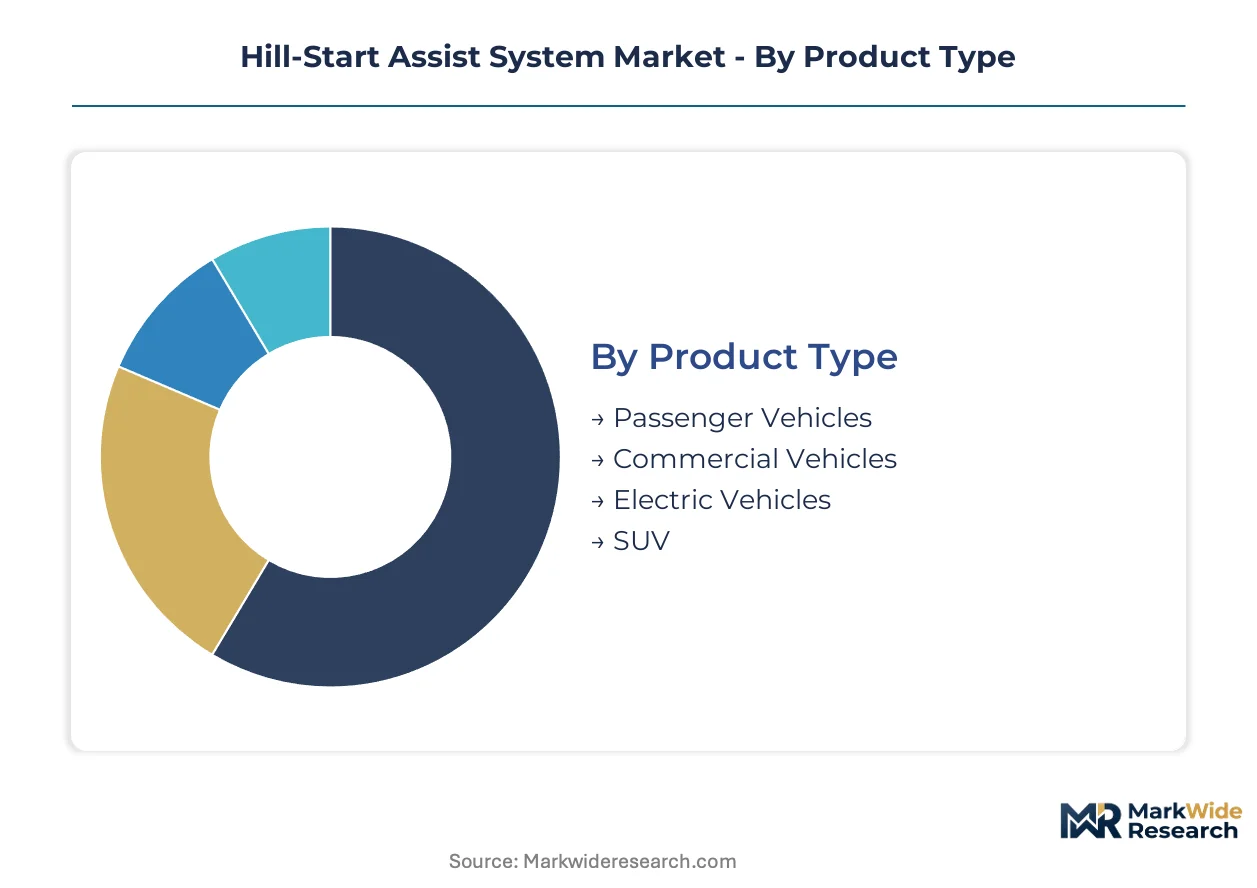
Segmentation in the hill-start assist system market reveals distinct procurement patterns across vehicle architectures and supply channels. Brake-system suppliers calibrate platform strategies around electrification timelines, regulatory fitment mandates, and fleet-operator consolidation trends.
Product Type:
Volume concentration determines supplier R&D allocation and manufacturing footprint decisions across vehicle categories.
- Passenger Vehicles:Sedans and hatchbacks generate the largest absolute unit demand for hill-start assist systems, with European and Chinese OEMs mandating fitment on A-segment and above. German premium manufacturers bundle the function with electronic parking brake systems, compressing module count and supplier margins.
- Electric Vehicles:Battery-electric platforms require recalibrated hill-start assist logic to coordinate with regenerative braking torque mapping. Chinese electric bus operators in Shenzhen and Chengdu specify enhanced gradient-hold capability for depot ramps exceeding 15% grade.
- Commercial Vehicles:Heavy-duty trucks deploy pneumatic-hydraulic hybrid actuation for loaded gradient starts on interstate corridors.
- SUV:All-terrain capability marketing drives fitment on compact SUVs in the US Sun Belt states.
Passenger vehicles lead on scale; electric vehicles lead on momentum.
Technology:
Actuation mechanism selection hinges on vehicle electrical architecture voltage and brake-system integration depth.
- Hydraulic System:Conventional 12-volt architectures in internal combustion vehicles rely on solenoid-modulated brake fluid pressure. European suppliers face REACH compliance pressure on brake fluid formulations, accelerating module replacement cycles.
- Electric System:Motor-driven caliper actuation eliminates hydraulic lines, enabling packaging flexibility for skateboard electric vehicle platforms. US and Chinese electric vehicle programs specify electric hill-start assist for unified brake-by-wire architectures.
- Pneumatic System:Air-brake commercial fleets in North America retain pneumatic gradient-hold for trailer compatibility.
- Electronic Control:Software-defined parameter tuning allows over-the-air calibration updates for dormant hardware.
Hydraulic systems dominate current installed base; electric systems show steepest expansion trajectory.
End User:
Procurement authority concentration shapes pricing leverage and contract structure across customer types.
- OEMs:Vehicle manufacturers specify hill-start assist as standard equipment on platforms above economy trim levels. German and Chinese OEMs integrate the function within consolidated chassis domain controllers, eliminating standalone ECU procurement.
- Aftermarket Providers:Independent workshops face calibration barriers from proprietary diagnostic protocols. US and European aftermarket demand concentrates on collision repair and flood-damage replacement rather than upgrade installations.
- Fleet Operators:Last-mile delivery consolidators in the United States negotiate multi-year brake-system bundles with penalty clauses.
- Individual Users:Direct consumer purchases remain negligible due to installation complexity and warranty implications.
OEMs command pricing power through volume commitments; fleet operators are consolidating procurement authority fastest.
Installation:
Fitment timing relative to vehicle lifecycle determines margin structure and technical validation requirements.
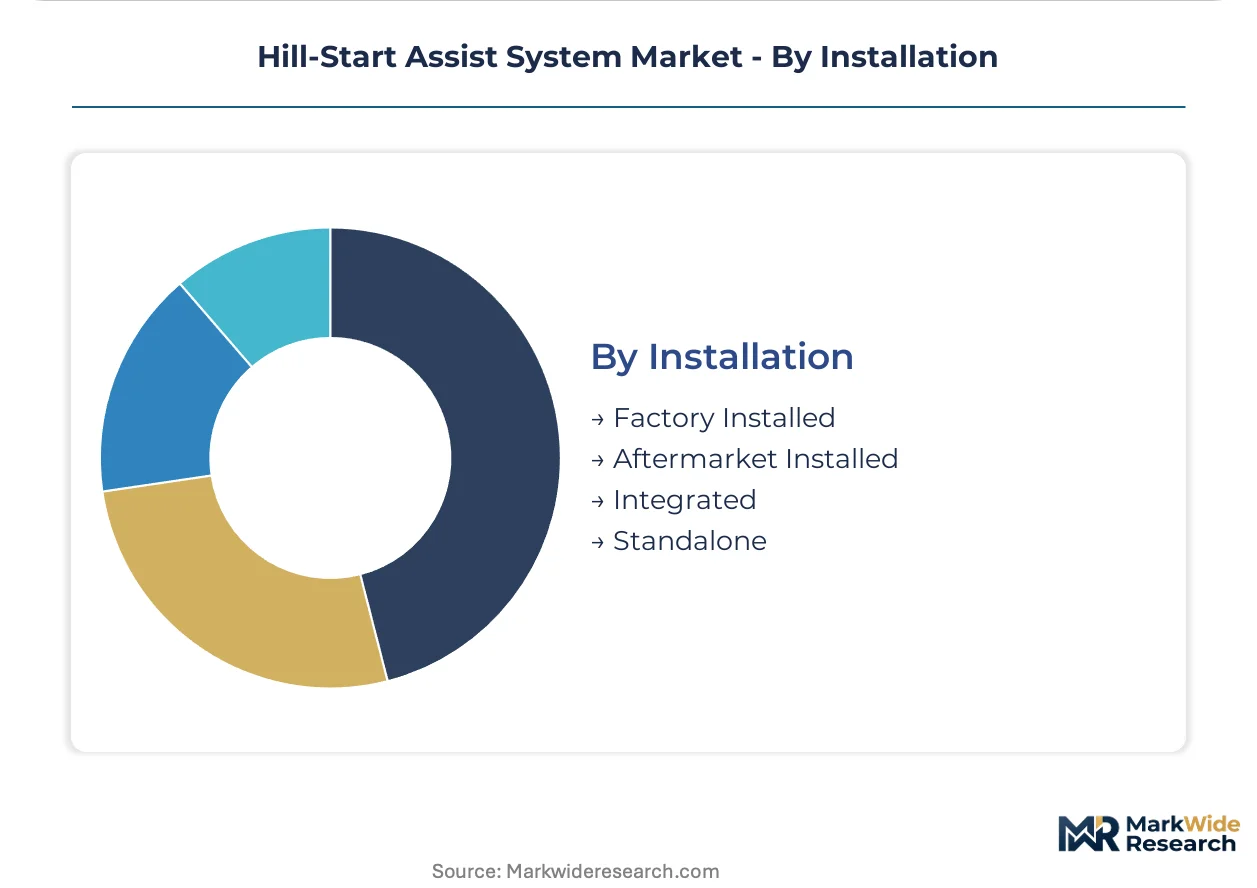
- Factory Installed:Original equipment fitment captures dominant share as OEMs mandate hill-start assist across expanding trim levels. European Union General Safety Regulation deadlines are pulling forward supplier capacity investments for light commercial vehicle programs.
- Integrated:Consolidation into unified chassis controllers eliminates standalone module categories. Premium electric vehicle platforms in Germany and China specify integrated hill-start assist within vehicle dynamics computers.
- Aftermarket Installed:Post-production fitment faces margin compression from calibration complexity and diagnostic access restrictions.
- Standalone:Discrete ECU configurations persist in legacy commercial vehicle retrofit programs.
Factory installed leads on scale; integrated configurations gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as suppliers migrate capacity toward jurisdictions with harmonized brake-system certification and lower cost-of-compliance thresholds. German and Chinese regulatory frameworks now serve as de facto global standards, pulling supplier investments away from fragmented national approval regimes.
United States
Commercial fleet electrification and last-mile delivery consolidation are driving hill-start assist specification on electric vans and medium-duty trucks. NHTSA Federal Motor Vehicle Safety Standards mandate expanded stability control coverage for light commercial vehicles. Detroit-based brake-system engineering centers coordinate Tier-1 supplier validation programs for North American OEM platforms.
Germany
Premium electric vehicle platforms and consolidated chassis domain controllers are accelerating integrated hill-start assist adoption. EU General Safety Regulation deadlines force brake-system suppliers to recalibrate sensor-actuator architectures ahead of enforcement. Stuttgart and Munich engineering clusters host validation facilities for unified brake-by-wire development programs.
China
Electric bus depot ramp operations and steep-gradient urban corridors demand enhanced gradient-hold capability on commercial EV platforms. GB/T vehicle safety standards incentivize hill-start assist fitment across expanding vehicle categories. Shenzhen and Chengdu municipal operators specify 15%-grade capability for electric bus procurement tenders.
India
Two-wheeler safety mandate expansion and commercial vehicle fleet renewal are creating first-mover opportunities for brake-system suppliers. Proposed BIS standards for motorcycles above 125cc would extend hill-start assist requirements to mass-market segments. Pune and Chennai automotive clusters attract component localization investments from European brake-system manufacturers.
Japan
MEMS sensor miniaturization and compact vehicle packaging requirements are enabling hill-start assist fitment on kei cars and city vehicles. METI industrial standards coordinate domestic OEM brake-system harmonization initiatives. Nagoya-based supplier networks integrate gradient sensors with transmission control modules for factory-installed applications.
Hill-Start Assist System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined braking and subscription-based feature activation. The supplier base concentrates around integrated brake-control module manufacturers with chassis domain controller expertise. Three archetypes dominate: diversified automotive conglomerates with full-system capability, specialized brake-system engineering houses, and sensor-component specialists supplying into Tier-1 assemblies. Competitive moves center on mechatronic integration depth and strategic partnerships with electric vehicle platform architects.
Within the diversified conglomerate tier, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG exemplify scale-driven positions anchored in European automotive supply chains. Bosch represents the integrated sensor-actuator platform archetype, while Continental occupies a position tied to brake-control module consolidation. ZF exemplifies mechatronic bundling strategies that collapse discrete functions into unified transmission-brake systems. These three German entities sit within a supplier ecosystem where factory-installed procurement dominance and proprietary diagnostic protocols create high barriers for aftermarket challengers.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Knorr-Bremse AG |
| HELLA GmbH & Co. KGaA |
| Aisin Corporation |
| Murata Manufacturing Co., Ltd. |
| BWI Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 26262-compliant brake-control modules and uncertified commodity sensors manifests in both pricing stratification and supplier qualification barriers. German Tier-1 suppliers command premium positioning through integrated chassis domain controllers, while Asian sensor specialists compete on unit economics for non-safety-critical inclinometer components.
Pricing Analysis
Distributor margins on aftermarket hill-start assist modules compress under proprietary diagnostic lockout from Bosch, Continental, and ZF factory-installed programs. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D certification grade and bundled electronic parking brake integration. Cost compression in hydraulic control modules intensifies because REACH compliance deadlines accelerate European brake-fluid replacement cycles. Fleet operators exhibit lowest price sensitivity due to unified five-year supply contracts with non-compliance penalty clauses, while independent workshops face highest sensitivity from calibration equipment investments.
Supply Chain Analysis
UN R155 cybersecurity certification gates Tier-2 sensor supplier access to European OEM brake-control ECU procurement. Wheel-speed sensor ASIC fabrication concentrates in Taiwan, South Korea, and Germany, with MEMS inclinometer wafer processing anchored in Japan and the United States. Raw material dependencies include automotive-grade semiconductors, rare-earth magnets for electric caliper motors, and specialized brake-fluid formulations. Single-source vulnerability around Taiwanese foundry concentration for sensor ASICs exposes module lead times to allocation shocks. Distribution runs through OEM direct-supply agreements and authorized Tier-1 subsystem integrators, bypassing traditional aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as electric vehicle platforms demand ASIL-D certified gradient-hold logic integrated with regenerative braking torque mapping.
For Market Incumbents: Anchor factory-installed dominance by deepening backward integration into MEMS sensor fabrication and securing captive supply of automotive-grade semiconductors. Consolidate chassis domain controller architectures ahead of EU General Safety Regulation enforcement to eliminate standalone ECU competitors. Threaten emerging software-defined braking entrants through proprietary over-the-air calibration protocols that lock aftermarket access. For New Entrants and Emerging Players: Launch via subscription-based feature activation for dormant hill-start assist hardware in legacy electric vehicle fleets. Target India two-wheeler safety mandate expansion as the most penetrable geography, where 22-million-unit annual production lacks incumbent brake-system suppliers. Pursue autonomous shuttle campus deployments in US university settings as a specification channel outside traditional automotive procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where Tier-2 sensor suppliers face UN R155 cybersecurity certification barriers and penetration-testing capability gaps. Long-term viability favors suppliers with chassis domain controller expertise and electric vehicle platform architect partnerships. Watch for inflection signals in India BIS motorcycle safety standard finalization and China GB/T commercial EV gradient-hold requirement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Collapses standalone hill-start assist ECU procurement into unified chassis domain controllers at Continental and ZF. |
| Sensor ASIC Supply Agreement | Secures Taiwanese foundry allocation for wheel-speed sensor fabrication amid semiconductor input volatility. |
| Software-Defined Braking Investment | Enables over-the-air calibration updates and subscription-based feature activation for dormant hardware. |
| India Manufacturing Footprint Expansion | Positions first-mover suppliers for BIS two-wheeler safety mandate enforcement in Pune and Chennai clusters. |
| Autonomous Vehicle Partnership | Opens specification channel for fail-safe gradient hold in US campus shuttle deployments outside traditional OEM procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier-1 brake-system procurement managers, OEM platform engineers, aftermarket distributors, fleet operator maintenance directors, and MEMS sensor R&D leads. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, EU General Safety Regulation implementation documents, China GB/T vehicle safety standards, vehicle production databases, and SEC disclosures from listed brake-system suppliers. Bottom-up unit demand modeling triangulated against top-down market value estimates.
Segment-weighting approaches distributed volume and value across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from logistic growth curve fitting with S-curve inflection adjustments for regulatory mandate enforcement windows. Industry-specific forecast inputs included electric vehicle platform launch timelines, EU General Safety Regulation fitment phase-in schedules, and commercial fleet electrification procurement programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor allocation shocks or regulatory timeline delays. Projections reflect assumptions on OEM integration strategies, Tier-1 supplier consolidation trajectories, and aftermarket diagnostic access evolution. A model refresh is warranted upon material change in India BIS two-wheeler mandate finalization or UN R155 cybersecurity certification requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market