
 Europe Airbag Systems Market | 2026-2036
Europe Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airbag Systems Market Foresight
EU General Safety Regulation is hardening the cost-of-entry calculus for suppliers without certified advanced restraint engineering capabilities. Autoliv Inc. anchors its European position through integrated inflator and module manufacturing in Sweden and Romania. ZF Friedrichshafen AG leverages its passive safety division to sustain dual sourcing relationships with German and French OEM platforms. Continental AG competes on electrochemical sensing integration that enables adaptive deployment algorithms.
Europe airbag systems comprise fabric cushions, gas generators, and electronic control units engineered to deploy within milliseconds of crash detection, typically using sodium azide or nitroguanidine propellants to inflate nylon or polyester woven bags that protect occupants from interior impact. The primary commercial purpose is to reduce fatal and serious injury rates in frontal, side, and rollover collision scenarios across passenger and commercial vehicle categories. Frontal airbags occupy the largest installed base but face margin compression as standard equipment across all vehicle classes. Curtain airbags represent the fastest-growing product category as side-impact and ejection-mitigation requirements expand under Euro NCAP protocols. Electrochemical deployment technology leads innovation investment, while mechanical systems dominate aftermarket replacement demand due to lower unit costs and simpler diagnostic requirements.
The EU General Safety Regulation, Euro NCAP testing protocols, and ECE R94/R95 harmonized standards collectively mandate multi-point airbag coverage, crash sensor calibration, and pedestrian protection integration that reshape product development priorities and homologation timelines for suppliers. REACH chemical restrictions on propellant compositions and the F-Gas Regulation on inflation gas alternatives further constrain material selection and manufacturing process design across European production facilities. Stakeholders must monitor the interplay between autonomous vehicle interior reconfigurations and adaptive restraint system requirements as cabin layouts evolve away from traditional forward-facing seating positions.
Market Dynamics
The EU General Safety Regulation and Euro NCAP's evolving test protocols are compressing homologation timelines while mandating multi-chamber airbag coverage across all vehicle classes. This regulatory tightening is forcing suppliers to accelerate electrochemical sensing integration and adaptive deployment algorithm development.
Growth Catalysts
- Euro NCAP Protocol Expansion:Side-impact and ejection-mitigation requirements are accelerating curtain airbag installations across B-segment and C-segment vehicle platforms in France and Germany.
- REACH-Compliant Propellant Transition:Sodium azide substitution programs are driving nitroguanidine formulation R&D investment at manufacturing facilities in Sweden and Romania.
- Autonomous Interior Reconfiguration:Non-forward-facing seating concepts in German premium OEM development programs are creating demand for adaptive restraint geometries.
Market Restraints
- F-Gas Regulation Constraint:Inflation gas alternatives face material selection restrictions that limit manufacturing process flexibility at European production facilities.
- Swedish-Romanian Supply Concentration:Integrated inflator and module manufacturing clusters create geographic vulnerability for dual-sourcing relationships with German and French OEM platforms.
- Mechanical System Aftermarket Persistence:Lower unit cost and simpler diagnostic requirements for legacy electromechanical deployments delay full electrochemical system penetration in replacement channels.
Strategic Opportunities
- Polish Manufacturing Corridor:Greenfield production capacity in Lower Silesia offers proximity to expanding German OEM supplier parks with favorable labor cost structures.
- Pedestrian Protection Integration:External airbag and hood-lifting actuator mandates under EU General Safety Regulation create new product categories for exterior sensing-to-deployment systems.
- Electrochemical-Mechanical Convergence:Hybrid deployment architectures combining solid-state sensing with compressed gas inflation address mid-market price sensitivity while preserving safety performance.
Industry Challenges
- ECE R94/R95 Homologation Timeline Compression:Crash sensor calibration certification cycles now overlap with vehicle platform development windows, squeezing validation schedules.
- Adaptive Algorithm Talent Scarcity:Embedded software engineering for real-time occupant position detection and deployment force modulation commands premium compensation in Stuttgart and Munich labor markets.
- Legacy Platform Integration Friction:Electrochemical control units must interface with decade-old vehicle electrical architectures without full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airbag Systems Market |
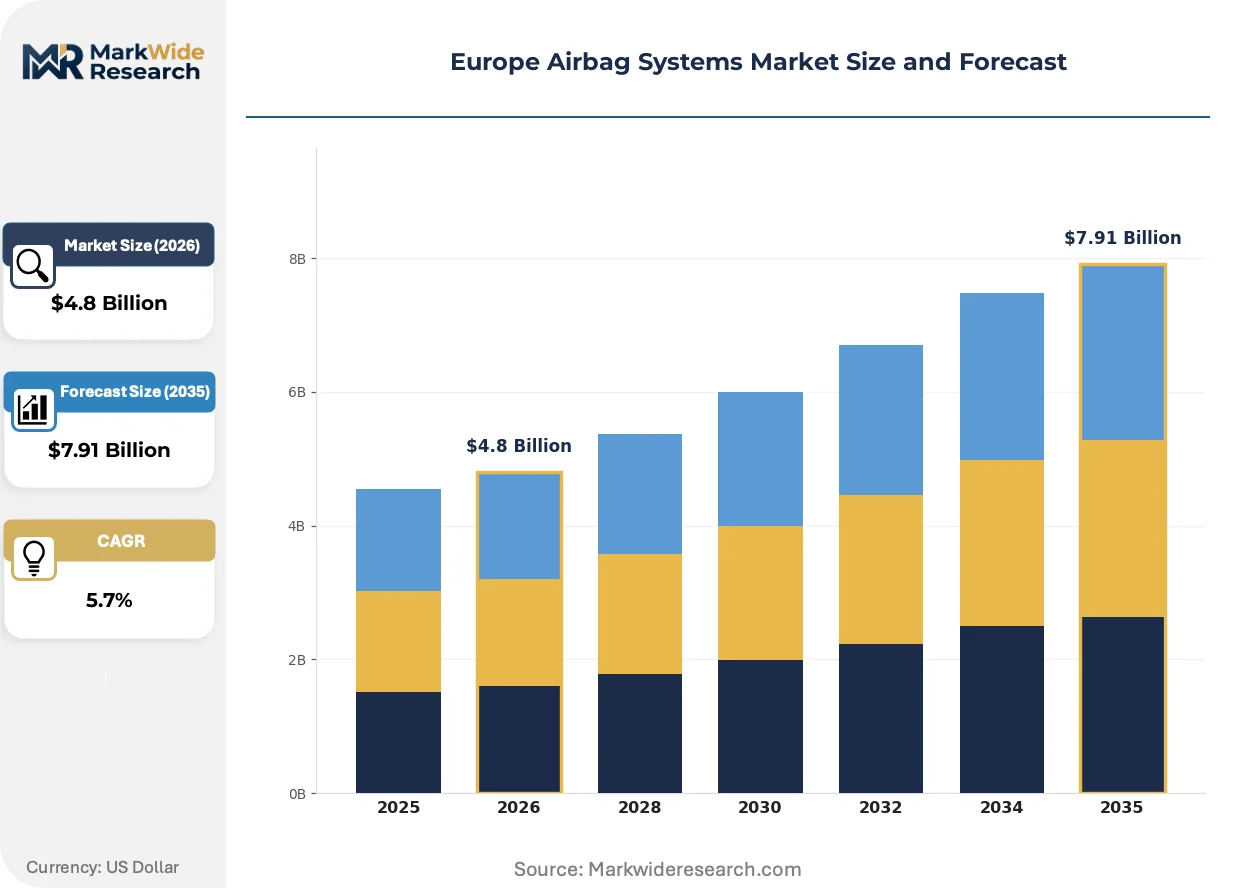
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Mechanical, Electrochemical, Hybrid, Gas Generators End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Installation Type: Integrated, Retrofitted, Modular, Custom |
| Companies Covered | ZF Friedrichshafen AG, Hyundai Mobis Co Ltd, Autoliv Inc., TRW Automotive, Toyoda Gosei Co Ltd, Robert Bosch GmbH, Denso Corporation, Delphi Automotive Plc, Continental AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airbag Systems Market Shifts & Advancements
Electrochemical deployment technology is unifying sensing, decision, and actuation functions into single-chip architectures. This integration is compressing supplier margins while enabling OEMs to reduce module count and wiring complexity.
Multi-chamber airbag configurations are unifying frontal, side, and knee protection into coordinated deployment sequences. German premium OEMs are adopting these systems fastest, requiring suppliers to consolidate previously separate inflator and cushion supply chains. The structural consequence is that tier-one suppliers with captive gas generator production are unifying module assembly and inflator manufacturing under single-facility control.
Euro NCAP's 2026 testing protocol revision is mandating far-side impact protection and advanced seatbelt-integrated airbag coordination. This regulatory tightening is forcing French and Italian OEMs to accelerate development programs previously scheduled for 2028 platform refreshes. The segment most affected is compact SUVs, where packaging space constraints conflict with expanded airbag volume requirements.
Fleet procurement departments are consolidating safety specification authority previously held by regional purchasing offices. This centralization is compressing supplier negotiation cycles and favoring pan-European service contracts over country-specific agreements. The shift is most visible in German commercial vehicle manufacturing, where corporate safety mandates now override local plant preferences.
Europe Airbag Systems Market Segmentation
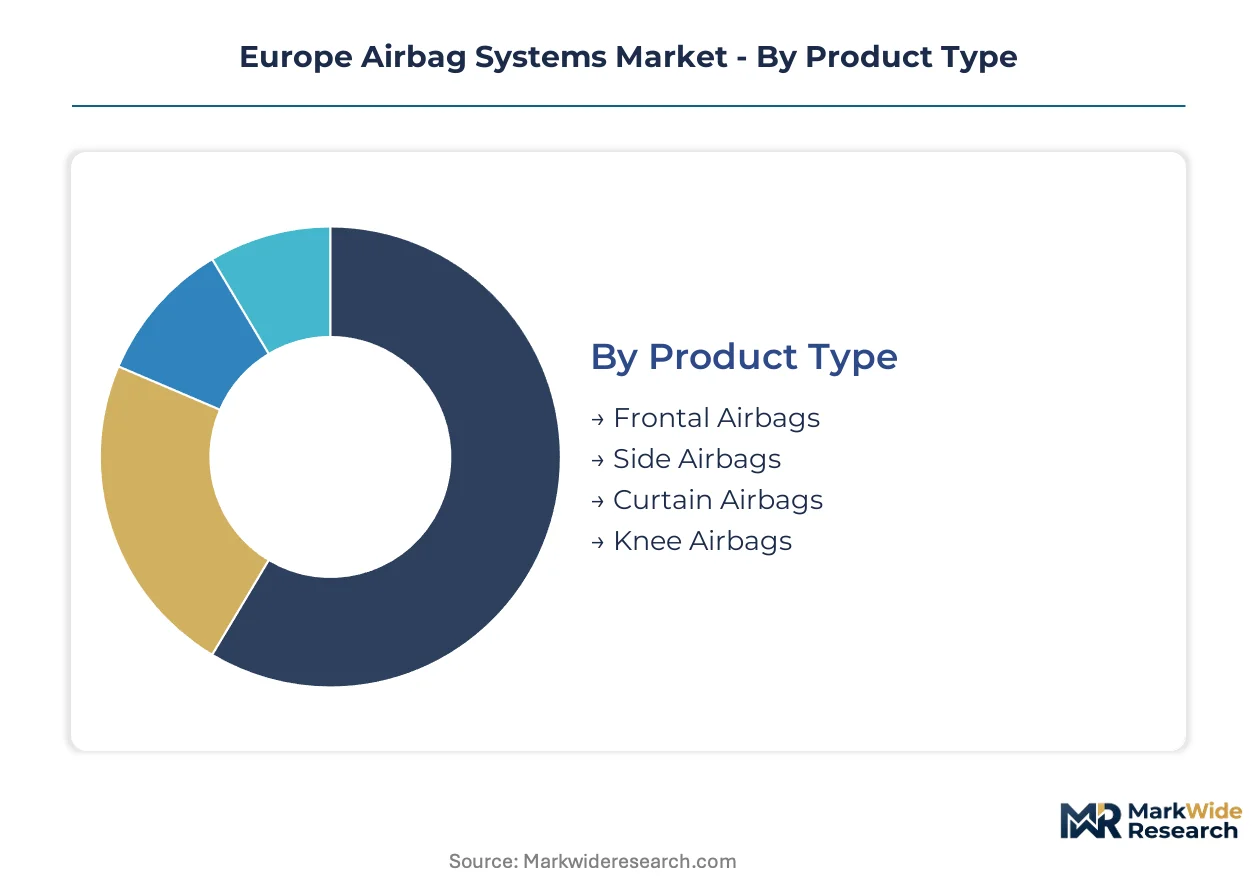
Airbag system procurement decisions in Europe pivot on regulatory compliance thresholds, platform integration complexity, and lifecycle cost structures. OEMs segment supplier qualifications by deployment technology maturity and homologation track record under ECE R94/R95 standards. Tier-1 sourcing strategies differentiate between integrated module assemblies for new platforms versus replacement channel requirements.
Product Type:
Vehicle platform architecture and occupant kinematics determine cushion geometry selection, with Euro NCAP scoring protocols directly influencing chamber count per seating position.
- Frontal Airbags:Dual-stage pyrotechnic inflators deploy nylon or polyester woven cushions from steering wheel and dashboard housings. German premium OEMs mandate adaptive venting systems that modulate inflation force based on occupant mass and seat position sensors. Driver and passenger frontal units occupy the largest installed base across European passenger vehicle production.
- Curtain Airbags:Roof-rail mounted tubular or pleated cushions extend from A-pillar to C-pillar during side-impact and rollover events. French and Italian OEMs are accelerating installations across B-segment and C-segment platforms to meet ejection-mitigation requirements. This segment is gaining share fastest as side-impact protection mandates expand beyond luxury vehicle categories.
- Side Airbags:Seat-mounted or door-panel cushions protect thorax and pelvic regions during lateral collisions.
- Knee Airbags:Lower dashboard deployments reduce femur and hip injury risk in frontal impacts, increasingly standard in German-manufactured vehicles.
Frontal airbags lead on scale; curtain airbags lead on momentum.
Technology:
Deployment mechanism selection tracks directly to vehicle electrical architecture generation and diagnostic capability requirements.
- Electrochemical:Solid-state sensors, microprocessor-controlled decision logic, and precision inflator ignition circuits enable adaptive deployment algorithms. Swedish and Romanian manufacturing clusters concentrate production for German OEM platforms requiring real-time occupant position detection. REACH-compliant propellant formulations are displacing legacy sodium azide compositions.
- Mechanical:Spring-mass sensors and mechanical ignition systems persist in aftermarket replacement channels where diagnostic simplicity and lower unit costs dominate purchasing criteria. Eastern European vehicle parc maintenance supports continued demand despite declining new vehicle fitment.
- Hybrid:Compressed gas storage combined with pyrotechnic augmentation addresses mid-market price sensitivity while preserving deployment speed.
- Gas Generators:Sodium azide and nitroguanidine propellant assemblies remain the core inflation energy source across all electronic control architectures.
Electrochemical systems command the premium tier; mechanical systems retain replacement channel volume.
End User:
Procurement authority concentration shapes contract structures, with fleet safety specification centralization displacing regional purchasing autonomy.
- OEMs:Volkswagen Group, Stellantis, and BMW specify integrated passive safety modules through long-term supply agreements with captive inflator production. Platform development timelines now overlap with ECE R94/R95 homologation cycles, compressing supplier validation schedules.
- Tier-1 Suppliers:Autoliv, ZF Friedrichshafen, and Continental aggregate fabric cushion, gas generator, and electronic control unit production under single-facility control to meet German OEM dual-sourcing requirements.
- Aftermarket:Independent repair channels source replacement modules through distributors serving aging European vehicle parc.
- Vehicle Assemblers:Contract manufacturing operations for niche and specialty vehicle producers.
OEMs concentrate specification authority; Tier-1 suppliers control manufacturing integration.
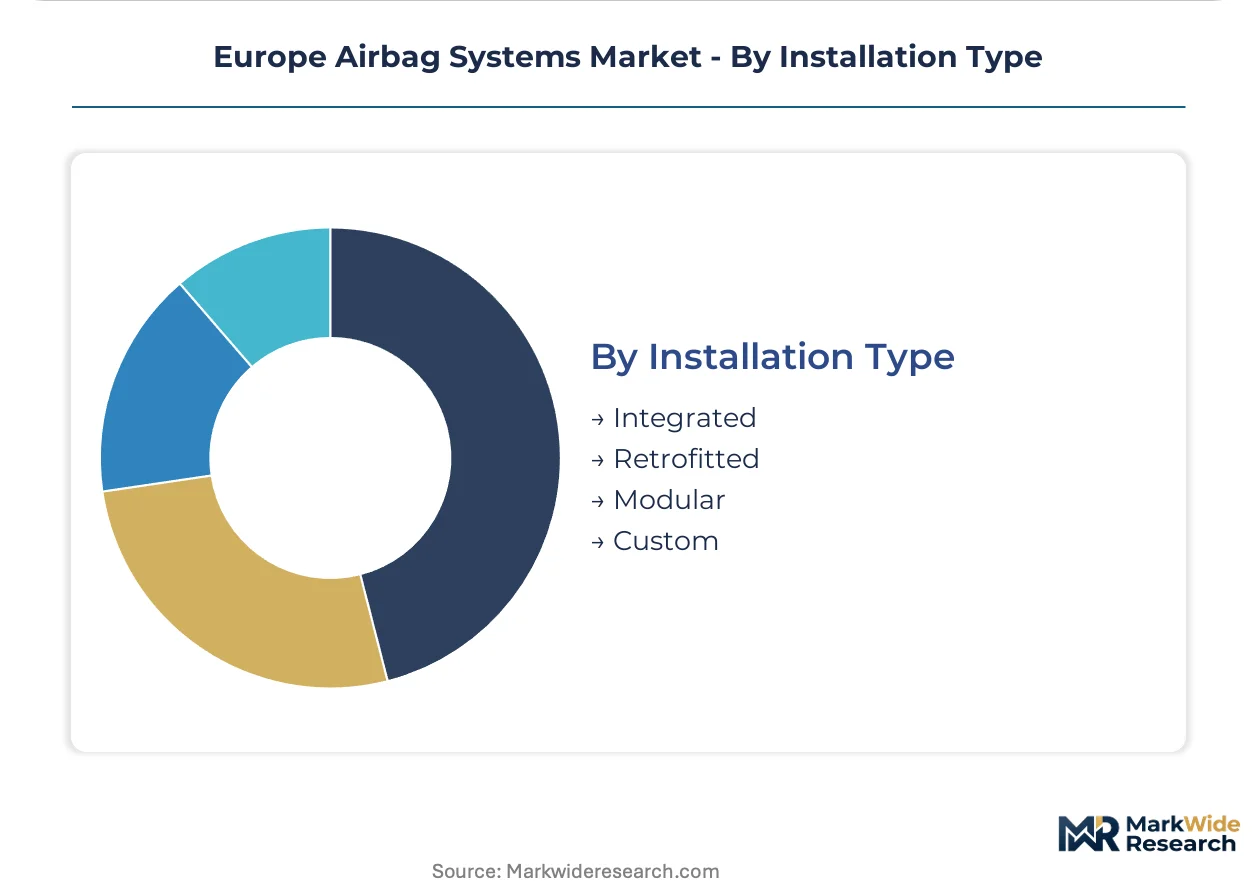
Installation Type:
Integration depth with vehicle electrical and structural systems determines warranty liability and service protocol complexity.
- Integrated:Factory-installed modules with dedicated wiring harnesses and crash sensor networks calibrated to specific vehicle platform deformation characteristics. German and French OEM production lines mandate this configuration for type-approval compliance.
- Modular:Pre-assembled cushion-inflator-control unit combinations enabling platform-commonality across multiple vehicle segments.
- Retrofitted:Post-manufacture additions to commercial vehicle and specialty applications.
- Custom:Bespoke configurations for motorsport, defense, and limited-production vehicle programs.
Integrated installations dominate new vehicle output; modular designs enable platform scale economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded software engineers in Stuttgart and Munich labor markets command premium compensation for adaptive algorithm development. Romanian and Swedish manufacturing clusters concentrate integrated inflator production. REACH compliance deadlines reshape material sourcing across continental production networks.
Germany
Volkswagen Group and BMW procurement specifications drive multi-chamber airbag adoption across premium platforms. KBA homologation requirements compress supplier validation schedules for ECE R94/R95 certification. The Stuttgart-Munich corridor concentrates electrochemical sensing R&D and adaptive restraint engineering talent pools.
France
Stellantis production platforms accelerate curtain airbag installations across B-segment and C-segment vehicles to meet ejection-mitigation mandates. ANSM technical standards influence pyrotechnic component safety protocols. The Île-de-France region hosts supplier engineering centers coordinating with Auvergne-Rhône-Alpes manufacturing sites.
Sweden
Autoliv's integrated inflator and module manufacturing anchors national export capacity for German OEM dual-sourcing contracts. ECHA REACH enforcement drives sodium azide substitution programs in propellant formulations. The Västerås-Linköping production corridor specializes in gas generator assembly and nitroguanidine R&D facilities.
Romania
Lower labor cost structures attract greenfield module assembly investments serving expanding German supplier parks. EU Green Deal manufacturing sustainability criteria constrain facility design and energy sourcing decisions. The Arad-Timișoara industrial zone hosts tier-one captive inflator production for cross-border just-in-sequence delivery.
Poland
Lower Silesia offers proximity advantages to Czech and German automotive corridors with favorable wage structures for assembly operations. F-Gas Regulation compliance restricts inflation gas alternative selection at new production facilities. The Wrocław-Katowice region attracts supplier park investments from tier-one passive safety module integrators.
Europe Airbag Systems Market Competitive Landscape
The competitive structure tilts toward integrated module manufacturers with captive gas generator production. Three to five global suppliers control approximately two-thirds of European OEM supply relationships through long-term platform agreements. The dominant archetypes comprise integrated safety module producers, specialized inflator manufacturers, and diversified automotive electronics conglomerates. Capacity consolidation and dual-sourcing contract structures represent the primary competitive maneuvers reshaping supplier positioning.
Among Germany-based diversified automotive suppliers, ZF Friedrichshafen AG and Continental AG occupy positions within the integrated module tier, while Sweden-incorporated Autoliv Inc. exemplifies the specialized passive safety archetype with concentrated manufacturing in Nordic and Eastern European facilities. These three entities anchor the supplier landscape through distinct strategic postures: diversified conglomerate breadth versus focused safety module integration versus geographic production clustering.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Hyundai Mobis Co Ltd |
| Autoliv Inc. |
| TRW Automotive |
| Toyoda Gosei Co Ltd |
| Robert Bosch GmbH |
| Denso Corporation |
| Delphi Automotive Plc |
| Continental AG |
| Others |
Supply & Pricing Matrix
EU Green Deal manufacturing sustainability criteria gate qualified supply access and premium-tier pricing power for airbag system integrators serving German and French OEM platforms. REACH-compliant propellant formulations and F-Gas Regulation compliance costs bifurcate the supplier base between certified premium-tier producers and cost-pressured mechanical system assemblers.
Pricing Analysis
Integrated module assemblies command premium positioning against unbundled component sourcing. Three-tier pricing structure across premium, standard, and economy levels reflects ECE R94/R95 certification grade, captive inflator production, and after-sales diagnostic capability. Cost compression in mid-market electromechanical hybrids intensifies as Polish and Romanian assembly operations scale. Fleet procurement centralization renders aftermarket channels most price-sensitive, while German premium OEMs absorb adaptive algorithm premiums.
Supply Chain Analysis
Embedded software engineering scarcity in Stuttgart and Munich labor markets constrains electrochemical system expansion. Manufacturing concentrates in Sweden, Romania, and Poland, drawing from sodium azide and nitroguanidine propellant feedstocks, nylon and polyester woven fabrics, and solid-state sensor components. Single-source vulnerability pervades the Västerås-Linköping gas generator corridor. Distribution runs through tier-one captive inflator facilities to just-in-sequence OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe airbag systems rests on REACH-compliant propellant substitution programs and adaptive restraint premiumization in German autonomous vehicle development pipelines.
For Market Incumbents: Anticipate Euro NCAP protocol expansion compressing homologation timelines for legacy platform compatibility. Secure captive nitroguanidine formulation capacity in Sweden or Romania to defend dual-sourcing relationships against Polish greenfield entrants. Prioritize embedded software acquisition in Stuttgart-Munich corridor to address adaptive algorithm talent scarcity threatening electrochemical system margins. For New Entrants and Emerging Players: EU General Safety Regulation pedestrian protection mandates in France and Germany open a window for exterior airbag and hood-lifting actuator specialization. Target Polish Lower Silesia manufacturing corridor for greenfield module assembly serving expanding German supplier parks. Lead with hybrid electrochemical-mechanical architectures addressing mid-market price sensitivity in Eastern European aftermarket channels. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two mechanical system assemblers with Eastern European production footprints and legacy platform service contracts. Five-to-ten year viability favors integrated module manufacturers with REACH-certified propellant chemistry and adaptive algorithm development capability. Watch Euro NCAP testing protocol revision timing as inflection indicator for far-side impact protection content acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Propellant Transition | ECHA enforcement in Sweden and Romania accelerates sodium azide substitution program investment. |
| Adaptive Algorithm Development | Stuttgart-Munich software engineering acquisition enables real-time occupant position detection capability. |
| Polish Manufacturing Footprint | Lower Silesia greenfield capacity captures proximity advantages to German OEM supplier parks. |
| Pedestrian Protection Integration | EU General Safety Regulation external airbag mandates create new exterior sensing-to-deployment category. |
| Dual-Sourcing Contract Consolidation | Autoliv and ZF Friedrichshafen captive inflator production secures long-term platform agreements. |
Research Methodology
Direct dialogue with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and ECE homologation specialists grounded this analysis in operational reality. Secondary validation drew from KBA type-approval databases, Euro NCAP test protocol documentation, ECHA REACH substance restriction updates, and vehicle production registration data. Bottom-up and top-down triangulation reconciled module-level shipment estimates with OEM platform content assumptions.
Bottom-up modeling segmented volume and value across the projection horizon by product type, technology architecture, end-user procurement authority, and installation integration depth. CAGRs derived from platform-level content-per-vehicle trajectories, regulatory mandate phase-in schedules, and replacement channel mechanical system persistence. Electrochemical adoption curves and autonomous interior reconfiguration timelines served as industry-specific forecast inputs.
Revisions become necessary when Euro NCAP protocol revisions accelerate, REACH enforcement intensifies propellant substitution timelines, or autonomous vehicle seating reconfiguration stalls. Forecasts reflect documented assumptions about regulatory phase-in schedules and OEM platform development windows. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Smart Airbag Coats Market