
 Germany Airbag Systems Market | 2026-2036
Germany Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Airbag Systems Market Foresight
UN ECE R94 and R95 homologation cycles is redrawing supplier eligibility for frontal and side-impact systems in Germany. Autoliv Inc. leverages its pyrotechnic inflator manufacturing footprint in Saxony to anchor contracts with domestic premium OEMs. Continental AG sustains competitive positioning through integrated electronic control unit development tied to its broader chassis electronics portfolio. ZF Friedrichshafen AG differentiates via multi-chamber airbag architectures aligned with automated driving interior reconfigurations.
Germany airbag systems deploy textile cushions woven from polyamide 6.6 yarns, inflated by sodium azide or nitroguanidine-based gas generators within 20-40 milliseconds of crash detection to occupant contact. Their primary purpose is kinetic energy absorption and occupant kinematic control during collision events. Frontal airbags dominate installed base volumes across passenger car applications, while curtain and far-side systems capture expanding fitment mandates under revised Euro NCAP assessment protocols. Multi-chamber and hybrid gas technologies attract development investment as OEMs seek adaptive deployment profiles for diverse occupant statures and seating positions.
KBA enforces type-approval compliance for all new safety systems, while EU General Safety Regulation mandates advanced driver assistance and passive safety integration from mid-decade. The EU AI Act introduces algorithmic transparency requirements for sensor fusion architectures governing airbag deployment decisions. Stakeholders must monitor convergence between functional safety standards and emerging cybersecurity frameworks for connected restraint systems.
Market Dynamics
Multi-chamber airbag architectures are forcing Tier-1 suppliers to reconfigure manufacturing footprints around Stuttgart and Wolfsburg as Euro NCAP far-side impact protocols tighten deployment timing requirements.
Growth Catalysts
- Euro NCAP 2026 Protocols:New far-side impact testing mandates expand curtain and center airbag fitment across C-segment and above vehicles.
- Baden-Württemberg OEM Clusters:Premium manufacturers in Stuttgart's engineering corridor accelerate orders for adaptive restraint systems.
- Nitroguanidine Generators:Cooler gas deployment chemistry enables thinner textile cushions and expanded seating position flexibility.
Market Restraints
- Polyamide 6.6 Supply Concentration:German weaving capacity concentrates among three suppliers, creating input vulnerability for cushion production.
- KBA Type-Approval Timelines:Extended homologation cycles for pedestrian protection systems delay new product launches by 8-14 months.
- Seatbelt-Integrated Restraints:Advanced pretensioner systems capture kinetic energy management functions in entry segments.
Strategic Opportunities
- Automated Driving Interiors:Swivel seats and reconfigurable cabins demand omnidirectional airbag coverage beyond traditional mounting points.
- EU AI Act Compliance:Algorithmic transparency requirements for sensor fusion create first-mover advantage for ECU-integrated suppliers.
- Bavarian Supplier Corridors:Underdeveloped airbag textile weaving capacity in Munich's northern manufacturing belt offers greenfield expansion potential.
Industry Challenges
- Pyrotechnic Chemist Talent Scarcity:Sodium azide and nitroguanidine formulation expertise concentrates among retiring specialists in Saxony.
- Functional Safety Integration:ISO 26262 ASIL-D certification for airbag ECUs requires 18-24 month validation cycles.
- Legacy 12V Architecture Compatibility:New multi-chamber systems strain electrical distribution networks in vehicle platforms predating 48V migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Airbag Systems Market |
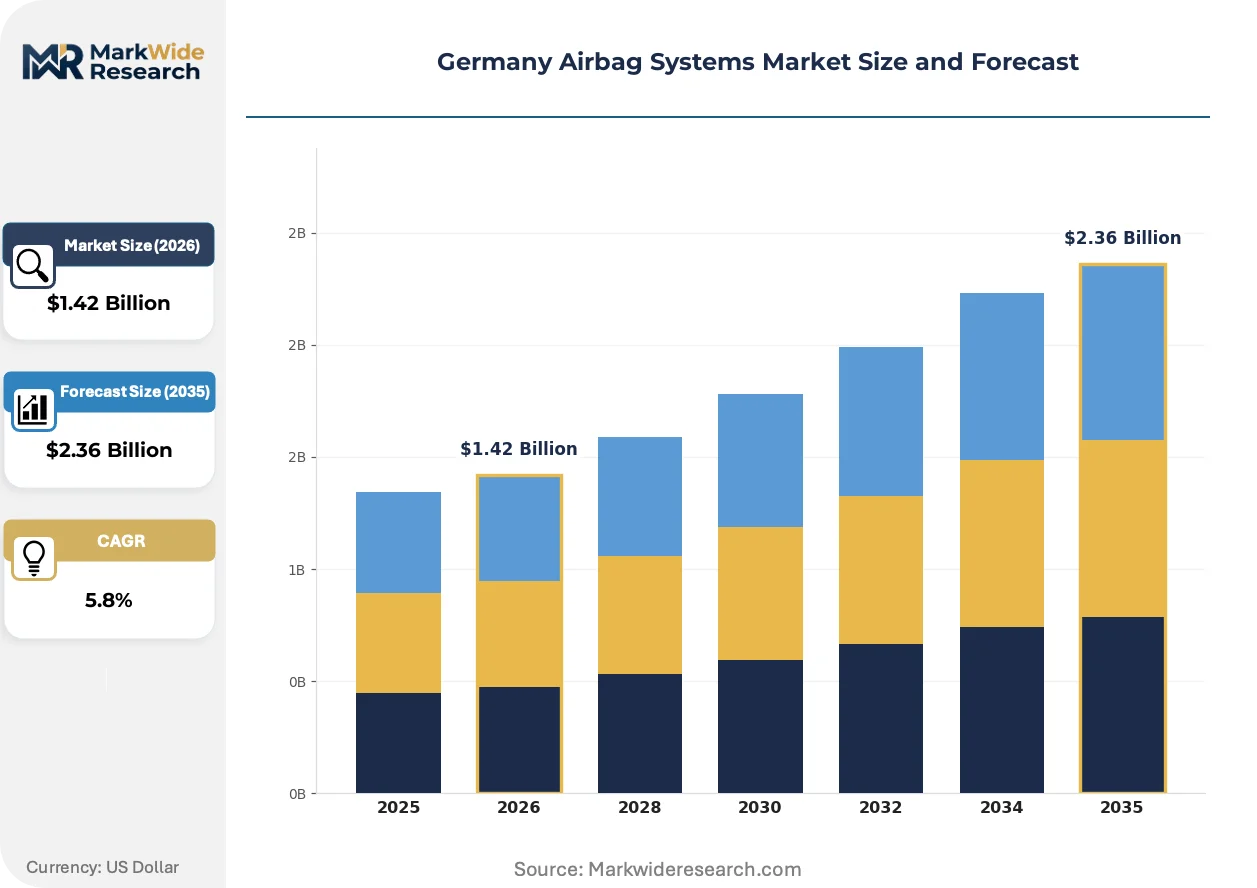
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags, Pedestrian Airbags Technology: Inflatable Curtain, Dual-Stage, Multi-Chamber, Hybrid Gas, Electronic Control Unit Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Autoliv Inc., Continental AG, ZF Friedrichshafen AG, Robert Bosch GmbH, Denso Corporation, Hyundai Mobis, Toyoda Gosei Co., Ltd., Joyson Safety Systems, Valeo SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Airbag Systems Market Shifts & Advancements
Adaptive deployment algorithms and textile engineering advances are compressing traditional hardware-centric competition toward software-defined restraint optimization.
Multi-chamber cushion designs separate inflation zones for thorax and head protection, enabling staged pressure profiles. Premium OEMs in Bavaria and Baden-Württemberg are adopting these architectures for 2027 platform cycles. This capability is displacing single-chamber systems in vehicles above D-segment classification.
KBA enforcement of UN ECE R94 and R95 homologation updates is redrawing supplier eligibility for frontal and side-impact systems. The revised testing cycles mandate pedestrian protection integration that extends deployment decision windows. Stuttgart-based engineering clusters are responding with expanded sensor fusion development.
Fleet procurement of standardized restraint configurations is fragmenting as leasing companies demand vehicle-specific safety ratings. Direct OEM contracting for multi-chamber systems is replacing bundled Tier-1 supply agreements in corporate fleet channels. This pattern concentrates in Wolfsburg's supply corridor where volume OEMs negotiate platform-level specifications.
Germany Airbag Systems Market Segmentation
German airbag procurement channels fragment sharply between direct OEM contracting for premium platforms and bundled Tier-1 supply for volume segments. Channel configuration determines pricing leverage, technical specification depth, and homologation responsibility allocation across the value chain.
Product Type:
Frontal systems flow predominantly through established Tier-1 bundled agreements, while emerging categories increasingly bypass traditional distribution layers for direct platform engineering relationships.
- Frontal Airbags:Deployed from steering wheel and dashboard modules using sodium azide or nitroguanidine generators with 20-40 millisecond inflation timing. Stuttgart's premium OEM clusters and Wolfsburg's volume corridors absorb the bulk of German production capacity under long-term supply agreements.
- Side Airbags:Seat-mounted thorax protection systems utilizing single-point or dual-point tethering architectures. KBA type-approval timelines for revised UN ECE R95 protocols are extending deployment decision windows, compressing supplier margins on entry-segment platforms.
- Curtain Airbags:Roof-rail mounted head protection with extended coverage zones for rollover events. Euro NCAP far-side impact mandates are accelerating fitment rates across C-segment and above classifications.
- Knee Airbags:Lower dashboard modules controlling femur loading and pelvic kinematics. Premium manufacturers in Baden-Württemberg specify these for sport utility and crossover platforms with elevated seating positions.
- Pedestrian Airbags:Hood-deploying external restraint systems triggered by bumper-mounted impact sensors. KBA homologation cycles for pedestrian protection integration delay new product launches by 8-14 months.
Frontal Airbags dominates installed base. Pedestrian Airbags is where expansion concentrates.
Technology:
Cost tier stratification separates commodity inflator technologies from premium adaptive architectures commanding engineering-intensive procurement relationships.
- Inflatable Curtain:Extended-duration gas retention for rollover protection using thicker polyamide 6.6 weave specifications. Bavarian OEM platforms specify these for panoramic roof architectures where traditional mounting points are compromised.
- Dual-Stage:Sequential ignition profiles matching deployment force to crash severity and occupant position. This architecture is climbing the fastest as mid-segment manufacturers seek adaptive capability without full multi-chamber cost.
- Multi-Chamber:Zoned inflation separating thorax and head protection pressures within a single cushion. Stuttgart's premium engineering clusters are adopting these for 2027 platform cycles, displacing single-chamber systems above D-segment classification.
- Hybrid Gas:Combined stored gas and pyrotechnic generation for cooler, more controlled inflation chemistry. Nitroguanidine-based formulations enable thinner textile cushions and expanded seating position flexibility.
- Electronic Control Unit:Sensor fusion architectures governing deployment timing and staged ignition sequences. EU AI Act algorithmic transparency requirements are reshaping supplier eligibility for ECU-integrated contracts.
Dual-Stage systems anchor volume production. Multi-Chamber configurations are where margin expansion concentrates.
Application:
Customer type differentiation separates fleet procurement standardization from premium OEM platform-specific engineering requirements.
- Passenger Cars:C-segment through F-segment platforms with varying fitment mandates under Euro NCAP protocols. Corporate fleet channels are fragmenting procurement patterns as leasing companies demand vehicle-specific safety ratings.
- Commercial Vehicles:Cab-over and conventional truck architectures with distinct restraint mounting constraints. KBA enforces separate homologation cycles for commercial vehicle safety systems.
- Electric Vehicles:Battery pack protection requirements and modified crash pulse signatures alter deployment timing calibration. Stuttgart and Munich engineering corridors are developing EV-specific sensor fusion architectures.
- Autonomous Vehicles:Swivel seats and reconfigurable cabins demand omnidirectional coverage beyond traditional mounting points. This application is gaining share fastest as Bavarian OEMs advance automated driving interior concepts.
- Specialty Vehicles:Limited-production performance and luxury platforms with custom restraint integration. Direct OEM contracting replaces bundled Tier-1 supply in this high-margin niche.
Passenger Cars commands volume scale. Autonomous Vehicles is where technical development investment concentrates.
End User:
Supply concentration determines procurement leverage, with Tier-1 suppliers in Saxony and Baden-Württemberg controlling critical pyrotechnic and textile manufacturing capacity.
- OEMs:Premium manufacturers in Bavaria and Baden-Württemberg negotiate platform-level specifications directly with inflator and cushion suppliers. Direct contracting is displacing bundled Tier-1 agreements in multi-chamber system procurement.
- Tier-1 Suppliers:Integrated restraint system assemblers managing inflator, cushion, and ECU sourcing. Autoliv's Saxony manufacturing footprint and Continental's chassis electronics integration anchor competitive positioning.
- Vehicle Assemblers:Final integration points for imported platform architectures with localized safety system adaptation. Wolfsburg's supply corridor concentrates volume assembly relationships.
- Aftermarket Providers:Replacement cushion and inflator modules for collision repair and system refurbishment. KBA type-approval requirements limit aftermarket participation to certified refurbishment specialists.
Tier-1 Suppliers dominate production flow. OEMs is where specification control and margin capture concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA enforcement of UN ECE R94 and R95 homologation updates is redrawing supplier eligibility across German states. State-level industrial policy and cluster concentration determine procurement leverage and technical specification depth for airbag system deployment.
Bavaria
Premium OEMs in Munich's northern manufacturing belt accelerate orders for adaptive multi-chamber systems. KBA type-approval requirements for pedestrian protection extend homologation timelines for new product launches. Ingolstadt and Munich engineering corridors concentrate development investment for automated driving interior reconfigurations.
Baden-Württemberg
Stuttgart's automotive engineering cluster drives specification control for zoned inflation architectures in D-segment and above vehicles. EU AI Act algorithmic transparency requirements reshape supplier eligibility for ECU-integrated contracts. Karlsruhe and Stuttgart house the densest concentration of sensor fusion development for far-side impact protocols.
Lower Saxony
Wolfsburg's OEM supply corridors absorb bulk volume production under long-term bundled Tier-1 agreements. Corporate fleet procurement fragmentation concentrates negotiation leverage at platform-level specifications. Hanover and Wolfsburg anchor integrated restraint system assembly for C-segment through F-segment applications.
Saxony
Pyrotechnic inflator manufacturing footprints anchor competitive positioning for sodium azide and nitroguanidine formulation. Pyrotechnic chemist talent scarcity concentrates among retiring specialists, compressing knowledge transfer timelines. Dresden and Leipzig house specialized gas generator production tied to domestic premium OEM contracts.
North Rhine-Westphalia
Legacy automotive supplier infrastructure supports aftermarket refurbishment channels under KBA certification requirements. Extended homologation cycles for pedestrian protection systems delay new product introductions by 8-14 months. Cologne and Düsseldorf concentrate certified collision repair specialists for cushion and inflator module replacement.
Germany Airbag Systems Market Competitive Landscape
Player mix skews toward integrated Tier-1 conglomerates with pyrotechnic and electronics capabilities. Three supplier archetypes dominate: pyrotechnic specialists with inflator manufacturing depth, chassis electronics integrators with ECU development scale, and diversified automotive suppliers with multi-chamber textile engineering. Consolidation pressure intensifies through direct OEM contracting displacement of bundled agreements and backward integration into cushion weaving capacity.
Among Germany-based diversified suppliers, Continental AG and ZF Friedrichshafen AG exemplify the electronics-integrated archetype, while Autoliv Inc. represents the pyrotechnic-specialist position with established manufacturing footprints. These three anchors illustrate competitive positioning strategies: chassis electronics portfolio leverage, multi-chamber architecture differentiation, and gas generator chemistry specialization respectively.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Hyundai Mobis |
| Toyoda Gosei Co., Ltd. |
| Joyson Safety Systems |
| Valeo SA |
| Others |
Supply & Pricing Matrix
Nitroguanidine-based gas generator chemistry displacing sodium azide formulations is redrawing supplier economics across German airbag manufacturing, compressing input costs for cooler-deployment systems while concentrating pyrotechnic expertise in Saxony's remaining specialist workforce. This substitution dynamic simultaneously shifts procurement leverage toward ECU-integrated suppliers and fragments pricing power between commodity inflator tiers and adaptive multi-chamber architectures.
Pricing Analysis
Certification level under KBA type-approval timelines creates the primary spread between premium multi-chamber systems and commodity frontal airbag modules. Three-tier pricing structure across premium adaptive, standard dual-stage, and economy single-chamber levels anchors contract negotiations, with ISO 26262 ASIL-D certification commanding substantial engineering premiums. Cost compression in entry-segment bundled supply is intensifying because seatbelt-integrated restraints capture kinetic energy functions previously assigned to airbag systems. Fleet procurement managers exhibit highest price sensitivity, while premium OEM platform engineers prioritize deployment timing precision over per-unit cost.
Supply Chain Analysis
Polyamide 6.6 textile weaving capacity concentrated among three German suppliers creates a chokepoint for cushion production scalability. Pyrotechnic inflator manufacturing draws from Saxony's gas generator facilities, nitroguanidine chemical supply from specialized European producers, and electronic control unit fabrication from Continental's chassis electronics network. Single-source vulnerability in pyrotechnic chemist talent pools threatens knowledge transfer continuity as retiring specialists exit the workforce. Distribution runs through Tier-1 integrated restraint assemblers for volume platforms, with direct OEM contracting displacing bundled agreements in premium multi-chamber procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seatbelt-integrated restraint systems advancing in entry segments present a direct substitution threat that incumbent airbag suppliers must neutralize through adaptive deployment differentiation. Incumbents face compressed margins in commoditized frontal systems while opportunity concentrates in algorithmically transparent ECU architectures.
For Market Incumbents: Consolidate pyrotechnic manufacturing depth in Saxony through captive retention of retiring specialist knowledge and backward integration into polyamide 6.6 weaving capacity. Secure KBA type-approval pipeline advantages by pre-validating pedestrian protection architectures ahead of regulatory enforcement timelines. Prioritize multi-chamber ECU development to outpace seatbelt-integrated restraint displacement in C-segment and above classifications.
For New Entrants and Emerging Players: Differentiate on EU AI Act-compliant sensor fusion transparency, targeting direct OEM contracting channels in Bavarian and Baden-Württemberg premium engineering clusters. Underdeveloped airbag textile weaving capacity in Munich's northern manufacturing belt offers the most penetrable geographic white space. Lead with algorithmic auditability as the go-to-market wedge against incumbent black-box ECU architectures.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors ECU-integrated suppliers with homologation pipeline depth over pure-play pyrotechnic manufacturers. Long-term viability hinges on automated driving interior reconfiguration readiness across the next decade. Acquisition targets should display multi-chamber textile engineering capability paired with functional safety certification velocity. Watch Euro NCAP protocol evolution as the primary inflection signal for curtain and far-side system fitment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chamber Architecture Development | Enables zoned thorax-head protection for Stuttgart premium OEM 2027 platform cycles. |
| EU AI Act Compliance Investment | Creates first-mover eligibility for algorithmically transparent ECU-integrated contracts. |
| Pyrotechnic Talent Retention Programs | Secures nitroguanidine formulation continuity against Saxony specialist retirement waves. |
| Direct OEM Contracting Expansion | Displaces bundled Tier-1 agreements in Bavarian adaptive restraint procurement channels. |
| Polyamide 6.6 Weaving Capacity Addition | Reduces input vulnerability from three-supplier concentration in cushion production. |
Research Methodology
Operator-level perspectives from Tier-1 supplier procurement directors, OEM platform engineers, KBA homologation specialists, and aftermarket refurbishment technicians anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against KBA type-approval databases, UN ECE regulatory filings, Euro NCAP testing protocol documentation, and vehicle production registration data. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive safety system trade associations.
Sensitivity analysis around deployment timing requirements, pyrotechnic chemistry substitution rates, and regulatory protocol enforcement schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, vehicle classification, propulsion architecture, and regional production cluster. CAGRs derived from slope-interpolation between base and terminal year values, incorporating EV-specific crash pulse signatures and automated driving interior reconfiguration timelines as industry-specific forecast inputs.
Material uncertainties — KBA homologation timeline extensions, pyrotechnic chemist talent pool depletion, and seatbelt-integrated restraint technology advancement — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and OEM platform cycle cadence. Practitioners should keep alternative scenarios live as Euro NCAP testing protocol revisions and EU AI Act implementation guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market