
 Global Automotive Lidar Sensor Market | 2026-2036
Global Automotive Lidar Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Lidar Sensor Market Intelligence
The mandate for safer electric vehicles under frameworks like the EU Green Deal is hardening the requirement for advanced sensor suites. Luminar Technologies specializes in high-performance, long-range sensors targeting premium autonomous driving applications. Robert Bosch GmbH leverages its extensive Tier-1 supplier network to integrate lidar into broader ADAS platforms for mass-market vehicles. Hesai Group competes on manufacturing scale and cost-efficiency, particularly within its home market of China.
An automotive lidar sensor is an active remote sensing device that emits laser pulses to measure distances. Operating on Time of Flight (ToF) principles, these systems typically use near-infrared light around 905nm to generate a precise, three-dimensional point cloud of the vehicle's surroundings. Advanced Driver Assistance Systems (ADAS) represent the largest application segment by volume, driven by OEM integration. Within product types, solid-state lidar is gaining traction over mechanical versions, with MEMS-based designs leading this transition due to cost and durability advantages.
Regulatory bodies including the NHTSA in the United States and through UNECE regulations in Europe are defining performance standards for autonomous emergency braking, influencing sensor requirements. In parallel, China's MIIT sets guidelines for intelligent connected vehicles, creating a distinct market access pathway. The critical decision for suppliers now revolves around balancing sensor performance against the aggressive cost-down pressures from automotive OEMs.
Market Dynamics
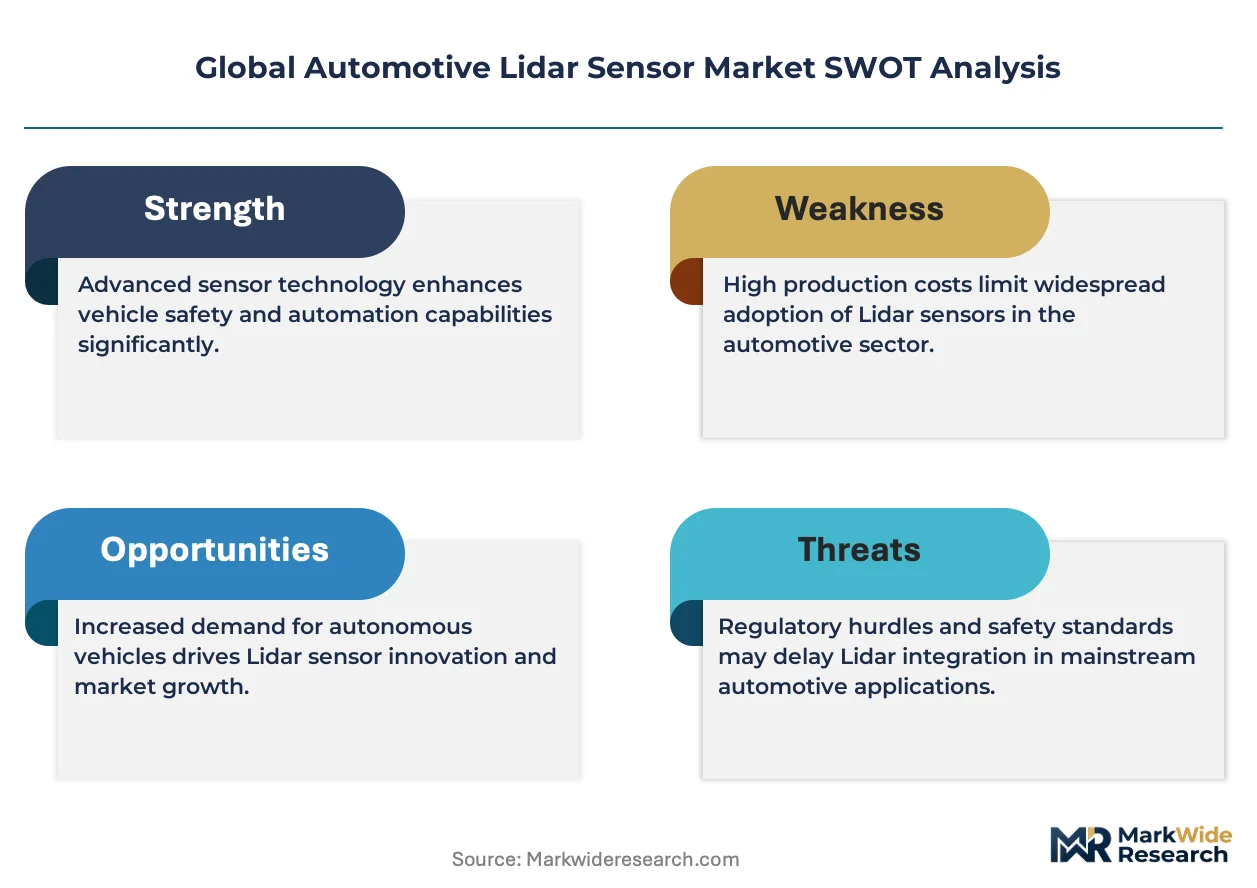
The central dynamic governing the automotive lidar sensor market is the conflict between the performance requirements for higher-level autonomous driving and the severe cost-down pressure exerted by mass-market vehicle OEMs. This tension forces innovation toward cost-effective, scalable solid-state architectures.
Growth Catalysts
- Regulatory Mandates:Frameworks like UNECE regulations for advanced emergency braking systems in Europe and MIIT guidelines for intelligent connected vehicles in China create direct demand for high-performance perception sensors, including lidar.
- Solid-State Technology:The maturation of MEMS-based solid-state lidar offers a compelling alternative to mechanical scanners, providing improved durability, smaller form factors, and a clear path to cost reduction for mass ADAS integration.
- Enhanced Safety Demand:Consumer and insurance industry pressure for vehicle safety features that exceed basic ADAS capabilities, particularly for vulnerable road user detection in complex urban settings, accelerates lidar adoption in premium and mainstream vehicles.
Market Restraints
- Material Costs:The high price of specialized components, such as indium gallium arsenide (InGaAs) photodetectors required for longer-wavelength 1550nm lidar systems, acts as a structural barrier to their widespread adoption in cost-sensitive vehicle segments.
- Sensor Interference:In environments with a high density of lidar-equipped vehicles, signal crosstalk between sensors can degrade performance or generate false readings, a technical limitation that requires complex mitigation strategies.
- Fragmented Standards:The lack of a single, globally harmonized set of performance and testing standards from bodies like NHTSA, UNECE, and MIIT forces suppliers to pursue costly and time-consuming validation for each distinct regional market.
Strategic Opportunities
- Industrial Automation:Adapting automotive-grade lidar for non-automotive applications, such as autonomous mobile robots in logistics centers or obstacle detection on port and mining equipment, opens new revenue streams with different cost and performance criteria.
- Raw Sensor Fusion:The convergence of lidar, radar, and camera data at the raw signal level, rather than object-level, presents an opportunity for suppliers to offer integrated perception systems that deliver superior environmental modeling for ADAS.
- Commercial Vehicle Fleets:Targeting the trucking and logistics sectors in markets like Brazil and India offers a significant opportunity, as fleet operators invest in advanced safety systems to reduce accidents, lower insurance premiums, and improve operational uptime.
Industry Challenges
- Software Integration Complexity:Integrating lidar point cloud data into an automaker's existing software stack and vehicle ECU architecture is a significant challenge, demanding specialized software engineering talent and extensive validation cycles.
- Data Format Standardization:The absence of a universal standard for point cloud data formats creates friction for OEMs and Tier-1s, complicating software development and limiting interoperability between sensors from different vendors.
- Manufacturing Scalability:Achieving automotive-grade quality, reliability, and cost targets at production volumes of millions of units per year requires substantial capital investment in automated assembly and calibration facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Lidar Sensor Market |
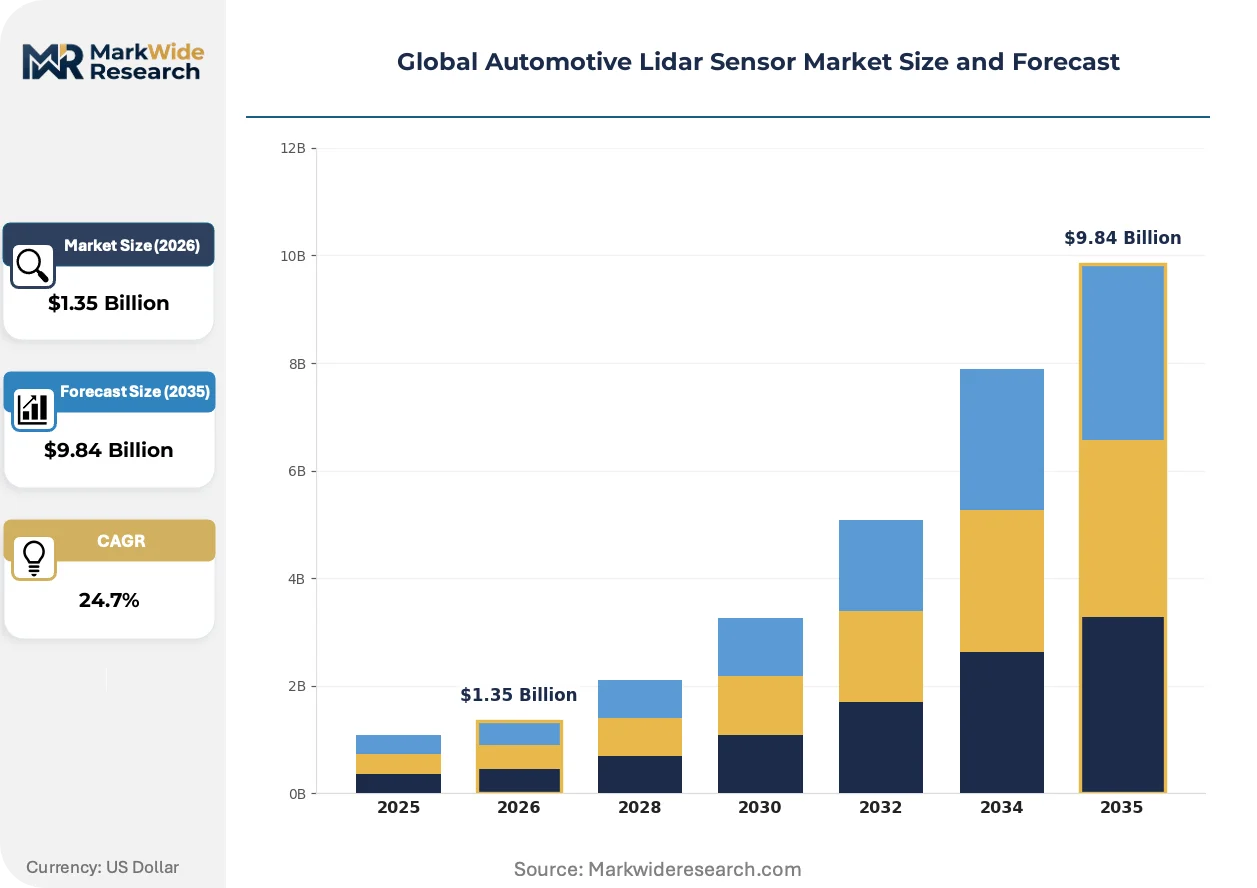
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $9.84 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State, MEMS, Frequency Modulated Continuous Wave, Flash Application: Autonomous Driving, Advanced Driver Assistance Systems, Mapping, Robotics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Time of Flight, Phase Shift, Coherent, Hybrid |
| Companies Covered | Hesai Group, Luminar Technologies, RoboSense Technology, Seyond, Velodyne Lidar, Innoviz Technologies, Continental AG, Denso Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Lidar Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from a technology-push dynamic, where capabilities were paramount, to a market-pull model. Application-specific requirements, particularly for cost, reliability, and integration ease in mass-market ADAS, now dictate the direction of product development.
Frequency-Modulated Continuous-Wave (FMCW) lidar represents a significant technological evolution, measuring both distance and velocity directly for every point in the cloud. Developers targeting Level 4 and Level 5 autonomous systems are adopting this approach for its inherent immunity to interference and its ability to reject sun glare. This technology is unifying the measurement of range and instantaneous velocity within a single hardware modality, reducing the computational load for sensor fusion algorithms.
Regulatory bodies are establishing more stringent performance benchmarks for automated driving features. The National Highway Traffic Safety Administration (NHTSA) in the United States, for example, is updating its New Car Assessment Program to include more rigorous testing of automatic emergency braking systems, especially in darkness. This action compels automakers to adopt sensors like lidar that function reliably in poor lighting. The passenger vehicle segment is most impacted, with development prioritizing sensor suites that can secure top safety ratings.
Automotive OEMs are fundamentally changing their purchasing behavior as they transition toward software-defined vehicle architectures. This move displaces the traditional model of buying a self-contained sensor with a new demand for access to raw sensor data streams. Carmakers want to deploy their own proprietary perception software and update it remotely, a trend most visible within premium electric vehicle platforms in Germany and China.
Global Automotive Lidar Sensor Market Segmentation
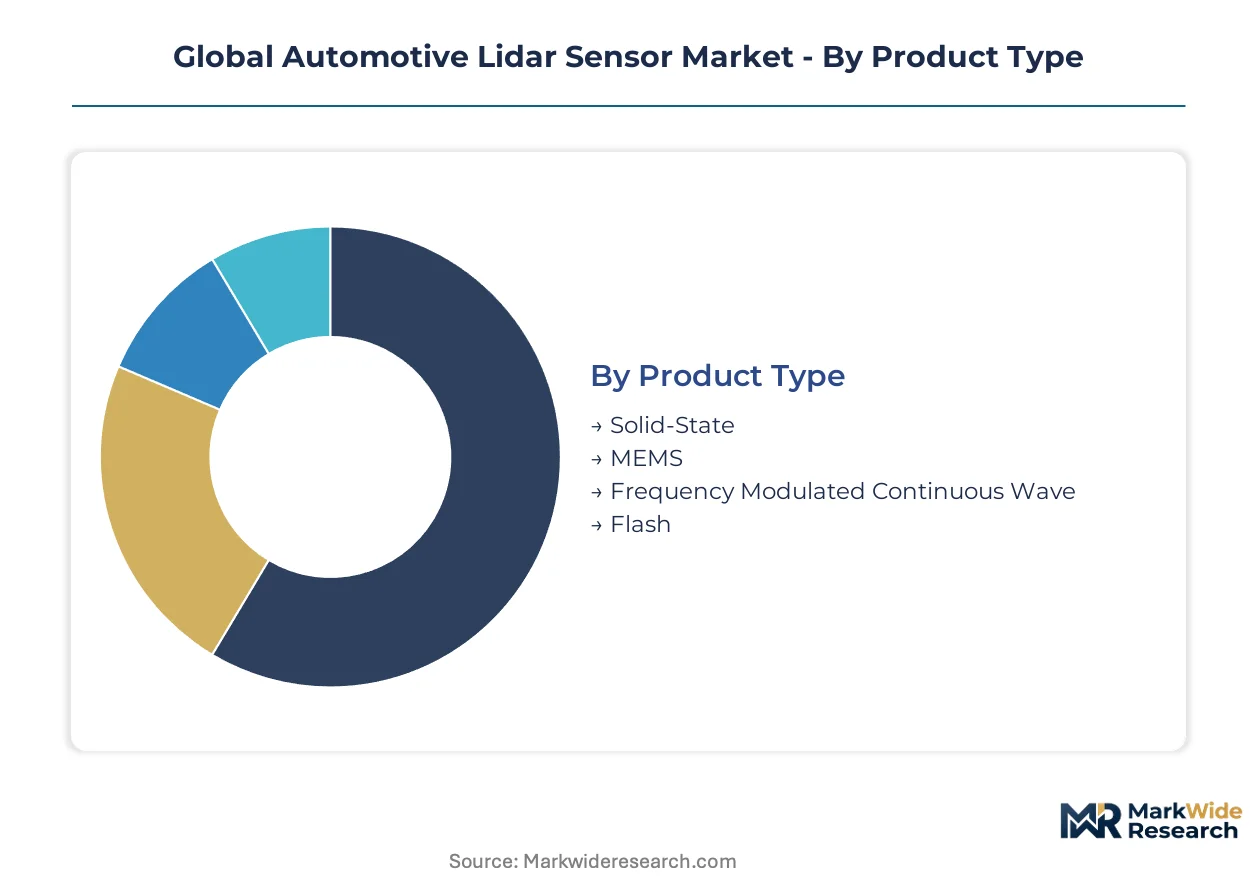
The global automotive lidar sensor market is intricately segmented across various dimensions, reflecting the diverse technological pathways and application requirements driving its expansion. Understanding these segmentations is critical for suppliers to align product development with specific market needs and for automakers to select optimal sensor suites.
Product Type:
Buyer differentiation in product type often hinges on a trade-off between sensor performance, form factor, and long-term cost of ownership.
- Solid-State:These lidar units utilize micro-electromechanical systems (MEMS) or optical phased arrays, eliminating moving parts to enhance durability and reduce size. Demand concentrates in mass-market Advanced Driver Assistance Systems (ADAS) due to their cost-effectiveness and robustness.
- Frequency Modulated Continuous Wave (FMCW):This advanced technique measures both distance and instantaneous velocity directly, offering immunity to interference and improved performance in challenging conditions. Developers targeting Level 4 and Level 5 autonomous systems prioritize this for its superior data quality.
- MEMS:Micro-electromechanical systems-based designs enable compact, robust lidar sensors through tiny, steerable mirrors.
- Flash:Flash lidar illuminates an entire scene simultaneously with a single laser pulse, capturing a 3D image without mechanical scanning.
Solid-State lidar leads volumes today; Frequency Modulated Continuous Wave is gaining share fastest.
Application:
The volume of deployment across different applications reflects varying levels of vehicle autonomy and safety integration.
- Advanced Driver Assistance Systems:This segment includes features like automatic emergency braking, adaptive cruise control, and lane-keeping assistance, leveraging lidar for enhanced perception. OEM integration drives significant demand for these systems to meet regulatory mandates and consumer safety expectations.
- Autonomous Driving:This application involves fully self-driving vehicles, requiring high-performance, long-range lidar sensors for comprehensive environmental understanding and redundancy. Premium electric vehicle platforms in Germany and China are key areas for this development.
- Mapping:Lidar sensors are used for creating highly detailed 3D maps essential for autonomous vehicle navigation and infrastructure planning.
- Robotics:This segment includes the use of automotive-grade lidar in autonomous mobile robots for industrial automation and logistics.
Advanced Driver Assistance Systems applications dominate current deployments, with Autonomous Driving solutions showing rapid expansion.
End User:
Procurement patterns for lidar sensors vary significantly among different end-user segments, reflecting distinct integration capabilities and supply chain relationships.
- OEMs:Automotive Original Equipment Manufacturers integrate lidar sensors directly into vehicle designs during the production phase, often requiring deep collaboration with sensor suppliers. These manufacturers demand sensors that meet stringent automotive-grade quality and reliability standards.
- Tier-1 Suppliers:These companies act as intermediaries, integrating lidar sensors with other components into complete ADAS modules or perception systems for OEMs. Robert Bosch GmbH exemplifies this model, leveraging its network to deliver integrated solutions for mass-market vehicles.
- Aftermarket Providers:These entities supply lidar systems for installation in vehicles after their initial sale, often for specialized or upgrade purposes.
- Fleet Operators:Commercial vehicle fleets, particularly in trucking and logistics, adopt lidar for improved safety, accident reduction, and operational efficiency.
OEMs maintain significant influence over product specifications, while Tier-1 Suppliers are crucial for broader market integration.
Technology:
The maturity and performance characteristics of sensor technologies dictate their suitability for specific automotive lidar applications.
- Time of Flight:This principle measures the time taken for a laser pulse to travel to an object and return, forming the basis for many current lidar systems. Near-infrared light around 905nm is commonly used for generating precise 3D point clouds.
- Coherent:Coherent detection methods, such as FMCW, offer advantages like direct velocity measurement and enhanced interference rejection by analyzing the phase and frequency shift of the returned light. This technology reduces the computational load for sensor fusion algorithms.
- Phase Shift:Phase shift technology calculates distance by measuring the phase difference between emitted and received continuous-wave laser signals.
- Hybrid:Hybrid systems combine aspects of different lidar technologies, such as mechanical scanning with solid-state components, to balance performance and cost.
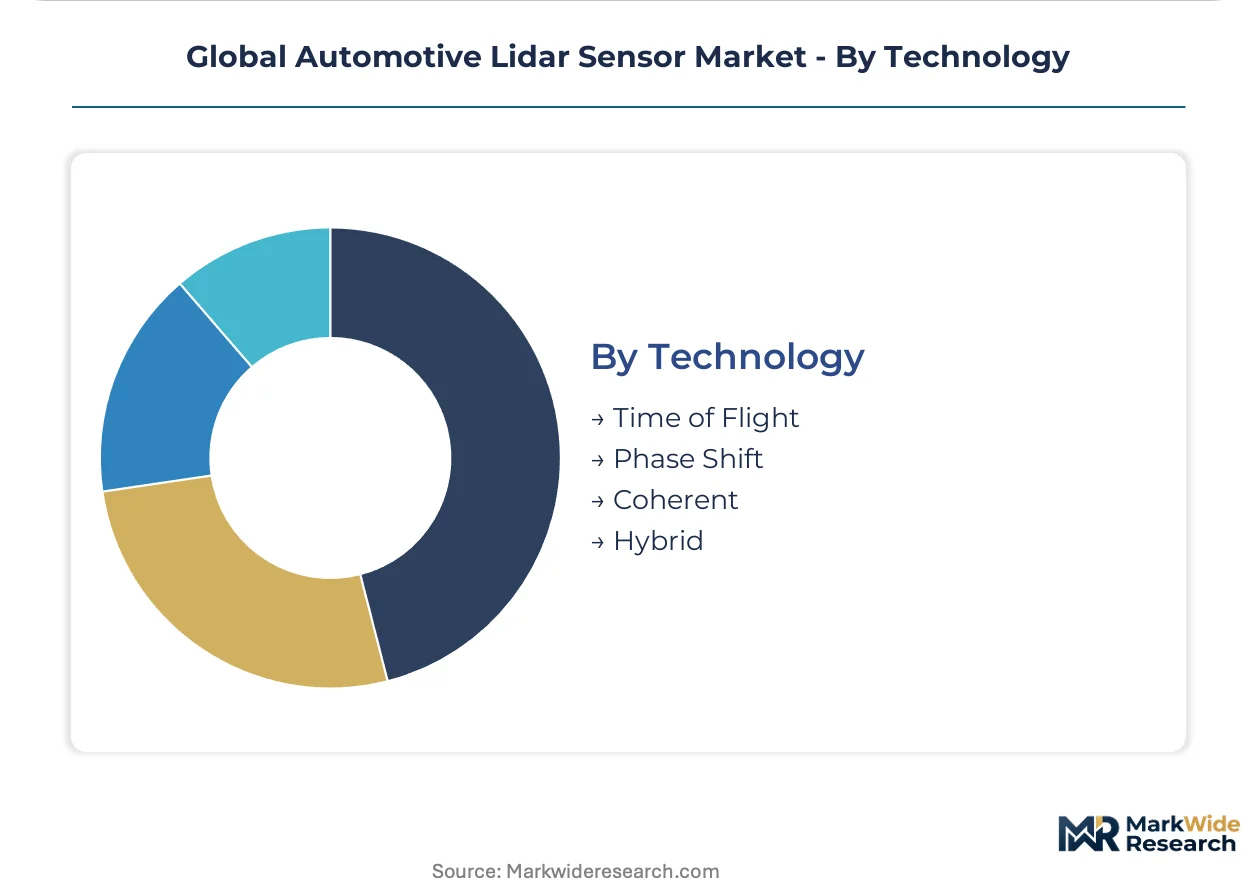
Time of Flight technology forms the foundational basis for many current systems, with Coherent approaches presenting a strong future trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global Automotive Lidar Sensor Market has its historical foundations in advanced sensing technologies developed for defense and industrial applications. Early innovations in optical ranging systems paved the way for automotive integration. Today, the market's expansion is driven by the global push for enhanced vehicle safety and autonomy.
China
Demand for intelligent connected vehicles in China is significant, fueled by domestic automotive production. The MIIT sets guidelines for intelligent connected vehicles, influencing sensor requirements and market access. Shanghai and the Yangtze River Delta region concentrate significant automotive and technology development, fostering innovation and adoption.
United States
The United States market sees strong demand for advanced safety features, driven by consumer expectations and insurance industry pressure. NHTSA is updating its New Car Assessment Program to include more rigorous testing for automatic emergency braking systems. Silicon Valley and Detroit are hubs for autonomous vehicle research and sensor development, attracting substantial investment.
Germany
Germany exhibits strong demand for high-performance lidar sensors, especially in premium autonomous driving applications. The EU Green Deal framework emphasizes safer electric vehicles, hardening sensor requirements for advanced perception suites. Stuttgart and Munich host major automotive OEMs and Tier-1 suppliers, driving innovation in sensor integration.
Japan
Japanese automakers integrate advanced ADAS features, seeking high reliability and compact sensor designs for their vehicles. METI initiatives support the development of next-generation automotive technologies, including advanced lidar systems. Tokyo and Nagoya are key centers for automotive research and development and manufacturing excellence, fostering new partnerships.
India
India presents a growing opportunity for lidar adoption in commercial vehicle fleets to improve safety and operational efficiency. The PLI scheme for the automotive sector encourages domestic manufacturing and advanced technology integration. Pune and Chennai are emerging as significant automotive manufacturing and engineering hubs, attracting sensor suppliers.
Global Automotive Lidar Sensor Market Key Industry Players
Premium-margin players sit above commodity-margin players across performance capabilities, reflecting diverse market needs for automotive lidar sensors. The market exhibits a tiered structure, with high-performance specialists targeting advanced autonomous driving, mass-market integrators focusing on ADAS, and cost-efficient volume producers. Strategic partnerships between sensor manufacturers and automotive OEMs are common competitive moves to secure design wins. Technology licensing and capacity expansion also remain critical focuses for market share gains and scale.
Within the high-performance specialist tier, Luminar Technologies represents a focus on long-range sensors crucial for premium autonomous driving applications. Robert Bosch GmbH, a German-based GmbH, occupies a position as a prominent Tier-1 supplier, leveraging its extensive network to integrate lidar into broader ADAS platforms for mass-market vehicles. Hesai Group, a Chinese-based Group, anchors the cost-efficient volume production segment, competing on manufacturing scale and affordability, particularly within its home market of China. These companies exemplify the varied strategic approaches within the automotive lidar sensor market.
| Leading Market Players |
|---|
| Hesai Group |
| Luminar Technologies |
| RoboSense Technology |
| Seyond |
| Velodyne Lidar |
| Innoviz Technologies |
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Cost-focused volume producers, often backed by strategic national initiatives, exert downward pressure on pricing, which in turn drives supply chain optimization towards scalable, lower-cost components for mass-market automotive lidar sensors.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model for automotive lidar sensors. Price differentiation stems from sensor performance capabilities, particularly for Level 4 and Level 5 autonomous systems, and the manufacturing scale of the supplier. Significant cost-down pressure from automotive OEMs drives pricing softness, especially for mass-market Advanced Driver Assistance Systems integration. Developers of premium autonomous driving solutions exhibit less price sensitivity, prioritizing advanced data quality and reliability.
Supply Chain Analysis
Specialized component supply for automotive lidar, particularly indium gallium arsenide (InGaAs) photodetectors and MEMS mirrors, rests on a concentrated global base. Key manufacturing and design hubs are found in China, Germany, and the United States. High material costs for these specialized components act as a structural barrier, impacting overall system affordability. Distribution primarily runs through Tier-1 suppliers who integrate lidar sensors into broader ADAS platforms for automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive lidar sensor market functions as a stable compounder, driven by the continuous demand for enhanced vehicle perception in Advanced Driver Assistance Systems. This foundational safety requirement ensures consistent, long-term expansion.
For Market Incumbents:Extend existing Tier-1 supplier relationships to deepen integration into OEM software stacks, countering the threat of in-house perception software development by automakers. Invest significantly in manufacturing scalability and automated assembly to meet automotive-grade quality at high volumes, mitigating aggressive cost-down pressures. Prioritize the development of cost-effective solid-state architectures to maintain market share against emerging competitors.
For New Entrants and Emerging Players:A significant price-point gap exists between high-performance, premium lidar and cost-constrained mass-market ADAS solutions. Target the underpenetrated commercial vehicle fleets in markets like India, focusing on robust, cost-efficient solid-state designs. Offer integrated perception systems through raw sensor fusion, providing a superior environmental model for ADAS applications. Develop specialized lidar for industrial automation, leveraging automotive-grade reliability for new revenue streams.
For Investors and Strategic Acquirers:Valuations sit cheapest among pure-play hardware manufacturers struggling with OEM cost pressures, yet offer long-term viability in core perception technology. Seek out firms with proprietary solid-state lidar technology or robust software integration capabilities to secure future design wins. The signal to watch is the widespread adoption of a universal standard for point cloud data formats, which will unlock greater interoperability and market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Allows OEMs to deploy proprietary perception software and enable remote updates. |
| Capacity Expansion for Solid-State Lidar | Addresses aggressive cost-down pressures and meets mass-market ADAS volume demands. |
| Strategic Partnership with Tier-1 Supplier | Integrates lidar into broader ADAS platforms, securing market access for mass-market vehicles. |
| FMCW Technology Licensing | Accelerates development of immunity to interference and direct velocity measurement capabilities. |
| Industrial Automation Diversification | Opens new revenue streams by adapting automotive-grade sensors for non-automotive applications. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each key region informing the analysis. This involved extensive interviews with OEM procurement leads, Tier-1 system architects, lidar sensor R&D directors, and automotive safety regulators. Secondary validation drew from NHTSA reports, UNECE regulations, MIIT guidelines, and specialized automotive industry white papers. A rigorous bottom-up market sizing was triangulated with top-down validation for accuracy.
Rate-of-change decomposition formed the core analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and vehicle autonomy level. Compound annual growth rates were derived from historical trends, technology adoption curves, and regulatory impact assessments. Key forecast inputs included global vehicle production volumes and ADAS penetration rates across different vehicle segments.
Caveats apply where rapid technological advancements or unforeseen regulatory shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding technology maturation and market adoption rates. Sensor interference challenges and fragmented regulatory standards represent key triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Lane Departure Warning System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market