
 Automotive Anti-Lock Braking System Market | 2026-2036
Automotive Anti-Lock Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Anti-Lock Braking System Market Intelligence
The bundling of anti-lock braking systems with broader advanced driver-assistance systems (ADAS) is broadening the technology's accessibility in mid-range vehicles. Continental AG leverages its extensive ADAS portfolio to offer integrated safety packages to automakers. Bosch sustains its market leadership through significant R&D investment in sensor fusion and electronic control units. ZF Friedrichshafen AG competes by specializing in modular and scalable braking solutions for a diverse range of vehicle platforms.
An automotive anti-lock braking system is an active safety feature designed to prevent wheel lock-up during hard braking. The system functions by rapidly modulating brake pressure via a hydraulic unit, allowing the driver to maintain steering control. Passenger cars constitute the largest end-user segment by volume. The heavy-duty trucks category, however, is expanding rapidly due to safety mandates, with electronic control technology becoming the standard.
Vehicle safety regulations from bodies like the US National Highway Traffic Safety Administration (NHTSA) and Germany's Kraftfahrt-Bundesamt (KBA) mandate ABS in new passenger cars. China's GB standards for vehicle safety extend similar requirements to commercial vehicles, driving adoption. The critical decision for suppliers now revolves around balancing the cost of advanced sensor integration against the performance demands of autonomous driving platforms.
Market Dynamics
The central force shaping the market is the mandatory integration of anti-lock braking systems into broader electronic stability control and advanced driver-assistance systems, a shift driven by global regulatory bodies like the NHTSA and through China's GB standards.
Growth Catalysts
- Regulatory Mandates:China's GB standards requiring advanced braking systems in new commercial vehicles are a significant catalyst, compelling adoption across the world's largest automotive manufacturing market and influencing supply chains.
- ADAS Integration:The bundling of ABS with ADAS suites makes the technology accessible in mid-range passenger cars, expanding the addressable market beyond premium vehicles and basic safety compliance.
- Commercial Vehicle Safety:Demand within the heavy-duty trucks segment is expanding rapidly, propelled by regulations in North America and Europe aimed at reducing accidents involving large commercial vehicles.
Market Restraints
- Sensor Cost:The high cost of advanced sensors, such as high-resolution cameras and radar required for sensor fusion in autonomous-ready ABS, limits their deployment in economy vehicle segments.
- ECU Supply Concentration:The market's reliance on a concentrated number of semiconductor suppliers for electronic control units (ECUs) creates vulnerability to supply chain disruptions and price volatility.
- Integration Complexity:Technical challenges in ensuring seamless software and hardware interoperability between ABS modules and diverse ADAS platforms from different vendors can delay vehicle development cycles.
Strategic Opportunities
- EV-Specific Systems:There is a distinct opportunity in developing ABS solutions specifically for electric vehicles, focusing on integration with regenerative braking to maximize efficiency and enhance stability.
- Technology Convergence:The fusion of ABS sensor data with vehicle-to-everything (V2X) communication systems presents an opportunity to create predictive braking applications that react to hazards beyond the vehicle's line of sight.
- Emerging Market Fleets:Commercial vehicle fleets in underpenetrated regions like Southeast Asia and Latin America represent a significant growth vector as local safety standards begin to align with international norms.
Industry Challenges
- Software Talent Scarcity:A shortage of software engineers with specialized expertise in real-time control systems and sensor fusion algorithms hinders the pace of innovation and product development for next-generation braking systems.
- Validation Timelines:The lengthy and expensive validation and certification processes required by authorities like Germany's KBA for any modification to safety-critical systems create a high barrier to entry and slow down updates.
- System Interoperability:Ensuring flawless communication and function between the core ABS and a growing array of third-party ADAS features on a single vehicle platform remains a persistent integration challenge for automakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Anti-Lock Braking System Market |
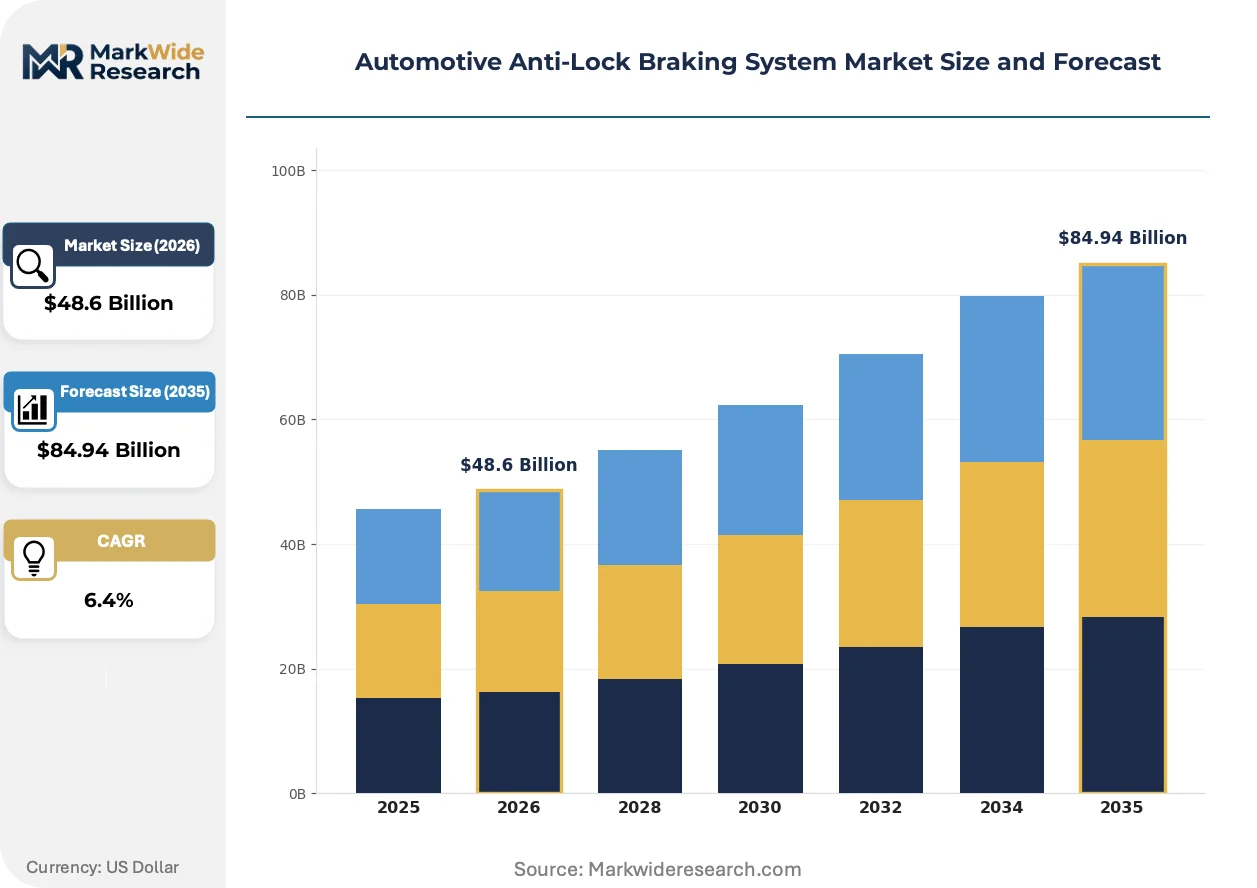
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Electromechanical Systems, Hydraulic Systems Technology: Active Braking, Passive Braking, Electronic Control, Sensor Integration End User: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Application: Off-Road Vehicles, On-Road Vehicles, Emergency Braking, Stability Control |
| Companies Covered | Denso Corporation, Autoliv Inc., Bosch, Brembo S.p.A., Aisin Corporation, Continental AG, Hyundai Mobis, Mando Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Anti-Lock Braking System Market Strategic Shifts & Innovations
The evolution of ABS is now defined by its integration into software-centric vehicle architectures, transforming it from a standalone hardware device into a dynamic, updatable component of the vehicle's central nervous system.
Scalable braking control units allow automakers to manage functions from basic anti-lock braking to full stability control on a single hardware platform. Mid-range and economy vehicle segments are seeing rapid adoption of these systems. This technology is modularizing the vehicle's safety stack, enabling feature differentiation through software rather than costly hardware changes.
Global standards, such as UN Regulation No. 140 concerning Electronic Stability Control, are creating a harmonized floor for vehicle safety. Because ESC requires an underlying ABS, the regulation accelerates the adoption of more advanced, integrated braking systems. This shift most impacts passenger car segments in emerging economies that are signatories to the UN's World Forum for Harmonization of Vehicle Regulations.
Purchasing decisions for both consumers and commercial fleets are increasingly influenced by vehicle safety ratings from programs like Euro NCAP. This trend is displacing the isolated evaluation of ABS in favor of assessing comprehensive safety packages where ABS is a foundational element. The effect is most pronounced in North America and Europe, where five-star safety ratings are a critical marketing differentiator for automakers.
Automotive Anti-Lock Braking System Market Segmentation
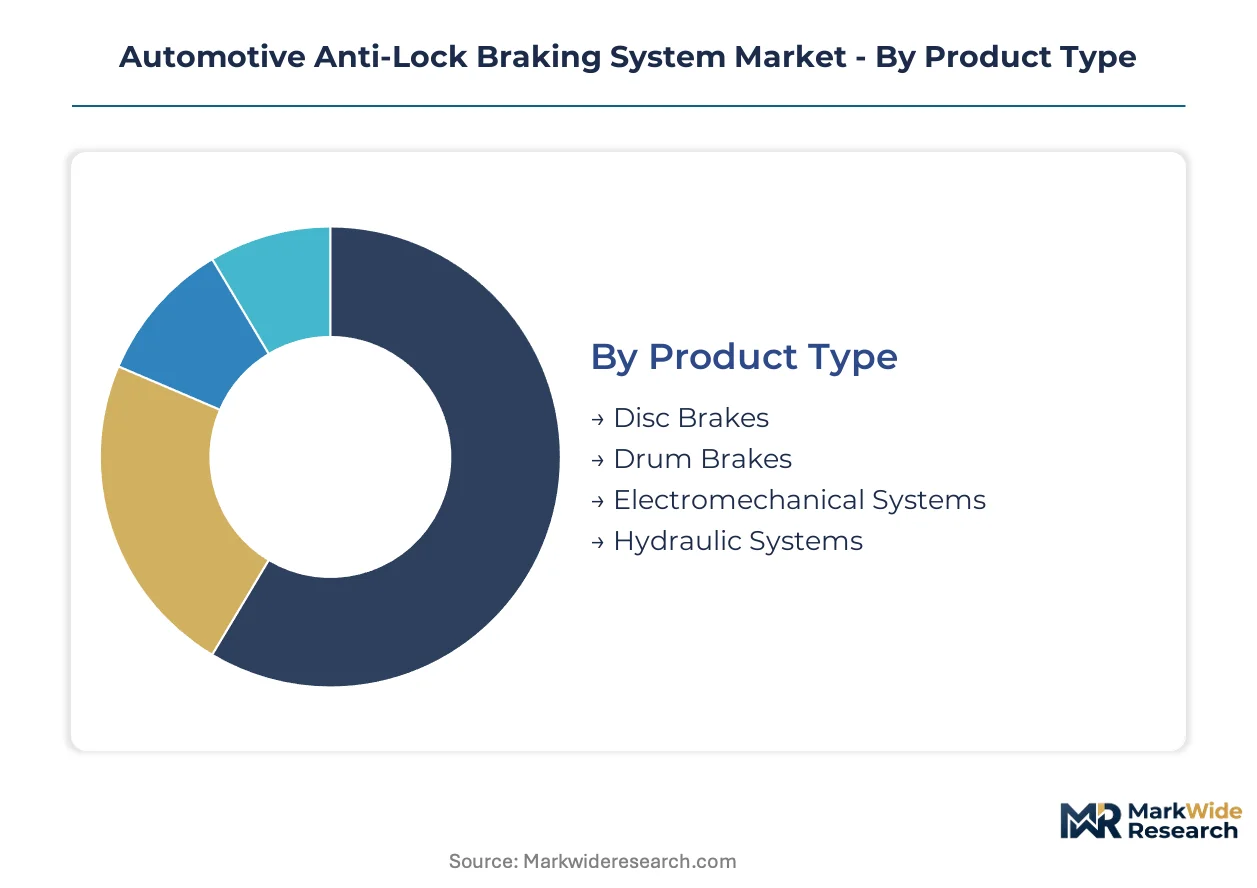
Segmentation clarifies the diverse requirements and market dynamics for anti-lock braking systems, revealing how technological advancements and regulatory pressures shape adoption across various vehicle types. Understanding these segments assists automakers and suppliers in targeting development efforts and market strategies.
Product Type:
Vehicle manufacturers prioritize product type based on the required braking performance and integration complexity for specific vehicle models.
- Disc Brakes:This friction-based system uses calipers to squeeze pads against a rotating disc, effectively converting kinetic energy into heat. Demand concentrates in passenger cars and light commercial vehicles due to superior heat dissipation and consistent performance under varied conditions.
- Hydraulic Systems:These systems utilize incompressible fluid pressure to transmit force from the brake pedal to the calipers or wheel cylinders, forming the core of most ABS setups. China's vast automotive manufacturing base drives demand for these foundational systems in new vehicle production across multiple segments.
- Electromechanical Systems:These integrate electric motors to actuate braking, offering precise control and significant potential for energy recuperation in electric vehicles.
- Drum Brakes:An older friction-based system with shoes pressing against a rotating drum, still found in some rear axles and economy vehicle segments due to lower cost.
Disc Brakes leads on scale; Electromechanical Systems leads on momentum.
Technology:
Application requirements dictate the selection of anti-lock braking system technologies, influencing system sophistication and cost.
- Electronic Control:This technology employs sensors, an electronic control unit (ECU), and hydraulic modulators to prevent wheel lock-up during sudden braking. Demand is high across all vehicle segments due to global regulatory mandates from bodies like the US National Highway Traffic Safety Administration (NHTSA).
- Sensor Integration:This involves combining data from wheel speed sensors and other vehicle dynamics sensors for enhanced braking and stability functions. Commercial vehicle safety regulations in Europe, particularly those impacting heavy-duty trucks, drive demand for advanced sensor suites.
- Active Braking:Systems that can autonomously intervene to apply brakes, often forming a critical component of broader advanced driver-assistance functionalities.
- Passive Braking:This refers to basic anti-lock braking functionality without active intervention beyond preventing wheel lock, serving as a fundamental safety feature.
Electronic Control technology dominates the market due to its foundational role in modern safety systems, while Sensor Integration is experiencing rapid expansion.
End User:
Volume and use-case characteristics define the anti-lock braking system requirements for different end-user segments.
- Passenger Cars:Individual consumer vehicles represent the largest volume segment for anti-lock braking systems. Global safety regulations, such as those from Germany's Kraftfahrt-Bundesamt (KBA), ensure widespread adoption in this category.
- Heavy-Duty Trucks:These large commercial vehicles are subject to stringent safety mandates and demanding operational conditions, requiring robust braking solutions. North American and Chinese regulations compel advanced ABS integration to reduce accident rates involving large vehicles.
- Commercial Vehicles:This segment encompasses vans, buses, and light commercial vehicles, benefiting from similar safety mandates and technological advancements as passenger cars.
- Motorcycles:Two-wheeled vehicles where anti-lock braking systems significantly improve rider safety and stability, particularly during emergency braking maneuvers.
Passenger Cars represent the largest end-user segment, with Heavy-Duty Trucks showing significant growth potential.
Application:
The operating environment and primary function determine the anti-lock braking system application.
- On-Road Vehicles:This represents the primary application for anti-lock braking systems, covering all vehicles operating on public roads. Regulatory compliance in emerging markets like India and Brazil drives consistent demand for these systems.
- Stability Control:Anti-lock braking forms the foundational layer for electronic stability control systems, enhancing overall vehicle dynamics and accident prevention. Integration with broader advanced driver-assistance systems in mid-range vehicles is a key driver.
- Emergency Braking:This specific anti-lock braking functionality optimizes braking performance during sudden stops, often integrated with predictive ADAS features.
- Off-Road Vehicles:Vehicles designed for challenging terrain require specialized anti-lock braking calibrations for effective traction management and control.
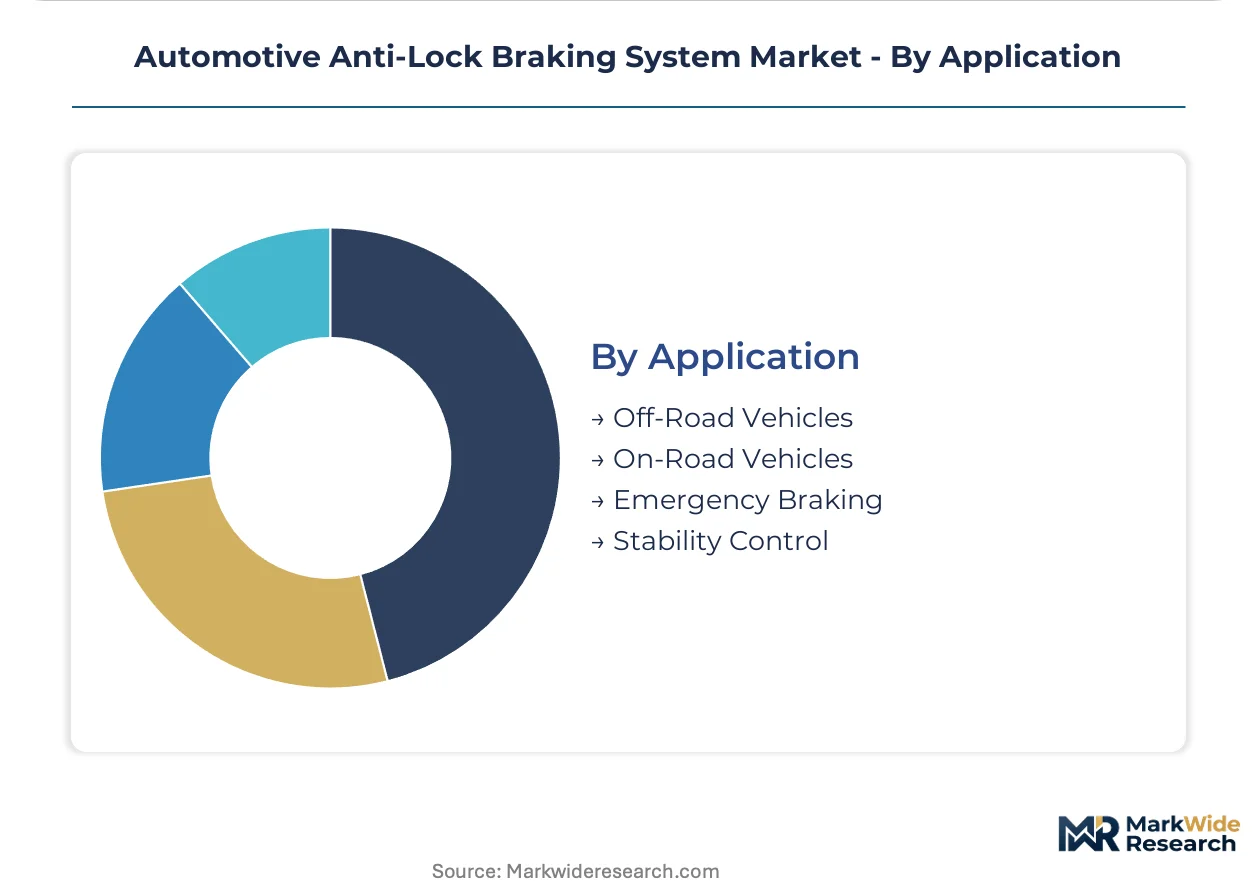
On-Road Vehicles constitute the largest application area, with Stability Control seeing continuous enhancement through ADAS integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive industry's foundational developments in Europe and North America initially scaled anti-lock braking system technologies. Early safety innovations in these regions established regulatory precedents that later influenced global adoption. This historical lineage continues to shape market dynamics and technological advancements worldwide.
Germany
Demand for advanced anti-lock braking systems in Germany stems from its robust premium automotive manufacturing base and stringent safety standards. The Kraftfahrt-Bundesamt (KBA) mandates comprehensive safety features for new vehicles, including advanced ABS and electronic stability control. Automotive clusters in regions like Bavaria and Baden-Württemberg drive innovation in integrated braking and ADAS solutions.
United States
The United States market for anti-lock braking systems is driven by a large consumer vehicle segment and commercial fleet safety requirements. The US National Highway Traffic Safety Administration (NHTSA) enforces regulations requiring ABS and electronic stability control in all new passenger vehicles. Detroit, Michigan, remains a central hub for automotive R&D and manufacturing, influencing braking system integration.
China
China's vast vehicle production volume and evolving safety regulations are significant demand drivers for anti-lock braking systems. The country's GB standards increasingly mandate advanced braking technology, particularly for commercial vehicles. Manufacturing centers in the Yangtze River Delta and Pearl River Delta are crucial for the production and supply of these systems.
Japan
Technological sophistication and a focus on vehicle safety define the Japanese anti-lock braking system market. Regulations from the Ministry of Land, Infrastructure, Transport and Tourism (MLIT) encourage the adoption of advanced driver-assistance features that rely on robust braking. Major automotive manufacturers in Aichi Prefecture and the Kanto region are at the forefront of developing next-generation ABS.
India
India's expanding automotive market and increasing focus on road safety are fueling demand for anti-lock braking systems. The Bureau of Indian Standards (BIS) has introduced norms making ABS mandatory for most new two-wheelers and passenger cars. Production hubs in Chennai and Pune are rapidly scaling up local manufacturing capabilities for these essential safety components.
Automotive Anti-Lock Braking System Market Key Industry Players
Premium-margin players sit above commodity-margin players across the technology and integration sophistication dimension. The market structure for anti-lock braking systems is tiered, with established automotive suppliers dominating the core component segments. Key strategic archetypes include integrated safety system providers, specialized braking technology developers, and regional component manufacturers. Strategic partnerships and significant R&D investment are dominant competitive moves.
Among the integrated safety system providers, Bosch and Continental AG exemplify companies offering extensive ADAS portfolios that incorporate anti-lock braking as a foundational element. ZF Friedrichshafen AG represents a specialized braking technology developer, focusing on modular and scalable solutions for diverse vehicle platforms. These companies anchor advancements in sensor fusion and electronic control units, crucial for next-generation braking systems. Their offerings often cater to global automakers seeking comprehensive safety packages and advanced control capabilities.
| Leading Market Players |
|---|
| Denso Corporation |
| Autoliv Inc. |
| Bosch |
| Brembo S.p.A. |
| Aisin Corporation |
| Continental AG |
| Hyundai Mobis |
| Mando Corporation |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
The performance tier divergence between basic ABS and advanced ADAS-integrated braking systems shapes both pricing and supply chain configurations. This bifurcation influences component sourcing and final vehicle safety package costs.
Pricing Analysis
The contract-based long-term offtake model dominates anti-lock braking system pricing for OEMs. Price differentiation stems from the level of ADAS integration and the performance tier of the braking system, alongside volume scale. Pricing pressure stems from the high cost of advanced sensors and the concentrated supply of electronic control units. Economy vehicle segments are most price-sensitive, while premium passenger cars and heavy-duty trucks tolerate higher costs for enhanced safety features.
Supply Chain Analysis
Semiconductor supply for electronic control units largely rests on East Asian producers in China, Japan, and South Korea. Key component dependencies include high-resolution sensors and hydraulic modulators, often sourced from specialized Tier 1 suppliers. A structural risk is the market's reliance on a concentrated number of semiconductor suppliers, creating vulnerability to supply chain disruptions. Distribution runs through established automotive Tier 1 suppliers directly to global vehicle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a pronounced demand-shift towards premium specifications in advanced driver-assistance systems. These systems necessitate higher performance anti-lock braking components.
For Market Incumbents:Deploy targeted R&D investment into sensor fusion and electronic control unit capabilities to maintain market leadership. Incumbents like Bosch must integrate ABS technology seamlessly into broader ADAS portfolios to counter emerging specialized braking technology developers. Consolidate market share through strategic acquisitions of software talent to address the scarcity.
For New Entrants and Emerging Players:Cloud-based software development platforms offer a unique entry point for new entrants specializing in modular braking solutions. Target underpenetrated commercial vehicle fleets in Southeast Asia and Latin America, where local safety standards are evolving. A go-to-market angle involves offering scalable, cost-effective ABS modules compatible with diverse vehicle platforms.
For Investors and Strategic Acquirers:Consolidation pressure builds where advanced integration with ADAS becomes a core competitive differentiator. The market's long-term viability depends on continuous innovation in sensor fusion and software-defined braking. Seek acquisition targets with specialized expertise in electromechanical braking or EV-specific regenerative braking. A critical signal to watch is the pace of regulatory harmonization for autonomous driving platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Automakers gain flexibility to update braking features, enhancing vehicle safety ratings from Euro NCAP. |
| Capacity Addition in China | Suppliers meet growing demand for advanced braking systems driven by China's GB standards. |
| Platform Standardization | Manufacturers reduce development costs and complexity across diverse vehicle models. |
| Sensor Fusion R&D Partnership | Companies accelerate innovation in combining sensor data for predictive braking, crucial for ADAS. |
| Regenerative Braking Integration | Electric vehicle manufacturers enhance energy efficiency by optimizing ABS with recuperation. |
Research Approach
Bottom-up passenger car and heavy-duty truck modeling reconciled against top-down Tier 1 supplier tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 procurement leads, and regulatory affairs specialists provided qualitative insights. Secondary validation utilized vehicle production databases, NHTSA reports, and KBA safety mandates to ensure data integrity and market context.
Historical trendline analysis established foundational growth patterns, projecting market evolution across the analysis window. Segmentation dimensions modeled include vehicle class, technology sophistication, application environment, and regional regulatory frameworks. Compound annual growth rates were derived from a weighted average of historical performance and future market drivers. Key forecast inputs include projected vehicle production volumes and anticipated ADAS penetration rates.
The model assumes a particular technology adoption path; alternative pathways for electromechanical braking or V2X integration would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement and semiconductor supply stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market