
 Veterinary Video Endoscopy Market | 2026-2036
Veterinary Video Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Video Endoscopy Market Analytics
The EU Medical Device Regulation is shifting compliance burdens for veterinary-adapted human endoscopy systems sold across European markets. KARL STORZ SE & Co. KG anchors its position through captive optical manufacturing in Germany. Olympus Corporation extends its imaging sensor expertise from human healthcare into veterinary flexible platforms. Biovision Veterinary Endoscopy specializes in species-specific rigid endoscope designs for equine and exotic practices.
Veterinary video endoscopy encompasses camera-equipped insertion systems with working channels of 1.0–3.0 mm diameter, delivering 720p to 4K resolution through fiber-optic or digital sensor architectures for minimally invasive diagnostic and surgical intervention in animals. Flexible endoscopes command premium positioning in gastroenterology and pulmonology applications where airway and alimentary tract navigation demands steerable tip deflection. Digital imaging technology leads technology segmentation as CMOS sensor costs decline and software integration enables image capture, measurement, and telemedicine transmission. Wireless communication represents the fastest-growing technology segment, eliminating cable drag during lengthy equine or large-animal procedures.
FDA Center for Veterinary Medicine regulates device safety labeling while ISO 13485 quality management standards govern manufacturing processes for instruments crossing human and veterinary production lines. The EU MDR's heightened clinical evidence requirements extend to veterinary-adapted devices, compelling manufacturers to maintain dual regulatory files. Stakeholders must monitor convergence between human healthcare imaging standards and veterinary-specific reimbursement pathways as specialty practice consolidation accelerates equipment procurement decisions.
Market Dynamics
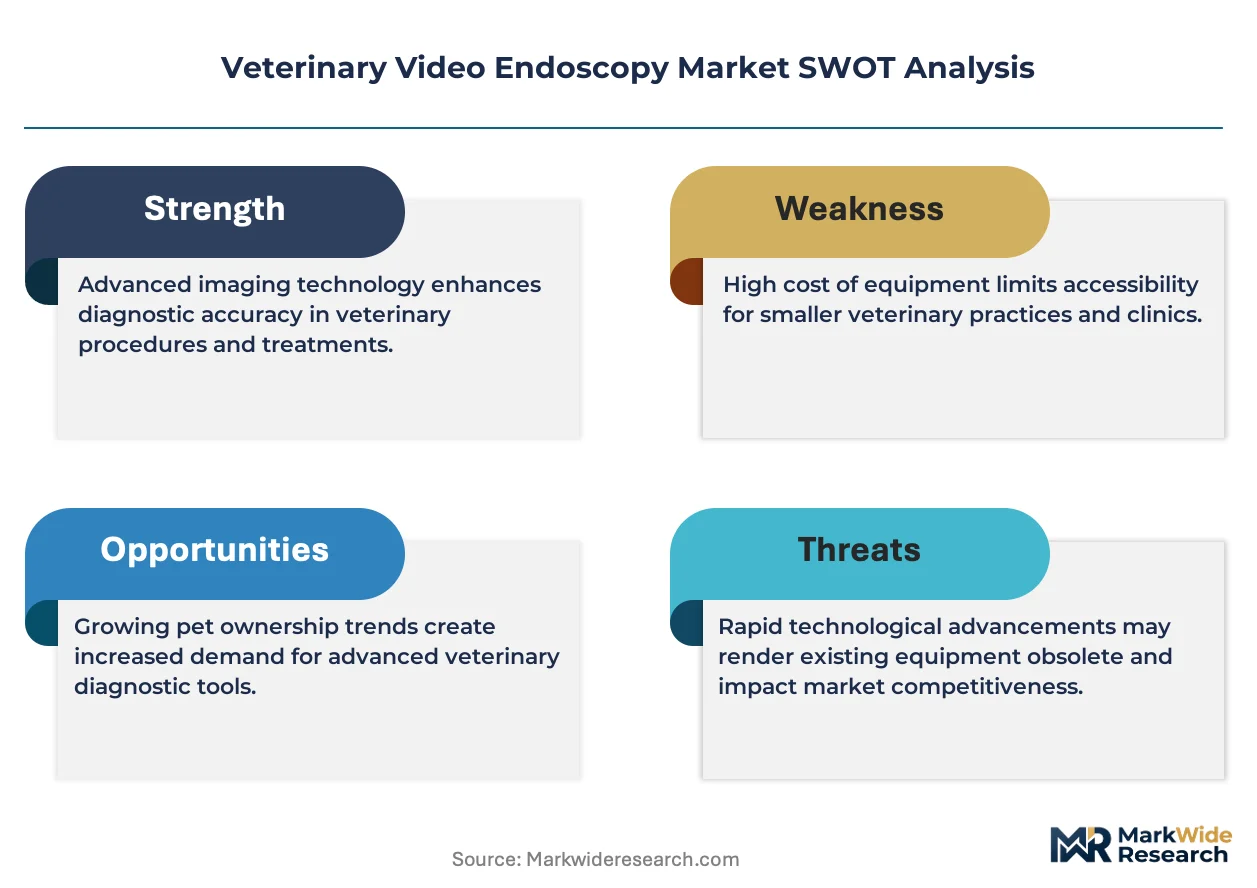
Specialist veterinary referral networks in the United States, Germany, and Japan are compressing equipment refresh cycles as CMOS sensor costs decline and software-integrated platforms enable telemedicine transmission. This demand concentration is forcing manufacturers to balance dual regulatory files for human-adapted veterinary systems while managing captive optical production investments.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:Stricter conformity assessments for veterinary-adapted devices are elevating barriers for marginal suppliers, consolidating procurement toward established manufacturers with dedicated regulatory affairs teams.
- CMOS Sensor Cost Decline:Digital imaging components are migrating from human healthcare production lines into veterinary platforms, enabling 4K resolution at price points accessible to mid-sized companion animal hospitals.
- Wireless Communication Modules:Elimination of cable drag during lengthy equine procedures is expanding addressable procedural volume in large-animal practices previously constrained by operator fatigue.
Market Restraints
- Dual Regulatory File Maintenance:ISO 13485 quality management standards governing cross-production-line instruments impose documentation burdens that disproportionately strain smaller manufacturers lacking dedicated compliance infrastructure.
- German Optical Component Concentration:Captive manufacturing of precision lenses and fiber bundles in southern Germany creates supply vulnerability for non-integrated assemblers dependent on third-party sourcing.
- Ultrasound Substitution in Abdominal Imaging:Lower-cost portable ultrasound systems are capturing diagnostic volume in general practice settings where endoscopic skill concentration remains thin.
Strategic Opportunities
- Japanese Specialist Referral Networks:METI-supported veterinary technology adoption programs in Tokyo and Osaka metropolitan areas are accelerating capital equipment procurement in consolidated specialty hospital chains.
- Telemedicine Integration:Convergence of cloud-based image storage with real-time surgical consultation platforms enables remote specialist oversight of procedures in geographically dispersed practices.
- Equine Sports Medicine Expansion:Upper respiratory and gastrointestinal endoscopy demand is rising among performance horse veterinarians serving racing and competition stables across Kentucky and Newmarket.
Industry Challenges
- Veterinary Endoscopy Technician Training:Steerable tip deflection proficiency requires hands-on procedural volume that general practice associates rarely accumulate, constraining equipment utilization rates post-purchase.
- FDA Center for Veterinary Medicine Labeling Timelines:Device safety documentation reviews for novel indications extend commercialization lead times by twelve to eighteen months versus human-equivalent clearances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Video Endoscopy Market |
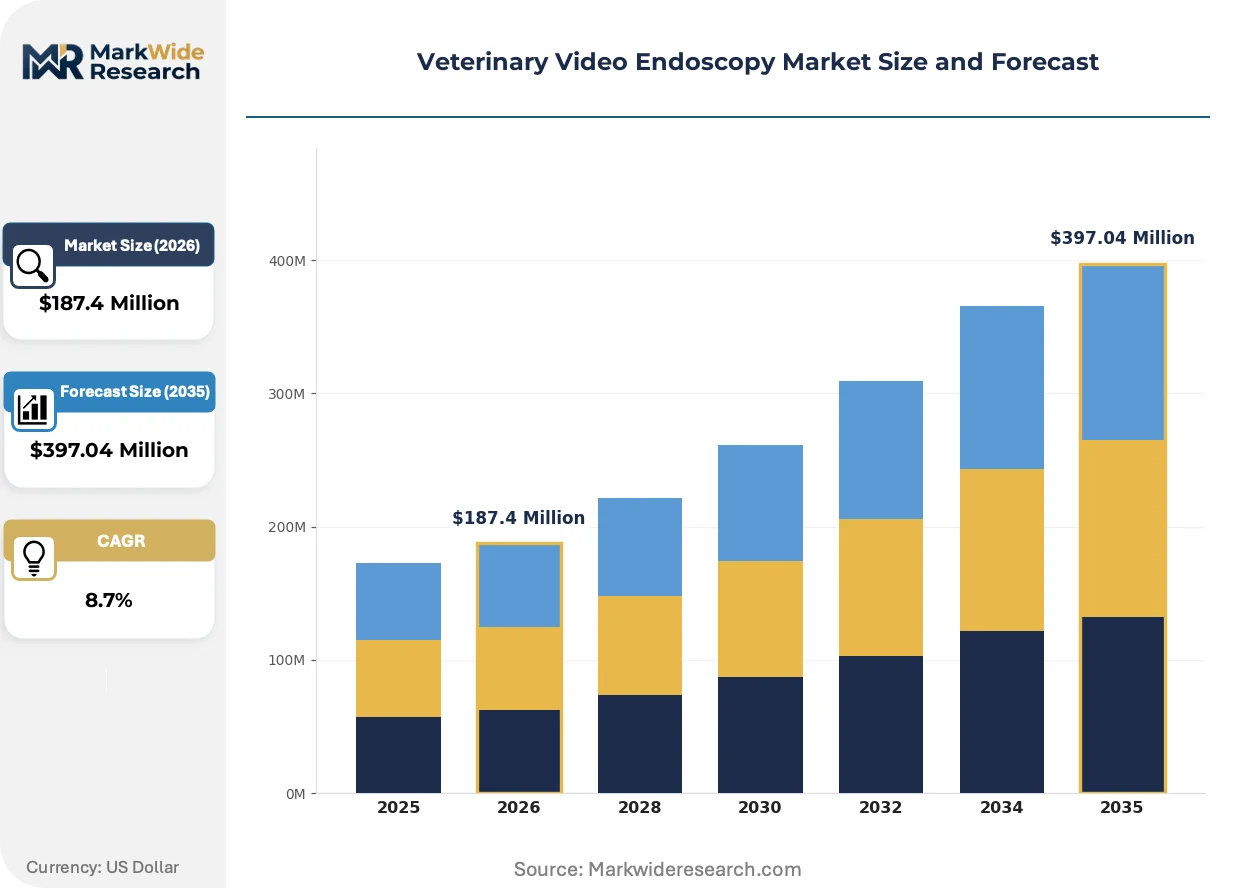
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Video Cameras, Light Sources Application: Gastroenterology, Urology, Pulmonology, Orthopedics End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Emergency Services Technology: Digital Imaging, Fiber Optics, Wireless Communication, Software Integration |
| Companies Covered | Biovision Veterinary Endoscopy, Eickemeyer, Steris, MDS Incorporated, Firefly Global, KARL STORZ SE & Co. KG, Dr. Fritz Endoscopes GmbH, Advanced Monitors Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Video Endoscopy Market Evolving Landscape
Imaging sensor architectures and wireless transmission protocols are converging to reshape how veterinary procedures are documented, supervised, and reimbursed. These shifts are compressing the gap between diagnostic capability in specialist and general practice settings.
Single-use endoscope sheaths with integrated working channels are absorbing contamination risk management burdens previously handled through reprocessing departments. Companion animal hospitals in high-caseload metropolitan areas are adopting these disposable barriers to reduce turnaround time between procedures. This technology is absorbing capital previously allocated to automated endoscope reprocessors and dedicated technician staffing.
EU MDR Article 10 clinical evidence requirements are extending to veterinary-adapted human devices, compelling manufacturers to maintain parallel technical documentation files. German notified bodies are interpreting scope expansively for instruments with dual-use potential. Small-cap specialists without dedicated regulatory affairs functions are exiting European distribution agreements rather than absorbing compliance investment.
Specialty practice consolidation is altering equipment procurement authority, shifting decision-making from individual clinicians to centralized supply chain functions. United States veterinary hospital networks exceeding fifty locations are negotiating enterprise pricing arrangements directly with manufacturers, displacing traditional distributor relationships. This concentration is most visible in California and Texas metropolitan corridors where private equity-backed rollups have achieved critical mass.
Veterinary Video Endoscopy Market Segmentation
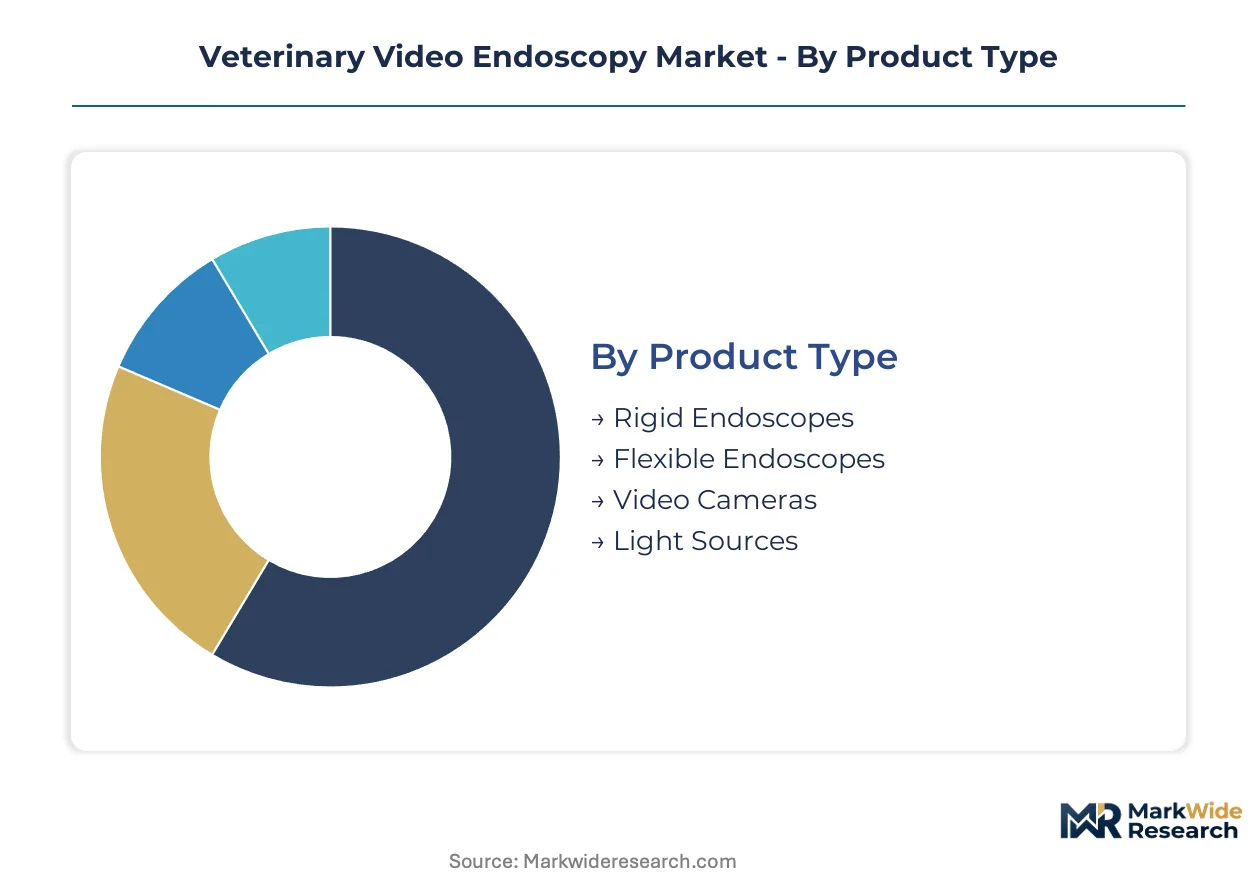
Segmentation in veterinary video endoscopy reveals how regulatory complexity, procedural specialization, and technology cost curves concentrate investment across distinct equipment categories. Understanding these divisions clarifies where FDA Center for Veterinary Medicine and EU MDR compliance burdens fall most heavily.
Product Type:
Certification requirements vary sharply across product types, with flexible endoscopes triggering the most extensive FDA 510(k) documentation and EU MDR technical file maintenance due to their steerable tip mechanisms and patient contact duration.
- Flexible Endoscopes:Steerable insertion tubes with 1.0–3.0 mm working channels dominate gastroenterology and pulmonology procedures. Demand concentrates in United States companion animal referral hospitals where CMOS sensor upgrades justify capital replacement cycles.
- Video Cameras:Detachable camera heads delivering 720p to 4K resolution through CMOS or CCD sensors. German and Japanese manufacturers leverage captive optical production to supply both human and veterinary product lines under unified ISO 13485 quality systems.
- Rigid Endoscopes:Fixed-angle optical systems for arthroscopy and laparoscopy with rod-lens or Hopkins lens configurations. Equine sports medicine practices in Kentucky and Newmarket drive procurement for upper respiratory examinations.
- Light Sources:LED and xenon illumination systems with fiber-optic cable interfaces. Mid-sized veterinary clinics prioritize these for compatibility across multiple endoscope inventories.
Flexible endoscopes sit at the top of the volume ranking, with video cameras climbing the fastest as sensor modularity enables incremental upgrades without full system replacement.
Application:
Procedure reimbursement patterns and specialist training availability determine application-level demand distribution, with gastroenterology commanding premium equipment configurations.
- Gastroenterology:Esophageal, gastric, and intestinal examination via flexible endoscopy represents the most mature application segment. United States specialty hospital networks sustain highest procedural volumes through consolidated referral pathways.
- Pulmonology:Bronchoscopy and airway assessment requiring ultrathin flexible scopes with biopsy capability. Japanese metropolitan veterinary centers lead adoption of advanced navigation technologies.
- Urology:Cystoscopy for urinary tract examination in companion animals. General practice penetration remains constrained by procedural training requirements.
- Orthopedics:Arthroscopy for joint examination and minimally invasive surgery. Equine practitioners drive demand for durable rigid scope configurations.
Gastroenterology maintains the largest installed base, while pulmonology gains share fastest as respiratory diagnostics expand beyond tertiary referral centers.
End User:
Procurement authority consolidation is reshaping end-user segmentation, shifting purchasing decisions from individual clinicians to centralized supply chain functions in large networks.
- Animal Hospitals:Multi-specialty facilities with dedicated endoscopy suites and trained technicians. Private equity-backed networks exceeding fifty locations in California and Texas negotiate direct manufacturer contracts.
- Veterinary Clinics:General practice settings with lower procedural volumes and thinner specialist coverage. Portable ultrasound systems capture diagnostic share where endoscopic skill concentration remains limited.
- Research Institutions:Academic veterinary medical centers conducting comparative studies. These facilities drive demand for documentation and measurement capabilities supporting publication requirements.
- Emergency Services:Urgent care facilities requiring rapid diagnostic turnaround. Single-use sheath adoption is highest here to minimize reprocessing delays.
Animal hospitals dominate capital expenditure, with emergency services expanding most quickly as after-hours specialty coverage gaps widen.
Technology:
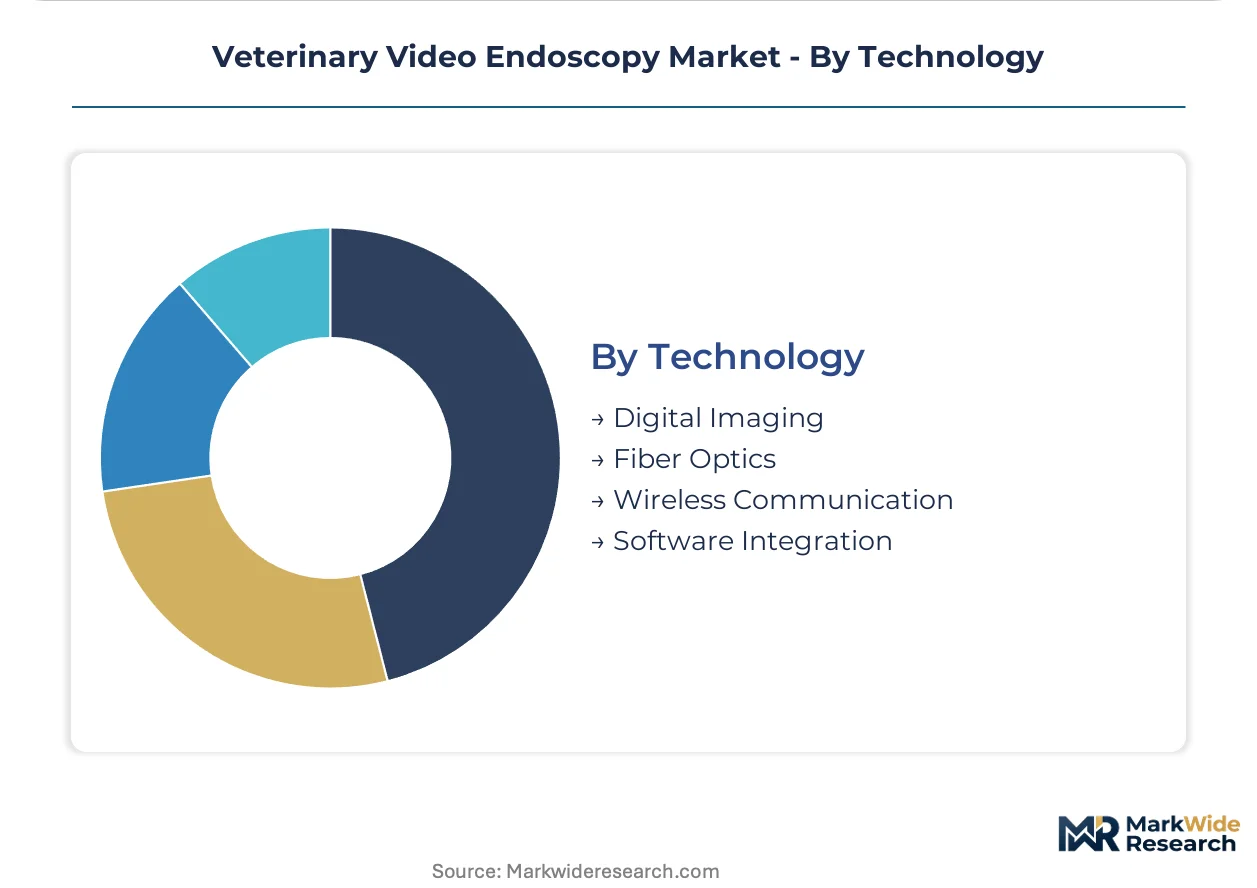
Technology segmentation tracks the migration of imaging and connectivity innovations from human healthcare into veterinary-adapted platforms.
- Digital Imaging:CMOS and CCD sensor architectures with software-integrated capture and measurement. Cost declines in sensor components are compressing price differentials between veterinary and human-equivalent systems.
- Wireless Communication:Elimination of cable drag through Bluetooth or proprietary transmission protocols. Equine practitioners performing lengthy procedures represent the primary adoption cohort.
- Fiber Optics:Traditional image transmission through coherent fiber bundles. Legacy installations in cost-sensitive clinics sustain residual demand.
- Software Integration:Cloud-based image storage, telemedicine transmission, and AI-assisted measurement tools. METI-supported programs in Tokyo and Osaka accelerate Japanese adoption.
Digital imaging leads technology deployment, with wireless communication showing the steepest expansion trajectory as large-animal procedural volume grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical engineering traditions established the foundation for precision endoscope manufacturing, with southern German clusters later supplying lens systems to veterinary equipment assemblers worldwide. Japanese imaging sensor development and American specialty hospital consolidation now drive regional demand variation across three continents.
United States
Private equity-backed veterinary hospital networks exceeding fifty locations in California and Texas negotiate direct manufacturer contracts, bypassing traditional distribution channels. FDA Center for Veterinary Medicine oversees device safety labeling for flexible endoscopy systems deployed across these consolidated chains. Kentucky's equine sports medicine corridor sustains demand for upper respiratory examination equipment serving racing and competition stables.
Germany
Captive optical manufacturing in Baden-Württemberg and Bavaria supplies precision lenses and fiber bundles to both human and veterinary product lines under unified ISO 13485 quality systems. EU MDR Article 10 clinical evidence requirements elevate compliance burdens for veterinary-adapted devices distributed across European markets. Tuttlingen and the Stuttgart metropolitan area concentrate rod-lens fabrication for rigid endoscope configurations.
Japan
METI-supported veterinary technology adoption programs in Tokyo and Osaka metropolitan areas accelerate capital equipment procurement in consolidated specialty hospital chains. PMDA regulatory frameworks govern imaging sensor integration into flexible platforms adapted from human healthcare production lines. Nagoya's industrial corridor hosts component suppliers serving both medical and veterinary imaging equipment manufacturers.
United Kingdom
Specialist veterinary referral networks in London and the Southeast compress equipment refresh cycles as CMOS sensor upgrades justify capital replacement. MHRA oversight aligns with EU MDR conformity requirements for devices entering European distribution channels. Newmarket's equine racing industry sustains procurement of durable rigid scope configurations for performance horse veterinarians.
Canada
Health Canada and PMRA regulate veterinary device safety while provincial veterinary medical associations influence specialty practice equipment standards. Toronto and Vancouver metropolitan areas concentrate multi-specialty animal hospitals with dedicated endoscopy suites and trained technician staff. Cross-border supply relationships with United States distributors shape procurement timelines for mid-sized companion animal clinics.
Veterinary Video Endoscopy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capability and captive optical manufacturing depth. Market structure consolidates toward established manufacturers with dedicated regulatory affairs teams capable of maintaining dual files for human-adapted veterinary systems. Three archetypes dominate: integrated optical manufacturers with unified quality systems, specialized veterinary equipment designers, and human healthcare incumbents extending imaging platforms. Competitive moves concentrate on strategic partnerships for wireless communication module integration and portfolio diversification into single-use sheath technologies.
Within the integrated optical manufacturing tier, KARL STORZ SE & Co. KG and Dr. Fritz Endoscopes GmbH exemplify German precision engineering traditions applied across human and veterinary product lines. Olympus Corporation occupies a position bridging human healthcare imaging expertise into veterinary flexible platforms. Biovision Veterinary Endoscopy represents the specialized veterinary archetype with species-specific design focus. These three anchors demonstrate how regulatory compliance infrastructure and manufacturing depth stratify competitive positioning.
| Leading Market Players |
|---|
| Biovision Veterinary Endoscopy |
| Eickemeyer |
| Steris |
| MDS Incorporated |
| Firefly Global |
| KARL STORZ SE & Co. KG |
| Dr. Fritz Endoscopes GmbH |
| Advanced Monitors Corporation |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
Private equity-backed veterinary hospital networks exceeding fifty locations in California and Texas anchor procurement volume and negotiate direct manufacturer contracts, compressing distributor margins and forcing a three-tier pricing structure across premium, standard, and economy levels based on certification grade and after-sales service bundling.
Pricing Analysis
Premium-mid-economy pricing differentiation separates FDA 510(k)-cleared flexible endoscopy systems with dedicated regulatory files from CE-marked economy tiers and uncertified aftermarket alternatives. Price differentiation hinges on ISO 13485 quality certification and captive optical manufacturing depth. Pricing pressure stems from CMOS sensor cost declines migrating from human healthcare production lines. General practice veterinary clinics exhibit highest price sensitivity, while consolidated specialty hospital chains absorb premium configurations.
Supply Chain Analysis
Precision optics manufacturing clusters in southern Germany face workforce constraints as optical engineering talent concentrates in Tuttlingen and Stuttgart metropolitan areas. Captive lens fabrication draws from Baden-Württemberg and Bavaria, with CMOS sensor sourcing tethered to Japanese and South Korean component suppliers. Single-source vulnerability persists for fiber-optic bundles and rod-lens assemblies. Distribution runs through authorized veterinary equipment distributors serving mid-sized companion animal hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary video endoscopy functions as a stable compounder, with specialty practice consolidation and equipment refresh cycles sustaining predictable procurement velocity across economic cycles.
For Market Incumbents: Hedge against portable ultrasound substitution in general practice settings by deepening software integration and telemedicine capabilities. Prioritize backward integration into CMOS sensor supply chains to defend margin position against component cost volatility. Maintain dual regulatory files for human-adapted veterinary systems to preserve EU MDR market access. For New Entrants and Emerging Players: Begin with wireless communication modules for equine sports medicine practitioners in Kentucky and Newmarket, where cable drag elimination commands premium positioning. Target emergency services facilities adopting single-use sheath technologies to minimize reprocessing infrastructure. Pursue METI-supported veterinary technology adoption programs in Japan as the primary go-to-market channel. For Investors and Strategic Acquirers: Human healthcare imaging equipment manufacturers are the most active acquirer in this space, seeking veterinary platform extensions. The five-to-ten-year viability window favors targets with dedicated regulatory affairs infrastructure and ISO 13485 certification. Monitor FDA Center for Veterinary Medicine labeling timeline extensions as the critical inflection signal for commercialization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Module Integration | Eliminates cable drag during lengthy equine procedures in Kentucky racing stables. |
| Single-Use Sheath Development | Absorbs capital from automated reprocessors in high-caseload metropolitan hospitals. |
| EU MDR Technical File Investment | Maintains market access as German notified bodies expand scope interpretation. |
| Telemedicine Platform Partnership | Enables remote specialist oversight through cloud-based image storage systems. |
| CMOS Sensor Cost Migration | Compresses price differentials between veterinary and human-equivalent imaging platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary equipment procurement managers, biomedical engineers at specialty hospital networks, GPO contracts administrators, and regulatory affairs leads at manufacturers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up equipment shipment tracking and top-down veterinary practice consolidation analysis provided triangulation.
Segment-weighting approaches distributed volume and value across product type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from equipment refresh cycle analysis, CMOS sensor cost curve trajectories, and specialty practice consolidation velocity. Forecast inputs incorporated METI-supported adoption program timelines and FDA Center for Veterinary Medicine labeling review patterns.
Several conditions sit outside the modeled scope, including abrupt regulatory framework revisions, supply chain disruptions in German optical component clusters, and veterinary technician training capacity constraints. Forecasts reflect documented assumptions about procedural volume growth and reimbursement pathway stability. Material deviation in EU MDR enforcement intensity or CMOS sensor supply availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
China Arthroscopy Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Colonic Stents Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Endoscopy Device Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Spain Endoscopy Devices Market