
 Global Endometrial Cancer Market | 2026-2036
Global Endometrial Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endometrial Cancer Market Foresight
Precision-molecular diagnostic standards is reorganizing competitive dynamics across the Global Endometrial Cancer Market. Merck leverages its checkpoint inhibitor franchise to sustain leadership in PD-1 directed endometrial carcinoma protocols. Hoffmann-La Roche anchors its position through companion diagnostic development paired with therapeutic candidates. AstraZeneca differentiates via PARP inhibitor combinations in mismatch repair deficient patient subsets.
Endometrial cancer denotes malignancy arising from the endometrial lining of the uterus, characterized by histological subtypes including endometrioid, serous, and clear cell carcinomas with grade-dependent prognostic stratification. The condition demands staged therapeutic intervention ranging from hysterectomy to systemic therapy based on molecular profiling and FIGO staging criteria. Immunotherapy segments command premium positioning as pembrolizumab-lenvatinib combinations redefine frontline recurrent settings. Targeted therapy segments occupy expanding margin pools as biomarker-driven patient selection improves response rates. Surgical devices segments retain volume dominance in early-stage disease management across specialized hospitals and oncology clinics.
FDA breakthrough therapy designations and EMA conditional marketing authorizations compress regulatory timelines for novel endometrial cancer agents, while WHO cancer control frameworks elevate uterine malignancy screening priorities in national health programs. The EU MDR tightens clinical evidence requirements for surgical device platforms used in oncologic gynecology procedures. Stakeholders must monitor biomarker reimbursement decisions and pathology infrastructure investments to capture value from precision therapy transitions.
Market Dynamics
FDA breakthrough therapy designations are compressing regulatory timelines for novel endometrial cancer agents, while companion diagnostic requirements are restructuring how pharmaceutical and diagnostic value chains integrate across oncology clinics.
Growth Catalysts
- Immunotherapy protocol expansion:PD-1 inhibitor combinations are redefining frontline recurrent disease management, with oncology clinics in the United States and Germany prioritizing molecular profiling infrastructure to identify mismatch repair deficient patient subsets.
- EMA conditional marketing authorizations:Accelerated European approval pathways enable earlier patient access to novel agents, compressing the evidence-generation timeline for sponsors while expanding treatment options in specialized gynecologic oncology centers.
- Companion diagnostic mandates:Biomarker-driven patient selection is improving response rates in targeted therapy segments, with pathology laboratories investing in next-generation sequencing platforms to support precision oncology workflows.
Market Restraints
- Biomarker reimbursement uncertainty:Payer coverage decisions for molecular diagnostic testing vary substantially across national health programs, creating friction in patient access to precision-matched therapies.
- Clinical trial complexity:The requirement for biomarker-enriched patient populations narrows eligible cohorts, extending enrollment timelines and elevating development costs for sponsors targeting rare molecular subtypes.
- Supply concentration in surgical devices:Specialized oncologic gynecology equipment manufacturing clusters in Germany and the United States, creating vulnerability to regional production disruptions.
Strategic Opportunities
- Underpenetrated molecular diagnostics in Japan:Pathology infrastructure investments lag behind the United States and Germany, creating whitespace for diagnostic platform vendors and laboratory service expansion.
- PARP inhibitor combination protocols:Emerging therapeutic regimens targeting homologous recombination deficiency are expanding addressable patient populations beyond monotherapy-responsive subsets.
- WHO cancer control framework implementation:National screening program prioritization of uterine malignancies in lower-middle income health systems is elevating early-stage detection capacity and surgical intervention volumes.
Industry Challenges
- Gynecologic oncology specialist scarcity:Fellowship training program output fails to match rising case volumes, extending patient wait times for specialized surgical and systemic therapy consultation.
- EU MDR clinical evidence requirements:Surgical device platforms face tightened documentation burdens for oncologic gynecology applications, extending recertification timelines and elevating regulatory affairs staffing needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endometrial Cancer Market |
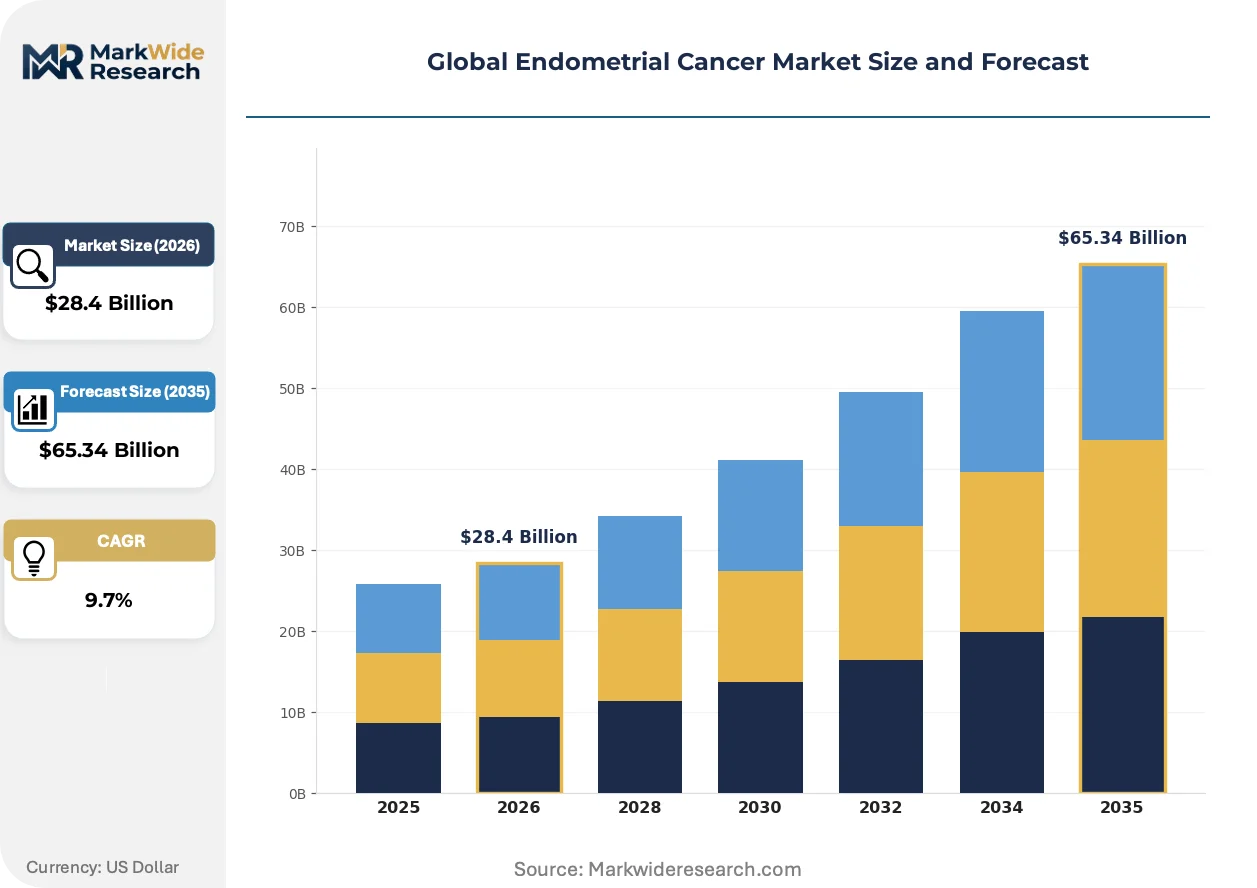
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $65.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Chemotherapy, Immunotherapy, Targeted Therapy, Surgical Devices Therapy Area: Stage I, Stage II, Stage III, Stage IV, Recurrent Cases End User: Oncology Clinics, Cancer Research Institutes, Diagnostic Laboratories, Specialized Hospitals Delivery Mode: Oral, Intravenous, Intramuscular, Subcutaneous, Localized Administration |
| Companies Covered | Merck, GlaxoSmithKline, AstraZeneca, Hoffmann-La Roche, Pfizer, Novartis, Karyopharm Therapeutics, Incyte Corporation, Eisai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endometrial Cancer Market Shifts & Advancements
Precision-molecular diagnostic standards are reorganizing how therapeutic value is captured across the endometrial cancer treatment pathway, with biomarker infrastructure investments preceding protocol adoption in leading oncology centers.
Liquid biopsy circulating tumor DNA analysis is decomposing the traditional tissue-based diagnostic hierarchy. Community oncology practices in the United States are adopting blood-based molecular profiling to accelerate treatment initiation. This shift is decomposing the historical monopoly of academic medical centers on complex biomarker testing, redistributing diagnostic capability toward outpatient settings.
EU MDR implementation is elevating clinical evidence requirements for surgical device platforms used in oncologic gynecology procedures. Manufacturers face expanded post-market surveillance obligations and stricter biocompatibility documentation. Specialized hospitals in Germany and France are prioritizing MDR-certified instrumentation in procurement specifications, compressing demand for legacy device portfolios.
Integrated diagnostics-therapeutics contracting is restructuring pharmaceutical-commercial relationships. Oncology clinics are consolidating vendor relationships around vendors offering combined molecular profiling and targeted therapy access. This consolidation is most visible in United States academic medical centers, where single-source agreements are displacing fragmented point solution procurement.
Global Endometrial Cancer Market Segmentation
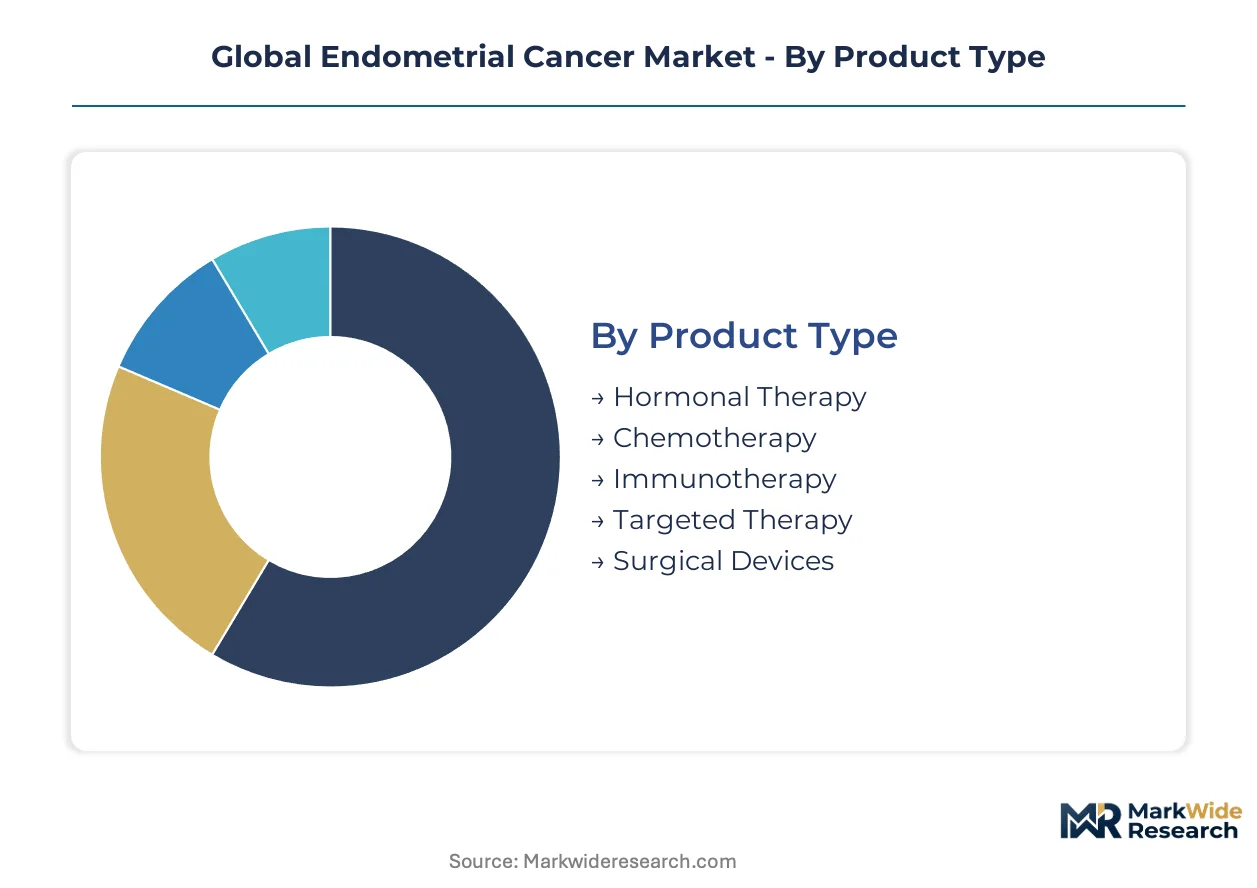
Endometrial cancer treatment pathways fragment across molecular staging, therapeutic modality, and care setting. Segmentation clarity enables stakeholders to align R&D investment with reimbursement pathways and infrastructure requirements.
Product Type:
FDA breakthrough designations and EMA conditional approvals create divergent regulatory timelines across therapeutic categories, compressing development cycles for immunotherapy while maintaining traditional evidentiary standards for surgical devices.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors dominate frontline recurrent protocols. Oncology clinics in the United States and Germany prioritize molecular profiling infrastructure to identify mismatch repair deficient subsets eligible for pembrolizumab-based regimens.
- Targeted Therapy:PARP inhibitors and anti-angiogenic agents address homologous recombination deficiency and vascular endothelial growth factor pathways. Demand concentrates in specialized hospitals with next-generation sequencing capabilities to guide patient selection.
- Surgical Devices:Minimally invasive hysterectomy platforms and robotic-assisted instrumentation retain volume dominance in early-stage disease management.
- Chemotherapy:Platinum-taxane combinations maintain utility in advanced and recurrent settings where immunotherapy contraindications exist.
- Hormonal Therapy:Progestin-based regimens preserve fertility in select early-stage patients and manage low-grade endometrioid carcinomas.
Established volume favors surgical devices; emerging adoption favors immunotherapy.
Therapy Area:
FIGO staging criteria determine intervention intensity, with cost structures escalating from surgical monotherapy to multimodal systemic regimens.
- Stage I:Confined to uterine corpus, managed primarily through hysterectomy with or without lymphadenectomy. Surgical device procurement dominates treatment expenditure in this category.
- Stage IV:Distant metastasis requiring systemic therapy combinations. Immunotherapy and targeted therapy command premium positioning as first-line options in the United States and Japan.
- Recurrent Cases:Disease progression after initial treatment drives demand for molecular profiling and biomarker-directed therapy selection.
- Stage II:Cervical stromal involvement necessitates radical hysterectomy with adjuvant radiation considerations.
- Stage III:Regional lymph node or adnexal spread requires multimodal approaches combining surgery, radiation, and systemic therapy.
Stage I generates the highest procedure volumes; Stage IV commands the steepest per-patient expenditure trajectory.
End User:
Capability concentration varies across settings, with molecular diagnostic infrastructure determining access to precision-matched therapies.
- Oncology Clinics:Outpatient systemic therapy administration sites expanding molecular profiling partnerships with academic medical centers.
- Specialized Hospitals:Gynecologic oncology surgical volume centers with integrated pathology and clinical trial access.
- Cancer Research Institutes:Early-phase clinical trial enrollment and biomarker discovery programs.
- Diagnostic Laboratories:Next-generation sequencing service providers supporting community oncology practices with remote molecular profiling.
Specialized hospitals anchor surgical volume; oncology clinics are gaining share fastest in systemic therapy delivery.
Delivery Mode:
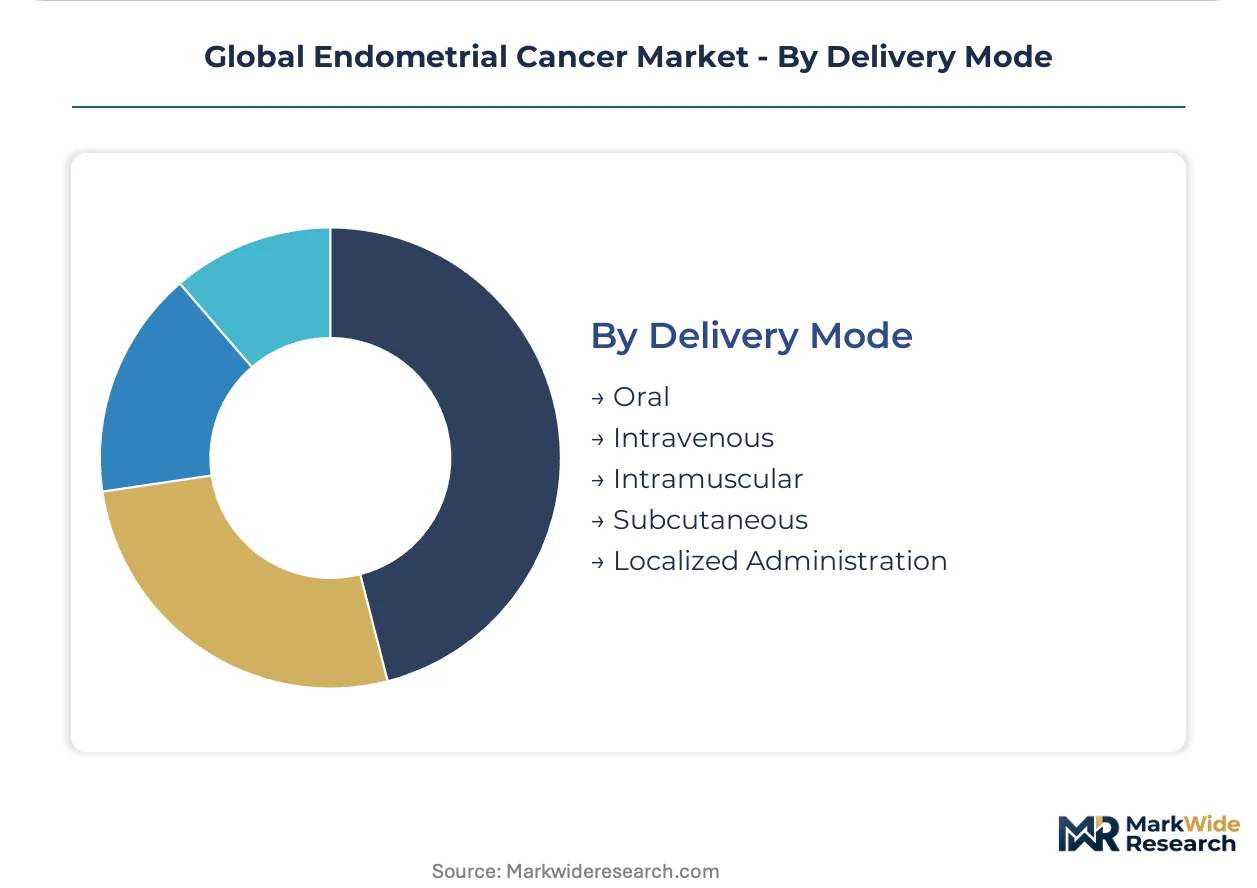
Route selection follows pharmacokinetic requirements and patient compliance considerations, with oral formulations expanding community-based treatment access.
- Intravenous:Checkpoint inhibitors and cytotoxic agents requiring infusion center infrastructure. United States oncology clinics invest in ambulatory infusion capacity to accommodate rising immunotherapy volumes.
- Oral:PARP inhibitors and hormonal agents enabling home-based administration. Patient preference and reduced healthcare utilization costs drive formulary prioritization in Germany and Japan.
- Subcutaneous:Emerging delivery innovation for select biologics, potentially displacing intravenous administration in maintenance settings.
- Intramuscular:Limited application for hormonal depot formulations in fertility-preserving protocols.
- Localized Administration:Intraperitoneal chemotherapy and intracavitary radiation for select advanced or recurrent presentations.
Intravenous retains protocol dominance; oral formulations are climbing the fastest in patient-access metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for precision oncology infrastructure characterizes the Global Endometrial Cancer Market, with diagnostic platforms and biologics flowing from manufacturing clusters in Germany, the United States, and Japan toward emerging treatment centers in lower-middle income health systems.
United States
Oncology clinics in Massachusetts and California are expanding molecular profiling partnerships with academic medical centers to identify mismatch repair deficient patient subsets. FDA breakthrough therapy designations compress regulatory timelines for pembrolizumab-based combinations in frontline recurrent protocols. The Boston-Cambridge corridor anchors biomarker discovery programs and early-phase clinical trial enrollment capacity.
Germany
Specialized hospitals in Bavaria and North Rhine-Westphalia prioritize MDR-certified surgical instrumentation in procurement specifications. The EU MDR tightens clinical evidence requirements for oncologic gynecology device platforms, extending recertification timelines. Heidelberg and Munich cluster pathology infrastructure investments supporting precision oncology workflows.
Japan
Pathology infrastructure investments lag behind the United States and Germany, creating whitespace for diagnostic platform vendors. The PMDA accelerates review timelines for companion diagnostics paired with immunotherapy candidates. Tokyo and Osaka metropolitan areas concentrate gynecologic oncology surgical volume and systemic therapy administration sites.
United Kingdom
NHS England cancer control frameworks elevate uterine malignancy screening priorities in national health programs. NICE technology appraisals determine reimbursement access for PARP inhibitor combinations in homologous recombination deficient subsets. London and Manchester anchor integrated diagnostics-therapeutics contracting models consolidating vendor relationships.
India
CDSCO regulatory pathways for biosimilars and targeted therapies are compressing market entry timelines for domestic manufacturers. National cancer grid programs expand molecular diagnostic capacity in tier-two cities. Hyderabad and Bengaluru clusters support laboratory service expansion for community oncology practices.
Global Endometrial Cancer Market Competitive Landscape
Listed leaders compete with private specialists across immunotherapy and targeted therapy segments, with publicly traded pharmaceutical conglomerates anchoring PD-1 inhibitor franchises while private biotechs pursue niche biomarker-driven indications. The vendor base concentrates around three strategic archetypes: checkpoint inhibitor franchise holders, companion diagnostic-therapeutic integrators, and PARP inhibitor combination developers. Dominant competitive moves include strategic partnerships between diagnostic platform vendors and pharmaceutical sponsors, plus geographic licensing arrangements to access emerging market reimbursement pathways.
Within the checkpoint inhibitor tier, Merck and Hoffmann-La Roche occupy positions exemplifying franchise sustainability through regulatory pathway expertise and companion diagnostic integration. AstraZeneca represents the PARP inhibitor combination archetype, targeting mismatch repair deficient and homologous recombination deficient patient subsets with biomarker-directed protocols. These three entities anchor the competitive structure through distinct therapeutic modality specializations.
| Leading Market Players |
|---|
| Merck |
| GlaxoSmithKline |
| AstraZeneca |
| Hoffmann-La Roche |
| Pfizer |
| Novartis |
| Karyopharm Therapeutics |
| Incyte Corporation |
| Eisai |
| Others |
Supply & Pricing Matrix
Integrated diagnostics-therapeutics contracting locks in multi-year supply access for oncology clinics while compressing price visibility across immunotherapy and molecular diagnostic bundles. This structure concentrates procurement leverage within United States academic medical centers and German specialized hospitals, elevating switching costs for vendors outside approved vendor lists.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in surgical device procurement. Price differentiation hinges on MDR certification tier and after-sales service bundling, with German and United States manufacturers commanding brand premiums. Pricing pressure stems from CDSCO biosimilar pathways in India compressing originator margins. Community oncology practices exhibit highest price sensitivity; specialized hospitals prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Inventory lead times for next-generation sequencing platforms extend procurement cycles for United States and German pathology laboratories. Manufacturing concentrates in Germany, the United States, and Japan for precision oncology instrumentation. Raw material dependencies include semiconductor components, optical sensors, and reagent-grade biochemicals. Single-source vulnerability characterizes EU MDR-certified surgical device supply. Distribution runs through integrated diagnostics-therapeutics contracting models consolidating vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Endometrial Cancer Market sits in a cyclical recovery phase driven by FDA breakthrough therapy designations compressing development timelines and expanding reimbursable treatment protocols.
For Market Incumbents: Consolidate companion diagnostic partnerships to defend against emerging biotech entrants targeting niche biomarker subsets. Deepen vertical integration into pathology infrastructure through laboratory service acquisitions in Japan and India. Lock in long-term offtake agreements with oncology clinics before EMA conditional marketing authorizations broaden competitive access. For New Entrants and Emerging Players: Anchor in underpenetrated molecular diagnostics whitespace across Japanese community oncology practices where pathology infrastructure investments lag United States benchmarks. Target homologous recombination deficiency testing as the most penetrable segment given PARP inhibitor combination protocol expansion. Pursue geographic licensing arrangements with Indian CDSCO-registered manufacturers to access national cancer grid reimbursement pathways. For Investors and Strategic Acquirers: The market sits at an expansion phase that favors companion diagnostic-therapeutic integrators with FDA-cleared platforms and EMA MDR certifications. Long-term viability over the next decade hinges on biomarker reimbursement decisions stabilizing across national health programs. Watch NICE technology appraisals and CMS coverage determinations for mismatch repair deficiency testing as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Locks in biomarker-driven patient selection for pembrolizumab-based regimens in United States oncology clinics. |
| MDR Certification Pathway | Opens procurement access to German and French specialized hospitals with tightened clinical evidence requirements. |
| Geographic Licensing Arrangement | Accelerates market entry through CDSCO-registered manufacturing in Hyderabad and Bengaluru clusters. |
| Integrated Diagnostics-Therapeutics Contract | Consolidates vendor relationships around combined molecular profiling and targeted therapy access models. |
| Biomarker Discovery Program | Expands addressable patient populations for PARP inhibitor combinations in homologous recombination deficient subsets. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down therapeutic category sizing triangulate volume estimates.
Sensitivity analysis across molecular staging, therapeutic modality, administration route, and regional regulatory cluster dimensions shapes the analytical framework. CAGRs derive from segmented growth rate blending anchored in biomarker penetration curves and protocol adoption timelines. Forecast inputs incorporate WHO cancer control framework implementation progress and pathology infrastructure investment trajectories.
Decision-makers should treat outputs as directional under stable biomarker reimbursement and regulatory pathway assumptions; material deviation in payer coverage decisions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Hypothyroidism Market