
 Crude Oil Desalter Market | 2026-2036
Crude Oil Desalter Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Desalter Market Analysis
API 12J qualification for pressure vessel fabrication is collapsing the supplier base for upstream desalter projects. Baker Hughes Co leverages its electrostatic coalescer R&D pipeline to sustain technology leadership across Middle East refinery awards. Schlumberger Ltd anchors its position through integrated project delivery that bundles desalting with downstream separation. Alfa Laval AB differentiates via compact modular designs that reduce footprint for offshore platform retrofits.
Crude oil desalters are pressure vessels that remove inorganic salts, suspended solids, and formation water from crude oil through electrostatic coalescence, gravity settling, or chemical injection, typically operating at 100–150°C and 3–10 barg to protect downstream catalytic reformers and distillation columns from chloride-induced corrosion. Electrostatic desalters dominate refinery installations due to established reliability with high-API crudes, while membrane technology represents the fastest-growing segment as operators seek reduced chemical consumption and smaller effluent volumes. Horizontal desalters occupy the largest product category share given their superior residence time distribution for heavy crude processing, whereas compact and modular formats are gaining traction in remote field upgrades and FPSO tie-ins where space and weight constraints govern equipment selection.
EPA effluent limitation guidelines under the Clean Water Act mandate chloride and total dissolved solids thresholds that directly shape desalter performance specifications for US refineries, while REACH compliance in Europe restricts certain demulsifier chemistries and drives substitution toward bio-based formulations. Saudi Aramco engineering standards and ADNOC technical specifications function as de facto market access requirements for vendors targeting Gulf refinery expansions. Stakeholders must monitor how carbon border adjustment mechanisms and Scope 3 accounting rules reshape the economic calculus for desalter upgrades versus greenfield investments in heavier crude processing.
Market Dynamics
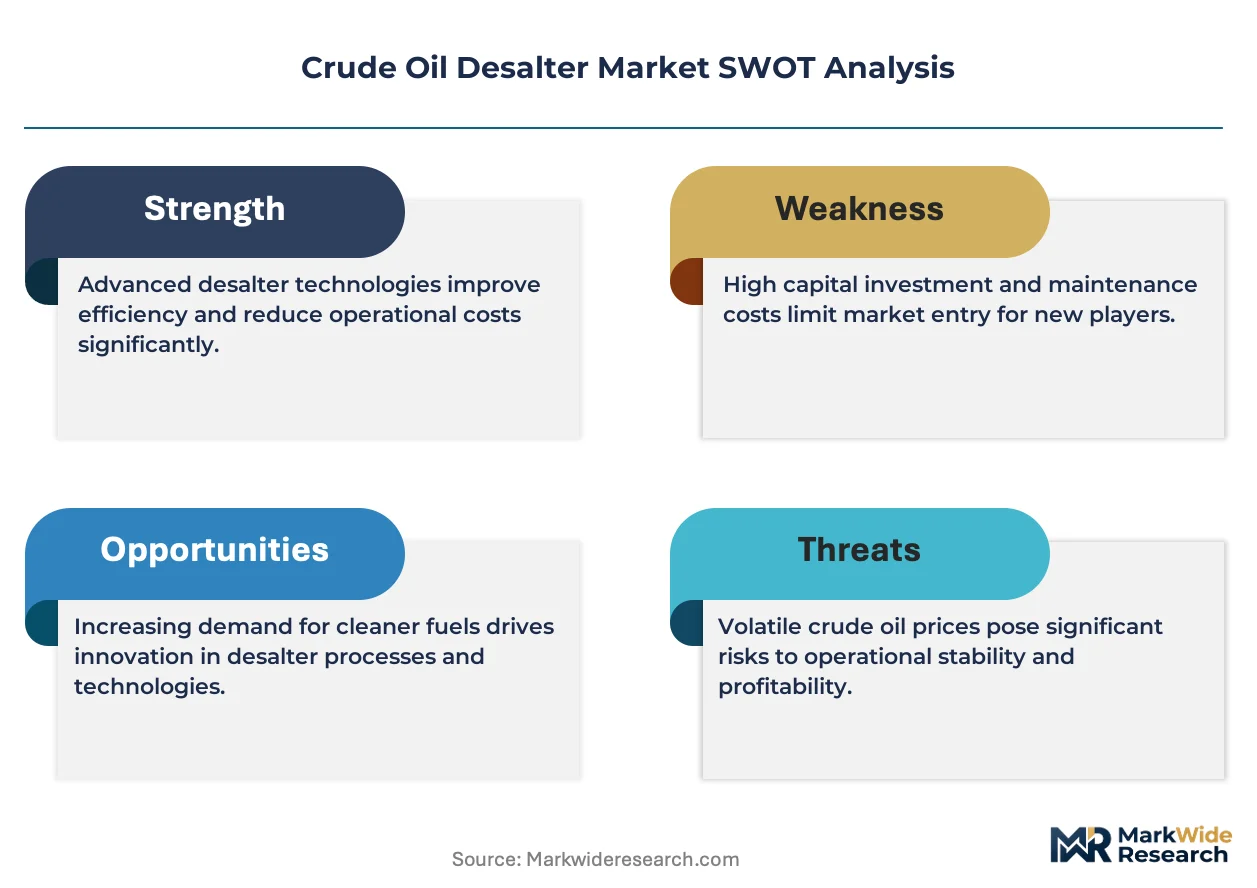
Refinery operators face intensifying pressure to process heavier, higher-salt crude slates while EPA effluent rules tighten chloride discharge limits. This structural tension between feedstock quality degradation and environmental compliance is forcing capital redeployment toward advanced electrostatic coalescence and membrane hybrid systems.
Growth Catalysts
- EPA Effluent Limitation Guidelines:The Clean Water Act mandates stricter chloride thresholds for US refineries. Operators upgrade desalter performance specifications to avoid penalties.
- Saudi Aramco Engineering Standards:Downstream infrastructure expansion across the Kingdom requires API 12J-qualified pressure vessel fabrication. Vendors meeting these specifications capture refinery award flows.
- Membrane Technology Maturation:Reduced chemical consumption and smaller effluent volumes drive adoption. Operators seek lower lifecycle operating costs versus conventional electrostatic units.
Market Restraints
- API 12J Qualification Barriers:Pressure vessel fabrication standards collapse the supplier base for upstream desalter projects. Only certified fabricators remain eligible for major awards.
- Specialized Alloy Input Volatility:Desalter construction requires corrosion-resistant steels for sour crude service. Nickel and molybdenum price swings compress fabricator margins.
- Electrostatic Coalescer Limitations:High-viscosity heavy crudes reduce separation efficiency. Operators must blend or heat-treat feedstock, adding energy intensity.
Strategic Opportunities
- Offshore Platform Retrofits:Compact modular desalter designs address space and weight constraints on aging FPSO vessels. Alfa Laval and competitors target this whitespace.
- EU REACH Compliance Tailwinds:Restrictions on conventional demulsifier chemistries drive substitution toward bio-based formulations. European refineries seek compliant chemical suppliers.
- Membrane-Electrostatic Convergence:Hybrid systems combine established reliability with reduced chemical use. Early deployments demonstrate viable performance for medium-API crudes.
Industry Challenges
- API 12J Certification Timelines:Pressure vessel qualification requires extensive documentation and third-party inspection. New entrants face 12-18 month approval cycles.
- Legacy Control System Integration:Modern desalter automation must interface with decades-old refinery distributed control systems. Custom engineering adds project risk.
- Electrostatic Grid Maintenance Skill Gaps:High-voltage transformer and electrode array servicing demands specialized technicians. Training pipelines lag fleet expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Desalter Market |
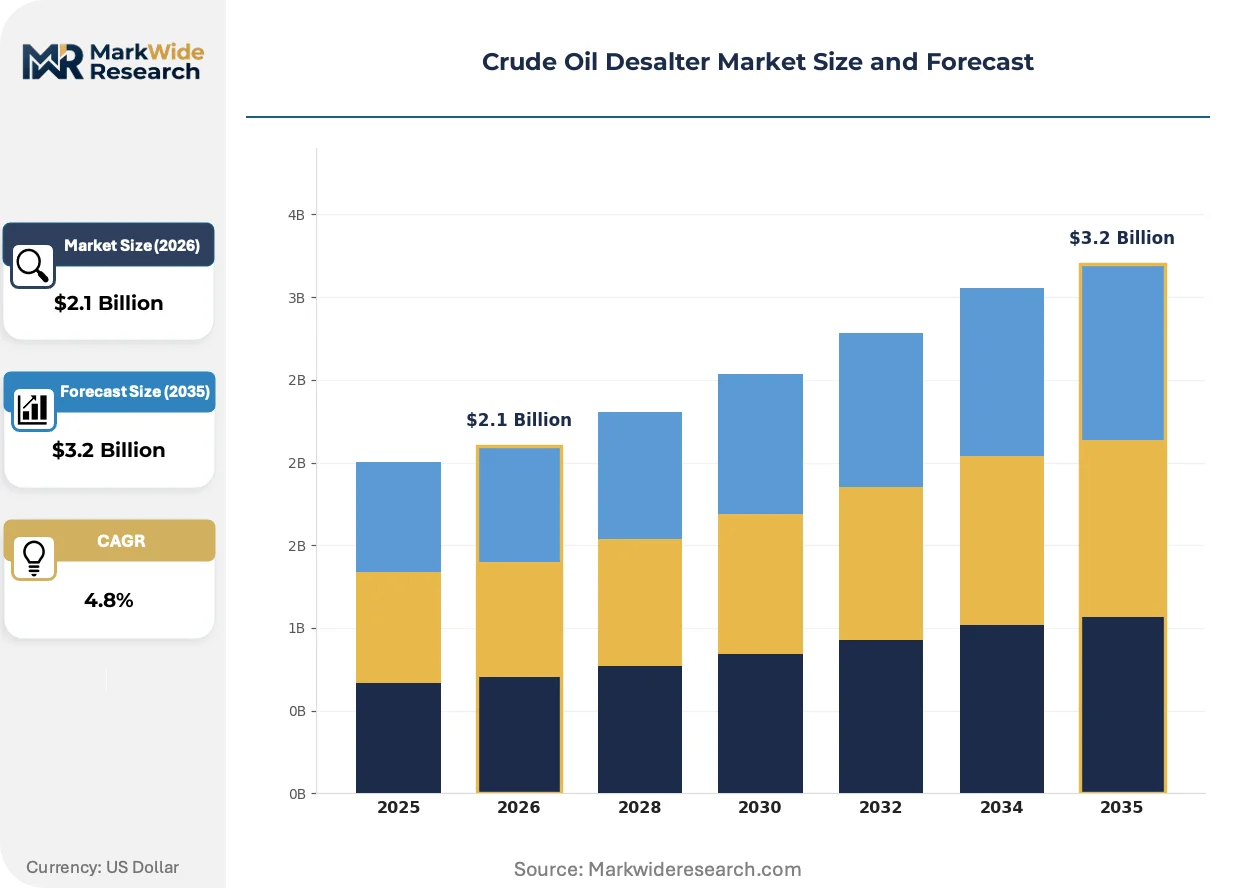
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrostatic, Chemical, Membrane, Thermal End User: Refineries, Petrochemical Plants, Oil Producers, Utilities Product Type: Vertical Desalters, Horizontal Desalters, Compact Desalters, Modular Desalters Operation Type: Batch Process, Continuous Process, Semi-Continuous Process, Hybrid Process |
| Companies Covered | Desalters LLC, Frames Group, Agar Corporation Ltd, Schlumberger Ltd, Alfa Laval AB, Canadian Petroleum Processing Equipment Inc, Forum Energy Technologies, Baker Hughes Co, AMR Process Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Desalter Market Emerging Trajectories
Technology trajectories in crude oil desalting center on hardware miniaturization, regulatory chemistry substitution, and procurement model evolution. These three vectors are compressing traditional equipment lifecycles and reshaping vendor-customer relationships.
Membrane separation technology is decomposing the conventional electrostatic desalter monopoly in specific crude applications. Offshore operators and remote field developers adopt ceramic and polymeric membrane skids for their 40-60% footprint reduction. The technology is decomposing capital allocation patterns by enabling brownfield expansions where conventional vessel additions would require impossible plot space.
REACH restrictions on ethoxylated phenol demulsifiers are forcing European refiners toward bio-based surfactant formulations. ECHA substance evaluations have flagged several conventional chemistries for authorization requirements. Heavy crude processors in Germany and the Netherlands face reformulation costs that alter chemical supplier selection criteria.
Integrated project delivery models now bundle desalting with downstream separation and water treatment. National oil companies in Saudi Arabia and the UAE award single-contractor responsibility for entire crude handling trains. This procurement consolidation disadvantages pure-play desalter vendors lacking adjacent separation capabilities.
Crude Oil Desalter Market Segmentation
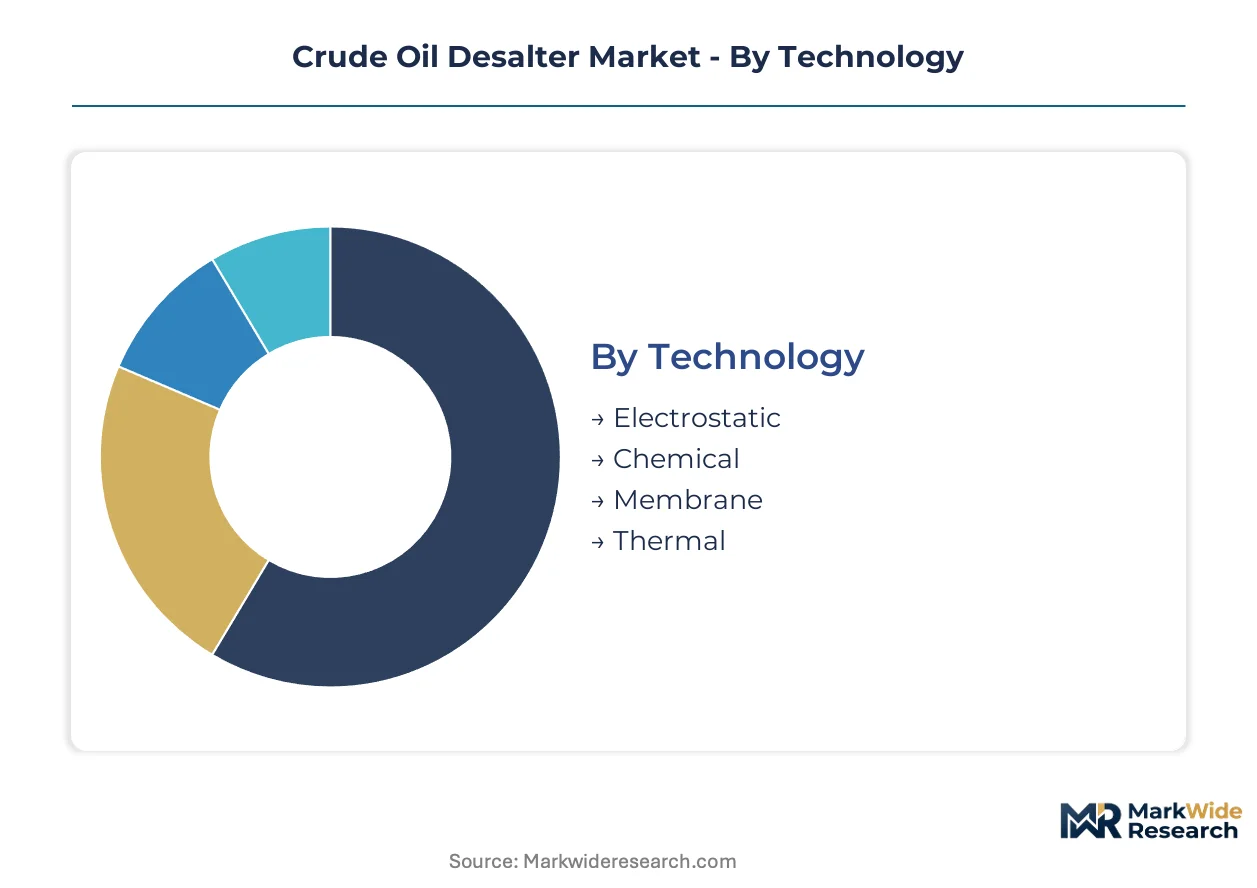
Technology and product architecture choices in crude oil desalting determine capital intensity, operating chemistry requirements, and plot space constraints. Procurement patterns diverge sharply between refinery operators seeking reliability at scale versus offshore developers prioritizing footprint reduction.
Technology:
Membrane separation is displacing conventional electrostatic units in specific viscosity and salinity bands, reshaping competitive positioning across the technology stack.
- Electrostatic:High-voltage coalescer grids operating at 100–150°C and 3–10 barg separate brine droplets through induced dipole attraction. Refinery operators in Saudi Arabia and the UAE specify these units for their established track record with medium-API crudes under Saudi Aramco engineering standards.
- Membrane:Ceramic and polymeric membrane skids reduce chemical consumption and effluent volumes versus electrostatic alternatives. Offshore platform retrofits and remote field tie-ins drive adoption where space constraints prohibit conventional vessel footprints.
- Chemical:Demulsifier injection systems break water-in-oil emulsions through surfactant action, often deployed as upstream pretreatment ahead of primary separation stages.
- Thermal:Heat-based desalting raises crude temperature to reduce viscosity and accelerate gravity settling, applicable for heavy crude preprocessing where electrostatic efficiency degrades.
Electrostatic retains volume leadership; membrane holds the steepest expansion curve.
End User:
Downstream integration depth separates capital deployment patterns, with integrated operators bundling desalting into larger crude handling train awards.
- Refineries:Atmospheric and vacuum distillation units require salt removal below 10 PTB to protect downstream catalytic reformers from chloride-induced corrosion. EPA effluent limitation guidelines mandate performance upgrades at US facilities.
- Petrochemical Plants:Steam cracker feedstock pretreatment demands ultra-low salt specifications to prevent furnace tube fouling. Gulf Coast and Rotterdam cluster operators drive specification tightening.
- Oil Producers:Field-level desalting at wellhead facilities reduces pipeline corrosion and meets crude purchaser quality clauses. Remote and marginal field developers prioritize compact formats.
- Utilities:Power generation feedstock conditioning for liquid fuel boilers represents a niche application with limited specification stringency.
Refineries command the largest installed base; petrochemical plants exhibit the most aggressive specification escalation.
Product Type:
Residence time distribution and plot space availability dictate vessel orientation and modularity choices for greenfield versus brownfield deployments.
- Horizontal Desalters:Extended horizontal vessels provide superior residence time distribution for heavy crude processing with elevated solids and water content. Middle East refinery expansions specify these units for their capacity to handle degraded feedstock slates.
- Compact Desalters:Skid-mounted designs with reduced footprint address space constraints on aging FPSO vessels and remote production facilities. North Sea and West African offshore operators drive specification demand.
- Vertical Desalters:Traditional upright vessels suit low-throughput applications and onshore fields with ample plot space availability.
- Modular Desalters:Factory-fabricated, transportable units enable rapid deployment and capacity staging for phased field developments.
Horizontal desalters dominate refinery awards; compact formats are climbing the fastest among product architectures.
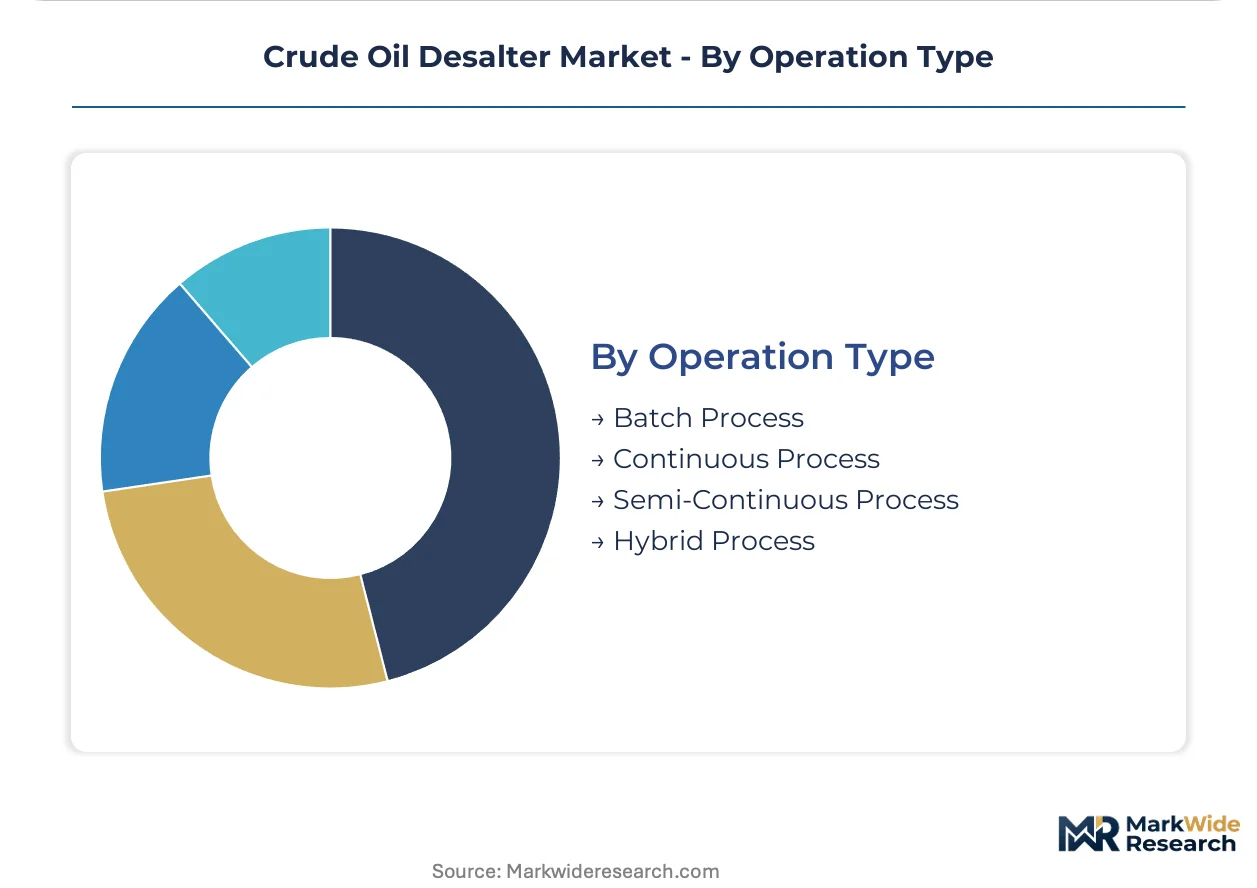
Operation Type:
Continuous versus batch processing trade-offs center on throughput scale, crude variability, and automation infrastructure maturity.
- Continuous Process:Uninterrupted crude flow through parallel desalter trains matches refinery distillation unit operating modes. Large-scale Gulf Coast and Singapore refining centers standardize on this architecture.
- Hybrid Process:Combined electrostatic-membrane stages optimize for medium-API crudes with moderate salinity, reducing chemical intensity while preserving separation reliability.
- Batch Process:Intermittent operation suits small-scale producers and pilot testing applications with irregular crude receipt schedules.
- Semi-Continuous Process:Cyclic operation with buffer tanks accommodates crude quality variation without full continuous automation investment.
Continuous process anchors refinery infrastructure; hybrid configurations are gaining share fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated refinery operators and national oil companies concentrate procurement authority in the Middle East and North America, where downstream infrastructure expansion and environmental compliance drive desalter investment cycles.
United States
Gulf Coast refiners in Texas and Louisiana process heavy sour crude imports from Latin America and Canada. EPA effluent limitation guidelines under the Clean Water Act mandate chloride discharge thresholds that force performance upgrades at Houston and Port Arthur facilities. The Houston Ship Channel refining cluster drives specification tightening for electrostatic coalescer replacements.
Saudi Arabia
Saudi Aramco engineering standards function as de facto market access requirements for vendors targeting Kingdom refinery expansions. Downstream infrastructure upgrades at Jubail and Yanbu industrial cities specify API 12J-qualified pressure vessel fabrication. The Eastern Province refining corridor concentrates newbuild desalter awards for heavy crude processing capacity.
United Arab Emirates
ADNOC technical specifications govern equipment selection for Abu Dhabi refinery modernization and Ruwais Derivatives Complex expansion. The Ruwais industrial zone anchors Gulf desalter demand as operators process heavier crude slates from Upper Zakum and other offshore fields. Dubai and Sharjah petrochemical clusters add secondary demand for steam cracker feedstock pretreatment.
China
State-owned refiners in Shandong and Guangdong provinces expand capacity to process high-sulfur Middle Eastern crudes. MIIT energy efficiency standards and MEE wastewater discharge rules tighten salt removal requirements at Dalian and Ningbo refining centers. The Yangtze River Delta petrochemical corridor drives membrane technology piloting for reduced chemical consumption.
Netherlands
Rotterdam cluster refiners face REACH restrictions on ethoxylated phenol demulsifiers that alter chemical supplier selection criteria. ECHA substance evaluations flag conventional chemistries for authorization requirements. The Port of Rotterdam refining and chemical complex drives bio-based surfactant formulation demand for heavy crude processing.
Crude Oil Desalter Market Vendor Landscape
Player mix skews toward integrated oilfield services conglomerates and specialized pressure vessel fabricators. Market structure concentrates procurement influence among national oil company engineering standards, collapsing the qualified supplier base for major refinery awards. Two strategic archetypes dominate: full-service separation technology providers bundling desalting with downstream water treatment, and compact modular specialists targeting offshore retrofit whitespace. Competitive moves center on API 12J certification maintenance and integrated project delivery model adoption.
Within the integrated services tier, Schlumberger Ltd and Baker Hughes Co occupy positions that exemplify bundled separation technology provision. Alfa Laval AB anchors the compact equipment archetype through modular design specialization. Among North American fabricators, Canadian Petroleum Processing Equipment Inc represents regional pressure vessel qualification capabilities. These three companies collectively span the procurement consolidation trajectory reshaping vendor-customer relationships in Middle East refinery expansions.
| Leading Market Players |
|---|
| Desalters LLC |
| Frames Group |
| Agar Corporation Ltd |
| Schlumberger Ltd |
| Alfa Laval AB |
| Canadian Petroleum Processing Equipment Inc |
| Forum Energy Technologies |
| Baker Hughes Co |
| AMR Process Limited |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at API 12J-certified fabrication yards in the US Gulf Coast and Saudi Arabia determines price floors across the desalter market. Scale economies in pressure vessel construction concentrate procurement leverage among national oil companies, compressing margins for non-integrated vendors while elevating cost-plus contract premiums for qualified suppliers.
Pricing Analysis
Cost-plus contracts with nickel and molybdenum indexation dominate desalter procurement. Price differentiation rests on API 12J certification tier and after-sales service bundling. Cost compression in standard electrostatic units is intensifying because membrane technology is capturing specification share at the premium end. Independent fabricators exhibit highest price sensitivity; integrated service providers with captive metallurgical supply chains demonstrate lowest.
Supply Chain Analysis
Strait of Hormuz transit underwrites raw material flows for sour-service alloy inputs. Supply concentrates in the United States, Saudi Arabia, and South Korea for pressure vessel fabrication. Construction draws from nickel-molybdenum superalloys, high-grade carbon steel plate, and specialized transformer components. Single-source vulnerability in API 12J certification capacity poses structural risk. Distribution runs through EPC contractors and national oil company engineering procurement divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping desalter procurement as integrated project delivery models bundle separation hardware with water treatment and downstream processing. Interoperability between desalter automation and legacy refinery distributed control systems is becoming the ecosystem gatekeeper.
For Market Incumbents: Fortify API 12J certification maintenance programs to preserve qualification barriers against emerging membrane specialists. Deepen backward integration into corrosion-resistant alloy supply through captive foundry partnerships or long-term offtake agreements with South Korean and US metallurgical producers. Membrane-electrostatic hybrid systems from unbundled technology vendors represent the primary substitution threat.
For New Entrants and Emerging Players: Aftermarket electrode array replacement and high-voltage transformer servicing present service-layer gaps where incumbents under-serve. Target offshore platform retrofit specifications in the North Sea and West African FPSO fleets where compact modular formats face minimal entrenched competition. Pursue OEM partnerships with Alfa Laval or Forum Energy Technologies to bypass API 12J qualification timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane-electrostatic hybrid specialists with proven pilot deployments. Long-term viability hinges on regulatory chemistry substitution tailwinds from REACH and bio-based demulsifier formulation capabilities. Acquisition targets should demonstrate installed base in medium-API crude applications with documented operating cost reduction. Monitor EPA effluent guideline enforcement intensity as the inflection signal for US refinery upgrade cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API 12J Certification Maintenance | Preserves market access for Saudi Aramco and ADNOC refinery awards. |
| Membrane-Electrostatic Hybrid Development | Captures specification share from EPA-driven chemical reduction mandates. |
| Backward Integration into Alloy Supply | Insulates margins from nickel-molybdenum price volatility in sour service. |
| Offshore Platform Retrofit Specialization | Addresses whitespace in aging FPSO vessel upgrade cycles. |
| Bio-Based Demulsifier Formulation | Aligns with REACH restrictions on ethoxylated phenol chemistries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery engineering directors, EPC procurement leads, pressure vessel fabrication plant managers, and aftermarket service technicians. Secondary validation drew from EPA effluent limitation guideline filings, Saudi Aramco engineering standard documentation, API 12J certification registries, and SEC 10-K disclosures from listed oilfield services conglomerates. Bottom-up equipment shipment tallies and top-down refinery capital expenditure tracking were triangulated to establish market sizing.
Across the analysis window, forecasts incorporate technology substitution curves, regulatory compliance cost pass-through rates, and national oil company procurement cycle timing. Segmentation modeling covers electrostatic, membrane, chemical, and thermal technology tiers; horizontal, compact, vertical, and modular product architectures; and refinery, petrochemical, oil producer, and utility end-use categories. CAGRs were derived from capacity expansion announcements and replacement demand run-rates for existing installed base.
Underlying assumptions cover sustained EPA enforcement of chloride discharge thresholds, stable Saudi Aramco downstream investment commitments, and nickel-molybdenum alloy price bands within historical volatility ranges, with deviation risk concentrated in regulatory rollback scenarios or metallurgical supply disruptions. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and Scope 3 accounting rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Well Casing Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Drill Collar Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market