
 Blueberry Ingredient Market | 2026-2036
Blueberry Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Blueberry Ingredient Market Outlook
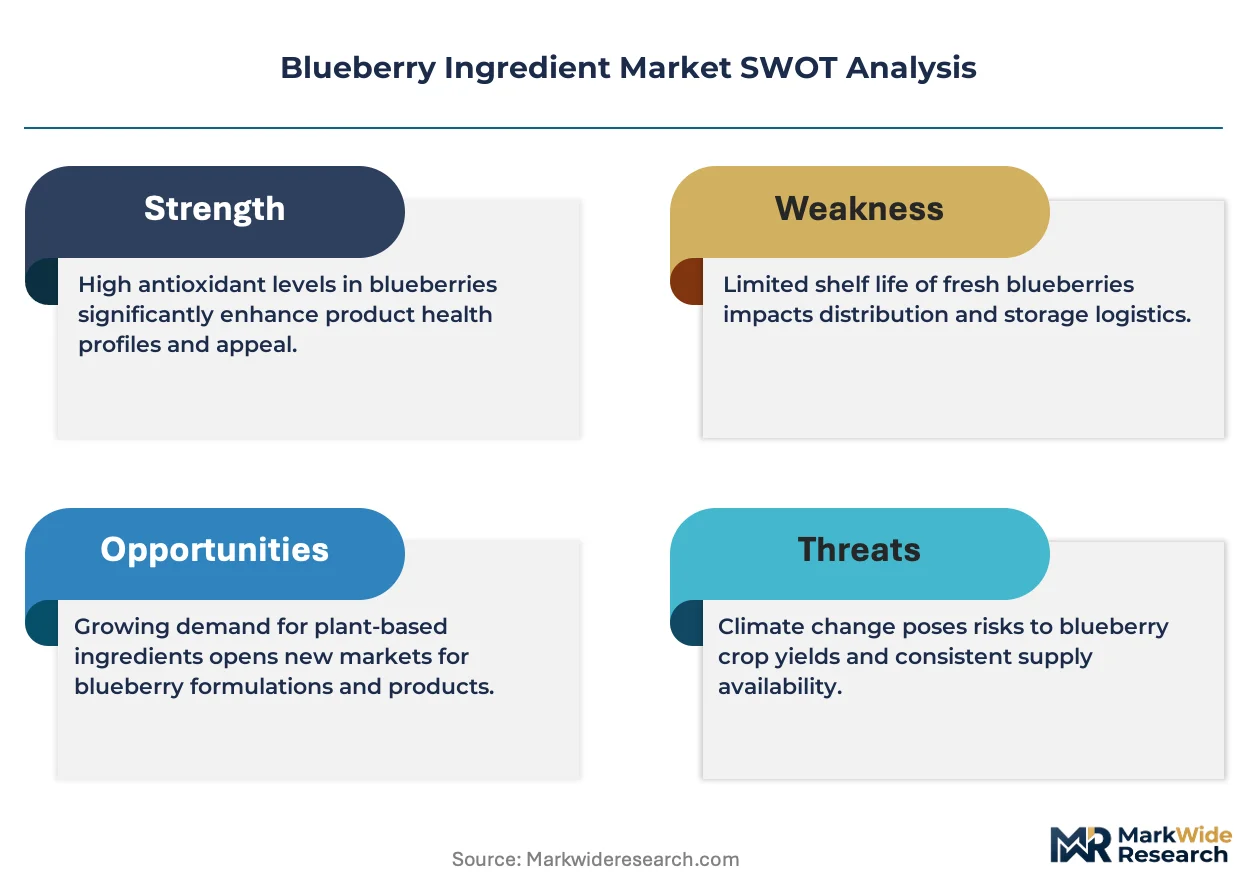
North American processing capacity, particularly in Michigan and Oregon growing regions, is reshaping supply availability for freeze-dried formats. ADM leverages its grain and specialty ingredient infrastructure to secure long-term berry contracts with co-operative growers. Kerry Group anchors its position through flavor-system integration, pairing blueberry concentrates with beverage emulsion technologies. Graceland Fruit dominates the industrial dried-fruit segment, operating controlled-atmosphere dehydration lines that preserve anthocyanin levels for bakery and snack applications.
Blueberry ingredients encompass processed or minimally processed forms derived from cultivated and wild Vaccinium species, standardized by parameters such as Brix levels in juice concentrates, particle size in spray-dried powders, and moisture content below four percent in freeze-dried whole berries, serving primarily as functional colorants, flavor carriers, and antioxidant sources across packaged goods. Freeze-dried blueberries command premium positioning in dietary supplements where whole-food labeling and minimal thermal degradation justify higher input costs, while blueberry juice concentrate competes on volume in beverage formulations where cost-per-serving drives procurement decisions. Blueberry powder occupies a narrowing middle tier, pressured by dual substitution from both whole freeze-dried pieces for clean-label claims and concentrated extracts for potency-focused nutraceuticals.
FDA dietary supplement cGMP enforcement and USDA organic certification requirements shape ingredient sourcing transparency, particularly for wild-harvested blueberry derivatives where traceability gaps create audit risk for finished goods manufacturers. The EPA's pesticide tolerance frameworks for berry crops influence conventional versus organic price spreads and determine which growing regions qualify for export-oriented processing. EFSA health claim evaluations on blueberry polyphenols create divergent marketing permissions between North American and European finished product positioning. Stakeholders must monitor evolving organic equivalency agreements and polyphenol extraction patent filings to anticipate which ingredient formats will retain formulation access across major demand jurisdictions.
Market Dynamics
FDA dietary supplement cGMP enforcement and USDA organic certification requirements are compressing supplier qualification timelines, forcing finished goods manufacturers to consolidate procurement around fewer qualified blueberry ingredient processors with verified traceability systems.
Growth Catalysts
- EFSA health claim evaluations:European nutraceutical firms are accelerating blueberry polyphenol extract development ahead of anticipated positive rulings on antioxidant cardiovascular benefits.
- Freeze-drying infrastructure clusters:Controlled-atmosphere storage and dehydration facilities concentrated in Oregon and Washington are reducing post-harvest anthocyanin degradation for premium supplement applications.
- Clean-label bakery reformulation:Industrial bakers are substituting synthetic colorants with standardized blueberry juice concentrates to meet retailer clean-ingredient mandates.
Market Restraints
- Wild-harvested supply volatility:Maine and eastern Canadian lowbush blueberry yields fluctuate with frost patterns, creating raw material shortages for heritage-positioned organic brands.
- Anthocyanin stability limitations:Current spray-drying technologies degrade polyphenol content by 15-40 percent, restricting powder applications in heat-processed foods.
- EPA pesticide tolerance compliance:Residue testing requirements for imported South American blueberry concentrates are extending customs clearance timelines and working capital cycles.
Strategic Opportunities
- Japan functional food integration:METI's Foods with Function Claims framework creates a regulatory pathway for blueberry-derived cognitive health positioning in an aging demographic.
- Upcycled pomace valorization:Juice processing waste streams containing concentrated skin polyphenols offer untapped feedstock for cost-competitive extract production.
- Direct-to-manufacturer e-procurement platforms:Specialty ingredient marketplaces are disintermediating traditional broker networks for mid-volume nutraceutical compounders.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel for anthocyanin quantification via HPLC methods are concentrated in academic and government laboratories, not commercial quality control departments.
- Dual organic-conventional line certification:Segregated processing infrastructure requires parallel USDA Organic and conventional handling systems, doubling facility capital requirements.
- Legacy ERP traceability gaps:Existing inventory management systems lack lot-level field-to-finished-goods tracking demanded by cGMP audit protocols.
Report Scope
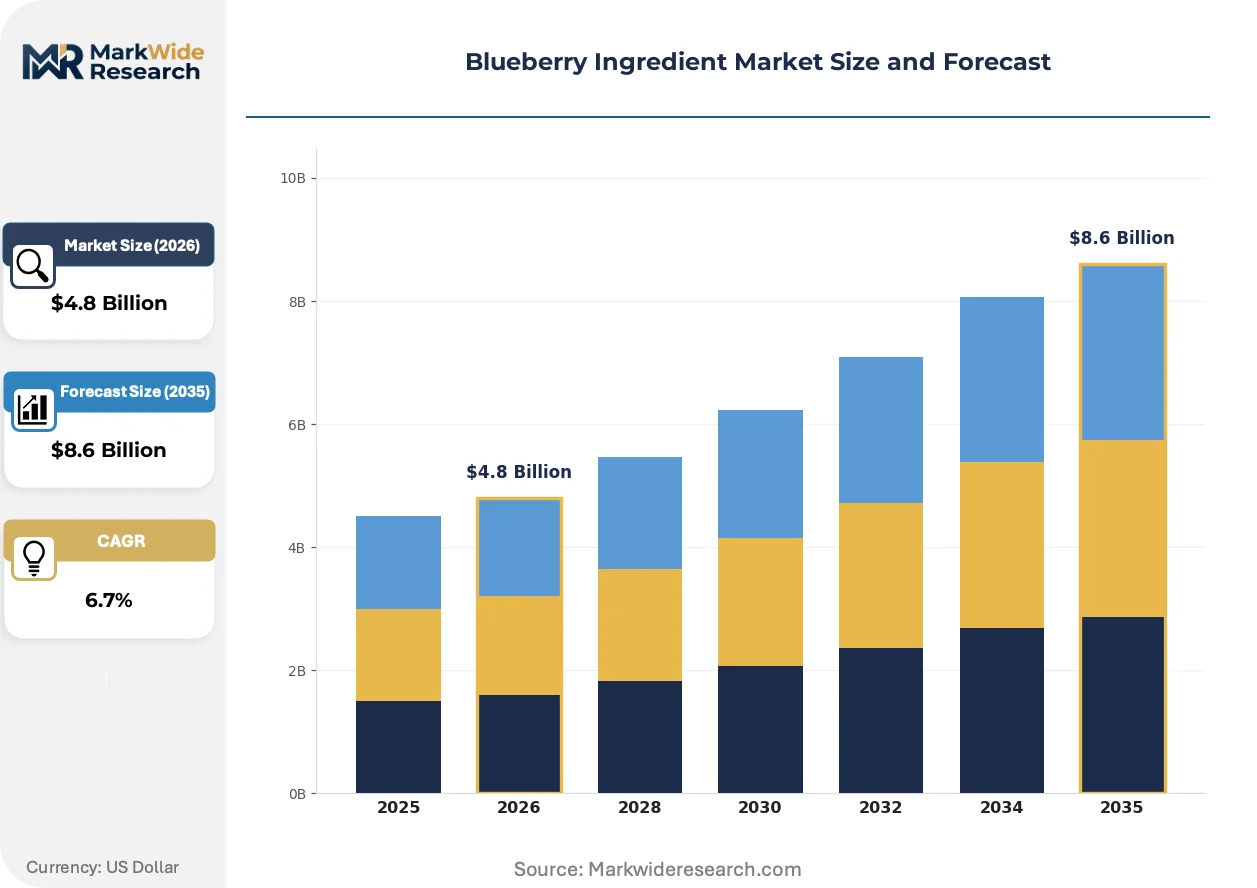
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blueberry Ingredient Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried Blueberries, Blueberry Powder, Blueberry Juice Concentrate, Fresh Blueberries Application: Beverages, Bakery Products, Snacks, Dietary Supplements End User: Food Manufacturers, Beverage Companies, Nutraceutical Firms, Retail Consumers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Distributors |
| Companies Covered | Ocean Spray Cranberries, ADM, Kerry Group, Döhler, Symrise, Ingredion Incorporated, Berry Global Group, Graceland Fruit, R. J. Van Drunen & Sons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blueberry Ingredient Market Strategic Shifts
Processing technology convergence and regulatory disclosure mandates are compressing the viable supplier base while opening formulation opportunities for verified-origin blueberry derivatives with standardized bioactive content.
Low-temperature vacuum belt drying is hybridizing conventional dehydration economics with freeze-dried quality parameters. Nutraceutical contract manufacturers in the Pacific Northwest are piloting these systems to capture mid-tier pricing between premium freeze-dried and commodity spray-dried formats. This technology convergence is enabling whole-food labeling claims at input costs 40 percent below traditional lyophilization.
USDA's National Organic Program updated equivalency determinations for imported blueberry derivatives are tightening foreign supplier audit requirements. European and South American processors must now demonstrate equivalent organic integrity to access US-labeled finished goods supply chains. Small-scale Peruvian and Chilean concentrate exporters face disqualification risk from enhanced paperwork and inspection protocols.
Brand procurement departments are consolidating supplier relationships around vertically integrated processors with captive cultivation and in-house analytical laboratories. This concentration displaces fragmented spot-market purchasing for anthocyanin-standardized ingredients. Dietary supplement manufacturers in California and Utah exhibit the most aggressive consolidation, driven by FDA warning letter exposure for mislabeled polyphenol content.
Blueberry Ingredient Market Segmentation
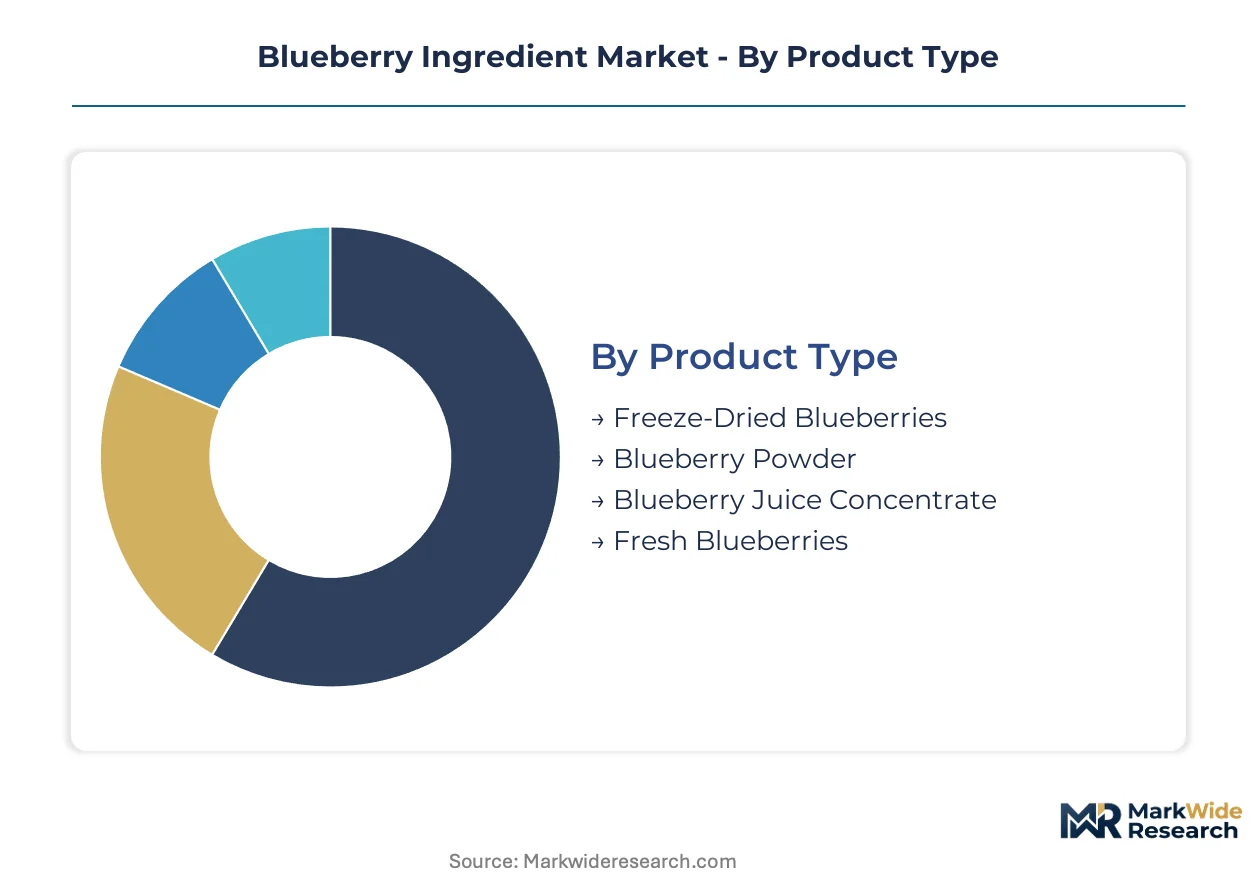
Ingredient format dictates procurement economics and regulatory compliance pathways for blueberry derivatives. Application-specific anthocyanin stability requirements and end-user quality thresholds fragment supplier qualification across distinct value chains.
Product Type:
Cost tier stratification separates premium preservation methods from commodity processing alternatives, with thermal degradation tolerance determining viable end-use markets.
- Freeze-Dried Blueberries:Lyophilization preserves cellular structure and anthocyanin integrity above 90 percent, commanding input costs 3-4x above conventional drying. Supplement manufacturers in Utah and California concentrate procurement here for whole-food labeling compliance with FDA cGMP documentation requirements.
- Blueberry Powder:Spray-dried and vacuum-belt formats occupy a narrowing middle tier, with polyphenol retention ranging 60-85 percent depending on inlet temperature parameters. Industrial bakers leverage standardized powder for consistent colorant dosing in high-throughput production lines.
- Blueberry Juice Concentrate:Volume-driven procurement for beverage formulations, with Brix standardization enabling cost-per-serving optimization.
- Fresh Blueberries:Minimal processing for immediate consumption channels and premium foodservice applications.
Freeze-dried formats command the established base. The steepest expansion runs through vacuum-belt hybrid technologies bridging quality and cost thresholds.
Application:
End-use thermal processing intensity and clean-label mandate stringency reshape ingredient selection criteria across packaged goods categories.
- Beverages:Juice concentrates dominate volume procurement for ready-to-drink formulations, with emulsion stability requirements driving Kerry Group's flavor-system integration investments. Carbonated and still beverage manufacturers prioritize Brix consistency over polyphenol retention.
- Bakery Products:Synthetic colorant substitution mandates from major retailers accelerate standardized concentrate adoption. Moisture migration control in freeze-thaw applications favors low-water-activity dried formats.
- Snacks:Texture preservation in extruded and coated applications limits viable ingredient formats to specific particle size distributions.
- Dietary Supplements:Capsule and tablet manufacturers demand Certificates of Analysis documenting anthocyanin content per serving.
Beverage applications anchor volume demand. Dietary supplements are climbing the fastest on EFSA health claim anticipation and METI Foods with Function Claims pathway development.
End User:
Customer scale and regulatory exposure determine supplier consolidation patterns, with large compounders displacing fragmented spot-market purchasing.
- Food Manufacturers:Industrial procurement departments consolidate around vertically integrated processors with captive cultivation and in-house HPLC analytical capabilities.
- Beverage Companies:Emulsion technology requirements favor partnerships with integrated flavor houses over commodity ingredient suppliers.
- Nutraceutical Firms:FDA warning letter exposure drives aggressive supplier qualification, compressing viable processor pools to Oregon and Washington cluster facilities.
- Retail Consumers:Direct procurement of dried formats through e-commerce channels, with organic certification premiums influencing purchase decisions.
Food manufacturers represent the volume anchor. Nutraceutical firms are expanding most quickly on regulatory compliance investments.
Distribution Channel:
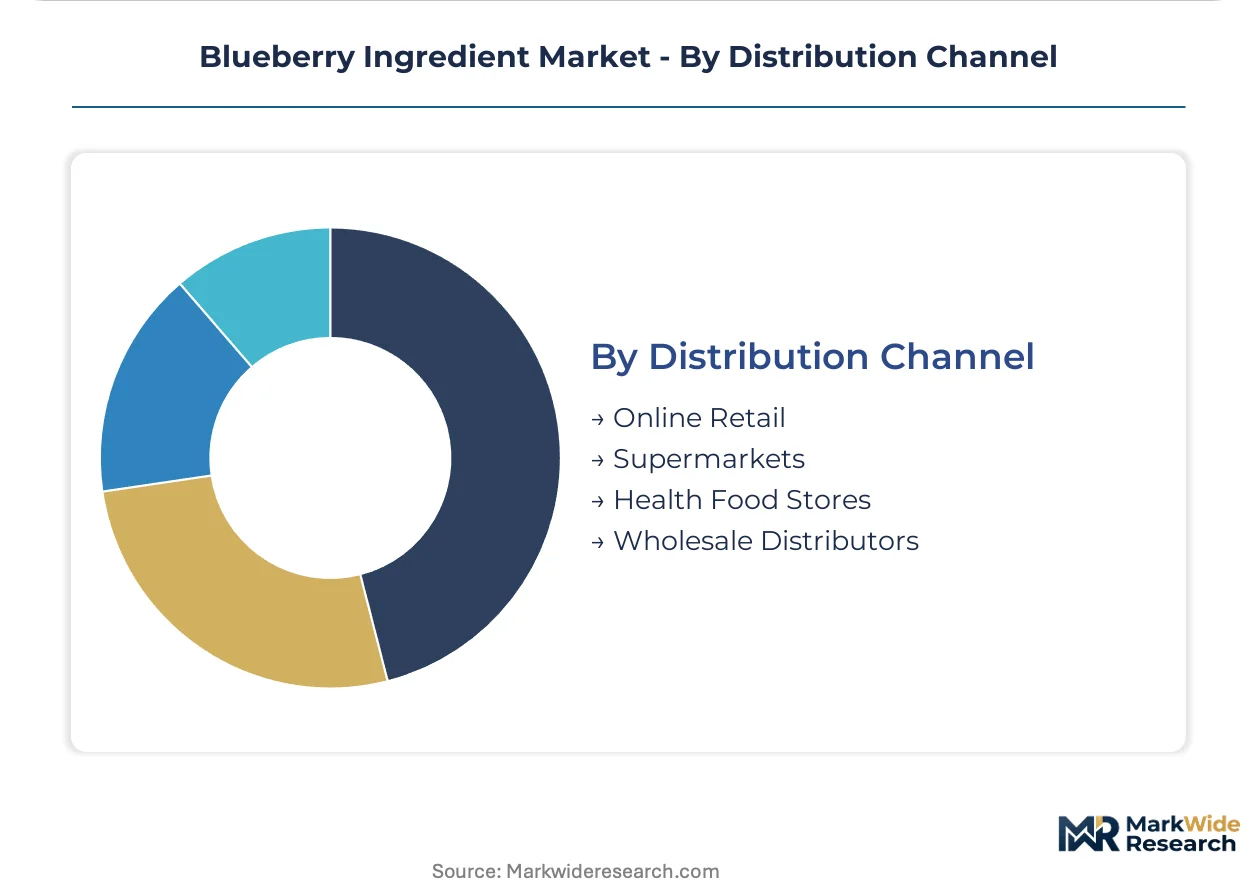
Channel selection reflects order scale, traceability documentation requirements, and buyer technical sophistication.
- Online Retail:Specialty ingredient marketplaces disintermediate traditional broker networks for mid-volume compounders, with lot-level traceability data becoming table stakes.
- Supermarkets:Private-label procurement departments demand standardized specifications across seasonal supply fluctuations.
- Health Food Stores:Heritage-positioned organic brands source wild-harvested derivatives, facing Maine and eastern Canadian yield volatility.
- Wholesale Distributors:Traditional broker networks retain relevance for large-volume conventional concentrate transactions with extended payment terms.
Wholesale distributors retain the established base. Online retail channels are gaining share fastest on procurement efficiency and documentation transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeze-drying infrastructure concentrates in the United States Pacific Northwest, with Oregon and Washington hosting controlled-atmosphere storage clusters that minimize post-harvest anthocyanin degradation. This supply-side clustering shapes procurement economics for nutraceutical and clean-label food manufacturers worldwide.
United States
Michigan and Oregon growing regions anchor North American processing capacity for freeze-dried formats. FDA dietary supplement cGMP enforcement compresses supplier qualification timelines, forcing consolidation around verified-traceability processors. The Willamette Valley cluster in Oregon integrates captive cultivation with in-house HPLC analytical laboratories serving Utah and California supplement manufacturers.
Canada
Eastern Canadian lowbush blueberry yields supply heritage-positioned organic brands facing frost-pattern volatility. Health Canada and PMRA pesticide tolerance frameworks determine which imported concentrates qualify for cross-border processing. Quebec and New Brunswick wild-harvest operations serve niche health food channels demanding traceable wild Vaccinium sourcing.
Germany
EMA and EFSA regulatory frameworks shape European nutraceutical formulation strategies ahead of anticipated polyphenol health claim rulings. Bavaria and Baden-Württemberg host flavor-system integrators pairing blueberry concentrates with beverage emulsion technologies. German processors leverage REACH compliance infrastructure to access North American organic equivalency agreements.
Japan
METI's Foods with Function Claims framework creates regulatory pathways for cognitive health positioning in an aging demographic. Kanto region contract manufacturers pilot low-temperature vacuum belt drying to bridge freeze-dried quality with mid-tier pricing. Japanese procurement departments demand lot-level field-to-finished-goods tracking exceeding domestic cGMP protocols.
Chile
Peruvian and Chilean concentrate exporters face disqualification risk from USDA National Organic Program equivalency determinations tightening foreign supplier audits. Central Valley processing facilities serve volume-driven North American beverage formulations. EPA residue testing requirements for imported concentrates extend customs clearance timelines and working capital cycles for South American exporters.
Blueberry Ingredient Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with format-specific preservation technologies. The supplier base fragments across three quality tiers: premium lyophilization operators, mid-market vacuum-belt hybrid processors, and commodity spray-dried concentrate exporters. Strategic archetypes include vertically integrated cultivator-processors with captive analytical laboratories, flavor-system integrators with emulsion technology platforms, and industrial dried-fruit specialists with controlled-atmosphere dehydration lines. Dominant competitive moves encompass backward integration into cooperative grower contracts and portfolio diversification into upcycled pomace valorization.
Among North American ingredient processors, ADM leverages grain and specialty ingredient infrastructure to secure long-term berry contracts, exemplifying the integrated agricultural conglomerate archetype. Kerry Group anchors its position through flavor-system integration, representing the beverage emulsion technology tier. Graceland Fruit occupies a position within the industrial dried-fruit segment, operating controlled-atmosphere dehydration lines that preserve anthocyanin levels for bakery and snack applications.
| Leading Market Players |
|---|
| Ocean Spray Cranberries |
| ADM |
| Kerry Group |
| Döhler |
| Symrise |
| Ingredion Incorporated |
| Berry Global Group |
| Graceland Fruit |
| R. J. Van Drunen & Sons |
| Others |
Value Chain & Pricing Dynamics
Freeze-drying capacity utilization in Oregon and Washington clusters sits above 85 percent during peak harvest windows, compressing spot-market availability for premium formats and forcing nutraceutical buyers into annual contract structures with fixed-price escalators tied to anthocyanin standardization costs.
Pricing Analysis
FDA cGMP enforcement dictates the pricing tier structure across the blueberry ingredient landscape, separating qualified processors with verified traceability from commodity exporters facing audit disqualification. Three-tier pricing structure across premium freeze-dried, standard vacuum-belt, and economy spray-dried levels reflects certification grade and volume scale as primary differentiation drivers. Cost compression in the spray-dried tier is intensifying because South American concentrate exporters face extended EPA residue testing timelines. Beverage manufacturers exhibit the highest price sensitivity due to cost-per-serving procurement metrics, while dietary supplement brands absorb premium inputs for whole-food labeling compliance.
Supply Chain Analysis
Contract manufacturing concentration among Pacific Northwest lyophilization operators and Michigan controlled-atmosphere dehydration facilities shapes procurement access for North American finished goods producers. Supply draws from United States, Canada, and Chile as dominant geographic nodes, with raw material dependencies centering on wild lowbush harvests, highbush cultivated volumes, and imported concentrate feedstocks. Single-source vulnerability runs through Maine and eastern Canadian frost-exposed wild harvests. Distribution runs through vertically integrated processor-direct channels for qualified supplement manufacturers, with wholesale broker networks retaining relevance for commodity beverage concentrate transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blueberry ingredient demand is accelerating on regulatory inflection, with EFSA polyphenol health claim anticipation and METI Foods with Function Claims pathway development creating formulation access for cognitive and cardiovascular positioning in aging demographics.
For Market Incumbents: Entrench procurement relationships through captive grower contracts in Oregon and Washington clusters, securing priority allocation during capacity-constrained harvest windows. Invest in in-house HPLC analytical laboratories to preempt FDA warning letter exposure on mislabeled anthocyanin content. Vertical integration into upcycled pomace valorization addresses margin pressure from juice processing waste stream competition. For New Entrants and Emerging Players: Pursue vacuum-belt hybrid technology deployment to capture mid-tier pricing between premium freeze-dried and commodity spray-dried formats. Target Japanese functional food contract manufacturers seeking METI-compliant cognitive health ingredients with lot-level traceability documentation. Lead with direct-to-manufacturer e-procurement platform integration, disintermediating traditional broker networks for mid-volume nutraceutical compounders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated processor-operators with captive cultivation and multi-year supply agreements anchoring utilization rates. Long-term viability over the projection horizon rests on organic equivalency certification maintenance and patent positioning on polyphenol extraction methods. Acquisition focus should center on Pacific Northwest facilities with freeze-drying infrastructure and verified cGMP compliance records. Monitor EFSA ruling timelines and USDA equivalency determination updates as inflection indicators for European market access and South American supplier qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Grower Contracts | ADM secures long-term berry supply through agricultural infrastructure leverage near Michigan and Oregon cultivation zones. |
| Flavor-System Integration Investment | Kerry Group pairs blueberry concentrates with proprietary beverage emulsion technologies for carbonated and still drink manufacturers. |
| Controlled-Atmosphere Dehydration Scale-Up | Graceland Fruit expands industrial dried-fruit capacity preserving anthocyanin levels for clean-label bakery applications. |
| Pomace Valorization Technology Deployment | Juice processing waste streams containing concentrated skin polyphenols enable cost-competitive extract production feedstocks. |
| Direct-to-Manufacturer E-Procurement Platform Launch | Specialty ingredient marketplaces disintermediate traditional broker networks with lot-level traceability documentation transparency. |
Study Parameters
A standing panel of procurement directors at nutraceutical compounders, quality control managers at dietary supplement manufacturers, flavor application technologists at beverage houses, and agricultural cooperative managers provided ongoing calibration across primary interview cycles and secondary validation. Stakeholder input triangulated against FDA warning letter databases, USDA National Organic Program equivalency determinations, EFSA health claim submission filings, and customs import records for South American concentrate shipments. Bottom-up volume modeling across ingredient format segments reconciled with top-down value projections derived from processor capacity utilization and contract pricing disclosures.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning preservation technology tier, application thermal processing intensity, end-user regulatory exposure level, and geographic certification cluster. CAGRs emerged from weighted average growth assumptions calibrated to EFSA ruling probability, METI framework adoption velocity, and organic equivalency agreement expansion patterns. Forecast inputs incorporated freeze-drying capacity expansion pipelines, wild harvest yield volatility coefficients, and spray-drying technology polyphenol retention degradation curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural input costs, energy pricing for lyophilization operations, and cross-border logistics rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline adherence and technology adoption curves. Quarterly review of EFSA submission status, USDA equivalency audit outcomes, and Pacific Northwest capacity utilization reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Nisin for Food Market