
 Global Shortenings Market | 2026-2036
Global Shortenings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shortenings Market Outlook
Enzymatic interesterification is reconfiguring how manufacturers engineer fat crystallization without hydrogenation. Cargill leverages this biocatalytic platform to produce zero-trans shortenings for North American bakery clients. Bunge Limited anchors its supply position through backward integration into South American soybean crushing. Wilmar International dominates Southeast Asian palm-based shortening volumes with integrated refinery networks.
Shortenings are plasticized fat systems composed of triglyceride blends, typically exhibiting solid fat content between 15 and 35 percent at 25 degrees Celsius, engineered to entrap air in baked matrices and extend frying stability. Vegetable shortening leads product type value pools due to its cost position and reformulation flexibility, while lard retains premium positioning in artisanal European bakeries. Baking commands the largest application share, though confectionery demands drive higher-margin interesterified specialty fats.
The FDA enforces trans fat disclosure on nutrition labels, compelling reformulation toward fully hydrogenated or enzymatically modified alternatives. EFSA evaluates novel food status for enzymatic processes under EU food law, shaping market access timelines for European suppliers. ISO 22000 and FSSC 22000 certification frameworks govern supply chain eligibility for multinational food manufacturers. Stakeholders must monitor evolving enzyme approval pathways and tropical oil sustainability certification as dual determinants of sourcing strategy and brand positioning.
Market Dynamics
Enzymatic interesterification has displaced partial hydrogenation as the dominant processing pathway, forcing capital reallocation across manufacturing footprints and rewiring supplier-customer technical relationships in real time.
Growth Catalysts
- Trans Fat Labeling Mandates:FDA disclosure rules in the United States compel bakery and snack manufacturers to source zero-trans alternatives, expanding the addressable base for enzymatically modified shortenings.
- Southeast Asian Bakery Expansion:Industrial laminated dough production across Indonesia, Vietnam, and the Philippines drives procurement of high-performance vegetable shortenings with specific solid fat content profiles.
- Palm Oil Refinery Integration:Malaysian and Indonesian processors are capturing margin through captive olein and stearin fractions, securing feedstock leverage for specialty shortening formulations.
Market Restraints
- Input Cost Volatility:Crude palm oil price swings in Kuala Lumpur futures markets transmit directly to shortening manufacturing economics, compressing blender margins unpredictably.
- Supply Concentration Risk:Southeast Asian plantation groups control over 85 percent of global palm oil exports, creating single-source vulnerability for multinational food manufacturers.
- Technical Limitation:Enzymatic processes currently achieve narrower plasticity ranges than legacy hydrogenation, restricting application in certain industrial frying systems requiring extreme oxidative stability.
Strategic Opportunities
- Underpenetrated African Markets:Nigeria and Egypt exhibit rising bakery sector formalization with limited local shortening production capacity, creating import substitution openings for integrated suppliers.
- Clean Label Convergence:EU EFSA novel food pathways for enzymatic processes, combined with consumer preference for simplified ingredient declarations, reward early certification investments.
- Specialty Confectionery Fats:Cocoa butter equivalent and cocoa butter replacer segments command premium pricing, with enzymatic interesterification enabling precise melting profile engineering for temperate climate distribution.
Industry Challenges
- Enzyme Supplier Dependence:Lipase biocatalyst sourcing concentrates among Danish and Japanese biotechnology firms, creating licensing bottlenecks and royalty stacking for process scale-up.
- FSSC 22000 Certification Timelines:Multinational food manufacturers require 12-18 month supplier qualification cycles, delaying market entry for novel enzymatic shortening platforms.
- Legacy Equipment Retrofit Costs:Hydrogenation infrastructure cannot accommodate enzymatic process conditions without reactor redesign, stranding capital at mid-sized processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shortenings Market |
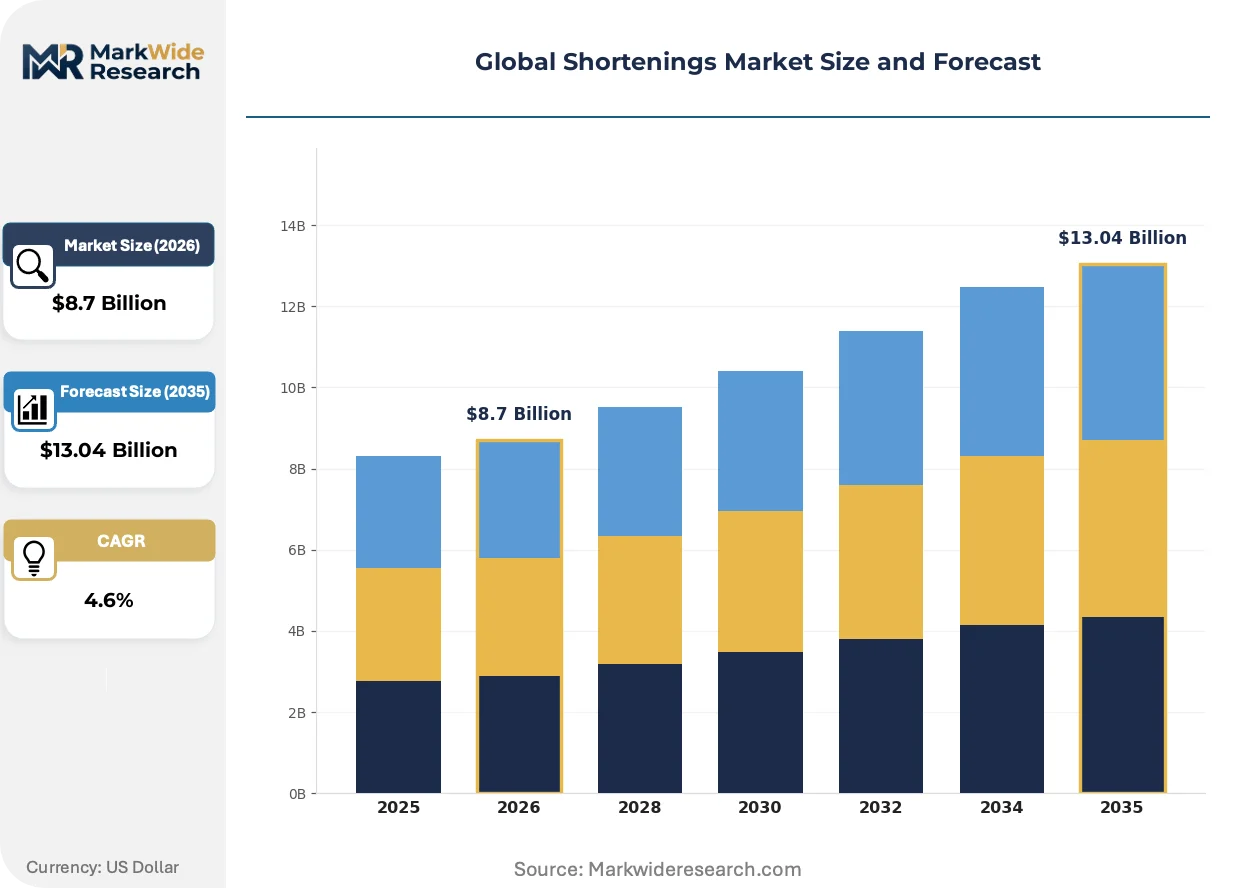
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Lard, Vegetable Shortening Application: Baking, Frying, Confectionery, Sauces End User: Food Manufacturers, Restaurants, Bakeries, Household Form: Solid, Liquid, Cream, Spray |
| Companies Covered | Cargill, Archer Daniels Midland, Bunge Limited, Wilmar International, Associated British Foods, AAK AB, Ventura Foods, Fuji Oil, Premium Vegetable Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shortenings Market Strategic Shifts
Biocatalytic processing architectures and sustainability verification systems are compressing traditional manufacturing timelines while fragmenting procurement authority across technical and commercial functions.
Enzymatic interesterification operates at ambient pressure with water as the sole byproduct, eliminating the need for nickel catalyst recovery and hydrogen gas handling. North American contract bakeries and multinational snack manufacturers have adopted this platform fastest, driven by FDA compliance deadlines and brand protection imperatives. The technology is rendering obsolete capital-intensive hydrogenation assets that cannot pivot to zero-trans production without complete reactor replacement.
EFSA maintains active evaluation queues for novel food enzyme applications under EU Regulation 2015/2283, with approval timelines averaging 18-24 months for microbial lipase strains. This regulatory friction delays European market entry for enzymatic shortening innovations already commercialized in the Americas. German and French industrial bakery groups are responding by accelerating in-house process validation to compress post-approval commercialization cycles.
Ingredient specification authority is migrating from procurement departments to food technology and regulatory affairs functions as clean label complexity intensifies. Large retail bakery chains and co-manufacturing platforms now demand batch-level traceability documentation and sustainability certification as standard contract terms. This shift is most pronounced in Northern European markets where ISO 22000 and RSPO supply chain certification function as baseline supplier eligibility filters rather than differentiators.
Global Shortenings Market Segmentation
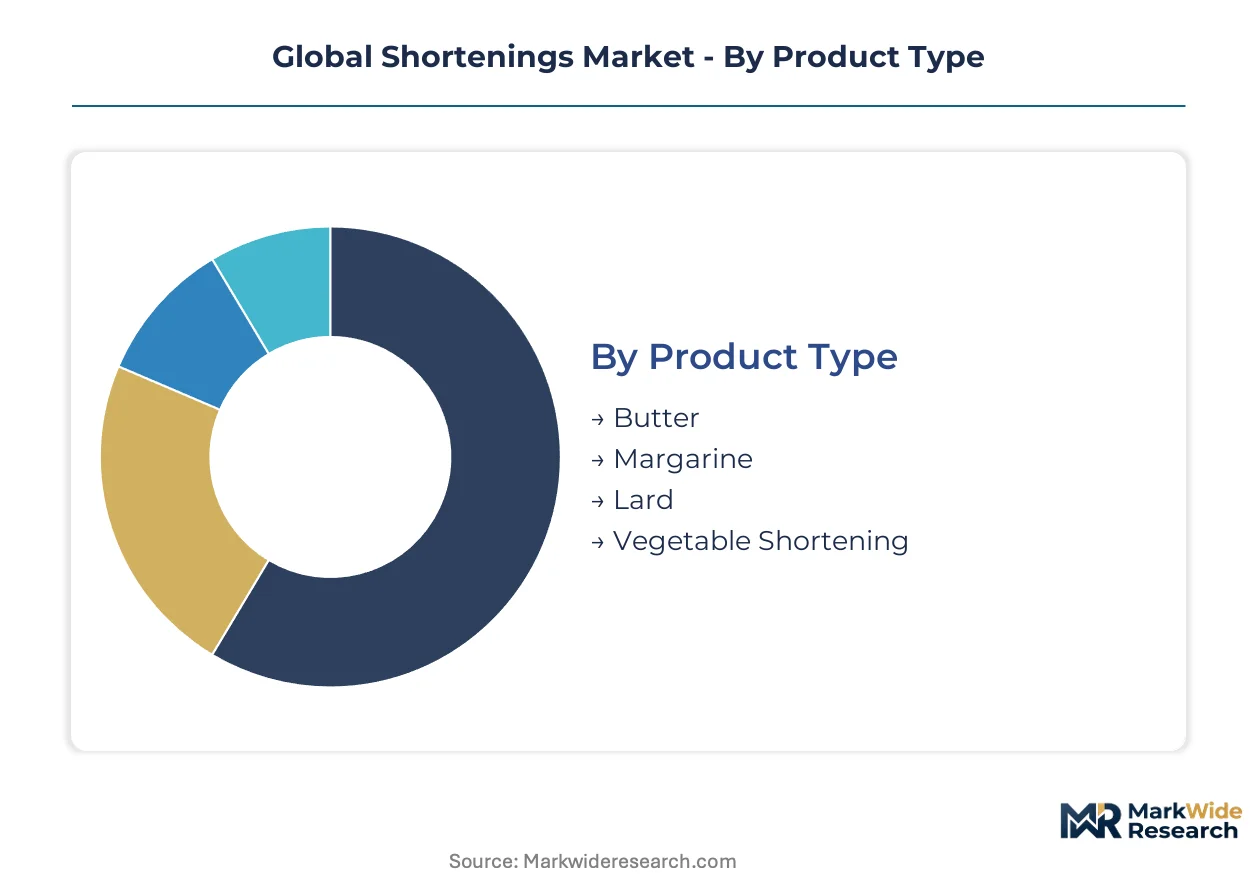
Shortening specifications diverge sharply across end-use applications, with solid fat content profiles and oxidative stability requirements dictating procurement decisions. Manufacturers configure product portfolios around four intersecting dimensions that determine margin structure and technical service intensity.
Product Type:
Cost tier differentiation separates commodity bulk sales from premium-positioned specialty fats with defined crystallization behavior.
- Vegetable Shortening:Triglyceride blends from palm, soybean, or canola oils deliver plastic fat systems with 15-35% solid fat content at 25°C. Southeast Asian bakery chains scale procurement for laminated dough production where precise aeration control determines product quality.
- Lard:Rendered pork fat retains premium positioning in artisanal European bakeries due to distinctive flavor contribution and crystallization properties that vegetable alternatives cannot replicate. Italian and French traditional producers specify lard for specific regional pastry applications despite higher unit costs.
- Butter:Milk fat-based shortening with minimum 80% fat content serves clean-label formulations where ingredient simplicity commands retail price premiums.
- Margarine:Water-in-fat emulsions with modified fat phases compete on cost position in industrial baking where flavor neutrality is acceptable.
Vegetable shortening commands the established base. The steepest expansion runs through enzymatically modified zero-trans variants.
Application:
Volume concentration and margin capture split unevenly across processing environments with divergent thermal stress requirements.
- Baking:Laminated dough, cake, and biscuit production consumes shortening volumes where fat crystallization rate determines manufacturing throughput. North American contract bakeries drive reformulation toward enzymatic interesterification to meet FDA trans fat disclosure deadlines.
- Frying:Industrial deep-frying applications in Southeast Asian palm oil processing corridors demand extreme oxidative stability that legacy hydrogenation achieved more cost-effectively than current enzymatic alternatives.
- Confectionery:Cocoa butter equivalents and replacers command premium pricing with precise melting profile engineering for temperate climate distribution.
- Sauces:Emulsion stability requirements in prepared dressings and spreads favor liquid or cream shortenings with specific solid fat index curves.
Baking captures the volume base. Confectionery specialty fats generate the highest margin per kilogram.
End User:
Customer type determines specification authority location and certification burden intensity.
- Food Manufacturers:Multinational snack and bakery corporations impose FSSC 22000 and RSPO certification as baseline eligibility filters, with 12-18 month supplier qualification cycles delaying novel enzymatic platform adoption.
- Bakeries:Industrial and artisanal baking operations split between cost-driven commodity procurement and premium specialty fat sourcing for differentiated product positioning.
- Restaurants:Foodservice frying applications prioritize price stability and supply security over technical performance optimization.
- Household:Retail shortening sales concentrate in emerging markets where home baking traditions persist and commercial bakery penetration remains limited.
Food manufacturers concentrate procurement authority. Bakeries represent the most technically demanding customer segment.
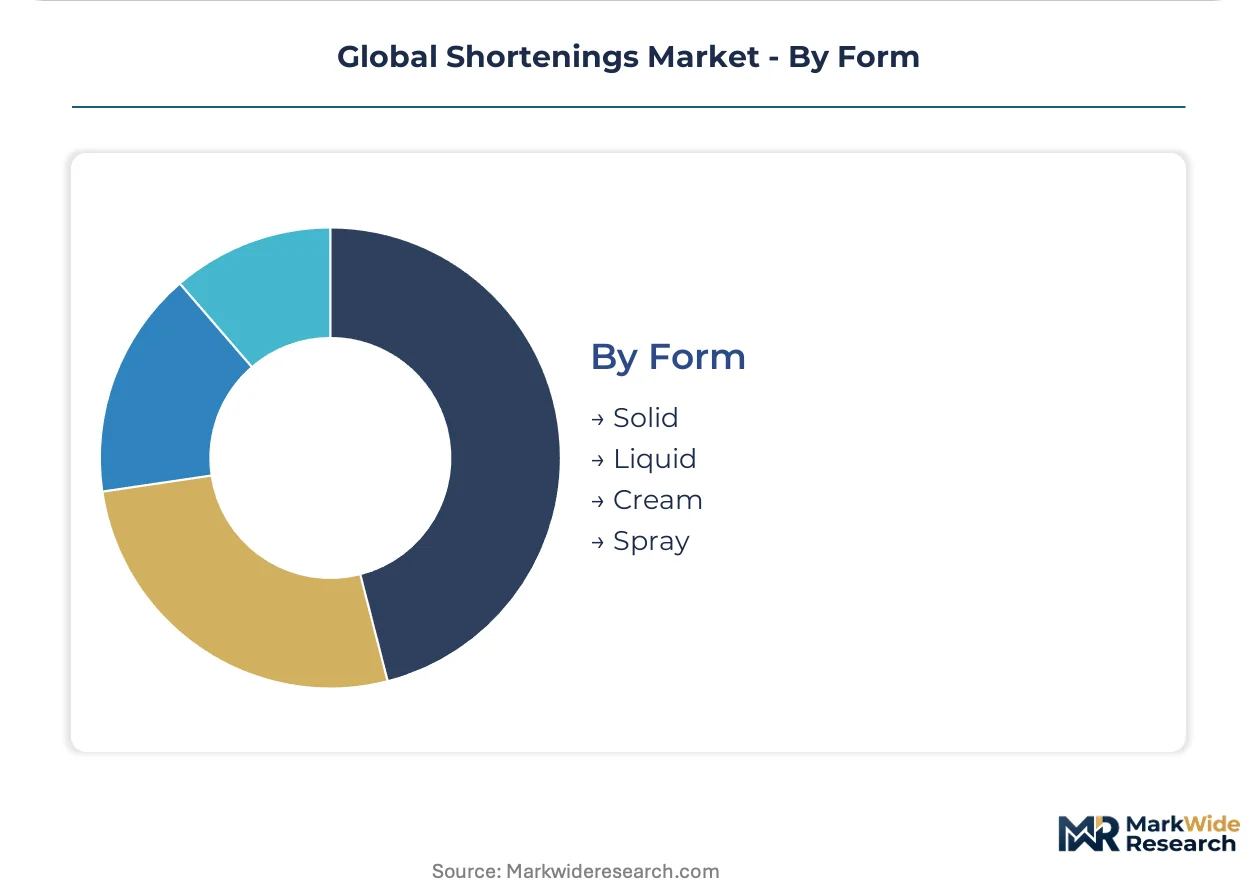
Form:
Physical state selection maps directly to processing equipment compatibility and labor cost economics.
- Solid:Block and cube formats dominate industrial baking where precise portioning and temperature-controlled handling infrastructure exists.
- Liquid:Pourable shortenings serve foodservice frying and sauce applications where melting step elimination reduces labor input.
- Cream:Tub-packaged formats target retail household segments and small commercial bakeries without bulk handling systems.
- Spray:Aerosolized application systems address specialized coating and release functions in industrial baking and confectionery molding.
Solid forms anchor industrial procurement. Liquid formats are gaining share fastest in foodservice channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia export refined palm oil fractions to North American and European bakery manufacturers, establishing the dominant trade corridor for shortening feedstocks. This flow pattern shapes regional production economics and regulatory compliance requirements across destination markets.
United States
FDA trans fat disclosure mandates drive bakery and snack manufacturers toward enzymatically modified zero-trans shortenings. The agency enforces strict labeling timelines that compress reformulation windows for industrial buyers. Chicago and Minneapolis host major contract bakery clusters where procurement specifications now exclude partially hydrogenated oils entirely.
Germany
EFSA novel food enzyme evaluations delay market entry for biocatalytic shortening innovations already commercialized elsewhere. REACH compliance adds chemical safety documentation burdens to imported fat formulations. The Rhine-Ruhr industrial corridor concentrates margarine and shortening production capacity serving Central European bakery chains.
Indonesia
Integrated palm oil refineries in Sumatra and Kalimantan capture margin through captive olein and stearin fractionation. The national government maintains biodiesel blending mandates that compete for crude palm oil supply. Surabaya and Medan function as export hubs for specialty shortening formulations bound for Southeast Asian bakery expansion.
Malaysia
Plantation groups control upstream feedstock leverage through vertical integration into downstream oleochemical processing. The Malaysian Palm Oil Board enforces sustainability certification requirements that multinational food manufacturers demand as baseline eligibility. Port Klang and Pasir Gudang anchor refining and export infrastructure for global shortening supply.
Brazil
Soybean crushing capacity in Mato Grosso and Paraná supplies domestic bakery sector growth while competing for export share. ANVISA maintains food additive regulations that shape import requirements for specialty fat formulations. São Paulo state concentrates industrial baking demand from formalized retail bakery chains and co-manufacturing platforms.
Global Shortenings Market Competitive Environment
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where scale advantages concentrate in integrated oilseed processors. Three archetypes dominate: plantation-integrated refiners with captive feedstock, multinational traders with global distribution networks, and regional blenders with technical service depth. Competitive moves center on backward integration into crushing assets and enzymatic technology licensing to secure zero-trans formulation capabilities.
Among plantation-integrated refiners, Wilmar International and Bunge Limited exemplify the upstream-control archetype through Southeast Asian and South American oilseed processing positions. Cargill occupies a position spanning trader and technology licensor roles with North American enzymatic platform deployment. AAK AB represents the specialty fat specialist tier with European confectionery fat engineering capabilities.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Bunge Limited |
| Wilmar International |
| Associated British Foods |
| AAK AB |
| Ventura Foods |
| Fuji Oil |
| Premium Vegetable Oils |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Malaysian palm oil refining is compressing spot premiums for olein and stearin fractions, forcing integrated processors to absorb margin erosion or push volume through long-term bakery contracts. This utilization imbalance grants multinational food manufacturers procurement leverage while stranding mid-sized blenders without backward integration into crushing assets.
Pricing Analysis
The enzymatic-to-hydrogenation pricing gap spans roughly 15-25 percent at bulk contract tiers, with next-generation biocatalytic platforms commanding premiums against legacy zero-trans alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by RSPO certification grade and solid fat content precision. Cost compression in standard-grade vegetable shortening is intensifying because Indonesian refinery expansions are flooding Southeast Asian spot markets. Industrial bakery chains exhibit highest price sensitivity due to reformulation volume scale, while artisanal European producers accept lard premiums for flavor specificity.
Supply Chain Analysis
Extended payment terms from 45 to 90 days have become standard for multinational food manufacturers sourcing from Malaysian and Indonesian plantation groups, with supply-chain finance facilities now covering 30-40 percent of trade flows. Upstream concentration in Indonesia, Malaysia, and Brazil creates feedstock dependencies on crude palm oil and soybean crush output. Single-source vulnerability concentrates in Southeast Asian olein fractionation, where Port Klang and Belawan anchor 60 percent of export-ready specialty shortening feedstock. Distribution runs through integrated refiner-traders with captive tankage and temperature-controlled bulk handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated North American and European bakery chains, which now dictate zero-trans reformulation timelines and certification requirements across supplier bases. This concentration fragments procurement authority between technical and commercial functions.
For Market Incumbents: Harden enzymatic platform defenses through exclusive lipase licensing agreements with Danish and Japanese biocatalyst suppliers, blocking rival access to cost-competitive zero-trans production. Secure backward integration into South American soybean crushing or Southeast Asian palm fractionation to defend margin position against feedstock volatility. FSSC 22000 certification renewal cycles represent the priority lever for locking out mid-sized regional blenders from multinational contract eligibility. For New Entrants and Emerging Players: Establish a beachhead in Nigerian and Egyptian industrial bakery markets where local shortening production capacity lags formal sector expansion. Target enzymatic interesterification retrofit services for stranded hydrogenation assets in Eastern European and Latin American mid-sized processors, offering toll processing partnerships that circumvent capital-intensive reactor replacement. A technical service-led go-to-market angle bypasses entrenched refiner-trader relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic processing infrastructure as lipase bioreactor scale-up demands specialized stainless-steel fabrication and temperature-control systems. Long-term viability favors plantation-integrated refiners with captive olein-stearin fractionation and established RSPO supply chain certification. The signal to watch is FDA enforcement discretion on trans fat disclosure timelines, which would accelerate or delay enzymatic platform payback periods.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Licensing | Secures biocatalytic production rights from Novozymes or Amano Enzyme for zero-trans formulation capabilities. |
| Backward Integration into Crushing | Captures olein and stearin margin through captive palm oil fractionation in Sumatra or Kalimantan. |
| RSPO Supply Chain Certification | Unlocks multinational food manufacturer procurement eligibility under ISO 22000 baseline requirements. |
| African Market Entry Partnership | Addresses underpenetrated Nigerian and Egyptian bakery formalization with import-substitution production. |
| Hydrogenation Asset Retrofit Services | Converts stranded legacy reactors to enzymatic processing through toll manufacturing arrangements. |
Study Parameters
Initial hypotheses were tested against primary input from refinery operations managers, bakery procurement directors, food technology R&D leads, and sustainability certification auditors, then refined through secondary validation against Malaysian Palm Oil Board production statistics, FDA enforcement discretion records, Kuala Lumpur futures exchange data, and FSSC 22000 certification registries. Bottom-up volume estimates from individual refinery capacity and top-down demand calibration from bakery sector output statistics were triangulated to converge on market sizing.
Demand-supply-balance modeling across the analysis window incorporated solid fat content tier, application thermal stress requirement, end-user certification burden, and regional regulatory cluster as segmentation dimensions. CAGRs were derived from slope analysis of year-over-year volume trajectories adjusted for capacity utilization inflection points. Palm oil biodiesel mandate competition and EFSA novel food enzyme approval queues served as industry-specific forecast inputs.
Sensitivities concentrate around crude palm oil price volatility, FDA trans fat enforcement timing, and EFSA lipase strain approval velocity. Forecasts reflect documented assumptions on enzymatic process yield rates and bakery sector formalization trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Global Wine Coolers Market