
 Vinasse Market | 2026-2036
Vinasse Market Size, Share, and Industry Trends Forecast 2026-2036
Vinasse Market Analytics
Agronomic expertise in potassium-rich effluent management is reorganizing competitive dynamics among ethanol processors. Raízen Energia S.A. leverages its integrated sugarcane-to-ethanol footprint to sustain captive vinasse volumes across Brazilian mill networks. Cofco Bio-Energy Co., Ltd. anchors its position through backward integration into corn-based distillery operations in China's Northeast Plain. Tereos Group competes by specializing in beet-derived vinasse conditioning for European fertilizer compliance.
Vinasse constitutes the residual liquid fraction remaining after ethanol distillation from sugarcane, sugar beet, or grain mash, typically carrying organic matter, potassium, and nitrogen at concentrations of 7-10% dry matter. Its primary commercial purpose centers on agricultural nutrient recycling and biogas substrate applications. Liquid vinasse dominates volume flows due to minimal processing requirements at distillery gate, while concentrated and dehydrated forms command premium positioning where transport economics favor reduced moisture. Animal feed applications represent the fastest-expanding consumption channel as protein recovery technologies mature, though fertilizer end-use retains the deepest margin pool through direct field application contracts.
Brazil's national environmental regulator enforces effluent discharge limits that compel distillery operators to convert vinasse into value-added outputs rather than releasing untreated streams. The EU Fertilizing Products Regulation and REACH frameworks restrict heavy metal content in recovered nutrients, shaping product certification requirements for European market access. Stakeholders must monitor evolving carbon credit methodologies for anaerobic digestion projects, as biogas valorization pathways increasingly determine vinasse pricing benchmarks against conventional fertilizer alternatives.
Market Dynamics
Brazil's ANA water agency enforces zero-discharge mandates on ethanol distilleries, forcing processors to monetize vinasse through fertilizer and biogas pathways rather than treat it as waste. This regulatory pressure compresses operational margins while creating captive supply pools that reshape competitive positioning across the value chain.
Growth Catalysts
- EU Fertilizing Products Regulation:Tightening contaminant thresholds for recycled nutrients accelerates certification demand for conditioned vinasse products entering European agricultural markets.
- Sugarcane ethanol expansion:Brazil's Northeast region is adding distillery capacity to meet RenovaBio biofuel targets, deepening regional vinasse supply availability for nutrient recovery processors.
- Biogas substrate valorization:Anaerobic digestion technology deployment at Brazilian mills converts organic matter into methane capture, creating dual-revenue streams from single effluent streams.
Market Restraints
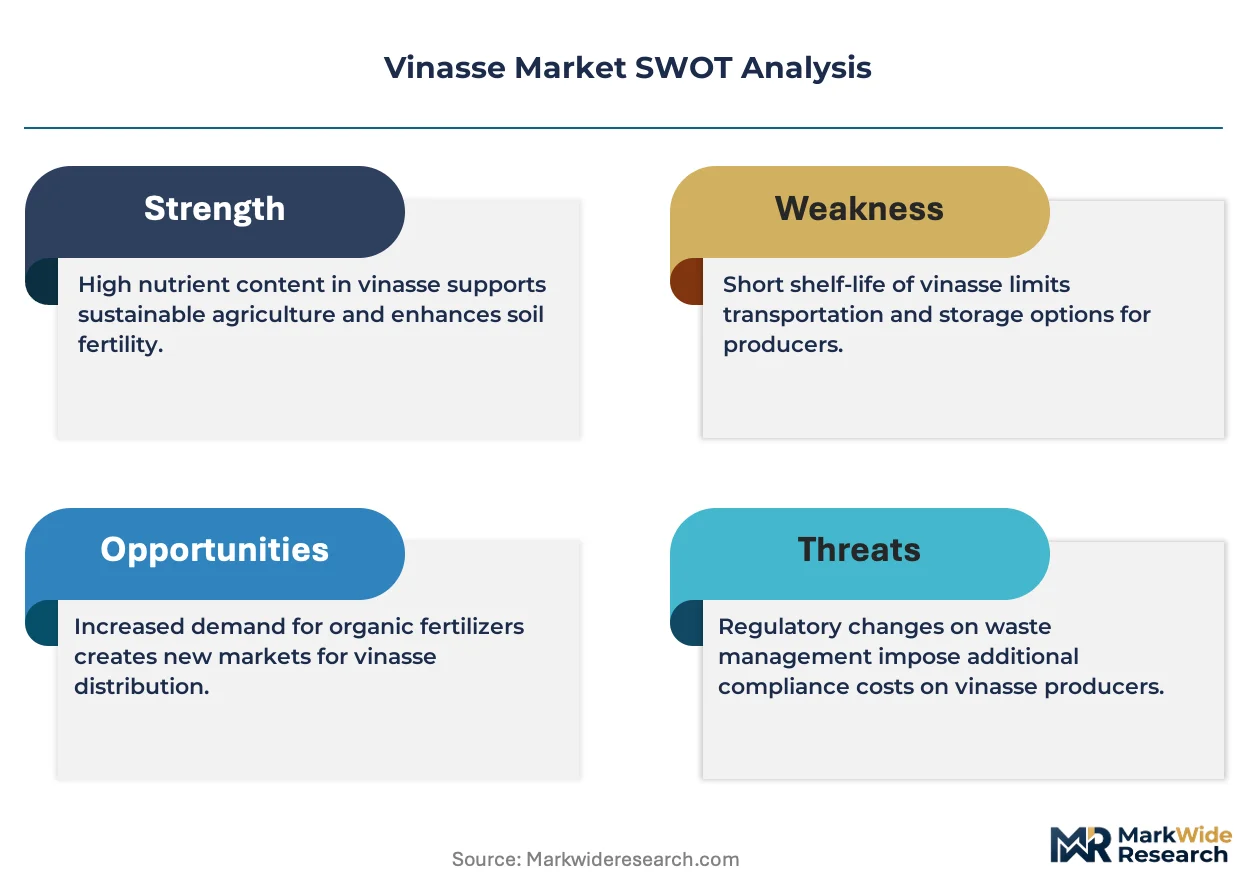
- Transport cost structure:Liquid vinasse's 93% water content imposes radius economics that limit viable distribution beyond 50 kilometers from distillery gates without concentration investment.
- Seasonal supply concentration:Brazilian harvest cycles concentrate vinasse generation during April-November, requiring storage infrastructure that locks working capital for fertilizer blenders.
- Synthetic fertilizer substitution:Urea and potash price volatility from Belarusian and Russian supply disruptions creates pricing pressure that compresses vinasse premium capture during commodity troughs.
Strategic Opportunities
- India's ethanol blending program:The country's 20% ethanol-by-2025 mandate is expanding molasses and grain-based distillery construction, creating new vinasse generation clusters in Uttar Pradesh and Maharashtra.
- Protein recovery from condensed solubles:Animal feed processors are extracting yeast biomass from vinasse streams, opening higher-margin outlets beyond traditional fertilizer application.
- Carbon credit methodology expansion:Brazil's national climate change secretariat is formalizing verification protocols for anaerobic digestion projects, enabling tradable offset generation from biogas capture investments.
Industry Challenges
- Agronomic calibration expertise:Field application of raw vinasse requires soil-specific potassium load management that most farm cooperatives lack without extension service support.
- Concentration technology capex:Evaporator and dryer installations for transportable product forms demand multi-million dollar outlays that smaller distilleries cannot finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinasse Market |
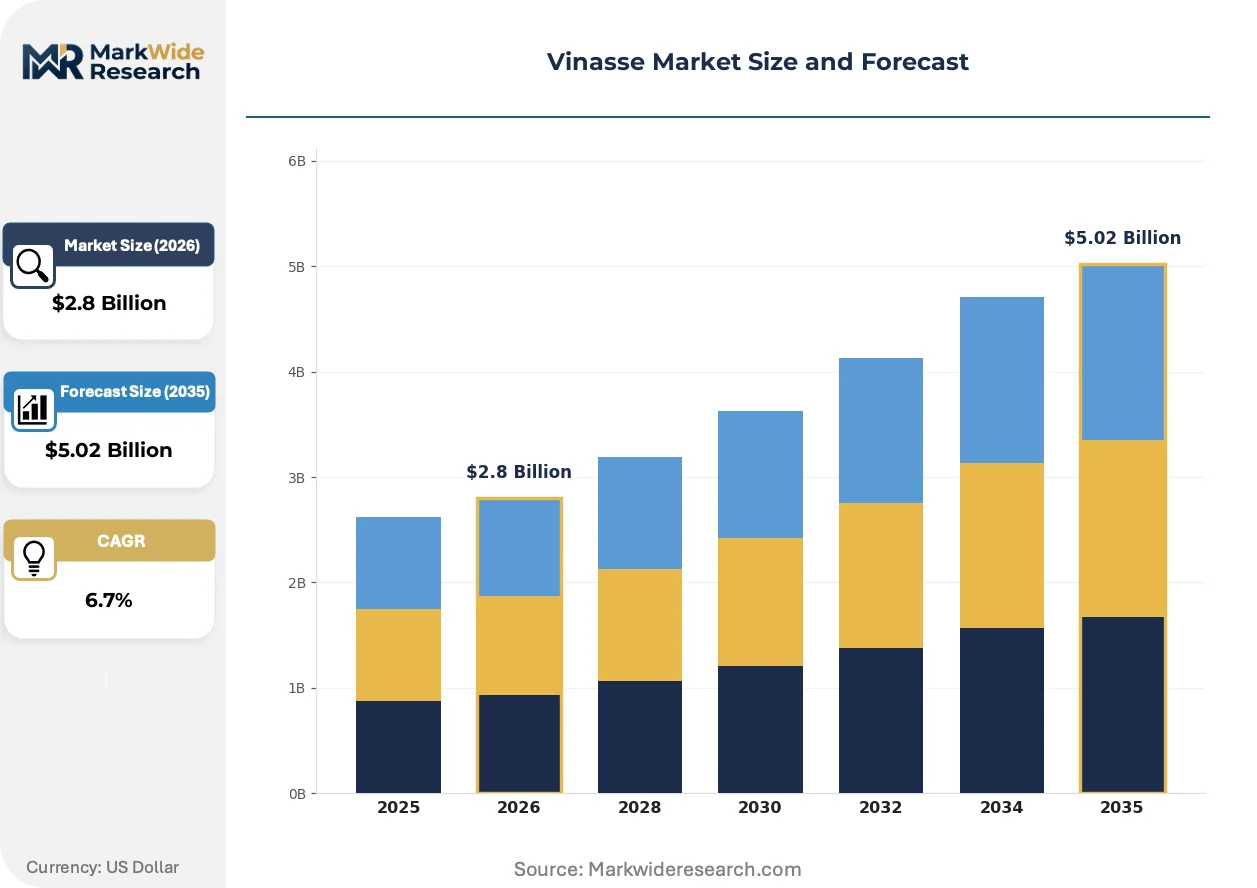
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Vinasse, Dehydrated Vinasse, Liquid Vinasse, Powdered Vinasse Application: Animal Feed, Fertilizer, Distillation, Biogas Production End User: Agriculture, Food Industry, Renewable Energy, Chemical Industry Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | Raízen Energia S.A., Cofco Bio-Energy Co., Ltd., Cargill, Inc., Tereos Group, Archer Daniels Midland Company, Balrampur Chini Mills Limited, Wilmar International Limited, Shree Renuka Sugars Ltd., BP Bunge Bioenergia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinasse Market Evolving Landscape
Membrane filtration and reverse osmosis systems are penetrating distillery operations at accelerating rates, enabling water recovery and nutrient concentration that alters product economics. These process intensification technologies compress the boundary between waste treatment and product manufacturing.
Electrodialysis reversal technology is fragmenting the conventional evaporation-dominated concentration landscape. Brazilian mill operators in São Paulo state are piloting modular membrane stacks that reduce energy intensity by 40% versus thermal methods. This diffusion is enabling smaller distilleries to enter dehydrated product markets previously reserved for integrated majors with captive energy supplies.
REACH enforcement through ECHA is tightening heavy metal documentation requirements for recovered nutrient products entering European Union member states. Fertilizer blenders in Germany and France now demand batch-level contaminant certificates that force Brazilian exporters to install spectroscopic testing equipment. Beet-derived vinasse processors in Northern France are capturing market access advantages through pre-existing compliance infrastructure.
Cooperative procurement consortia among São Paulo state sugarcane growers are displacing spot-market vinasse transactions with multi-year supply agreements tied to soil nutrient management plans. These structured contracts transfer price risk to distillery operators while guaranteeing offtake volumes. The model is spreading to Minas Gerais and Goiás as agricultural credit requirements tighten documentation of sustainable input sourcing.
Vinasse Market Segmentation
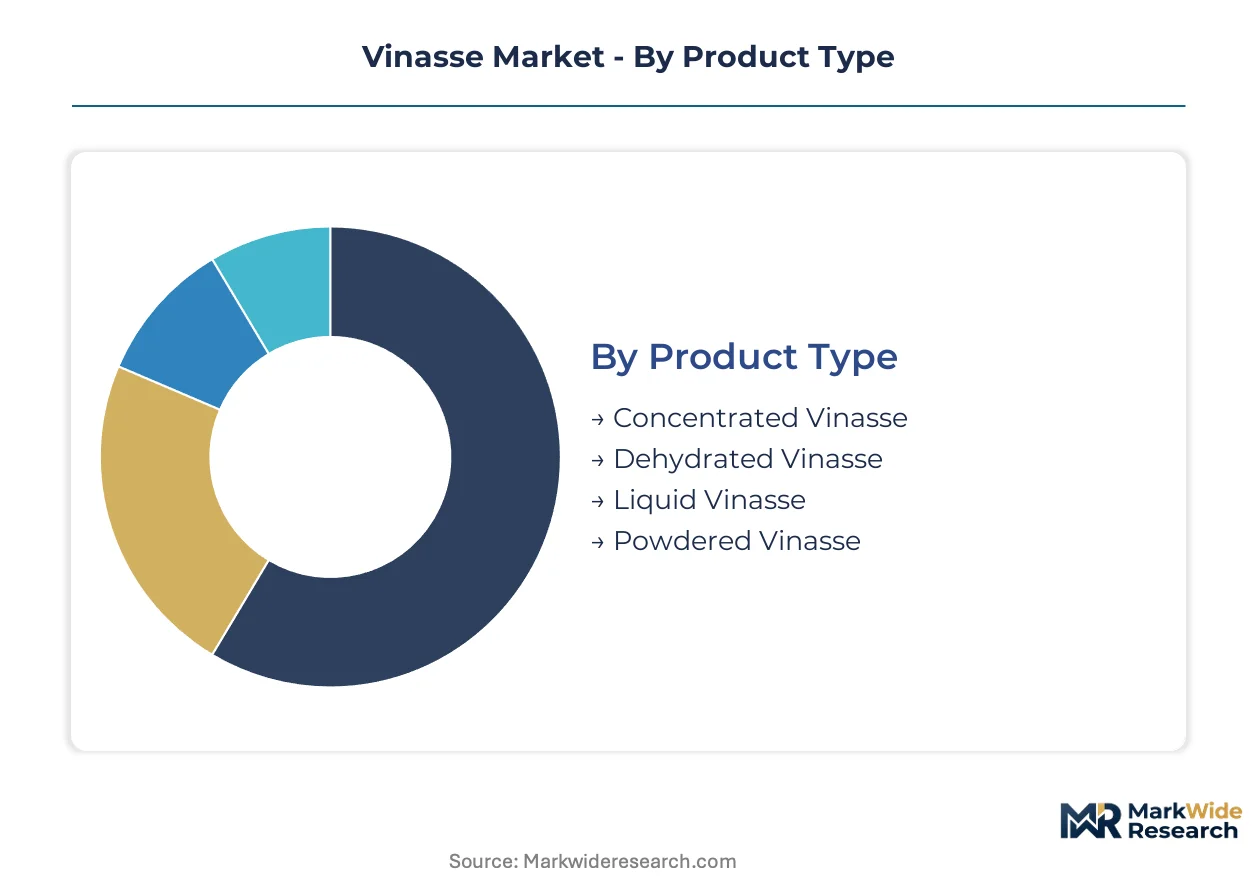
Vinasse segmentation reflects the tension between raw effluent disposal economics and value-added processing investments. Product form selection determines transport radius and end-use accessibility, while application channels diverge sharply between bulk agricultural offtake and specialized industrial recovery.
Product Type:
Liquid vinasse faces the most acute substitution pressure from synthetic fertilizers, as its high water content limits distribution reach and premium capture.
- Liquid Vinasse:The residual effluent stream exits distillation at 7-10% dry matter with minimal processing, dominating Brazilian field application through direct pipeline delivery to adjacent sugarcane plantations. São Paulo state cooperatives favor this form for potassium replacement under zero-discharge mandates from ANA.
- Concentrated Vinasse:Evaporator-reduced streams achieve 40-60% solids content, enabling truck transport beyond 50-kilometer radii to fertilizer blenders in Minas Gerais. Energy costs at smaller distilleries constrain supply expansion despite favorable logistics.
- Dehydrated Vinasse:Solid cake form commands premium positioning in European markets where REACH documentation requirements favor transportable, storable products with certified contaminant profiles.
- Powdered Vinasse:Micronized derivative serves specialty feed compounders requiring precise nutrient dosing, with protein recovery technologies driving uptake in poultry and aquaculture formulations.
Liquid vinasse anchors the volume base while concentrated forms gain share at the steepest rate as membrane filtration costs decline.
Application:
Application segmentation tracks margin dispersion between commodity nutrient cycling and emerging valorization pathways.
- Fertilizer:Direct soil amendment captures the deepest margin pool through long-term supply contracts with sugarcane cooperatives, though urea price volatility compresses premiums during commodity troughs.
- Animal Feed:Yeast biomass extraction from condensed solubles is climbing the fastest as protein recovery technologies mature, opening higher-margin outlets in poultry and ruminant nutrition.
- Biogas Production:Anaerobic digestion substrate generates methane capture revenue and carbon credit eligibility under Brazil's national climate change secretariat protocols.
- Distillation:Secondary ethanol recovery from residual sugars serves captive distillery operations, with limited third-party market development.
Fertilizer application retains volume dominance while animal feed channels expand most quickly on protein recovery economics.
End User:
End user concentration reflects the geographic clustering of ethanol production and downstream processing infrastructure.
- Agriculture:Sugarcane growers in São Paulo, Minas Gerais, and Goiás states constitute the primary offtake base, with cooperative procurement consortia displacing spot transactions.
- Renewable Energy:Biogas developers and carbon credit aggregators represent the emerging demand node, formalizing verification protocols for anaerobic digestion investments.
- Food Industry:Yeast extract and protein concentrate processors source conditioned vinasse for fermentation media and nutritional additives.
- Chemical Industry:Organic acid and biochemical producers pilot extraction of lactic acid and other platform chemicals from fermentation residues.
Agriculture commands the installed demand base while renewable energy end users are scaling fastest on carbon credit monetization.
Distribution Channel:
Channel structure follows the physical constraints of vinasse moisture content and the documentation requirements of regulated end markets.
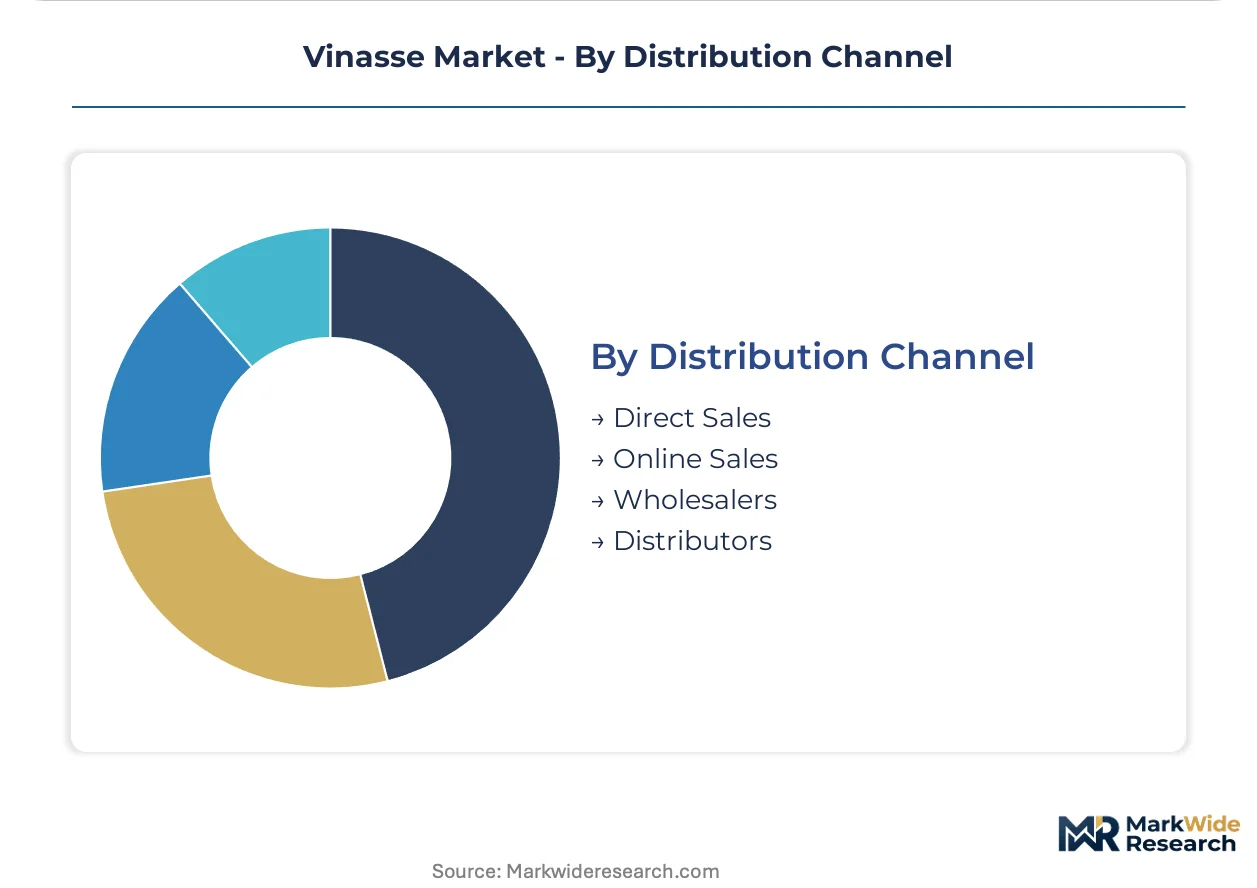
- Direct Sales:Pipeline and tanker contracts between distilleries and adjacent agricultural cooperatives eliminate intermediary margins, dominating Brazilian volume flows.
- Distributors:Regional fertilizer blenders aggregate concentrated and dehydrated forms for resale to smaller farms beyond direct delivery radii.
- Wholesalers:Bulk handlers manage inter-state and export movements of certified products, particularly for European REACH compliance.
- Online Sales:Digital procurement platforms serve specialty feed and biochemical buyers requiring small-batch, documented shipments with spectroscopic certificates.
Direct sales channels carry the volume foundation while distributor networks are extending fastest as concentration technologies expand supply reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes vinasse almost exclusively as liquid fertilizer under zero-discharge mandates, while European processors prioritize dehydrated forms for REACH-compliant export. India's emerging ethanol program is generating new vinasse clusters without established disposal infrastructure.
Brazil
Sugarcane cooperatives in São Paulo state anchor liquid vinasse demand through direct pipeline delivery to adjacent plantations. ANA water agency enforces zero-discharge mandates that compel distillery operators to monetize effluent rather than release untreated streams. The Northeast region is adding distillery capacity to meet RenovaBio biofuel targets, deepening regional supply pools in Pernambuco and Alagoas.
China
Corn-based ethanol expansion in the Northeast Plain is creating new vinasse generation clusters for fertilizer and feed applications. SAMR and MEE frameworks govern effluent discharge and nutrient recovery certification for agricultural inputs. Heilongjiang and Jilin provinces concentrate distillery construction where grain processing infrastructure already exists.
India
The 20 percent ethanol-by-2025 mandate is accelerating molasses and grain-based distillery construction in Uttar Pradesh and Maharashtra. BIS standards for organic fertilizers shape product quality requirements for vinasse-derived soil amendments. Distilleries in the Indo-Gangetic Plain lack established effluent management infrastructure, creating regulatory compliance pressure.
United States
Corn ethanol processors in Iowa and Illinois generate vinasse primarily for captive animal feed and regional fertilizer markets. EPA effluent guidelines and state-level nutrient management plans govern land application rates and seasonal restrictions. The Midwest corn belt concentrates production where integrated processors control downstream valorization pathways.
France
Beet sugar processors in Northern France specialize in conditioned vinasse for EU Fertilizing Products Regulation compliance. ECHA REACH enforcement requires batch-level heavy metal documentation that favors processors with pre-existing spectroscopic testing infrastructure. The beet processing corridor between Picardy and Champagne-Ardenne anchors European supply of certified dehydrated products.
Vinasse Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in vinasse valorization. Brazilian sugarcane majors and Chinese grain processors dominate liquid form production, while European beet specialists control dehydrated product certification. Three archetypes define competitive positioning: integrated ethanol-to-fertilizer operators, regional grain-based processors, and compliance-focused European conditioners. Capacity expansion and backward integration into captive distillery supply represent the dominant competitive moves across all tiers.
Among Brazilian integrated operators, Raízen Energia S.A. and BP Bunge Bioenergia exemplify the scale-driven archetype with captive mill networks. Cofco Bio-Energy Co., Ltd. anchors the Chinese grain-processing tier through its Northeast Plain presence. Tereos Group occupies a specialist position within European beet-derived vinasse conditioning for regulatory-compliant export markets.
| Leading Market Players |
|---|
| Raízen Energia S.A. |
| Cofco Bio-Energy Co., Ltd. |
| Cargill, Inc. |
| Tereos Group |
| Archer Daniels Midland Company |
| Balrampur Chini Mills Limited |
| Wilmar International Limited |
| Shree Renuka Sugars Ltd. |
| BP Bunge Bioenergia |
| Others |
Value Network & Pricing Analysis
Synthetic fertilizer substitution—urea and potash volatility from Eastern European supply disruptions—simultaneously compresses vinasse premium capture and redraws competitive geography toward Brazil's integrated sugarcane processors with captive potassium-rich effluent pools.
Pricing Analysis
Long-term offtake contracts between São Paulo distilleries and sugarcane cooperatives dominate Brazilian volume, while spot transactions persist only for surplus liquid vinasse beyond pipeline delivery radii. Price differentiation hinges on certification grade for EU Fertilizing Products Regulation compliance and transport moisture reduction through membrane concentration. Pricing pressure intensifies in liquid form as urea troughs erode organic fertilizer premiums. Smallholder cooperatives exhibit highest price sensitivity, whereas European blenders purchasing dehydrated products prioritize contaminant documentation over unit cost.
Supply Chain Analysis
Inventory cycles track Brazilian harvest seasonality, with April-November generation peaks forcing storage infrastructure commitments that lock working capital for fertilizer blenders. Supply concentrates in Brazil, China, and France, with raw material dependencies on sugarcane crush volumes, corn processing throughput, and beet sugar campaign timing. Single-source vulnerability runs through São Paulo state's pipeline network density. Distribution runs through direct pipeline contracts for liquid forms, regional distributors for concentrated products, and wholesalers for REACH-compliant European export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vinasse market sits in cyclical recovery as Brazilian RenovaBio biofuel targets expand distillery construction, deepening effluent supply pools that outpace current nutrient recovery processing capacity.
For Market Incumbents: Compound captive supply advantages by backward integration into membrane concentration technology at Northeast Brazil greenfield distilleries, and secure multi-year offtake agreements with Minas Gerais cooperatives before regional supply competition intensifies. Defend margin position against synthetic fertilizer substitution through soil-specific agronomic service bundling that locks in cooperative procurement consortia.
For New Entrants and Emerging Players: Differentiate on protein recovery technology for animal feed applications, where yeast biomass extraction margins exceed fertilizer pathways and customer concentration remains lower than sugarcane cooperative procurement. Target India's Uttar Pradesh molasses distilleries lacking established effluent management infrastructure, and enter through technology licensing partnerships rather than capital-heavy concentration asset builds.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Brazilian ethanol processors seeking exit liquidity before RenovaBio capacity additions mature. Five-to-ten year viability depends on carbon credit methodology formalization for anaerobic digestion projects. Watch for Brazil's national climate change secretariat protocol announcements as inflection signals for biogas substrate valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Concentration Deployment | Electrodialysis reversal installations at São Paulo mills reduce energy intensity versus thermal evaporation, enabling smaller distilleries to enter dehydrated product markets. |
| EU Certification Investment | Spectroscopic testing infrastructure for REACH batch-level documentation secures market access for Brazilian exporters into German and French fertilizer blender networks. |
| Anaerobic Digestion Scale-Up | Methane capture investments qualify for Brazil's national climate change secretariat carbon credit protocols, creating dual-revenue streams from single effluent streams. |
| Protein Recovery Technology Licensing | Yeast biomass extraction partnerships with Indian molasses distilleries capture higher-margin animal feed outlets without concentration technology capital requirements. |
| Cooperative Procurement Consortia Formation | Structured multi-year supply agreements with São Paulo sugarcane growers displace spot markets and transfer price risk to distillery operators. |
Research Methodology
A standing panel of distillery operations managers, sugarcane cooperative procurement directors, fertilizer blender technical buyers, and biogas project developers provided ongoing calibration across the research cycle. Primary interview findings were cross-validated against ANA regulatory filings, EU Fertilizing Products Regulation certification databases, Brazilian customs export records, and RenovaBio capacity registration disclosures. Bottom-up volume estimates from individual distillery operations were reconciled with top-down nutrient recovery market assessments across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled product form segmentation, application channel dynamics, end-user concentration patterns, and regional regulatory cluster effects throughout the forecast period. CAGRs were derived from trajectory fitting to historical capacity expansion rates and policy-mandated biofuel blending targets. Key inputs included membrane technology cost decline curves and synthetic fertilizer price volatility indices.
The analysis sits within stated boundaries; outcomes outside sustained RenovaBio execution, EU contaminant threshold stability, or carbon credit methodology formalization would require recalibration. Forecasts reflect documented assumptions regarding distillery construction timelines and agronomic adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
United States Feed Additives Market