
 Global Organic Feed Additives Market | 2026-2036
Global Organic Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Feed Additives Market Foresight
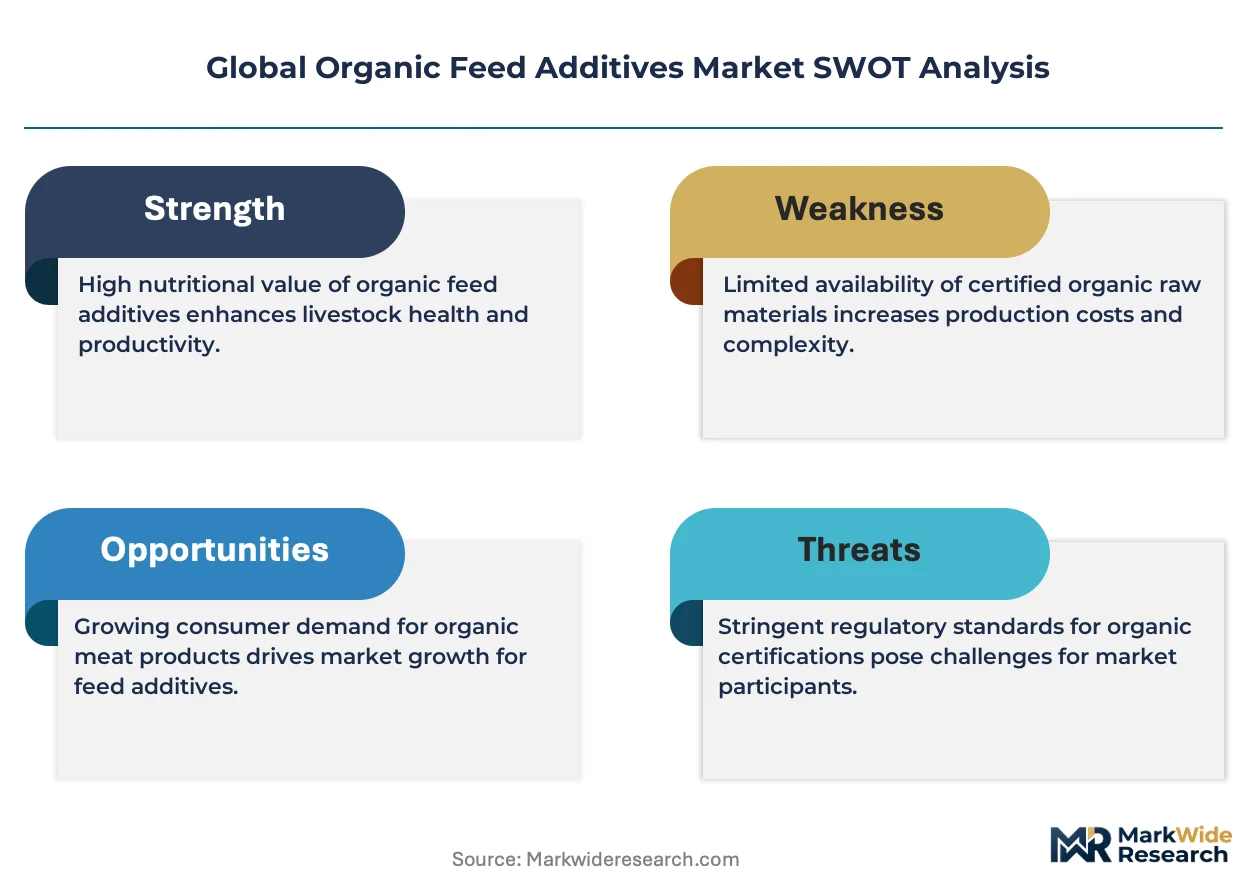
The capital-intensity divergence between integrated multinationals and regional formulators is collapsing as fermentation-based production platforms democratize scale economics. Cargill leverages its captive grain supply chains to backward-integrate into organic acid fermentation, sustaining cost advantages across North American poultry networks. BASF competes through synthetic biology investments in amino acid strains, positioning its Ludwigshafen hub as a technical anchor for European compounders.
Organic feed additives comprise biologically active compounds—vitamins, amino acids, probiotics, and chelated minerals—manufactured through fermentation, extraction, or controlled synthesis without synthetic chemical carriers, formulated to enhance nutrient utilization, gut health, and immune function in livestock. Probiotics command premium positioning due to live-cell stability requirements and cold-chain distribution infrastructure, while amino acids dominate volume throughput as lysine and methionine remain limiting nutrients in plant-based ration formulations. Poultry applications absorb the largest share of probiotic and vitamin tonnage, though aquaculture represents the fastest-expanding application as salmon and shrimp producers phase out antibiotic growth promoters.
The EU Green Deal and REACH frameworks mandate residue testing and restrict synthetic preservative carriers in organic-certified feed, while the USDA National Organic Program governs label claims and input approvals across United States supply chains. These regulatory architectures create dual compliance burdens: formulators must validate absence of prohibited substances and demonstrate live-cell counts or bioavailability metrics. Stakeholders must monitor evolving strain registration pathways and certification reciprocity agreements between jurisdictions to anticipate supply disruptions.
Market Dynamics
Fermentation-based production platforms are collapsing capital barriers that historically separated integrated multinationals from regional formulators, redistributing competitive leverage toward strain-optimization capabilities and captive feedstock access.
Growth Catalysts
- EU Green Deal residue mandates:Tightening limits on synthetic preservative carriers in organic-certified feed are accelerating procurement of plant-derived alternatives across German and Dutch livestock cooperatives.
- Antibiotic growth promoter phase-outs:Salmon and shrimp producers in Norway and Chile are expanding probiotic tonnage to fill performance gaps left by banned pharmaceutical inputs.
- Cold-chain infrastructure expansion:Live-cell stability requirements for probiotic distribution are driving refrigerated logistics investment across Brazil's poultry belt.
Market Restraints
- Organic grain feedstock volatility:Certified corn and soybean price swings compress margin buffers for fermentation-based amino acid producers dependent on non-GMO inputs.
- Strain registration pathway fragmentation:Divergent approval timelines between EFSA, FDA, and China's SAMR delay cross-border product launches by 18-36 months.
- Live-cell count validation costs:Third-party bioavailability testing for probiotic claims adds 12-15% to formulation costs versus synthetic alternatives.
Strategic Opportunities
- Underpenetrated Indonesian aquaculture:Shrimp producers in Sulawesi and Java lack access to certified organic acid blends, creating first-mover positioning for cold-chain-equipped distributors.
- USDA National Organic Program label premium:Certification reciprocity negotiations with EU organic frameworks could unlock dual-market pricing for compliant US formulators.
- CRISPR strain optimization:Convergence of gene-editing and precision fermentation is compressing lysine yield improvement cycles from years to months.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists capable of translating lab strain performance to 100,000-liter bioreactor consistency command 40% salary premiums.
- Dual jurisdiction compliance fatigue:Maintaining parallel EFSA and FDA dossiers for novel probiotic strains drains 20-25% of R&D budgets at mid-cap formulators.
- Legacy mineral premix integration:Chelated organic minerals require reformulation of existing compound feed matrices, forcing technical service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Feed Additives Market |
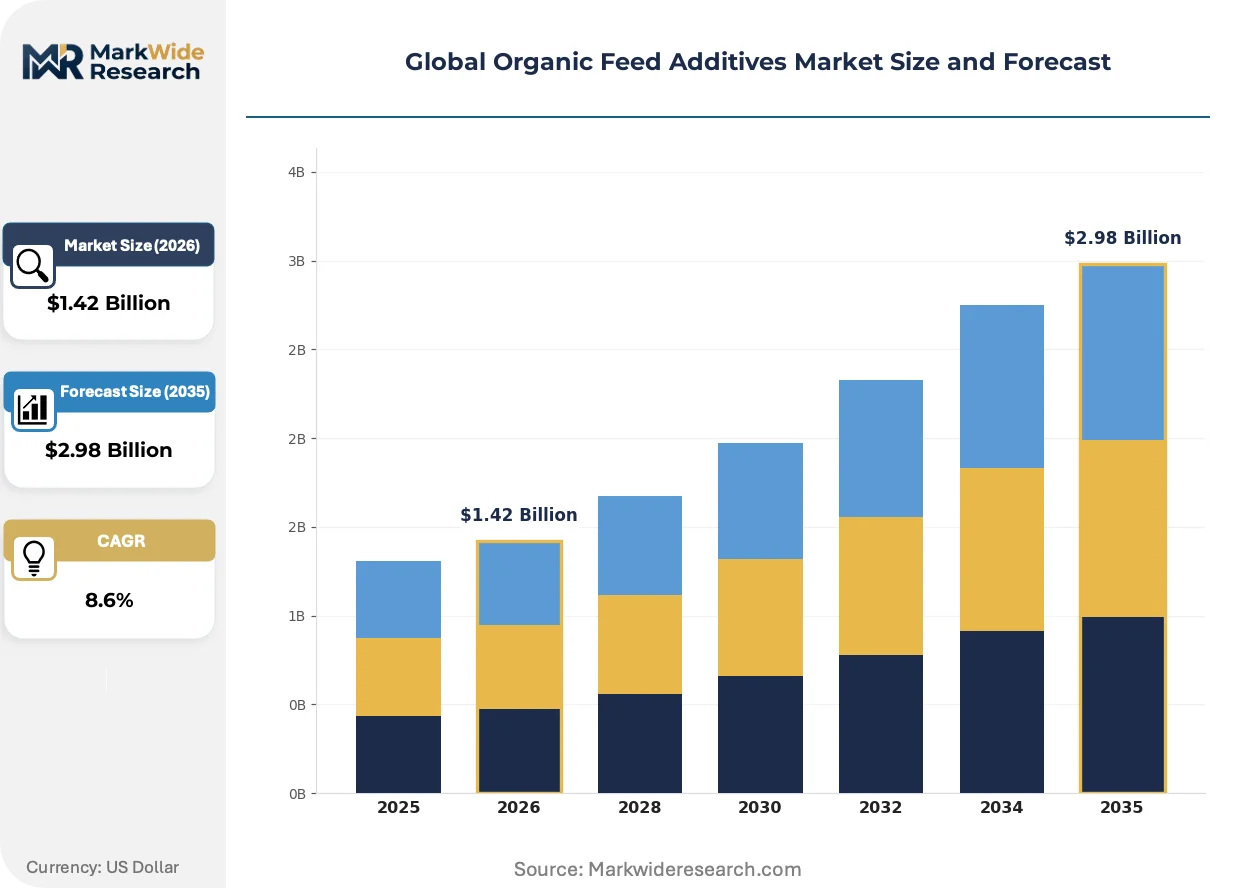
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Probiotics, Minerals Application: Poultry, Ruminants, Swine, Aquaculture Distribution Channel: Online, Retail, Wholesalers, Direct Sales End User: Farmers, Feed Manufacturers, Livestock Owners, Others |
| Companies Covered | Cargill, BASF, ADM, Evonik Industries, Nutreco, Alltech, Kemin Industries, Novus International, Phibro Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Feed Additives Market Shifts & Advancements
Precision fermentation and synthetic biology are resequencing competitive advantage away from chemical synthesis scale toward biological strain performance, while regulatory divergence between jurisdictions forces parallel compliance architectures.
Single-cell protein platforms derived from methanotrophic bacteria are miniaturizing the production footprint for high-value amino acids, enabling distributed manufacturing co-located with livestock operations rather than centralized petrochemical hubs. Poultry integrators in Denmark and the Netherlands are piloting 10,000-liter skid-mounted fermenters for on-site lysine generation. This topology is compressing logistics costs and cold-chain dependency for live-cell additives.
REACH framework amendments restricting synthetic chemical carriers in organic feed are forcing formulators to validate plant-derived excipient alternatives through ECHA's extended safety dossier requirements. The regulatory burden falls heaviest on probiotic blends requiring live-cell stability without petroleum-based encapsulation. German compounders are responding by partnering with regional oleochemical suppliers for lipid-matrix alternatives.
Integrated livestock cooperatives in Bavaria and Lower Saxony now specify additive transparency clauses in procurement contracts, demanding batch-level strain provenance and residue testing documentation. Traditional distributor networks are ceding share to direct manufacturer-cooperative relationships. This pattern is most visible in Germany, where the EU Green Deal implementation timeline has compressed purchasing decision cycles by 30-40%.
Global Organic Feed Additives Market Segmentation
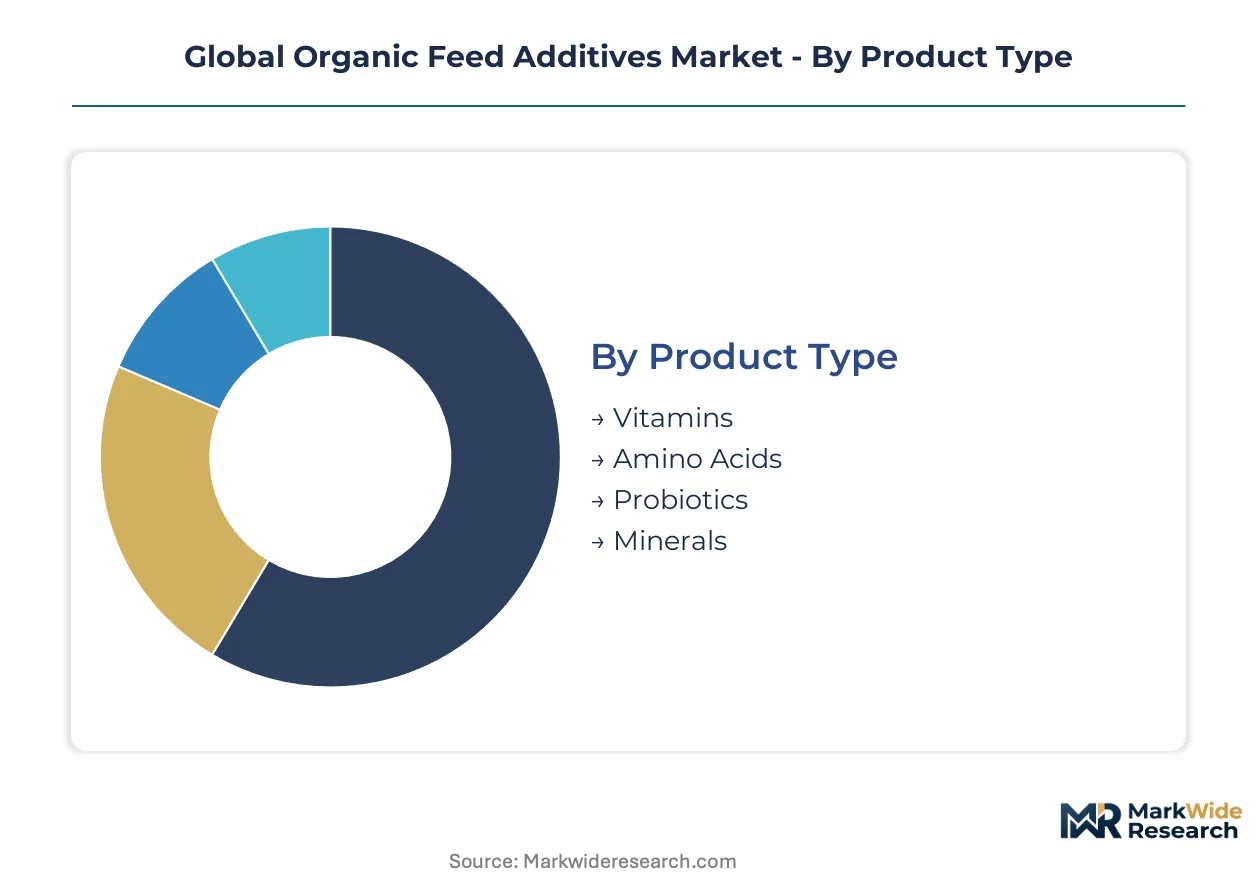
Segmentation in organic feed additives reveals how certification requirements, cold-chain infrastructure, and procurement contract structures reshape channel economics. Each dimension exposes different pressure points for margin capture and compliance burden distribution.
Product Type:
Channel mix varies sharply across product categories: probiotics demand refrigerated logistics partnerships, amino acids move through bulk commodity distributors, vitamins and minerals flow via traditional feed compounder networks.
- Vitamins:Fat-soluble and water-soluble compounds manufactured through fermentation or extraction processes, formulated to correct micronutrient deficiencies in plant-based rations. Demand concentrates in North American poultry integrators where USDA National Organic Program label claims command procurement premiums.
- Amino Acids:Lysine, methionine, threonine, and tryptophan produced via precision fermentation using non-GMO carbohydrate feedstocks. German and Dutch livestock cooperatives specify these in integrated procurement contracts under EU Green Deal residue mandates.
- Probiotics:Live microbial cultures requiring cold-chain distribution and validated cell-count documentation at point of use.
- Minerals:Chelated organic forms replacing inorganic salts to improve bioavailability in ruminant and swine applications.
Amino acids dominate installed base. Probiotics is where expansion concentrates.
Application:
Cost tier stratification separates applications: poultry operations absorb premium pricing for certified blends, aquaculture faces acute cold-chain cost pressure, ruminant and swine segments compete on feed conversion efficiency metrics.
- Poultry:Broiler and layer operations consuming the largest probiotic and vitamin tonnage, with integrators specifying additive transparency clauses in procurement contracts. Bavarian cooperatives now demand batch-level strain provenance documentation.
- Aquaculture:Salmon and shrimp producers in Norway and Chile expanding probiotic tonnage to fill performance gaps left by antibiotic growth promoter phase-outs. Cold-chain infrastructure gaps in Indonesian shrimp farming create distribution bottlenecks.
- Ruminants:Dairy and beef operations emphasizing chelated mineral bioavailability for methane reduction and fertility optimization.
- Swine:Weaner-to-finish systems prioritizing gut health additives to reduce post-weaning growth checks.
Poultry commands the largest revenue pool. Aquaculture is climbing the fastest.
Distribution Channel:
Volume throughput concentrates in wholesaler networks for commodity amino acids, while direct sales capture premium positioning for probiotic strains requiring technical service support.
- Direct Sales:Manufacturer-to-cooperative relationships bypassing traditional distributors, dominant in Germany where integrated livestock operations specify additive transparency clauses. EFSA registration documentation travels through these channels.
- Wholesalers:Bulk amino acid and mineral distribution through regional feed compounder networks, serving mid-scale poultry and swine operations across Brazil's production belt.
- Retail:Small-package vitamin and mineral premixes for independent livestock owners.
- Online:Emerging channel for probiotic products with standardized shelf-stable formulations.
Wholesalers handle the greatest tonnage. Direct sales is gaining share fastest.
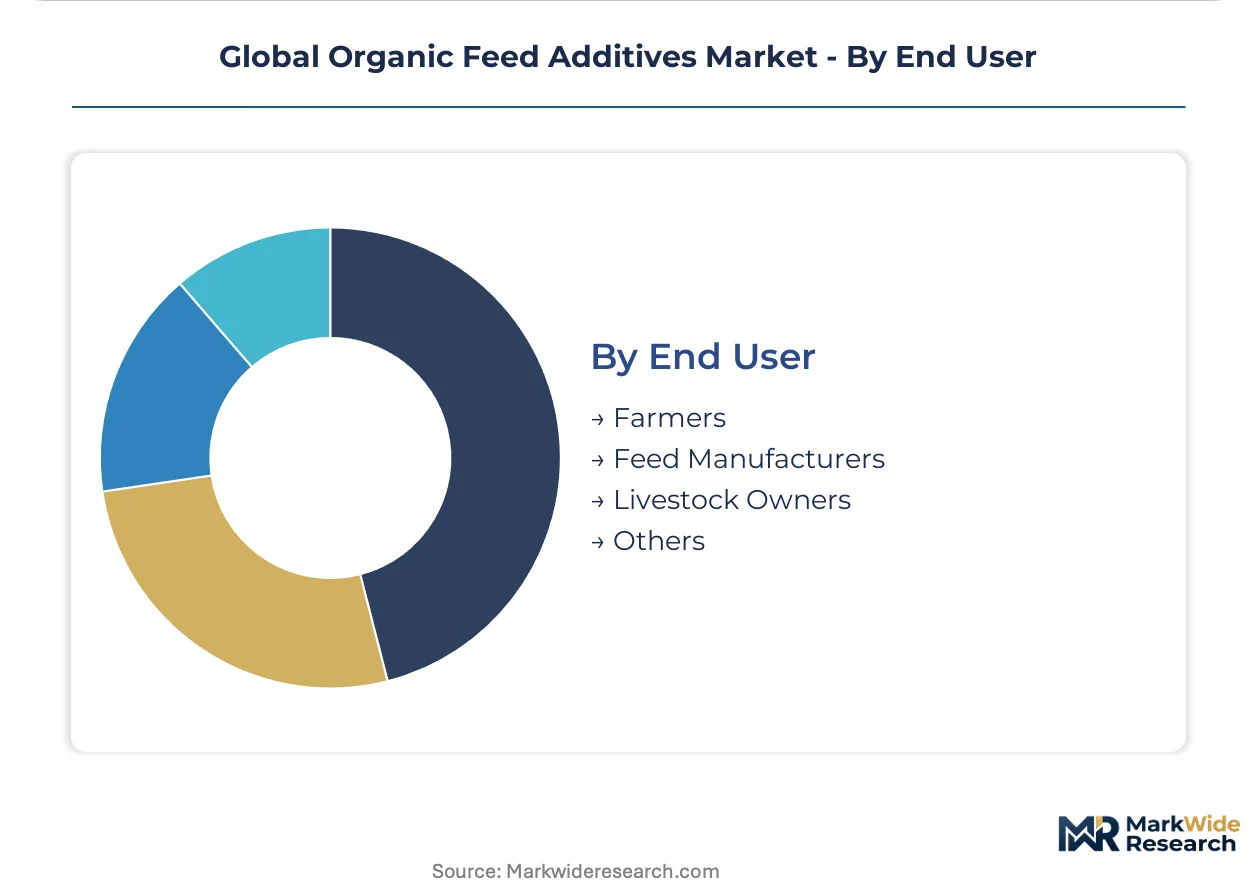
End User:
Customer type determines specification complexity: feed manufacturers require formulation integration support, farmers prioritize cost-per-unit-gain metrics, livestock owners demand certification documentation for premium market access.
- Feed Manufacturers:Compound feed producers integrating organic additives into certified ration matrices, facing dual EFSA and FDA compliance burdens for cross-border strain registration. These customers absorb 20-25% R&D budget drains at mid-cap formulators.
- Farmers:Direct procurement by integrated cooperatives in Denmark and the Netherlands piloting on-site fermentation for lysine generation.
- Livestock Owners:Independent operators sourcing through retail channels for small-scale organic certification compliance.
- Others:Research institutions and veterinary clinics conducting field trials for novel strain validation.
Feed manufacturers anchor procurement volume. Farmers is where channel disruption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German livestock cooperatives where EU Green Deal mandates command additive transparency premiums, while Brazilian poultry integrators absorb cold-chain cost volatility without equivalent contract leverage.
Germany
Bavarian and Lower Saxony cooperatives specify batch-level strain provenance in procurement contracts, compressing purchasing cycles by 30-40% under EU Green Deal implementation timelines. EFSA registration documentation travels through direct manufacturer relationships, bypassing traditional distributor networks. The Ludwigshafen chemical cluster anchors fermentation-based amino acid production for compound feed integration.
United States
USDA National Organic Program label claims drive procurement premiums among North American poultry integrators seeking residue-compliant additive blends. FDA strain registration pathways run parallel to EFSA dossiers, creating dual compliance burdens for cross-border product launches. Midwest grain belt operations leverage captive corn supply chains for organic acid fermentation backward integration.
Brazil
Poultry belt expansion across São Paulo and Paraná states drives refrigerated logistics investment for live-cell probiotic distribution. ANVISA approval timelines lag EFSA and FDA by 18-24 months, delaying novel strain market entry. Regional formulators compete on feed conversion efficiency metrics without equivalent certification premium capture.
Norway
Salmon producers in Bergen and Trondheim regions expand probiotic tonnage to fill performance gaps from antibiotic growth promoter phase-outs. The country's national veterinary regulator enforces residue testing protocols aligned with EU REACH frameworks. Coastal aquaculture clusters pilot cold-chain infrastructure for live-cell stability requirements.
Indonesia
Shrimp farming operations in Sulawesi and Java lack access to certified organic acid blends, creating distribution bottlenecks for cold-chain-equipped entrants. The country's national food and drug regulator maintains divergent approval timelines from EFSA and FDA, complicating cross-border strain registration. Sulawesi production zones represent first-mover positioning opportunities for compliant distributors.
Global Organic Feed Additives Market Competitive Landscape
Concentration sits with integrated multinationals possessing captive grain supply chains and fermentation scale, while regional formulators compete through strain-optimization capabilities and local regulatory dossier expertise. The vendor base stratifies across three tiers: global chemical conglomerates with synthetic biology investments, mid-cap specialists with precision fermentation platforms, and regional compounders serving single-country certification requirements. Dominant competitive moves include backward integration into organic feedstock sourcing and parallel EFSA-FDA registration pathway investment.
Among integrated conglomerates, Cargill exemplifies the grain-supply-chain archetype through North American poultry network penetration, while BASF anchors European technical positioning from its Ludwigshafen hub. ADM occupies a position within the fermentation-platform tier, representing mid-cap scale economics democratization. These three companies illustrate how capital-intensity divergence collapses as biological production platforms redistribute competitive leverage toward strain performance and captive feedstock access.
| Leading Market Players |
|---|
| Cargill |
| BASF |
| ADM |
| Evonik Industries |
| Nutreco |
| Alltech |
| Kemin Industries |
| Novus International |
| Phibro Animal Health |
| Others |
Supply & Pricing Matrix
Plant-derived excipient substitution for petroleum-based encapsulation is redistributing supply geography toward European oleochemical clusters while compressing probiotic formulation margins through ECHA extended safety dossier requirements. German compounders now absorb 12-15% cost premiums for live-cell stability validation, passing selective pricing power to integrated livestock cooperatives with contract leverage.
Pricing Analysis
The customization-premium spread separates standard amino acid commodities from configured-to-order probiotic blends with strain-specific documentation. Three-tier pricing structure across premium certification, standard compliance, and economy feedstock grades anchors contract negotiations, with EU Green Deal residue mandates widening the premium-standard gap. Cost compression in commodity amino acids is intensifying because Brazilian poultry integrators lack equivalent certification leverage. Small-scale livestock owners exhibit highest price sensitivity; Bavarian cooperatives with transparency clauses show lowest.
Supply Chain Analysis
Inventory lead-times for live-cell probiotics extend 3-4 weeks beyond mineral premixes due to cold-chain validation checkpoints. Supply concentrates in Germany, the United States, and Brazil, with fermentation capacity anchored in Ludwigshafen and Midwest grain belts. Raw material flows draw from certified non-GMO corn, soybean meal, and methanol feedstocks. Single-source vulnerability sits with strain-optimization talent pools commanding salary premiums. Distribution runs through direct manufacturer-cooperative channels in Germany, wholesaler networks in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as antibiotic growth promoter phase-outs in aquaculture and EU residue mandates accelerate first-mover positioning for certified organic acid distributors.
For Market Incumbents: Shield fermentation scale advantages through captive grain supply chain control and parallel EFSA-FDA dossier investment. Threat substitution from CRISPR-optimized strains demands accelerated R&D cycles. Priority lever: backward integration into organic feedstock sourcing.
For New Entrants and Emerging Players: Differentiate on cold-chain infrastructure deployment in underpenetrated Indonesian shrimp farming zones. White-space targets include Sulawesi aquaculture clusters and direct sales bypass of traditional distributor networks. Go-to-market angle: technical service partnerships with integrated cooperatives.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platforms with strain-optimization capabilities and regional regulatory dossier expertise. Long-term viability favors mid-cap specialists positioned for certification reciprocity between EU and USDA frameworks. Signal to watch: EFSA-FDA approval timeline convergence as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feedstock | Cargill's captive corn chains sustain cost advantages across North American poultry networks. |
| Parallel EFSA-FDA Registration Investment | Dual dossier capability unlocks cross-border launches and certification reciprocity premiums. |
| Cold-Chain Infrastructure Expansion | Brazilian refrigerated logistics investment addresses live-cell stability requirements in poultry belts. |
| CRISPR Strain Optimization Platform | Gene-editing convergence compresses lysine yield improvement cycles for fermentation economics. |
| Direct Manufacturer-Cooperative Channel | Bavarian transparency clauses bypass traditional distributors and capture procurement cycle compression. |
Research Methodology
A standing panel of fermentation plant managers, livestock cooperative procurement leads, feed compounder technical directors, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA strain registration databases, USDA National Organic Program input approvals, EU REACH amendment filings, and customs trade flows. Bottom-up volume modeling triangulated against top-down market sizing from disclosed capacity expansions.
Consistency checks validated projections against external benchmarks including livestock production forecasts and organic certification growth trajectories. The analytical framework segmented across product type, application, distribution channel, and end user throughout the forecast period. CAGRs derived from regression analysis of historical price-volume relationships and adoption curve penetration rates. Industry-specific inputs included cold-chain infrastructure buildout schedules and strain registration pathway timelines.
Forecasts assume regulatory continuity in EU Green Deal implementation and USDA National Organic Program standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Alpha-Amylase Baking Enzyme Market
Food Additives and Ingredients
United States Feed Additives Market