
 Robotic Biopsy Devices Market | 2026-2036
Robotic Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Biopsy Devices Market Outlook
CE marking under the EU Medical Device Regulation is collapsing the qualification cycle for new entrants, forcing smaller developers to seek notified-body partnerships before commercialization. Intuitive Surgical leverages its installed base of da Vinci systems to cross-sell biopsy-compatible instruments across existing hospital networks. Medtronic anchors its position through backward integration into surgical navigation software that feeds real-time imaging data to robotic biopsy consoles.
Robotic biopsy devices integrate precision electromechanical actuators, stereotactic guidance algorithms, and disposable needle cartridges to extract tissue samples with sub-millimeter accuracy under continuous imaging feedback. The robotic arm segment dominates capital expenditure budgets due to its mechanical complexity and service contract attach rates, while artificial intelligence technology is capturing the fastest growth as machine learning models reduce procedure time and variability in needle placement. Imaging systems sustain premium pricing through proprietary fluoroscopy and MRI compatibility protocols that lock hospitals into single-vendor ecosystems.
FDA 510(k) clearance requirements and the EU MDR conformity assessment process shape product development roadmaps by mandating clinical validation studies for each new indication. Siemens Healthineers navigates this framework by pre-certifying imaging-to-robot interfaces under joint regulatory submissions in both jurisdictions. Stakeholders must monitor how FDA draft guidance on autonomous surgical actions will redefine the boundary between physician-directed and robot-initiated tissue sampling.
Market Dynamics
Robotic biopsy device manufacturers face intensifying pressure from the EU Medical Device Regulation's compressed conformity timelines, which forces developers to front-load clinical validation spending before CE marking eligibility. This structural shift privileges established players with dedicated regulatory affairs teams while squeezing mid-tier competitors.
Growth Catalysts
- FDA 510(k) pathway compression:Streamlined clearance for predicate-based submissions accelerates time-to-revenue for Class II surgical robots targeting tissue extraction.
- Interventional radiology suite expansion:Hospital systems in Germany and Japan are dedicating capital budgets to integrated imaging-robotic biopsy installations.
- Machine learning needle placement:AI-driven trajectory algorithms reduce physician variability and procedure duration, driving platform adoption across academic medical centers.
Market Restraints
- High-precision actuator supply concentration:Electromechanical component sourcing clusters in Japanese and German precision manufacturing zones, creating single-source vulnerability.
- EU MDR notified body bottleneck:Collapsed qualification cycles delay market entry for developers lacking pre-existing notified-body partnerships.
- Fluoroscopy-compatible disposable cartridge costs:Proprietary needle systems lock hospitals into recurring consumable expenditures that strain capital-constrained budgets.
Strategic Opportunities
- Outpatient ambulatory surgical centers:Underpenetrated ASC channels in the United States present volume expansion potential for compact, cart-based robotic biopsy systems.
- Real-time MRI guidance convergence:Integration of closed-bore MRI compatibility with robotic actuation opens neurosurgical and prostate applications previously excluded from robotic access.
- Japan's METI medical robotics subsidies:National funding programs for surgical automation reduce customer acquisition costs for platform vendors targeting Japanese hospital networks.
Industry Challenges
- Cross-functional talent scarcity:Recruitment of engineers fluent in both electromechanical systems and sterile surgical instrument design lags platform development timelines.
- Legacy PACS integration complexity:Hospital IT departments struggle to bridge proprietary imaging-to-robot data protocols with existing radiology archive infrastructure.
- ISO 13485 quality system maintenance:Sustained certification costs burden smaller developers competing against scaled manufacturers with captive audit resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Biopsy Devices Market |
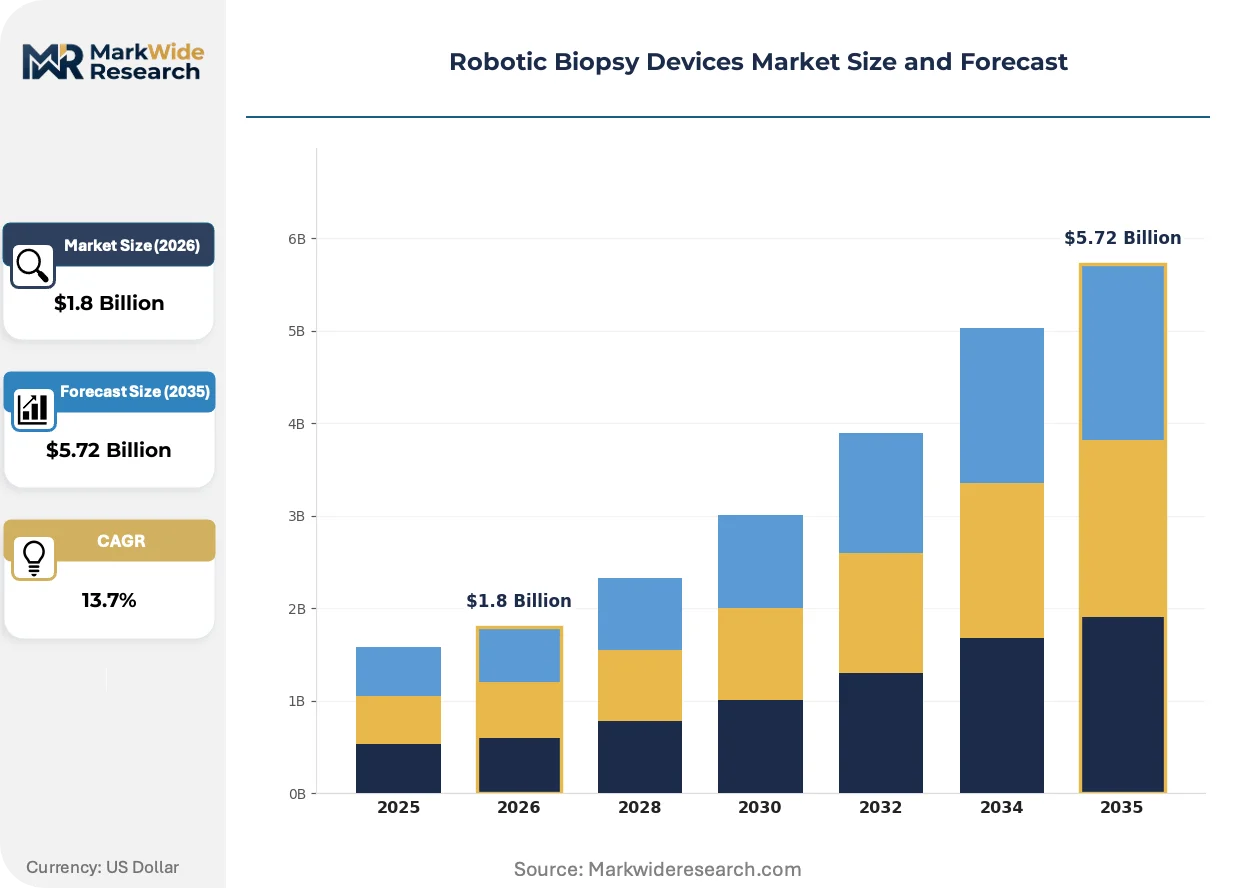
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arm, Biopsy Needle, Imaging System, Control Console End User: Hospitals, Diagnostic Centers, Research Laboratories, Pain Management Clinics Technology: Electro-Mechanical, Laser-Based, Electromagnetic, Artificial Intelligence Application: Oncology, Neurology, Dermatology, Cardiovascular |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, Intuitive Surgical, XACT Robotics, Biobot Surgical, Renishaw plc, Siemens Healthineers, Medical Device Business Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Biopsy Devices Market Strategic Shifts
Artificial intelligence is actively fragmenting how robotic biopsy platforms differentiate on precision and speed, compressing the performance gap between premium and mid-tier systems. This technological dispersion is rewriting vendor competitive positioning across installed base expansion strategies.
Deep learning trajectory algorithms now process intraoperative imaging feedback to adjust needle angulation in sub-second intervals. Academic medical centers in the United States and Germany are piloting these systems for lung and renal biopsies where respiratory motion complicates manual targeting. The technology is fragmenting the historical correlation between hardware actuator precision and clinical outcomes, enabling software-centric vendors to challenge established mechanical engineering leaders.
CE marking under the EU MDR is collapsing development roadmaps by mandating clinical evidence generation for each new indication rather than predicate-based equivalence. Device developers must now commit to prospective trials before market authorization, reshaping R&D budget allocation toward regulatory affairs. European interventional radiology suites are responding by consolidating procurement around vendors with pre-certified imaging-robot interfaces, accelerating single-vendor ecosystem lock-in.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing robotic biopsy vendors to price maintenance and software updates separately. This behavioral shift is most visible in United States health systems where value analysis committees scrutinize total cost of ownership over five-year horizons. Vendors must now defend recurring revenue streams through demonstrated uptime guarantees rather than bundled service attach rates.
Robotic Biopsy Devices Market Segmentation
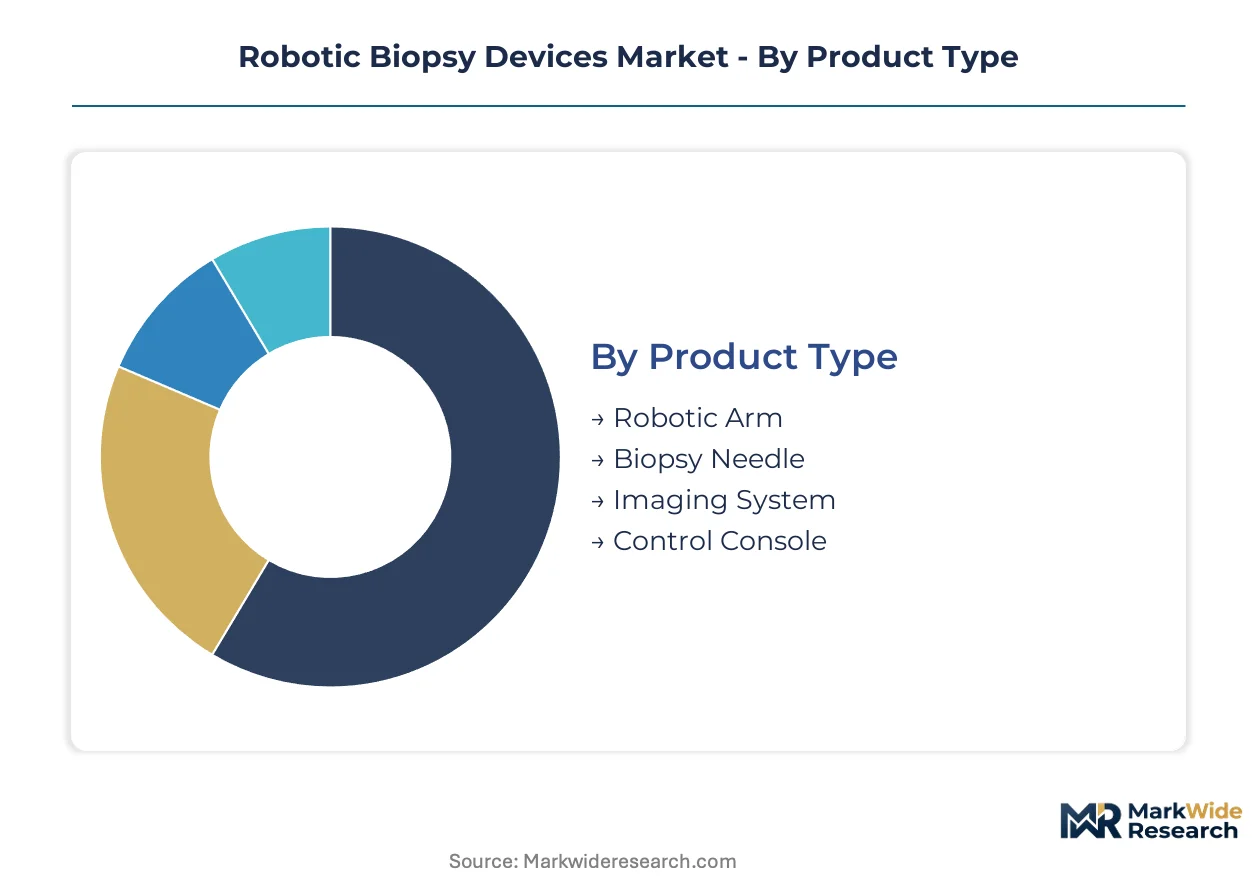
Segmentation in robotic biopsy devices reveals how capital equipment, consumables, and software layers interact across divergent procurement cycles. Hospital buyers prioritize integrated platforms while outpatient settings favor modular, cost-contained configurations.
Product Type:
Robotic arms and control consoles concentrate manufacturing in German and Japanese precision engineering clusters, while biopsy needles and imaging systems flow through broader global supply networks.
- Robotic Arm:Multi-axis electromechanical assemblies with sub-millimeter positioning accuracy anchor capital expenditure budgets. Demand clusters in United States academic medical centers and German university hospitals where interventional radiology suites require continuous imaging feedback compatibility.
- Biopsy Needle:Disposable, fluoroscopy-compatible cartridges with proprietary connection interfaces lock hospitals into recurring consumable streams. Procurement concentrates in high-volume United States health systems where procedure throughput justifies per-unit premium pricing.
- Imaging System:MRI and CT-compatible guidance platforms with vendor-locked protocols.
- Control Console:Surgeon interface units integrating navigation software and haptic feedback.
Robotic arm systems hold the largest share; momentum sits with biopsy needle consumables as recurring revenue models displace pure capital sales.
End User:
Procurement authority varies sharply across settings, with United States hospitals consolidating vendor relationships while Japanese diagnostic centers pursue METI-subsidized automation pilots.
- Hospitals:Integrated health systems with dedicated interventional radiology suites and value analysis committees scrutinizing five-year total cost of ownership. United States hospital networks dominate installed base expansion as they retrofit existing surgical robotics infrastructure.
- Diagnostic Centers:High-throughput outpatient facilities prioritizing compact, cart-based systems with rapid room turnover. German radiology chains and Japanese imaging centers lead procurement as regulatory pathways compress for predicate-based submissions.
- Research Laboratories:Academic and pharmaceutical sites requiring customizable trajectory algorithms.
- Pain Management Clinics:Smaller-scale settings seeking entry-level electromechanical systems.
Hospitals command the dominant procurement volume; diagnostic centers are expanding most quickly as ambulatory surgical center channels mature.
Technology:
Cost tiers separate established electromechanical platforms from emerging AI-augmented systems, with laser and electromagnetic technologies occupying mid-market positioning.
- Artificial Intelligence:Deep learning trajectory algorithms processing intraoperative imaging feedback to adjust needle angulation in sub-second intervals. Academic medical centers in Germany and the United States pilot these systems for lung and renal applications where respiratory motion complicates manual targeting.
- Electro-Mechanical:Precision servo motor and encoder assemblies with established ISO 13485 quality systems. Japanese and German manufacturers anchor supply through captive precision manufacturing capabilities.
- Laser-Based:Optical guidance systems for superficial tissue applications.
- Electromagnetic:Sensor arrays for real-time needle tracking without line-of-sight constraints.
Electro-mechanical platforms retain the largest installed base; artificial intelligence is gaining share fastest as software-centric vendors challenge hardware incumbents.
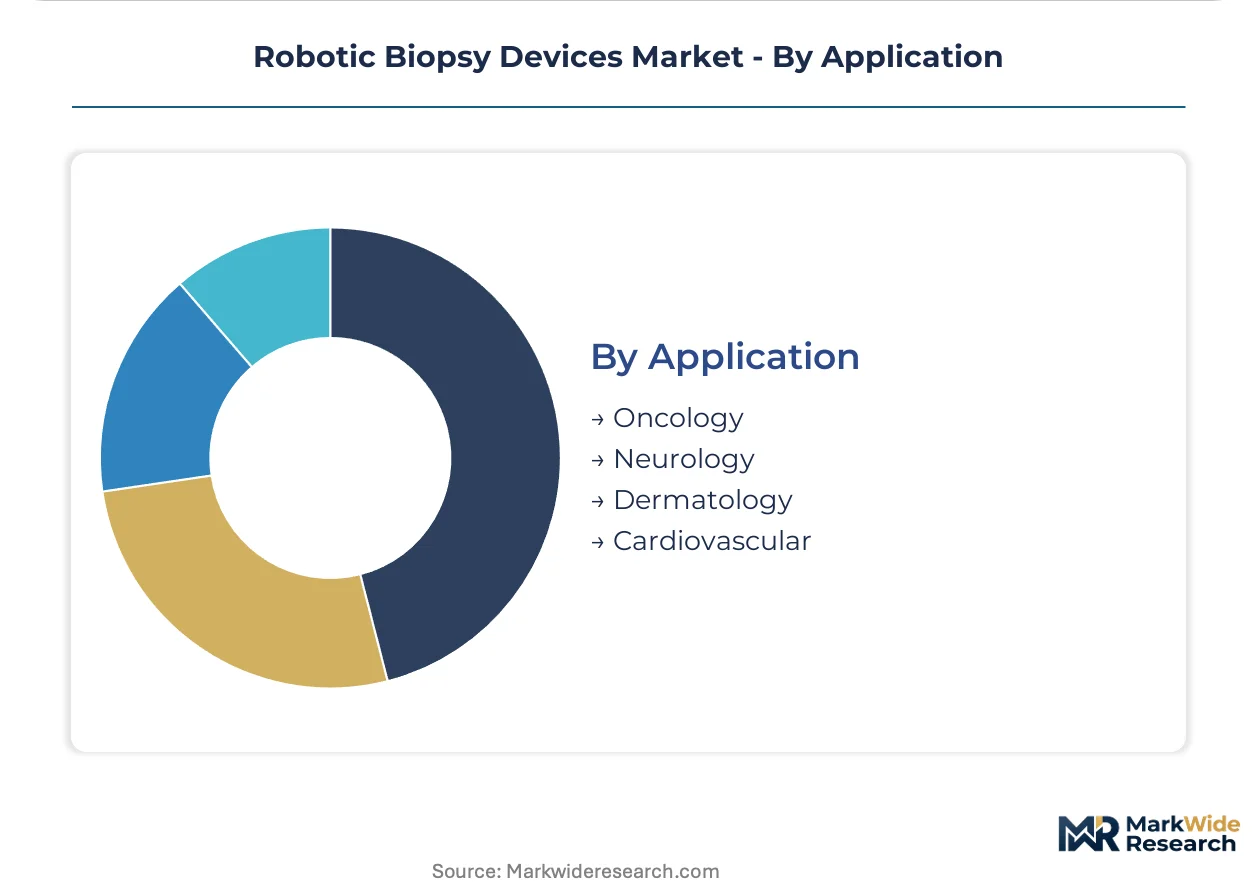
Application:
Procedure complexity and reimbursement levels create divergent technology requirements across therapeutic areas, with oncology commanding premium platform configurations.
- Oncology:Multi-site tissue extraction protocols requiring MRI compatibility and stereotactic guidance for deep lesions. United States cancer centers and German oncology networks drive demand as screening programs expand eligible patient populations.
- Neurology:Closed-bore MRI-compatible robotic actuation for brain and spinal biopsies. Japanese neurosurgical centers and United States academic medical centers pursue regulatory clearance for real-time imaging convergence.
- Dermatology:Superficial lesion targeting with simplified mechanical requirements.
- Cardiovascular:Specialized catheter-based access for myocardial tissue sampling.
Oncology applications dominate revenue concentration; neurology shows the steepest expansion trajectory as MRI guidance protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs are redirecting procurement flows across major hospital networks. National funding schemes for surgical automation compress customer acquisition timelines in targeted jurisdictions. Regulatory pathway variations between FDA 510(k) and EU MDR create divergent market entry sequences for device developers.
United States
Academic medical centers in Boston and Houston retrofit existing da Vinci infrastructure with biopsy-compatible instruments. FDA 510(k) pathway compression accelerates predicate-based submissions for Class II surgical robots. The Mayo Clinic and Cleveland Clinic anchor demand concentration through dedicated interventional radiology suite expansion.
Germany
University hospitals in Munich and Heidelberg dedicate capital budgets to integrated imaging-robotic biopsy installations. EU MDR conformity assessment mandates clinical validation studies before CE marking eligibility. The Baden-Württemberg precision engineering cluster supplies electromechanical actuators to domestic and export markets.
Japan
Tokyo and Osaka neurosurgical centers pursue regulatory clearance for real-time MRI guidance convergence. METI medical robotics subsidies reduce customer acquisition costs for platform vendors targeting hospital networks. The Nagoya precision manufacturing zone anchors actuator sourcing for regional device assembly.
United Kingdom
NHS trusts in London and Manchester consolidate procurement around vendors with pre-certified imaging-robot interfaces. MHRA recognition of EU MDR certificates streamlines market access for CE-marked devices. The Oxford-Cambridge life sciences corridor hosts pilot programs for AI-driven needle placement algorithms.
China
Shanghai and Beijing tertiary hospitals expand interventional radiology capacity under national cancer screening program mandates. NMPA innovation pathway designations compress review timelines for domestically developed surgical robots. The Yangtze River Delta medical device manufacturing base scales production of cart-based biopsy systems for domestic consumption.
Robotic Biopsy Devices Market Competitive Environment
Player mix skews toward diversified surgical robotics conglomerates with installed base leverage. Market structure concentrates around three to five integrated platform vendors commanding hospital network relationships. Strategic archetypes include imaging-to-robot ecosystem builders, precision electromechanical specialists, and AI-augmented software-centric challengers. Dominant competitive moves encompass backward integration into surgical navigation software and cross-selling biopsy-compatible instruments across existing robotic surgery infrastructure.
Within the diversified surgical robotics tier, Intuitive Surgical and Medtronic exemplify platform vendors with installed base expansion strategies. XACT Robotics occupies a position among the AI-augmented challenger set. Siemens Healthineers anchors the imaging-to-robot ecosystem builder archetype through pre-certified interface submissions. Stryker and Zimmer Biomet sit within the orthopedic-to-interventional crossover segment seeking biopsy market entry.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| Intuitive Surgical |
| XACT Robotics |
| Biobot Surgical |
| Renishaw plc |
| Siemens Healthineers |
| Medical Device Business Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japanese and German precision actuator foundries sits above 85 percent, compressing availability for mid-tier device developers and elevating price floors for electromechanical assemblies. This scale concentration permits incumbent vendors to extract premium positioning through captive manufacturing, while forcing smaller competitors toward modular, software-centric architectures that reduce hardware dependency.
Pricing Analysis
Certification level (ISO 13485, FDA 510(k), CE MDR-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and imaging-protocol compatibility. Cost compression in the standard tier is intensifying because hospital procurement committees unbundle maintenance contracts and demand five-year total cost of ownership transparency. Diagnostic centers exhibit the highest price sensitivity due to capital-constrained budgets and rapid room turnover requirements, while academic medical centers in the United States and Germany prioritize performance metrics over unit cost.
Supply Chain Analysis
Inventory lead times for sub-millimeter precision servo motors and optical encoders now stretch 16-20 weeks, constraining platform assembly schedules. Electromechanical component sourcing clusters in Japan, Germany, and the United States, with the Nagoya and Baden-Württemberg precision engineering zones anchoring regional supply. Raw material dependencies include rare-earth magnets for motor assemblies, fluoroscopy-compatible polymers for needle cartridges, and high-purity aluminum for robotic arm housings. Single-source vulnerability concentrates in Japanese actuator suppliers serving multiple device OEMs. Distribution runs through hospital GPO contracts and direct vendor relationships with interventional radiology suite directors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of engineers fluent in both electromechanical systems and sterile surgical instrument design constrains platform development timelines across the competitive landscape. This talent gap privileges incumbents with established recruitment pipelines while elevating acquisition premiums for specialized development teams.
For Market Incumbents:Fortify regulatory affairs capabilities through dedicated notified-body partnerships before EU MDR conformity assessment windows collapse further. Deepen backward integration into surgical navigation software to lock imaging-to-robot data protocols and preempt channel unbundling by hospital value analysis committees. The threat of AI-augmented software-centric challengers fragmenting the correlation between hardware precision and clinical outcomes demands preemptive software companion development.
For New Entrants and Emerging Players:Differentiate on real-time MRI guidance convergence for neurosurgical and prostate applications excluded from established robotic access. Target outpatient ambulatory surgical centers in the United States with compact, cart-based systems that reduce capital expenditure thresholds and accelerate room turnover. METI-subsidized Japanese hospital networks present the most penetrable geography for first commercial traction. A software-first go-to-market angle leveraging deep learning trajectory algorithms bypasses the electromechanical talent scarcity constraining hardware-centric competitors.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors AI-augmented challengers with regulatory-cleared algorithms over pure hardware plays facing component supply bottlenecks. Long-term viability across the projection horizon rests on demonstrated hospital system partnerships and imaging-protocol lock-in rather than patent portfolios alone. Acquisition target archetypes include software-centric vendors with FDA-cleared needle placement algorithms and established interventional radiology suite pilot programs. The signal to monitor is FDA draft guidance on autonomous surgical actions, which would redefine valuation premiums between physician-directed and robot-initiated tissue sampling platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR pre-certification compresses market entry timelines for imaging-robot interfaces. |
| Hospital System Partnership | United States academic medical center alliances anchor installed base expansion through interventional radiology suite retrofit programs. |
| Software Companion Development | Deep learning trajectory algorithms reduce procedure variability and challenge hardware-centric competitive positioning. |
| Backward Integration into Navigation | In-house surgical navigation software production locks proprietary imaging-to-robot data protocols. |
| Reimbursement Strategy | CPT code alignment for robotic-assisted biopsy procedures determines hospital capital budget justification. |
Study Parameters
A spread of perspectives from interventional radiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR notified-body certification records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down capital expenditure triangulation anchored value estimates.
Segmentation dimensions modeled span product type (robotic arm, biopsy needle, imaging system, control console), end user (hospitals, diagnostic centers, research laboratories), technology (artificial intelligence, electro-mechanical, laser-based, electromagnetic), and application (oncology, neurology, dermatology, cardiovascular). CAGRs derived from procedure growth rates, replacement cycles, and technology substitution curves. Forecast inputs include METI subsidy allocation trajectories and EU MDR notified-body capacity constraints.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR regimes; material policy shifts would require re-modeling. Technology disruption from fully autonomous tissue sampling algorithms and supply chain shocks from precision actuator export restrictions represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravenous Stopcock Market
Medical Devices
Skincare Devices Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
IV Poles Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Tissue Expanders Market
Medical Devices
Supraglottic Device Market
Medical Devices
Otoscope Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
Electrophysiology Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Light Therapy Beauty Devices Market