
 Pipeline Strainers Market | 2026-2036
Pipeline Strainers Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Strainers Market Intelligence
Market Dynamics and Competitive Landscape
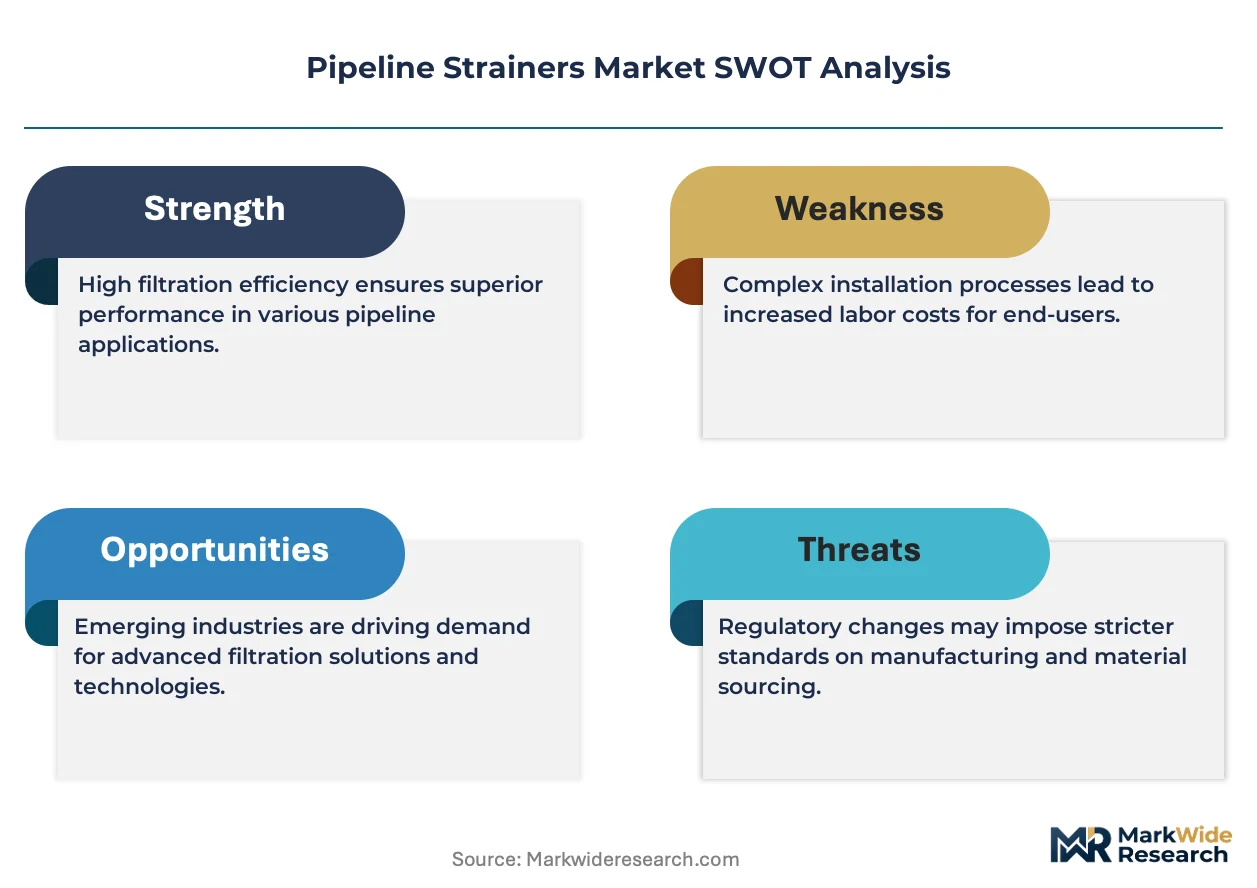
Skilled welder availability for custom stainless steel strainer fabrication is collapsing across Midwestern US manufacturing hubs, forcing producers to automate orbital welding lines or relocate production. Parker Hannifin Corporation leverages its vertically integrated filtration division to sustain captive supply of pleated filter elements that pair with its strainer housings. Eaton Filtration anchors North American municipal contracts through extensive distributor networks stocking ANSI-certified basket strainer configurations. CIRCOR Energy competes in offshore oil and gas with API-compliant duplex strainers rated for high-pressure subsea manifolds.
Product Architecture and Segment Structure
Pipeline strainers are mechanical filtration devices installed in piping systems to remove particulate matter from flowing liquids, typically constructed with perforated or mesh-lined baskets rated from 20 mesh to 400 mesh and pressure ratings spanning 150 psi to 600 psi class. Their primary purpose is protecting downstream pumps, valves, meters, and process equipment from debris-induced damage and unplanned shutdowns. Y-Strainers dominate compact installation budgets across HVAC and light industrial segments due to lower material cost and straight-through flow geometry. Basket Strainers capture margin pools in chemical processing where large debris volumes and frequent cleanout cycles justify higher upfront capital. Stainless Steel material grades, particularly 316L with molybdenum enhancement, lead specification sheets in corrosive media applications despite carbon steel maintaining volume leadership in standard water service.
Regulatory Environment and Strategic Outlook
EPA Safe Drinking Water Act amendments and FDA 21 CFR Part 177 indirect food contact regulations shape product certification requirements for potable and food-grade strainer installations across US territories. ASME B31.3 process piping codes and API 674 positive displacement pump standards mandate minimum strainer mesh specifications that directly determine procurement decisions in hydrocarbon processing. Stakeholders must monitor evolving PFAS filtration mandates at state level, as emerging MCLs could trigger retrofit demand for finer-mesh automatic strainer systems in industrial wastewater discharge points.
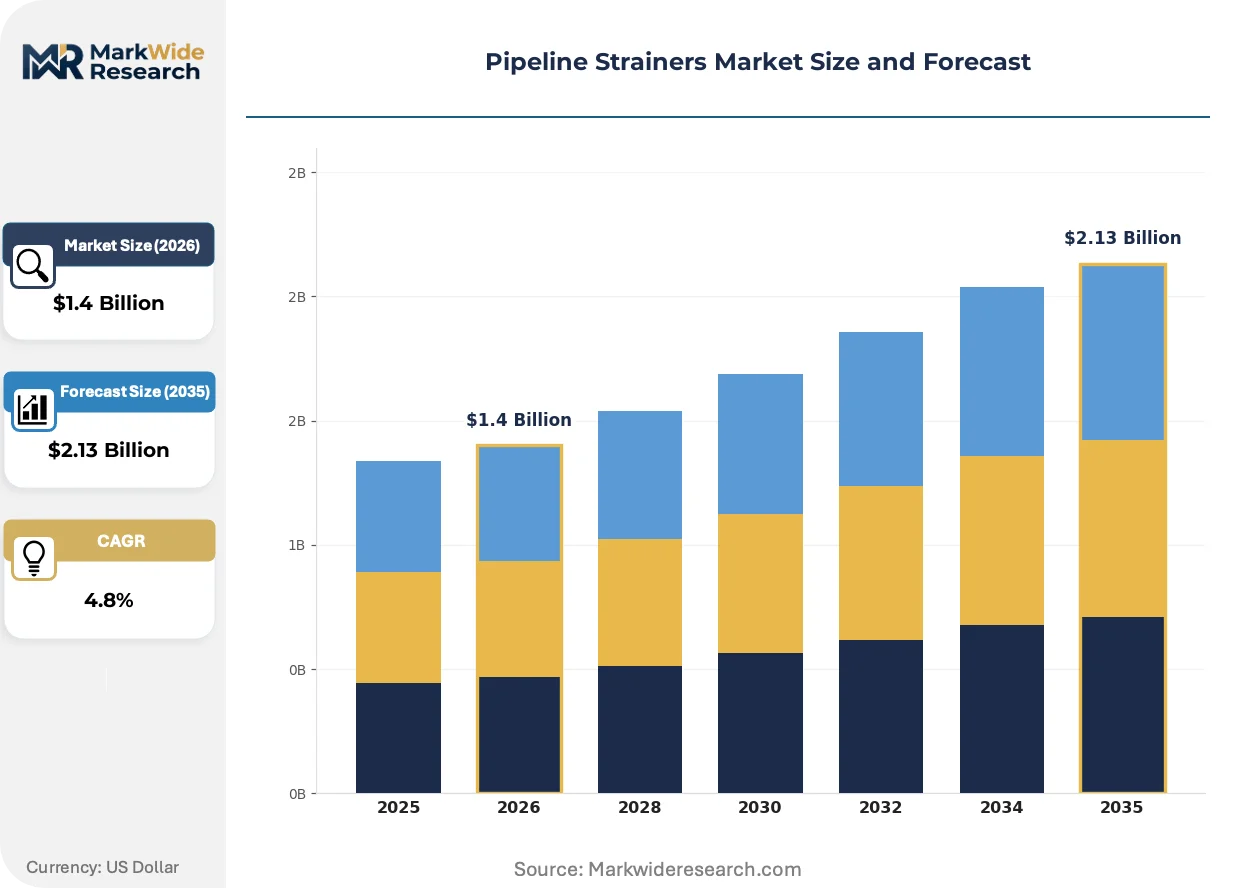
Market Dynamics
Automatic backwashing strainer technology is compressing maintenance labor requirements across municipal water utilities, forcing incumbent fabricators to retool production lines for electromechanical actuation systems or cede share to specialized automation suppliers.
Growth Catalysts
- EPA Clean Water Act compliance deadlines:Aging North American distribution infrastructure faces mandated upgrade timelines, triggering replacement cycles for legacy basket strainer installations with higher-capacity automatic systems.
- Ethylene cracker investments:The Texas Gulf Coast petrochemical corridor requires duplex strainer arrays rated for high-temperature hydrocarbon service, concentrating procurement volume in a single industrial cluster.
- 316L stainless steel specification:Corrosive media applications in chemical processing are elevating molybdenum-enhanced grades above carbon steel, expanding addressable margin pools for premium fabrication.
Market Restraints
- Skilled welder scarcity:Midwestern US manufacturing hubs face collapsing availability of certified orbital welders for custom stainless strainer fabrication, forcing automation capital outlays or geographic relocation.
- API 674 pump standard mesh mandates:Minimum strainer specifications for positive displacement pumps in hydrocarbon processing lock procurement decisions to certified configurations, limiting supplier flexibility.
- Carbon steel price volatility:Standard water service strainers remain exposed to ferrous input cost swings, compressing margins on high-volume, low-specification contracts.
Strategic Opportunities
- PFAS filtration mandates:Emerging state-level maximum contaminant levels for industrial wastewater discharge could trigger retrofit demand for finer-mesh automatic strainer systems at discharge points.
- Subsea manifold applications:Offshore oil and gas operators require API-compliant duplex strainers rated for high-pressure subsea environments, a specification niche with limited qualified suppliers.
- ANSI-certified distributor networks:Municipal procurement channels favor stocked basket strainer configurations with rapid fulfillment, rewarding distributors with regional inventory positioning.
Industry Challenges
- ASME B31.3 code certification timelines:Process piping compliance documentation for custom strainer fabrications extends delivery schedules, creating competitive friction against standardized catalog offerings.
- FDA 21 CFR Part 177 food-grade validation:Indirect food contact strainer installations require material traceability and surface finish documentation that strains quality systems at mid-tier fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Strainers Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Y-Strainers, Basket Strainers, Duplex Strainers, Automatic Strainers Material: Stainless Steel, Plastic, Carbon Steel, Bronze End User: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage Installation Type: Inline, Modular, Compact, Custom-Built |
| Companies Covered | Krone Filtertechnik, Keckley Company, Parker Hannifin Corporation, CIRCOR Energy, Hayward Flow Control, Eaton Filtration, Armstrong International, Metso Corporation, Watts Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Strainers Market Strategic Shifts & Innovations
Electromechanical actuation and sensor integration are transforming strainer architecture from passive mechanical devices to intelligent filtration nodes capable of predictive maintenance signaling and autonomous backwash triggering.
Smart differential pressure monitoring is decomposing the traditional scheduled maintenance model for basket strainers. Municipal water utilities in the Great Lakes region are deploying networked pressure transducers that trigger automated clean cycles only when fouling thresholds breach setpoints. This capability is compressing labor dispatch frequency and enabling remote asset management across distributed treatment networks.
REACH substance restrictions on chromium VI surface treatments are forcing European fabricators to migrate from traditional passivation chemistries to citric acid or nitric-free alternatives. The industrial consequence extends lead times for export-certified strainers destined for EU potable water installations. German chemical processors are responding by consolidating procurement with suppliers holding dual ASME and PED certification to ensure regulatory continuity.
Buyer preference is migrating from capital purchase toward performance-guaranteed service agreements. Large industrial operators in the Alberta oil sands are unbundling strainer supply from aftermarket maintenance, contracting filtration uptime rather than equipment ownership. Channel intermediaries with field service capabilities are capturing margin previously held by manufacturers, particularly in remote site applications where technical labor availability constrains owner-operated maintenance.
Pipeline Strainers Market Segmentation
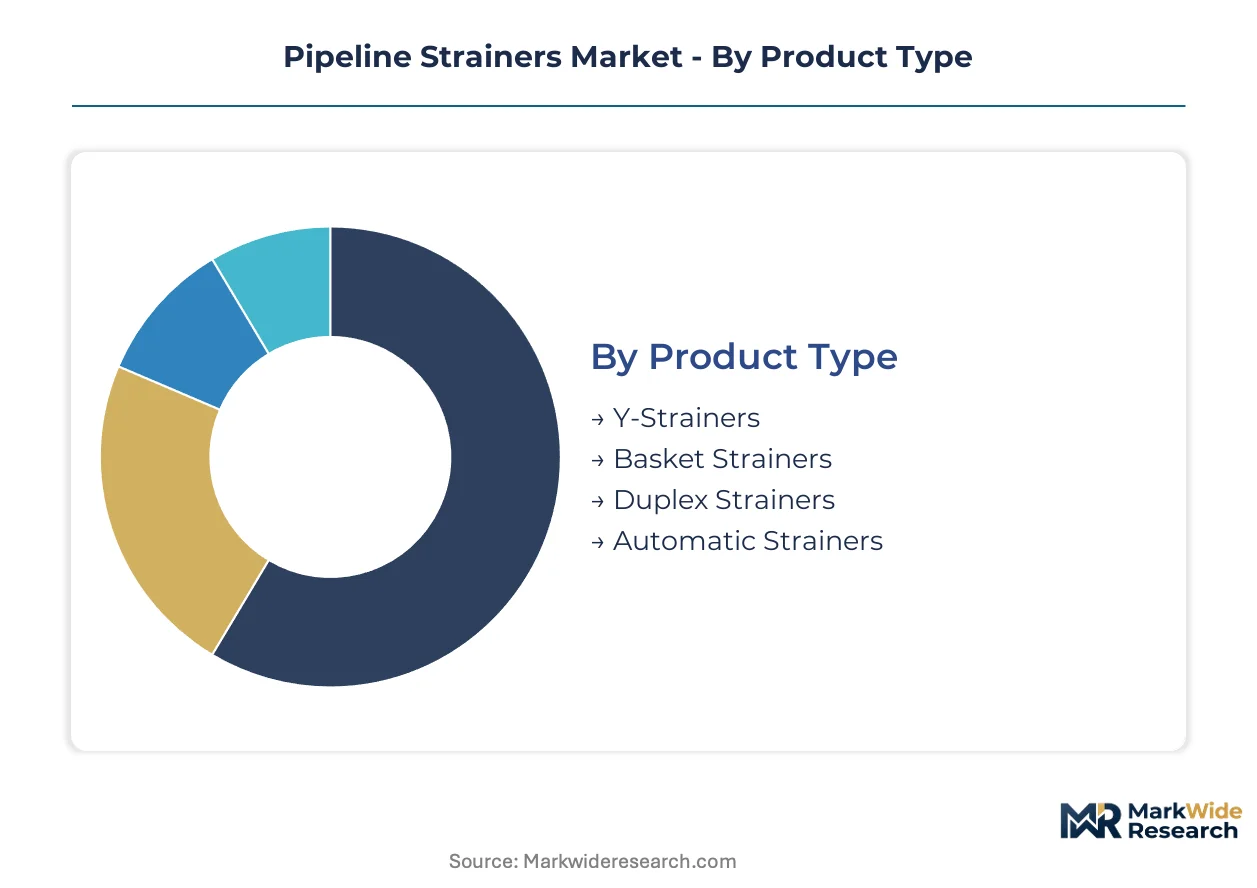
Product differentiation in pipeline strainers maps directly to lifecycle cost tradeoffs between upfront capital and maintenance labor. Specification decisions cascade from end-use severity, with corrosive media and continuous-duty applications demanding premium material grades and automated cleaning architectures.
Product Type:
Margin pools concentrate in duplex and automatic configurations where engineering complexity creates supplier stickiness and aftermarket service attachment.
- Y-Strainers:Compact cast or fabricated housings with cylindrical screens suited for low-debris, intermittent-service lines. HVAC contractors across Texas and Florida specify these for chilled water loops where first-cost sensitivity dominates and manual blowdown suffices.
- Basket Strainers:Larger-volume housings with removable perforated baskets enable rapid cleanout without line shutdown. Chemical processors on the Texas Gulf Coast deploy these for batch operations with scheduled maintenance windows, though duplex alternatives are displacing them in continuous-process lines.
- Duplex Strainers:Dual-chamber design permits isolated basket switching without flow interruption, commanding premium pricing in hydrocarbon service.
- Automatic Strainers:Electromechanical backwash systems eliminate manual intervention entirely, capturing municipal water treatment procurement as EPA compliance deadlines compress maintenance staffing.
Basket strainers hold installed capacity across legacy industrial infrastructure. Automatic strainers are rotating up the share rankings as labor scarcity forces automation adoption.
Material:
Specification grade determines fabrication cost structure and corrosion resistance, with molybdenum-enhanced alloys capturing margin in aggressive chemical environments.
- Stainless Steel:316L grade with molybdenum enhancement dominates corrosive media applications in chemical processing and offshore oil and gas, where chloride-induced pitting risks disqualify standard grades. Fabricators with orbital welding certification capture premium pricing for custom high-pressure housings.
- Carbon Steel:Standard water service and non-corrosive hydrocarbon applications favor this grade for cost efficiency, though price volatility in ferrous inputs compresses margins on high-volume municipal contracts.
- Plastic:PVC and CPVC housings serve low-pressure, chemically compatible applications in semiconductor ultrapure water and select food-grade installations.
- Bronze:Naval brass and silicon bronze alloys persist in marine seawater cooling and legacy shipboard piping where galvanic compatibility with copper-nickel systems matters.
Carbon steel retains volume leadership in standard water service. Stainless steel is climbing the fastest as chemical processing and offshore specifications tighten.
End User:
Application severity and regulatory exposure create divergent procurement patterns across industrial verticals.
- Oil & Gas:Upstream, midstream, and downstream operations require API-compliant configurations rated for high-pressure hydrocarbon service. Subsea manifold applications demand duplex strainers with hyperbaric certification, a specification niche with limited qualified suppliers.
- Water Treatment:Municipal utilities drive automatic backwashing procurement to reduce manual maintenance cycles, while industrial wastewater operators face emerging PFAS filtration mandates at state level.
- Chemical Processing:Aggressive media and high-temperature service elevate 316L stainless specifications, with ethylene cracker investments on the Texas Gulf Coast concentrating demand for high-capacity duplex arrays.
- Food & Beverage:FDA 21 CFR Part 177 indirect food contact regulations mandate material traceability and surface finish documentation, favoring suppliers with validated quality systems.
Water treatment holds installed capacity across municipal infrastructure. Chemical processing is gaining share fastest as petrochemical capacity expansion accelerates.
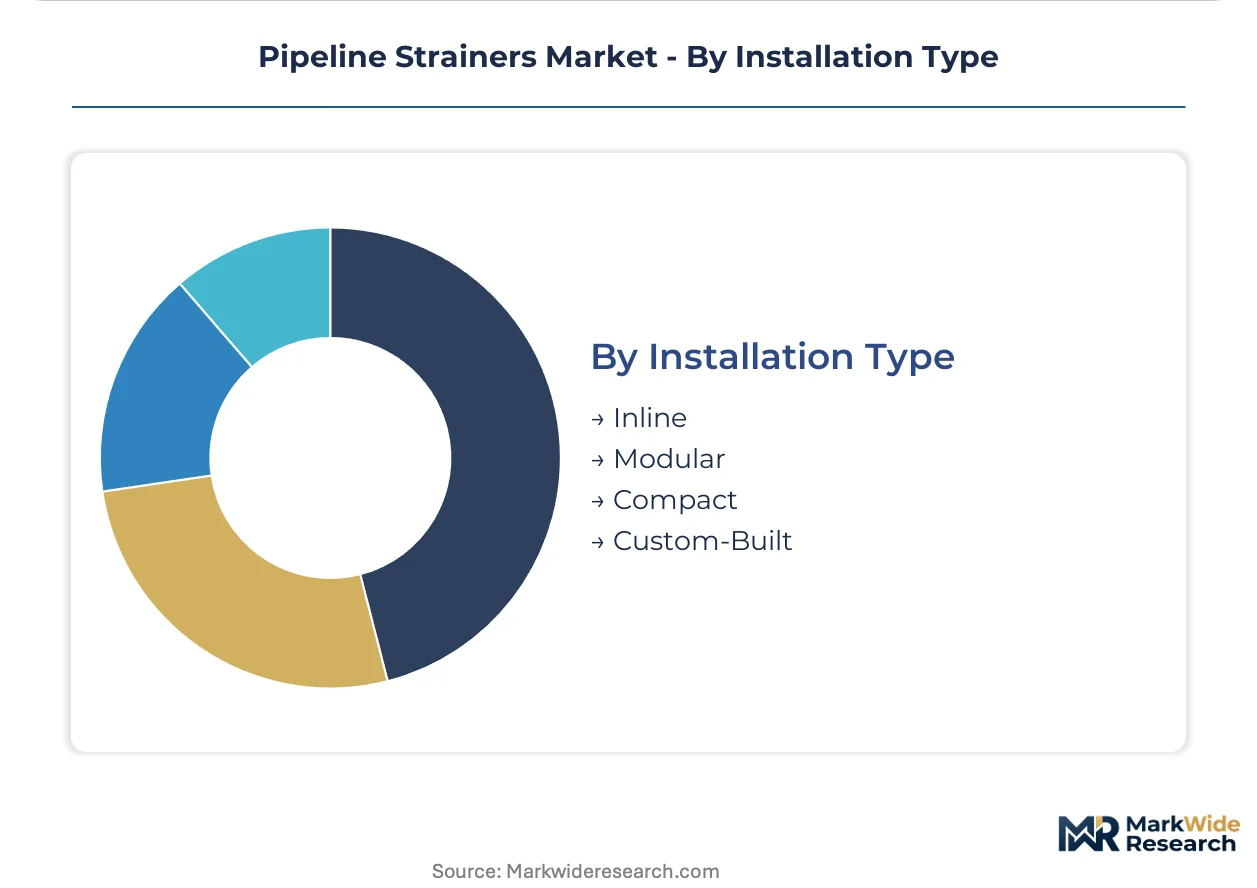
Installation Type:
Site constraints and maintenance accessibility determine configuration selection, with modular and custom architectures commanding engineering premiums.
- Inline:Standard flanged or threaded connections for straight-pipe insertion dominate replacement markets and greenfield construction where space permits.
- Modular:Pre-assembled skids with integrated valves and instrumentation reduce field installation labor, appealing to remote site operators in Alberta oil sands where technical labor availability constrains owner-operated construction.
- Compact:Reduced-footprint designs serve offshore platforms and congested process plants where piping density limits conventional housing dimensions.
- Custom-Built:Engineered-to-order fabrications address non-standard pressure ratings, exotic alloys, or unique space constraints, extending delivery schedules but capturing margin unavailable in catalog offerings.
Inline configurations hold installed capacity across standard industrial applications. Modular systems are expanding most quickly as remote site operators unbundle supply from field construction risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that of India by roughly 40% for API-certified duplex strainers, reflecting divergent certification burdens and labor cost structures. German fabricators command intermediate premiums through dual ASME-PED certification. Chinese producers compete on carbon steel volume but struggle to penetrate subsea and food-grade specification tiers.
United States
EPA Clean Water Act compliance deadlines drive municipal utility procurement of automatic backwashing systems across aging distribution infrastructure. The Safe Drinking Water Act amendments impose material traceability requirements that favor domestic fabricators with validated quality systems. The Texas Gulf Coast petrochemical corridor concentrates demand for high-capacity duplex strainer arrays serving new ethylene cracker investments.
Germany
REACH substance restrictions on chromium VI surface treatments force migration from traditional passivation chemistries to citric acid alternatives, extending lead times for export-certified strainers. The country's national chemical regulator enforces dual ASME and PED certification for cross-border industrial supply. Chemical processors in the Rhine-Ruhr industrial cluster consolidate procurement with certified suppliers to ensure regulatory continuity.
China
Domestic water treatment infrastructure expansion absorbs high volumes of carbon steel strainers for standard municipal service. GB standards and MIIT industrial policy shape local certification requirements that diverge from API and ASME specifications. Yangtze River Delta fabricators dominate domestic volume but face barriers penetrating offshore oil and gas specification tiers.
India
Central Public Health and Environmental Engineering Organisation guidelines drive municipal procurement for expanding urban water distribution networks. BIS certification requirements for pressure equipment create compliance friction for imported configurations. Gujarat chemical processors specify 316L stainless strainers for corrosive media handling at Dahej and Mundra industrial corridors.
Saudi Arabia
Aramco and SABIC downstream expansion concentrates procurement for high-temperature hydrocarbon service strainers. The country's national standards body enforces pressure equipment regulations aligned with API specifications. Jubail Industrial City and Yanbu petrochemical complexes anchor demand for duplex and automatic strainer configurations.
Pipeline Strainers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with automated electromechanical systems concentrated among diversified industrial conglomerates and carbon steel volume production dominated by regional fabrication specialists. The market structures around three tiers: premium specification suppliers with orbital welding certification, mid-tier ANSI-standard catalog producers, and commodity fabricators competing on delivery speed. Dominant competitive moves include backward integration into filter element supply and geographic relocation to escape skilled welder scarcity in Midwestern US manufacturing hubs.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton Filtration occupy positions that exemplify technology-forward archetypes through captive supply chain integration. CIRCOR Energy represents the specialized engineering tier focused on high-pressure subsea and hydrocarbon processing specifications. Keckley Company and Hayward Flow Control sit within the mid-tier catalog segment where ANSI-certified distributor networks determine competitive positioning.
| Leading Market Players |
|---|
| Krone Filtertechnik |
| Keckley Company |
| Parker Hannifin Corporation |
| CIRCOR Energy |
| Hayward Flow Control |
| Eaton Filtration |
| Armstrong International |
| Metso Corporation |
| Watts Water Technologies |
| Others |
Cost & Logistics Intelligence
Automatic backwashing strainer adoption replacing manual basket configurations is redrawing procurement economics and supplier geography simultaneously. Municipal utilities in the Great Lakes region are paying 40% premiums for electromechanical systems over passive housings, while carbon steel fabricators in India and China capture volume contracts at price points that compress margins for Midwestern US producers facing orbital welder scarcity.
Pricing Analysis
Price spreads between US and Indian markets for API-certified duplex strainers reach approximately 40%, reflecting divergent certification burdens and labor cost structures. Three-tier pricing structure across premium, standard, and economy levels separates orbital-welded 316L custom fabrications from ANSI-catalog carbon steel units and commodity-grade imports. Price differentiation stems from ASME B31.3 code documentation requirements and captive filter element supply integration. Pricing pressure intensifies in carbon steel municipal contracts as ferrous input volatility squeezes margin pools. Water treatment utilities exhibit highest price sensitivity in standard service, while offshore oil and gas operators accept premium positioning for subsea hyperbaric certification.
Supply Chain Analysis
Inbound logistics costs through Houston and Rotterdam ports shape landed pricing for European fabricators supplying US petrochemical corridors. Manufacturing concentration clusters in Germany, China, and the United States, with Yangtze River Delta producers dominating carbon steel volume and German specialists holding dual ASME-PED certification for cross-border industrial supply. Raw material dependencies center on nickel-molybdenum alloy feedstock for 316L grades, perforated plate from specialized metal service centers, and electromechanical actuator components. Supply chain risk concentrates in single-source vulnerability for orbital welding certification capacity. Distribution runs through ANSI-certified distributor networks stocking rapid-fulfillment basket configurations for municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Water Act compliance deadlines are accelerating a technology inflection that will displace legacy passive strainer architectures across North American municipal infrastructure. Automatic backwashing systems are capturing procurement share as labor scarcity forces automation adoption.
For Market Incumbents: Compound defensive positioning through backward integration into pleated filter element supply and captive orbital welding certification programs. Parker Hannifin Corporation's vertically integrated filtration division exemplifies this approach, sustaining margin pools that pure-play fabricators cannot match. Automate production lines or relocate from Midwestern US manufacturing hubs to escape skilled welder scarcity threatening custom stainless fabrication capacity. For New Entrants and Emerging Players: Aftermarket service unbundling represents the most penetrable white-space opportunity, particularly in remote site applications where technical labor availability constrains owner-operated maintenance. Alberta oil sands operators are contracting filtration uptime rather than equipment ownership, opening margin pools for channel intermediaries with field service capabilities. Target modular skid integration for greenfield petrochemical construction, where pre-assembled configurations reduce field installation labor and construction risk transfer. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier catalog producers holding ANSI-certified distributor networks but lacking automation engineering capabilities. Long-term viability favors suppliers with electromechanical system expertise and validated quality systems for FDA 21 CFR Part 177 food-grade installations. Monitor state-level PFAS maximum contaminant level announcements as the signal indicating retrofit demand inflection for finer-mesh automatic strainer systems at industrial wastewater discharge points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Element Supply | Parker Hannifin's captive pleated element production sustains margin pools unavailable to pure-play fabricators. |
| Orbital Welding Automation Capital Deployment | Midwestern US producers must automate or relocate to escape skilled welder scarcity compressing custom fabrication capacity. |
| Dual ASME-PED Certification Investment | German fabricators command intermediate pricing premiums through cross-border regulatory continuity for EU potable water installations. |
| Modular Skid Pre-Assembly Expansion | Remote site operators in Alberta oil sands unbundle supply from field construction risk through integrated valve and instrumentation packaging. |
| Smart Differential Pressure Monitoring Integration | Networked transducers enabling predictive maintenance signaling transform passive strainers into intelligent filtration nodes for municipal utilities. |
Research Approach
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented procurement patterns. Plant engineers at Texas Gulf Coast ethylene crackers, municipal water utility maintenance directors, aftermarket service heads at distributor networks, and procurement leads at offshore oil and gas operators provided operational perspective. Secondary sources included EPA enforcement action databases, FDA 21 CFR Part 177 material validation records, ASME B31.3 code interpretation bulletins, and customs trade data for stainless steel pressure equipment imports. Bottom-up unit economics triangulated against top-down infrastructure investment forecasts.
Sensitivity analysis across material cost volatility scenarios and regulatory compliance timeline variations shaped the projection framework. Segmentation dimensions modeled include product type architecture, material grade specification, end-use vertical severity, and installation configuration complexity. CAGRs were derived from installed base replacement cycles and greenfield capacity addition pipelines. Industry-specific inputs incorporated ethylene cracker investment tracking, municipal bond issuance for water infrastructure, and state-level PFAS rulemaking progression.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement and FDA food-grade validation requirements; material policy shifts would require re-modeling compliance-driven procurement timing. Commodity price volatility in nickel-molybdenum alloys and ferrous inputs, plus skilled welder availability shocks, constitute primary revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Air Heated Vaporizer Market
Valves
India Industrial Valves Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Explosion Vents Market
Valves
Steam Trap Market
Valves
Dense Phase Vessels Market
Valves
Steel Cylinder Market
Valves
Leak Detection Market
Valves
Pipeline and Process Services Market
Valves
Global Plug Valve Market
Valves
Global Solenoid Valves Market
Valves
Penstock Market
Valves
Actuators and Valves Market
Valves
Servo Valves Market
Valves
Compressor Valves Market
Valves
Pressure Reducing Valve Market