
 Global Stainless Steel Control Valves Market | 2026-2036
Global Stainless Steel Control Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stainless Steel Control Valves Market Intelligence
Preventive maintenance contracts and remote diagnostics subscriptions are decoupling hardware margins from long-term revenue streams in this sector. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor recurring service income alongside valve shipments. Flowserve Corporation competes through specialized aftermarket programs that extend equipment life cycles in corrosive process environments. Samson AG differentiates by concentrating engineering resources on customized actuation packages for European chemical producers.
Stainless steel control valves regulate fluid flow through precision-machined austenitic or duplex stainless steel bodies, typically rated for pressures exceeding ANSI Class 600 and temperatures spanning cryogenic to 538°C service, with corrosion resistance mandated by NACE MR0175 for sour gas exposure. Globe valves dominate critical throttling applications in oil and gas refineries where cavitation resistance determines equipment longevity. Smart valve technology represents the fastest-expanding segment as integrated positioners and predictive algorithms reduce unplanned shutdowns in power generation plants. Diaphragm valves occupy stable niche positions in food and beverage manufacturing where sanitary surface finishes prevent microbial contamination.
The US EPA enforces Maximum Achievable Control Technology standards that compel petrochemical manufacturers to specify low-emission valve packing systems. REACH and the EU F-Gas Regulation restrict fluoropolymer seal materials while pushing stainless steel fabricators toward alternative metallurgies. Japan's METI industrial efficiency guidelines incentivize smart valve retrofits in existing power and chemical infrastructure. Buyers must weigh total lifecycle cost against first-cost procurement as regulatory compliance windows compress and predictive maintenance capabilities reshape supplier selection criteria.
Market Dynamics
Smart valve technology is compressing equipment replacement cycles as predictive diagnostics redefine maintenance economics across process industries. Buyers now evaluate total lifecycle cost rather than first-cost procurement, forcing suppliers to bundle hardware with recurring service revenue streams.
Growth Catalysts
- EPA Maximum Achievable Control Technology standards:US petrochemical manufacturers must specify low-emission valve packing systems, accelerating stainless steel valve retrofits across Gulf Coast refineries.
- Ethane cracker investments:New petrochemical capacity along the US Gulf Coast and in Germany's Ludwigshafen corridor demands corrosion-resistant flow control infrastructure rated for sour gas service.
- Integrated positioners with predictive algorithms:Power generation plants in Japan are retrofitting existing infrastructure to reduce unplanned shutdowns under METI industrial efficiency guidelines.
Market Restraints
- Nickel price volatility:Austenitic and duplex stainless steel grades depend on nickel alloying, exposing fabricators to London Metal Exchange commodity swings that compress margins on fixed-price contracts.
- REACH fluoropolymer restrictions:The EU F-Gas Regulation and ECHA chemical safety standards limit PTFE and other seal materials, forcing costly metallurgy redesigns for European valve suppliers.
- Technical limitation in cryogenic service:Conventional globe valve designs face cavitation damage below -196°C, constraining adoption in LNG liquefaction trains despite growing terminal construction.
Strategic Opportunities
- India's chemical manufacturing expansion:BIS certification requirements and PLI scheme incentives for specialty chemicals are creating procurement windows for corrosion-resistant valve suppliers in Gujarat and Maharashtra industrial corridors.
- Hydrogen infrastructure buildout:High-pressure stainless steel valves rated for 700 bar service are penetrating electrolyzer and fueling station applications as hydrogen blending mandates spread across Germany and Japan.
- Remote diagnostics subscriptions:Valve OEMs are unbundling hardware from predictive maintenance software, creating recurring revenue streams that decouple growth from unit shipment volumes.
Industry Challenges
- NACE MR0175 sour gas certification timelines:Third-party validation for H2S-resistant metallurgies extends product development cycles by 8-14 months, delaying qualification for upstream oil and gas projects.
- Integration complexity with legacy DCS architectures:Smart valve positioners require protocol translation layers to communicate with existing distributed control systems in brownfield chemical plants, raising commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stainless Steel Control Valves Market |
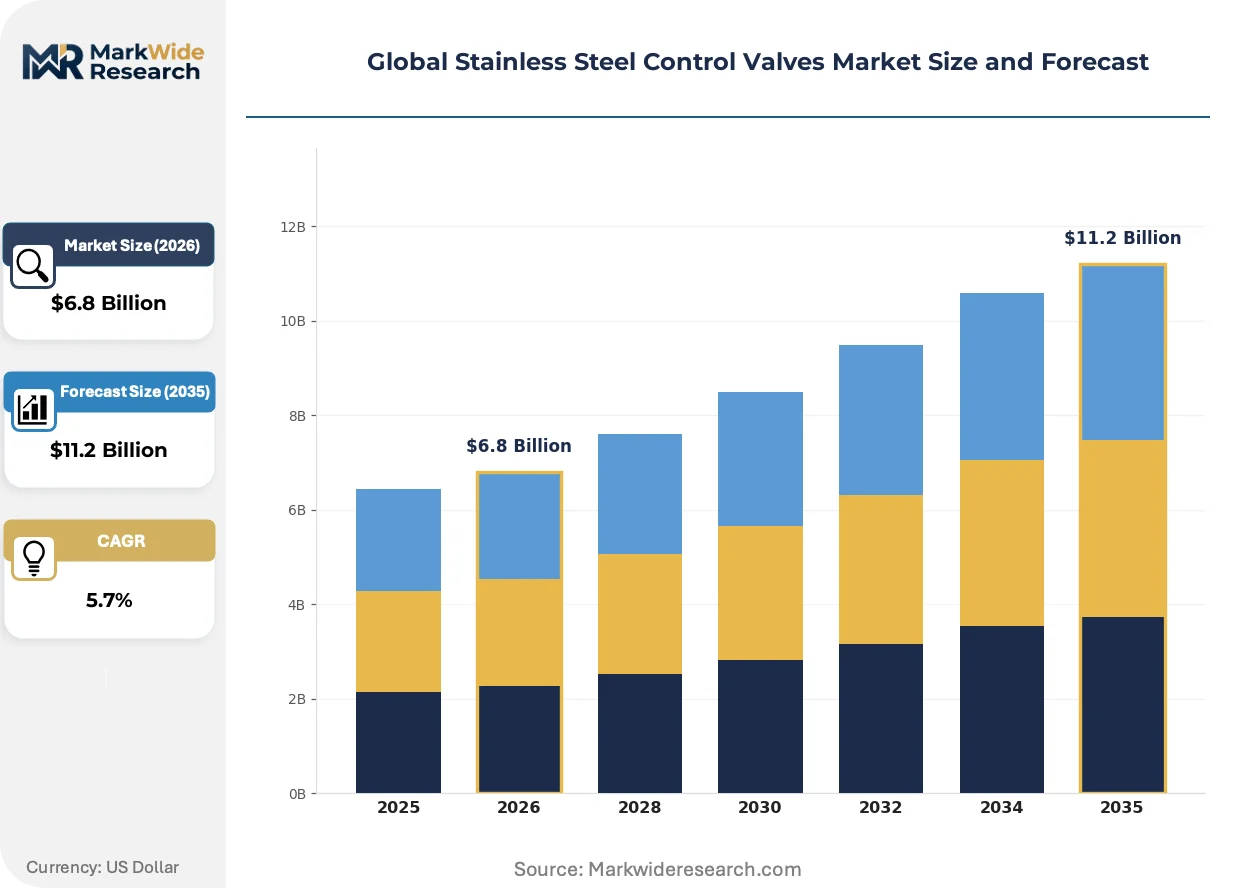
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Globe, Ball, Butterfly, Diaphragm, Gate, Needle Technology: Pneumatic, Electric, Hydraulic, Electro-Pneumatic, Smart, Manual Application: Oil & Gas Refineries, Power Generation Plants, Water Treatment Facilities, Chemical Processing Units, Food & Beverage Manufacturing, Pulp & Paper Mills End User Industry: Petrochemical Manufacturers, Power Producers, Wastewater Facilities, Specialty Chemical Firms, Beverage Producers, Paper Manufacturing Companies |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Pentair Plc, General Electric Co., Samson AG, IMI Plc, Christian Bürkert GmbH & Co. KG, Velan Inc., Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stainless Steel Control Valves Market Strategic Shifts & Innovations
Digitalization is redefining valve economics as hardware margins compress and software-enabled services capture expanding value pools. Three convergent developments are restructuring competitive positioning across the supply base.
Edge computing modules embedded in valve positioners are integrating vibration sensors, temperature probes, and pressure transducers into unified diagnostic platforms. Chemical processors in Germany's Ruhr industrial cluster are deploying these systems to predict stem seal degradation before fugitive emissions trigger EPA or REACH violations. This convergence is integrating maintenance scheduling with regulatory compliance windows, collapsing the traditional separation between operations and environmental health and safety functions.
Japan's METI industrial efficiency guidelines are mandating smart instrumentation retrofits in existing power generation infrastructure. Combined cycle gas turbine plants must demonstrate measurable efficiency improvements to maintain operating licenses, compelling owners to replace pneumatic actuation with electric smart valve packages. Japanese valve distributors are responding by building localized calibration and commissioning capabilities that foreign suppliers struggle to replicate.
Lifecycle service contracting is displacing transactional procurement as the dominant commercial model. End-users in US Gulf Coast petrochemical complexes are negotiating 10-year total cost of ownership agreements that bundle valve supply, installation, predictive maintenance, and eventual replacement. This restructuring concentrates purchasing authority among fewer procurement professionals who evaluate supplier ecosystems rather than individual product specifications.
Global Stainless Steel Control Valves Market Segmentation
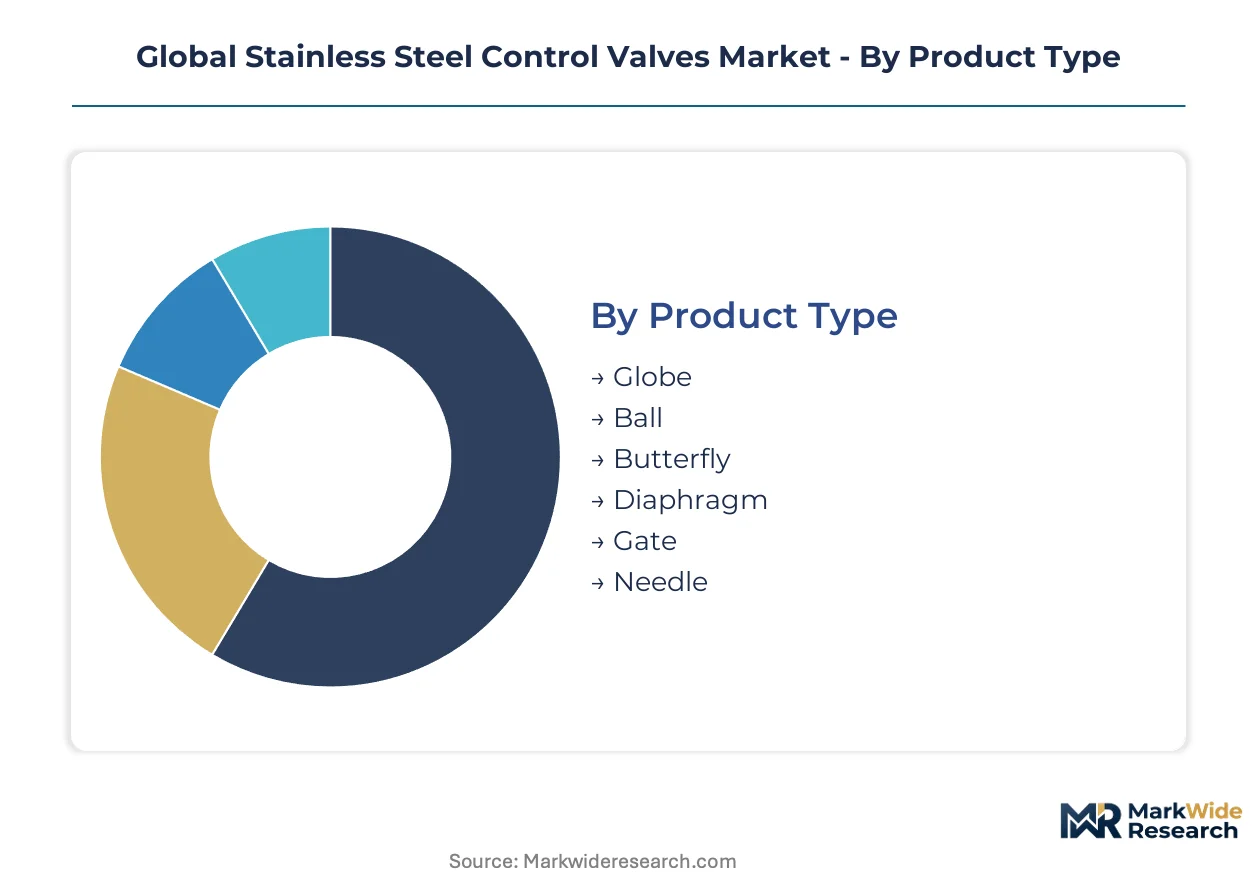
Segmentation in stainless steel control valves reveals how procurement criteria diverge across process environments. Material specifications, actuation technology, and regulatory exposure reshape supplier selection in each category.
Product Type:
Flow characteristics and pressure ratings dominate buyer evaluation in this category.
- Globe:Precision-machined austenitic bodies with linear flow control excel in throttling service. US Gulf Coast refineries specify these for cavitation-resistant applications under EPA Maximum Achievable Control Technology standards.
- Ball:Quarter-turn rotation through a perforated sphere delivers tight shutoff in high-cycle service. LNG liquefaction terminals in Japan favor ball configurations for cryogenic isolation below -162°C.
- Butterfly:Wafer-style designs reduce weight and face-to-face dimensions in large-bore piping. Water treatment facilities in Germany deploy these for cost-efficient flow modulation.
- Diaphragm:Flexible membranes isolate working fluid from mechanical components. Beverage producers require sanitary surface finishes meeting 3A standards.
- Gate:Wedge or parallel slide mechanisms provide straight-through flow with minimal pressure drop. Pulp mills use these for stock consistency control.
- Needle:Conical-tipped stems enable fine flow adjustment in instrument lines. Specialty chemical firms specify these for precise additive injection.
Volume sits with Globe configurations; growth tilts toward Ball designs for LNG infrastructure.
Technology:
Actuation method determines lifecycle economics and integration complexity.
- Smart:Integrated positioners with predictive algorithms and edge computing modules reduce unplanned shutdowns. Japanese power plants retrofit these under METI industrial efficiency guidelines.
- Pneumatic:Compressed air systems dominate legacy installations with proven reliability. Gulf Coast petrochemical corridors maintain extensive pneumatic infrastructure.
- Electric:Motor-driven actuation eliminates air supply dependencies and enables precise positioning. German chemical processors adopt these for energy efficiency compliance.
- Hydraulic:High-force output suits large valve sizes and high-pressure ratings. Offshore platforms specify these for subsea isolation.
- Electro-Pneumatic:Hybrid systems combine pneumatic power with electronic control. Brownfield plants favor these for protocol compatibility.
- Manual:Handwheel or lever operation serves isolation duties with minimal maintenance. Remote facilities deploy these where power supply is unreliable.
Smart technology commands premium positioning; Pneumatic retains installed base dominance.
Application:
Process severity and fluid characteristics dictate material and design specifications.
- Oil & Gas Refineries:Sour gas exposure demands NACE MR0175-certified duplex stainless metallurgies. US EPA fugitive emissions rules accelerate packing system upgrades.
- Chemical Processing Units:Corrosive media and temperature cycling require corrosion-resistant alloys. REACH fluoropolymer restrictions force seal material redesigns in European installations.
- Power Generation Plants:Steam conditioning and turbine bypass applications need precise thermal control. Japanese combined cycle facilities retrofit smart valves for efficiency certification.
- Water Treatment Facilities:Chlorine resistance and potable water compliance drive material selection. German municipalities specify these for infrastructure modernization.
- Food & Beverage Manufacturing:Sanitary surface finishes prevent microbial contamination. 3A and EHEDG standards govern procurement.
- Pulp & Paper Mills:Black liquor and bleaching chemical exposure requires specialized alloys. Scandinavian mills lead adoption of duplex stainless configurations.
Oil & Gas Refineries anchor procurement volume; Chemical Processing Units show steepest expansion trajectory.
End User Industry:
Capital intensity and regulatory exposure separate procurement behaviors.
- Petrochemical Manufacturers:Ethane cracker investments along the US Gulf Coast and Germany's Ludwigshafen corridor drive demand for corrosion-resistant flow control.
- Specialty Chemical Firms:Batch process flexibility and material traceability requirements favor customized valve packages. India's PLI scheme beneficiaries in Gujarat expand procurement.
- Power Producers:Efficiency mandates and emission controls compel instrumentation upgrades. Japanese utilities lead smart valve retrofit cycles.
- Wastewater Facilities:Infrastructure aging and capacity expansion create replacement demand. German Ruhr region utilities modernize treatment infrastructure.
- Beverage Producers:Hygienic design and clean-in-place compatibility dominate specifications. European craft brewing expansion supports niche demand.
- Paper Manufacturing Companies:Consolidation and environmental compliance reshape equipment procurement. Nordic integrated producers invest in process optimization.
Petrochemical Manufacturers concentrate volume; Specialty Chemical Firms expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates fabrication capacity for corrosion-resistant valve assemblies while the United States consumes the largest share of high-pressure units for petrochemical service. Japan and India represent the fastest-expanding procurement zones as efficiency mandates and industrial incentives reshape regional demand patterns.
United States
Ethane cracker investments along the Gulf Coast petrochemical corridor drive procurement of sour gas-rated stainless steel valves. EPA Maximum Achievable Control Technology standards compel low-emission packing retrofits across Texas and Louisiana refineries. Houston-area engineering firms specify duplex metallurgies for new construction projects.
Germany
Chemical processing expansions in Ludwigshafen and Leverkusen demand REACH-compliant seal materials and alternative fluoropolymer-free designs. EU F-Gas Regulation restrictions force metallurgy redesigns for valve fabricators serving European markets. Ruhr industrial cluster processors deploy edge computing diagnostics to predict stem seal degradation.
Japan
Combined cycle gas turbine plants retrofit pneumatic actuation with electric smart valve packages under METI industrial efficiency guidelines. Power producers in the Chubu and Kanto regions demonstrate measurable efficiency improvements to maintain operating licenses. Local distributors build calibration capabilities that foreign suppliers struggle to replicate.
India
BIS certification requirements and PLI scheme incentives for specialty chemicals create procurement windows in Gujarat and Maharashtra industrial corridors. Domestic chemical manufacturers expand stainless steel valve procurement as environmental compliance windows compress. Mumbai-Pune belt engineering contractors specify corrosion-resistant flow control for new batch process facilities.
China
Dual carbon goals and industrial efficiency targets accelerate smart valve retrofits in existing chemical and power infrastructure. MIIT guidelines push domestic fabricators toward higher-grade austenitic and duplex stainless specifications. Yangtze River Delta petrochemical complexes source locally certified valves for pressure-rated applications.
Global Stainless Steel Control Valves Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the stainless steel control valve sector. Integrated foundry operations in Germany and the United States cast duplex bodies in-house while specialized engineering firms outsource fabrication to certified Asian machine shops. Three archetypes dominate: diversified industrial conglomerates bundling valves with automation platforms, mid-cap specialists concentrating on severe-service metallurgies, and regional fabricators serving localized procurement requirements. Competitive moves center on lifecycle service contracting and predictive maintenance software unbundling rather than capacity expansion.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the platform-ecosystem archetype. Samson AG represents the European engineering-specialist tier with concentrated resources on customized actuation packages. These three anchor distinct competitive vectors: digital service integration, aftermarket lifecycle programs, and regional engineering customization.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Pentair Plc |
| General Electric Co. |
| Samson AG |
| IMI Plc |
| Christian Bürkert GmbH & Co. KG |
| Velan Inc. |
| Crane |
| Others |
Cost & Logistics Intelligence
Precision machining specialists concentrated in Germany's Ruhr industrial cluster anchor the labor-cost differential that separates premium smart valve packages from economy-grade pneumatic alternatives. Nickel alloy sourcing volatility and REACH compliance engineering hours widen pricing spreads between NACE-certified severe-service units and standard austenitic configurations.
Pricing Analysis
Margin tightening in economy-grade pneumatic valves reflects nickel price volatility on the London Metal Exchange and compressed procurement timelines from Indian specialty chemical projects. Three-tier pricing structure across premium smart packages, standard electric actuation, and economy pneumatic tiers differentiates on predictive maintenance bundling and NACE MR0175 certification depth. Cost-down pressure on standard-grade units accelerates as Gulf Coast petrochemical buyers consolidate purchasing authority under lifecycle contracting models. Price sensitivity concentrates among wastewater facilities and small-batch chemical processors, while sour gas-rated duplex metallurgies command inelastic demand from US and German upstream operators.
Supply Chain Analysis
Refurbishment flows for smart valve positioners and actuator remanufacturing programs in Japan's Chubu region create secondary supply channels that compete with new-unit fabrication. Raw material supply concentrates in Germany, the United States, and Japan for duplex stainless casting and precision machining, while seal component fabrication draws from specialized fluoropolymer-free suppliers in the EU. Nickel and molybdenum alloying inputs remain tethered to commodity exchange volatility, creating margin compression risk on fixed-price project contracts. Distribution runs through authorized distributor networks with localized calibration capabilities, particularly in Japan where METI compliance documentation requirements favor domestic channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply-constrained conditions where NACE MR0175 certification timelines extending 8-14 months prop pricing power for qualified suppliers. Duplex stainless foundry capacity and predictive maintenance software engineering talent represent binding bottlenecks.
For Market Incumbents: To counter margin compression from nickel volatility and fixed-price contract exposure, backward integration into captive duplex stainless foundry operations in Germany or the US Gulf Coast secures metallurgical control. Channel control through exclusive distributor relationships with localized METI calibration capabilities in Japan defends against emerging regional fabricators. For New Entrants and Emerging Players: Enter via India's Gujarat and Maharashtra specialty chemical corridors where BIS certification requirements and PLI scheme incentives create procurement windows for corrosion-resistant valve suppliers lacking legacy installed base. Hydrogen infrastructure applications at 700 bar service ratings offer the most penetrable white space, with electrolyzer OEM partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap severe-service specialists possessing NACE MR0175 qualification and smart valve software stacks, given hydrogen infrastructure buildout and predictive maintenance subscription scaling. Long-term viability over a multi-year horizon favors targets with recurring revenue streams decoupled from unit shipment volumes. Monitor METI efficiency guideline enforcement and EPA MACT standard expansion as inflection indicators for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Duplex Foundry Capacity | Captive metallurgy supply secures NACE MR0175 certification timelines against third-party bottlenecks. |
| Predictive Maintenance Software Unbundling | Recurring revenue streams from remote diagnostics subscriptions reduce hardware margin dependency. |
| Localized Calibration Infrastructure Buildout | Japanese METI compliance documentation requirements favor domestic channel partner investments. |
| Hydrogen Service Rating Expansion | 700 bar valve qualification opens electrolyzer and fueling station procurement in Germany and Japan. |
| Lifecycle Service Contracting | Ten-year total cost of ownership agreements concentrate purchasing authority among fewer procurement professionals. |
Research Approach
Trade association filings, customs and import-export databases, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning. Primary interviews with plant maintenance directors, petrochemical procurement leads, valve distributor technical specialists, and aftermarket service heads combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across installed base replacement cycles and new project capital expenditure patterns informed the analytical framework over the projection horizon. Segmentation modeling covered product type, actuation technology, application severity, and end-user industry capital intensity, with CAGRs derived from regression analysis against ethane cracker investment pipelines and regulatory compliance window timing. Nickel price volatility indices and NACE certification queue lengths served as industry-specific forecast inputs.
Revisions become necessary when EPA MACT enforcement intensity, REACH fluoropolymer restriction scope, or METI guideline expansion timelines materially diverge from baseline assumptions. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through rates and smart valve retrofit penetration curves. Practitioners should monitor London Metal Exchange nickel volatility, hydrogen infrastructure subsidy announcements in Germany and Japan, and third-party NACE certification backlog lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Static Seals Market
Valves
Global Marine Actuators and Valves Market
Valves
Dense Phase Vessels Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Global Gate Valve Market
Valves
Pneumatic Positioner Market
Valves
Refrigeration Valves Market
Valves
Vaneometer Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Choke Valves Market
Valves
Valve Grinder Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Rupture Discs Market
Valves
Cryogenic Valve Market
Valves
Christmas Tree Valves Market