
 Stainless Steel Valve Tag Market | 2026-2036
Stainless Steel Valve Tag Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Valve Tag Market Analytics
Pharmaceutical manufacturers are unwinding their reliance on paper-based valve identification toward permanent metal tagging systems. Brady leverages its captive engraving technology to sustain premium positioning in validated environments. Dixon anchors its competitive stance through specialized distribution to oil refineries across the Gulf Coast.
Stainless steel valve tags are corrosion-resistant identification plates, typically fabricated from 300-series austenitic grades with minimum chromium content of sixteen percent, designed to maintain legibility through thermal cycling and chemical exposure in process piping systems. Laser cutting now dominates high-precision applications where barcodes and serial numbers require sub-millimeter accuracy, while stamping retains cost advantages in bulk utility infrastructure. Among end users, oil and gas operators represent the most mature demand pool with standardized procurement frameworks, whereas pharmaceutical facilities represent the fastest-growing segment driven by serialization mandates and audit trail requirements.
The FDA enforces traceability standards for process equipment in drug manufacturing facilities, directly elevating demand for permanently marked metal tags that survive clean-in-place protocols. OSHA's Process Safety Management regulations for highly hazardous chemicals mandate clear valve identification, creating compliance-driven replacement cycles across chemical processing plants. Stakeholders must monitor evolving ISO 9001 certification requirements for supplier quality management, as these increasingly specify material test reports and alloy verification for critical service components.
Market Dynamics
The stainless steel valve tag market is experiencing structural compression as laser-etching technology eliminates mechanical engraving capacity while FDA sterilization traceability mandates force replacement cycles in pharmaceutical cleanrooms. This dual pressure is reshaping supplier economics and buyer procurement frameworks simultaneously.
Growth Catalysts
- FDA Unique Device Identification:Surgical instrumentation traceability requirements are mandating laser-etched 316L-grade tags that survive autoclave cycles without degradation, forcing hospital systems into compliance-driven procurement.
- OSHA Process Safety Management:Chemical processing facilities handling highly hazardous materials must maintain legible valve identification through thermal cycling and chemical exposure, creating recurring replacement demand.
- Germany's chemical corridor concentration:BASF and Bayer facility standardization on corrosion-resistant 316L valve tags for aggressive process environments is establishing specification benchmarks across European process industries.
Market Restraints
- Nickel price volatility:300-series austenitic stainless steel production depends on nickel alloying inputs subject to London Metal Exchange fluctuations, compressing fabricator margins during cost spikes.
- Laser equipment capex concentration:High-precision sub-millimeter engraving capability requires capital investment concentrated among specialized job shops in Germany and the United States, limiting supplier entry.
- Polymer tag substitution:High-performance thermoplastic identification systems offer lower unit costs for non-sterilization utility applications, capturing share in bulk water and wastewater infrastructure.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO serialization mandates for active pharmaceutical ingredient tracking are creating first-time demand for permanent metal valve tags in bulk drug production facilities.
- ISO 9001 supplier quality evolution:Certification requirements increasingly specify material test reports and alloy verification, creating premium positioning for fabricators with captive metallurgical testing.
- Barcode-etched tag convergence:Integration of Data Matrix and QR codes directly onto stainless steel surfaces enables digital asset management without adhesive label failure in clean-in-place environments.
Industry Challenges
- Laser programming expertise scarcity:Sub-millimeter accuracy for serialized barcodes requires specialized CAD-CAM operators, constraining production scaling for mid-tier fabricators.
- Legacy stamping equipment stranding:Mechanical die-based production lines face utilization collapse as pharmaceutical and chemical buyers specify laser-only procurement, forcing asset write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Valve Tag Market |
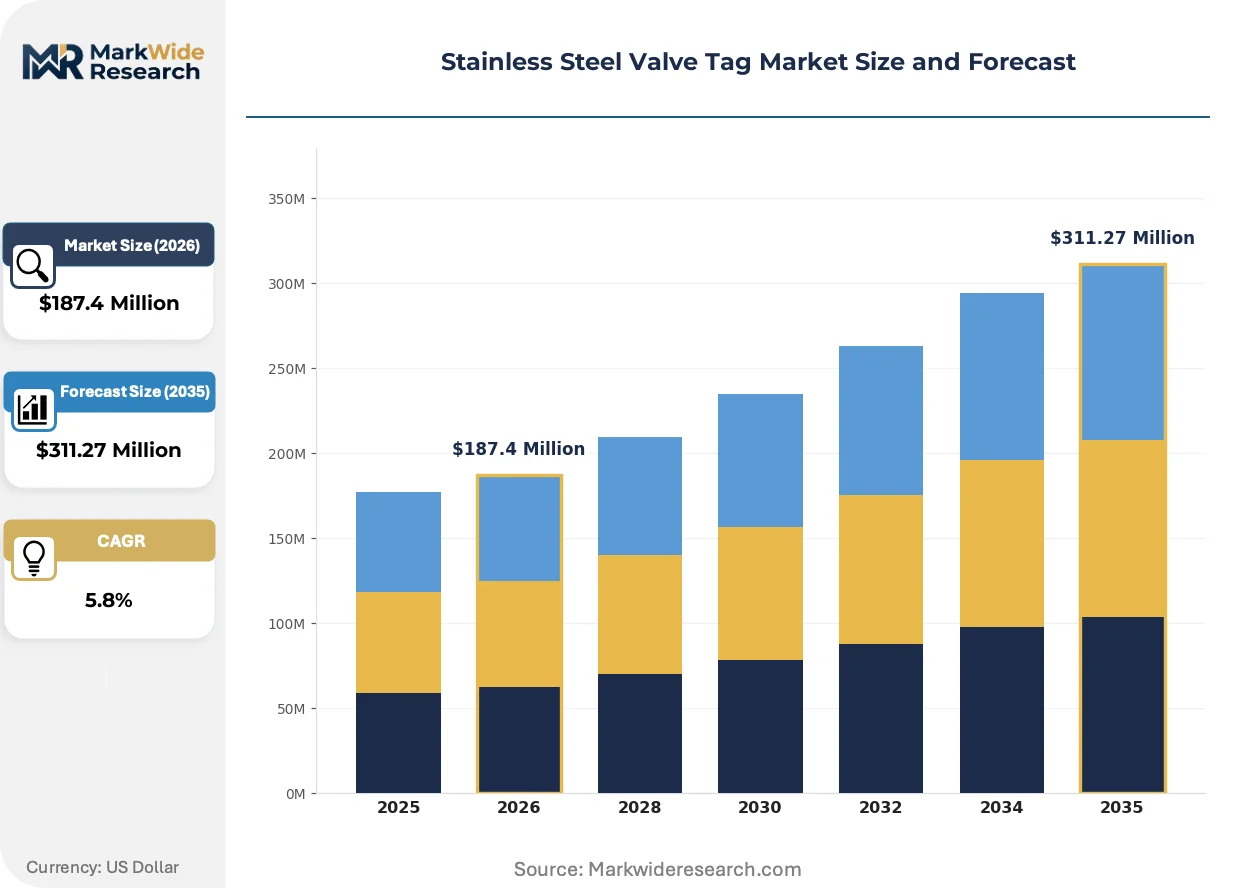
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Tags, Standard Tags, Engraved Tags, Color-Coded Tags Manufacturing Process: Laser Cutting, Stamping, Etching, Injection Molding End User: Oil & Gas, Water Treatment, Pharmaceuticals, Food & Beverage Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Brady, Creative Safety Supply, Dixon, Wellgrow Industries Corp, SSP Corporation, Truly Tubular Fitting Corp, Smith Cooper International, Top Line Process Equipment Company, Hebei Guangde Stainless Steel Valve Industry Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Valve Tag Market Evolving Landscape
Digital traceability requirements are fundamentally altering how process industries specify valve identification, compressing the acceptable technology set while elevating metallurgical and engraving precision standards. Three intersecting developments are reshaping competitive positioning.
Laser-etching technology is decomposing the traditional segmentation between premium precision work and bulk utility stamping. Pharmaceutical cleanroom operators now specify sub-millimeter barcode accuracy as standard, eliminating mechanical engraving from validated environments. This capability compression is forcing job-shop consolidation as capital-intensive laser systems displace lower-precision alternatives.
REACH regulation enforcement across the European Union is restricting hexavalent chromium surface treatments historically used for tag corrosion resistance. ECHA substance evaluation is driving fabricators toward passivation-only finishing or laser-induced surface modification, altering cost structures and supplier qualification timelines for chemical processing buyers.
Buyer specification behavior is fragmenting between centralized engineering standards and site-level procurement autonomy. Oil and gas majors with standardized global frameworks are contracting directly with certified fabricators, while municipal water utilities retain distributed purchasing through regional distributors. This bifurcation is most visible across United States utility infrastructure, where procurement centralization lags industrial process sectors by several adoption cycles.
Stainless Steel Valve Tag Market Segmentation
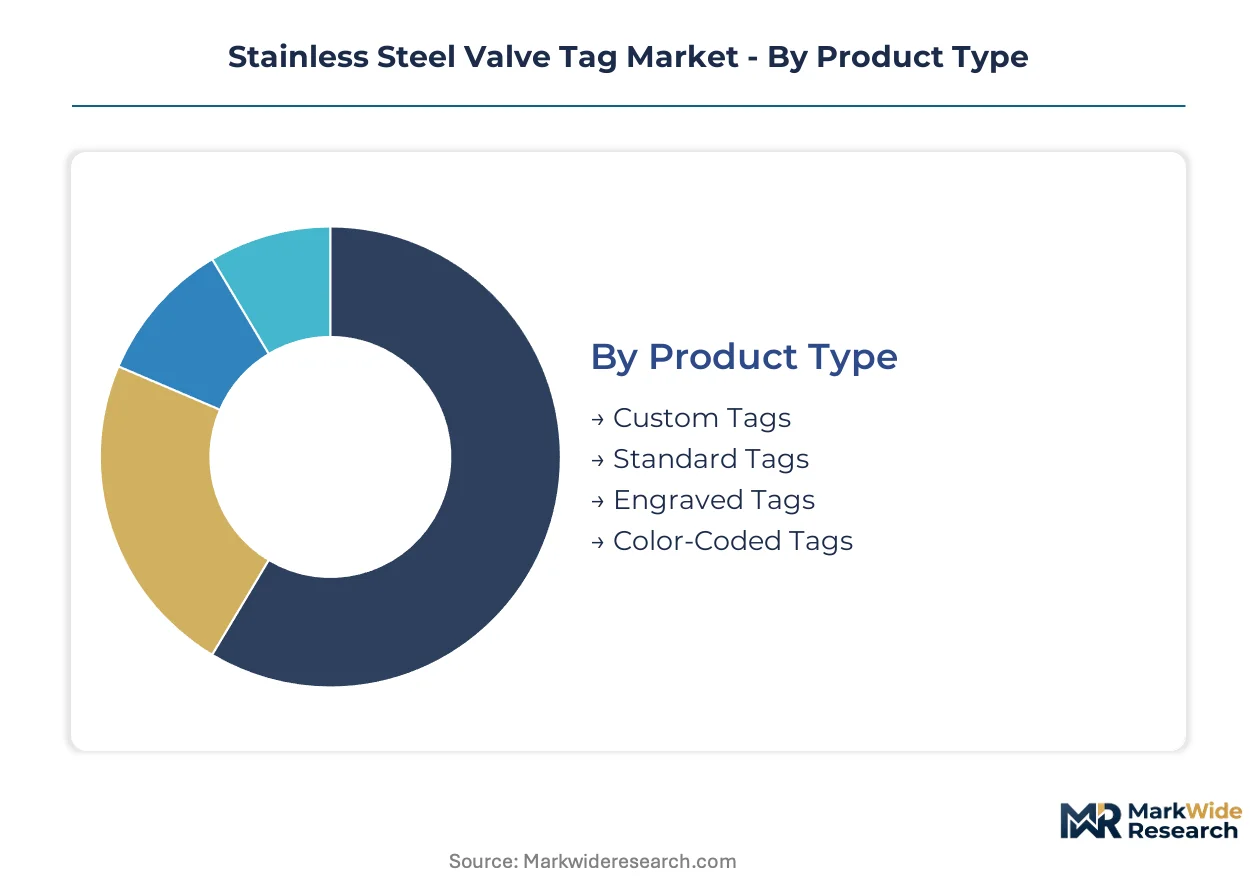
Valve tag procurement patterns fragment sharply across process industries, with pharmaceutical sterilization protocols demanding laser-etched permanence while municipal utilities tolerate stamped economy grades. Understanding these segment boundaries illuminates where specification premiums materialize and where price compression dominates.
Product Type:
FDA sterilization traceability mandates and OSHA chemical exposure standards create divergent specification tiers across product categories, with validated environments commanding metallurgical certifications absent from bulk utility procurement.
- Custom Tags:Engineered to client-specific dimensions, alloy grades, and serialization formats with full material test report documentation. Pharmaceutical manufacturers in Germany's chemical corridor specify these for cleanroom steam sterilization cycles where 316L-grade corrosion resistance proves mandatory.
- Engraved Tags:Mechanical or laser-cut character permanence distinguishes these from surface-printed alternatives. Oil and gas operators across the Gulf Coast standardize on these for subsea and surface facility valve identification subject to salt spray and thermal cycling degradation.
- Standard Tags:Pre-fabricated dimensional formats with limited alloy selection, serving maintenance departments with replacement volume requirements and compressed procurement timelines.
- Color-Coded Tags:Anodized or painted surface treatments for rapid fluid service identification, deployed in chemical processing plants where OSHA Process Safety Management regulations mandate visual hazard differentiation at valve stations.
Established volume favors Standard Tags; emerging adoption favors Custom Tags.
Manufacturing Process:
Capital equipment intensity separates production methods into precision-capable and volume-optimized tiers, with laser systems commanding premium positioning against mechanical alternatives facing utilization collapse.
- Laser Cutting:Sub-millimeter accuracy enables Data Matrix and QR code integration directly onto stainless steel surfaces without adhesive failure risk. Pharmaceutical facilities specify this exclusively for barcode-etched tags supporting digital asset management in clean-in-place environments.
- Stamping:Mechanical die-based production retains cost advantages in bulk water and wastewater infrastructure where serialization requirements remain absent. Municipal utilities across United States regional systems continue procurement through this lower-unit-cost channel.
- Etching:Chemical or electrochemical material removal processes suited to moderate precision requirements with lower capital barriers than laser installation.
- Injection Molding:Polymer-based tag fabrication for non-metallic identification applications, capturing share in utility infrastructure where corrosion resistance demands fall below stainless steel thresholds.
Process concentration clusters in Laser Cutting for validated environments; Stamping retains utility-scale replacement cycles.
End User:
Regulatory compliance intensity varies dramatically across process sectors, with serialization mandates and sterilization protocols elevating metallurgical and engraving specifications in pharmaceutical applications above commodity utility standards.
- Pharmaceuticals:Cleanroom identification systems demand 316L-grade laser-etched tags surviving repeated autoclave cycles without legibility degradation. FDA Unique Device Identification requirements for surgical instrumentation traceability mandate permanent marking systems that withstand aggressive sterilization protocols.
- Oil & Gas:Standardized procurement frameworks across integrated operators specify corrosion-resistant tagging for subsea, offshore, and refining environments. Gulf Coast concentration of refining capacity sustains volume demand with established supplier qualification pathways.
- Water Treatment:Municipal and industrial facilities balance identification permanence against budget constraints, with polymer substitution threatening stainless steel share in non-critical service applications.
- Food & Beverage:FDA food contact surface regulations and washdown protocol requirements drive specification of passivated stainless steel tags in processing equipment zones.
Regulatory stringency peaks in Pharmaceuticals; procurement standardization concentrates in Oil & Gas.
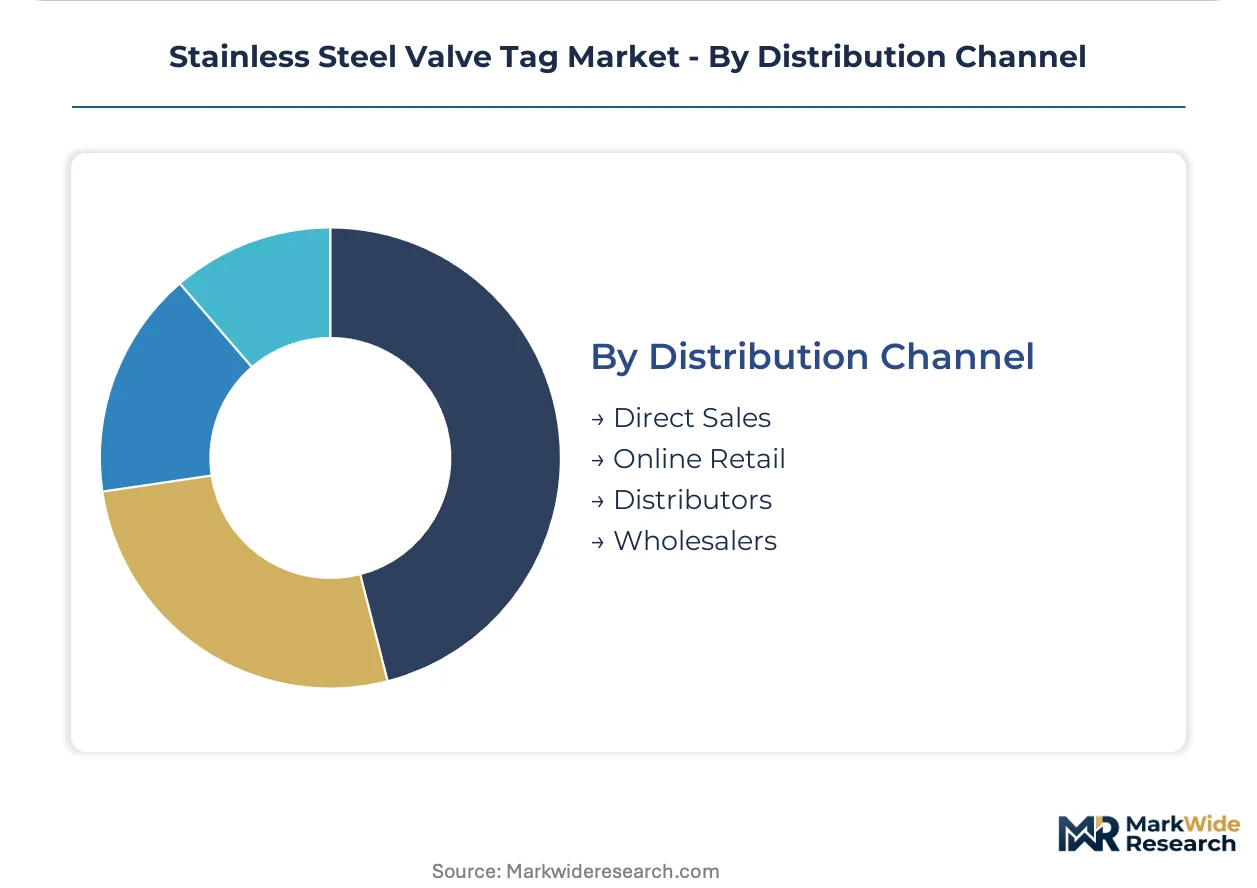
Distribution Channel:
Buyer sophistication and procurement centralization determine channel selection, with engineering-validated environments bypassing intermediaries while fragmented municipal purchasers rely on regional distributor networks.
- Direct Sales:Certified fabricators contract directly with oil and gas majors and pharmaceutical multinationals possessing centralized engineering standards. Material test reports and alloy verification documentation flow through these relationships to satisfy ISO 9001 supplier quality requirements.
- Distributors:Regional inventory positioning serves maintenance departments and smaller process facilities with intermittent replacement demand and limited metallurgical specification expertise.
- Online Retail:E-commerce platforms capture standard tag formats for expedited procurement in non-validated environments where documentation requirements remain minimal.
- Wholesalers:Volume aggregation for contractor and industrial supply houses serving fragmented utility and commercial building infrastructure markets.
Specification complexity favors Direct Sales; procurement fragmentation sustains Distributor relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators export laser-etched 316L-grade valve tags to pharmaceutical cleanrooms across India and the United States, establishing a trade corridor anchored by BASF and Bayer facility specifications in the chemical corridor.
United States
Gulf Coast refineries and pharmaceutical manufacturers drive demand for corrosion-resistant identification systems. OSHA Process Safety Management regulations mandate legible valve marking through thermal cycling and chemical exposure. Houston-area petrochemical clusters standardize procurement frameworks for subsea and surface facility applications.
Germany
BASF and Bayer facility standardization on 316L-grade valve tags establishes specification benchmarks across European process industries. ECHA REACH regulation enforcement restricts hexavalent chromium surface treatments, pushing fabricators toward passivation-only finishing. The Ludwigshafen chemical cluster anchors corrosion-resistant tag demand for aggressive process environments.
India
CDSCO serialization mandates for active pharmaceutical ingredient tracking create first-time demand for permanent metal valve tags in bulk drug production facilities. The country's national pharmaceutical regulator enforces traceability standards that elevate laser-etched specifications. Maharashtra and Gujarat pharmaceutical manufacturing zones drive cleanroom identification system upgrades.
China
Process equipment manufacturers in the Yangtze River Delta serve domestic chemical and pharmaceutical facility expansion. GB standards for industrial equipment identification align with ISO 9001 supplier quality requirements. Shanghai-area fabricators scale laser-cutting capacity for barcode-etched tag convergence in digital asset management.
Japan
METI industrial safety guidelines reinforce valve identification permanence in chemical processing and pharmaceutical manufacturing environments. JIS standards for stainless steel grades specify minimum chromium content for corrosion resistance. Osaka-based process equipment suppliers integrate laser-etched tags into clean-in-place protocol compliance.
Stainless Steel Valve Tag Market Competitive Landscape
Player mix skews toward specialized fabricators with captive laser-etching capability and established distributor relationships. The market exhibits moderate concentration, with premium-tier suppliers serving validated pharmaceutical environments and mid-tier stamping operations retaining utility-scale replacement cycles. Two strategic archetypes dominate: precision-focused job shops with metallurgical testing capabilities, and volume-oriented distributors leveraging regional inventory positioning. Competitive moves concentrate on technology licensing for sub-millimeter barcode accuracy and backward integration into captive alloy supply.
Among United States-based suppliers, Brady and Dixon exemplify divergent positioning archetypes. Brady occupies a position within the premium-tier validated environment segment, while Dixon anchors the industrial distribution channel serving Gulf Coast refining clusters. Hebei Guangde Stainless Steel Valve Industry Co. Ltd represents the Chinese fabrication tier supplying process equipment manufacturers in the Yangtze River Delta. These three companies illustrate how geographic origin and organizational structure correlate with market segment focus.
| Leading Market Players |
|---|
| Brady |
| Creative Safety Supply |
| Dixon |
| Wellgrow Industries Corp |
| SSP Corporation |
| Truly Tubular Fitting Corp |
| Smith Cooper International |
| Top Line Process Equipment Company |
| Hebei Guangde Stainless Steel Valve Industry Co. Ltd |
| Others |
Value Network & Pricing Analysis
FDA Unique Device Identification compliance gates both supplier qualification and price differentiation simultaneously, as pharmaceutical buyers will not source from fabricators lacking laser-etching capability regardless of unit cost advantages. This regulatory threshold stratifies the market into certified premium suppliers and excluded mechanical stamping operations.
Pricing Analysis
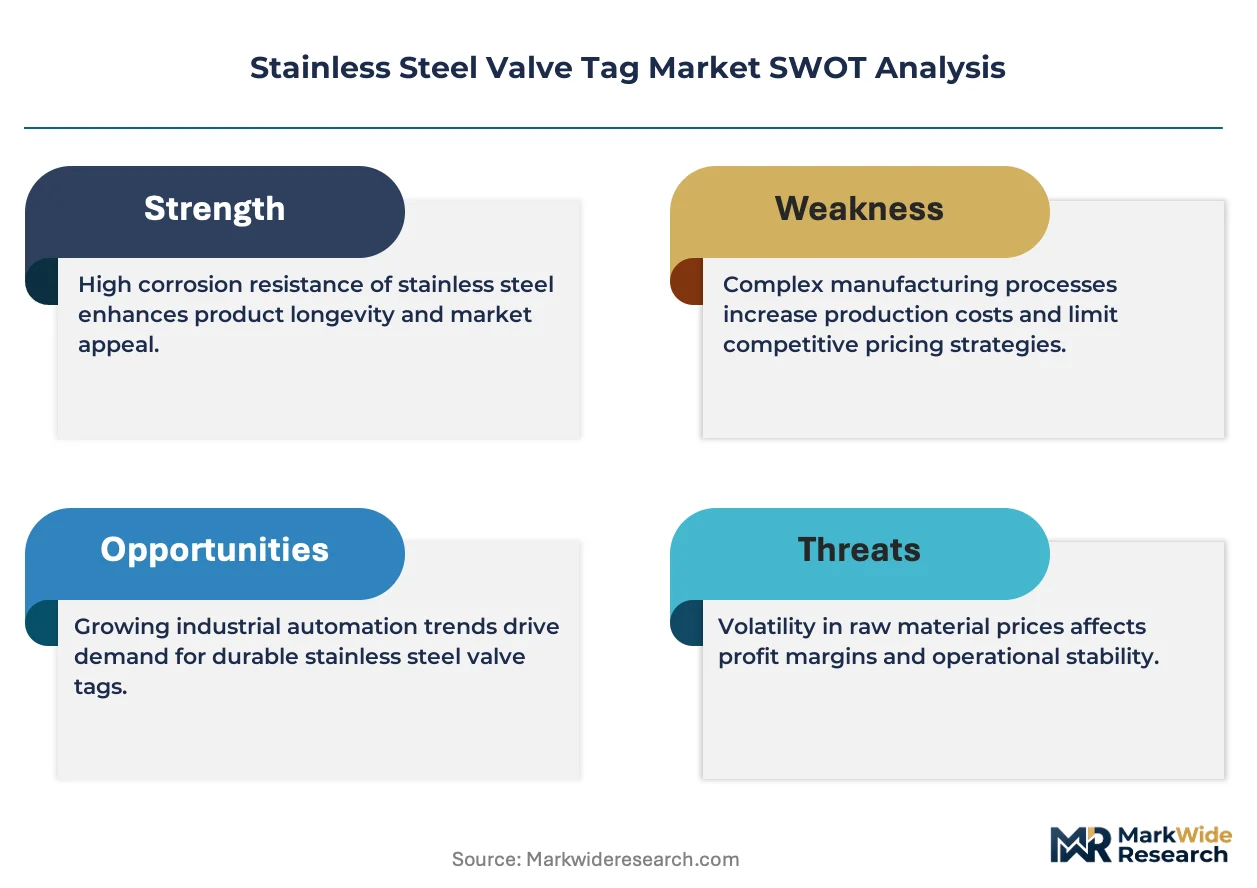
Current-generation laser-etched tags command substantial premiums over prior-generation stamped alternatives, while next-generation barcode-integrated formats with Data Matrix serialization sit at the apex. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with ISO 9001 material test report documentation adding further differentiation. Pricing pressure stems from nickel price volatility compressing fabricator margins on 300-series austenitic grades. Municipal water utilities represent the most price-sensitive segment, while pharmaceutical cleanroom operators prioritize traceability compliance over unit cost.
Supply Chain Analysis
Germany and the United States anchor precision laser-etching capacity for validated pharmaceutical environments, while China scales fabrication for process equipment manufacturers in the Yangtze River Delta. Raw material inputs draw from nickel alloying supplies subject to London Metal Exchange fluctuations, 316L-grade stainless steel sheet stock, and specialized laser optics systems. Single-source vulnerability concentrates in German job shops holding sub-millimeter barcode engraving expertise. Distribution runs through direct sales channels for certified fabricators serving oil and gas majors, with regional distributors capturing fragmented municipal utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stainless steel valve tag market is entering a cyclical recovery driven by pharmaceutical facility capital expenditure cycles upgrading cleanroom identification systems. Replacement demand from FDA sterilization traceability mandates creates sustained procurement momentum.
For Market Incumbents: Secure captive metallurgical testing capabilities to satisfy evolving ISO 9001 supplier quality requirements specifying material test reports and alloy verification. Defend against polymer tag substitution in utility infrastructure by emphasizing corrosion resistance in aggressive process environments. Add laser programming expertise through specialized CAD-CAM operator recruitment to constrain mid-tier competitor scaling. For New Entrants and Emerging Players: Anchor in India's pharmaceutical manufacturing expansion where CDSCO serialization mandates create first-time demand for permanent metal valve tags in bulk drug production facilities. Target Maharashtra and Gujarat pharmaceutical zones with laser-etching capability absent from local fabrication bases. Pursue technology licensing partnerships for sub-millimeter barcode accuracy rather than capital-intensive equipment acquisition. For Investors and Strategic Acquirers: FDA sterilization traceability mandates reshape the acquisition landscape toward precision-focused job shops with established pharmaceutical customer relationships. Long-term viability centers on fabricators with backward integration into captive alloy supply and demonstrated cleanroom validation experience. Monitor ECHA REACH regulation enforcement restricting hexavalent chromium surface treatments as a signal for passivation-only finishing capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Alloy Supply | Secures 316L-grade material test report documentation for ISO 9001 pharmaceutical compliance. |
| Laser-Cutting Capacity Expansion | Enables Data Matrix barcode integration for FDA Unique Device Identification traceability mandates. |
| Regional Distribution Partnership | Captures Gulf Coast refinery procurement through established oil and gas supplier qualification pathways. |
| Technology Licensing Agreement | Accelerates sub-millimeter engraving capability without concentrated German and US laser equipment capex. |
| Passivation-Only Finishing Transition | Aligns with ECHA REACH restrictions on hexavalent chromium for European chemical processing buyers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant engineers, maintenance directors at pharmaceutical and chemical processing facilities, OEM procurement teams, and aftermarket service heads; and secondary validation through customs and trade data, SEC 10-K filings of publicly traded industrial suppliers, OSHA and FDA regulatory filings, and industry association reports from chemical and pharmaceutical manufacturing groups. Bottom-up demand modeling triangulated against top-down market sizing across product type, manufacturing process, end user industry, and distribution channel dimensions.
Across the analysis window, the forecasting framework applied segment-specific growth coefficients derived from regulatory compliance intensity and replacement cycle dynamics. Modeled dimensions included valve tag grade tier, end-use industry regulatory stringency, engraving precision requirements, and regional pharmaceutical manufacturing expansion patterns. CAGRs were computed from installed base depreciation schedules and compliance-driven procurement inflection points, with nickel price volatility and laser equipment utilization rates incorporated as sensitivity variables.
Material uncertainties — nickel price spikes, ECHA substance evaluation outcomes, and CDSCO enforcement timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation consistency and pharmaceutical capital expenditure continuity. Recalibration cycles align with material shifts in FDA guidance documents and European chemical regulation enforcement actions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Steam Trap Market
Valves
United States Valves Market
Valves
Europe Butterfly Valve Market
Valves
Mobile Hydraulic Valves Market
Valves
Gate Impellers Market
Valves
Global Globe Valve Market
Valves
GCC and MENA Valves Market
Valves
Axial and Radial Seals Market
Valves
Pup Joint Market
Valves
Curb Valves Market
Valves
Sandblast Valves Market
Valves
Air Heated Vaporizer Market
Valves
Wind Energy Fasteners Market
Valves
Europe Industrial Valves Market
Valves
Valve Seat Inserts Market
Valves
Pipeline Pigging Equipment Market