
 Global Compression Packing Market | 2026-2036
Global Compression Packing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compression Packing Market Analysis
Graphite compression packing is rebalancing product economics as operators replace traditional asbestos and rubber formulations in high-temperature steam applications. Garlock leverages in-house carbon fiber braiding capabilities to anchor North American refinery contracts. EagleBurgmann sustains German engineering-intensive positioning through API 682-qualified pusher seal and packing combinations. John Crane dominates aftermarket channel control via its global service network and OEM-installed base.
Compression packing consists of braided, woven, or molded sealing elements engineered from PTFE, graphite, aramid, or synthetic fibers, typically rated for temperatures exceeding 500°C and pressures above 200 bar in rotating or reciprocating equipment. Its primary purpose is to constrain fluid leakage along pump shafts, valve stems, and compressor rods while permitting controlled wear and axial adjustment. PTFE-based formulations lead material value pools due to chemical inertness and low friction coefficients in pharmaceutical and food-grade pumps. Graphite segments capture premium pricing in power generation boiler feedwater and superheated steam valves where thermal conductivity prevents localized burnout. Fiber-reinforced rubber compounds occupy cost-sensitive automotive water pump and HVAC compressor niches where duty cycles moderate.
The EPA enforces methane leakage limits under New Source Performance Standards that compel oil and gas operators to specify low-emission packing sets in fugitive-prone valve and pump installations. The EU REACH regulation restricts perfluorinated substance formulations, redirecting European chemical processing demand toward compliant graphite and bio-based fiber alternatives. The API 622 and API 641 test protocols define emissions performance benchmarks that determine qualification for refinery and upstream project procurement lists. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions and align R&D roadmaps with third-party Type Approval certifications before specification lock-in at major engineering contractors.
Market Dynamics
EPA methane rules and EU F-Gas restrictions are forcing simultaneous material transitions across refinery, chemical, and power generation installations, compressing specification cycles and elevating qualification costs for packing suppliers.
Growth Catalysts
- EPA New Source Performance Standards:Methane leakage limits mandate low-emission packing sets in upstream valve and pump installations, driving replacement volume across US Gulf Coast petrochemical corridors.
- Graphite thermal conductivity:Power generation operators specify expanded graphite formulations in superheated steam valves to prevent localized burnout, displacing traditional asbestos and rubber compounds.
- LNG export capacity buildouts:Cryogenic and high-pressure wellhead equipment demand in Texas and Louisiana sustains recurring replacement cycles for PTFE and graphite packing.
Market Restraints
- Flake graphite supply concentration:High-purity graphite feedstock depends on Chinese mining and processing operations, exposing converters to export restriction risks and price volatility.
- EU REACH perfluorinated substance restrictions:PTFE formulation compliance costs redirect European chemical processing demand toward alternative materials with inferior performance envelopes.
- Fiber-reinforced rubber substitution:Cost-sensitive automotive water pump and HVAC compressor applications favor molded elastomer seals over braided packing, capping price realization in volume segments.
Strategic Opportunities
- Indian refinery expansion:Reliance Industries and Indian Oil Corporation turnaround programs create specification windows for API 622-qualified packing suppliers establishing local technical service presence.
- Hydrogen infrastructure deployment:High-pressure compression and valve sealing requirements in Germany and Netherlands hydrogen pipeline projects favor graphite-PTFE hybrid formulations rated for embrittlement resistance.
- Bio-based fiber development:EU Green Deal funding accelerates aramid and cellulose-derived alternatives that satisfy REACH compliance while maintaining temperature ratings for food-grade pump applications.
Industry Challenges
- API 641 certification timelines:Third-party emissions testing protocols require 6-12 month qualification periods that delay specification lock-in at major engineering contractors.
- Legacy system integration:Retrofit packing installation in decades-old refinery pump fleets demands custom gland dimensioning and skilled field machining capabilities that concentrate among aging technician pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compression Packing Market |
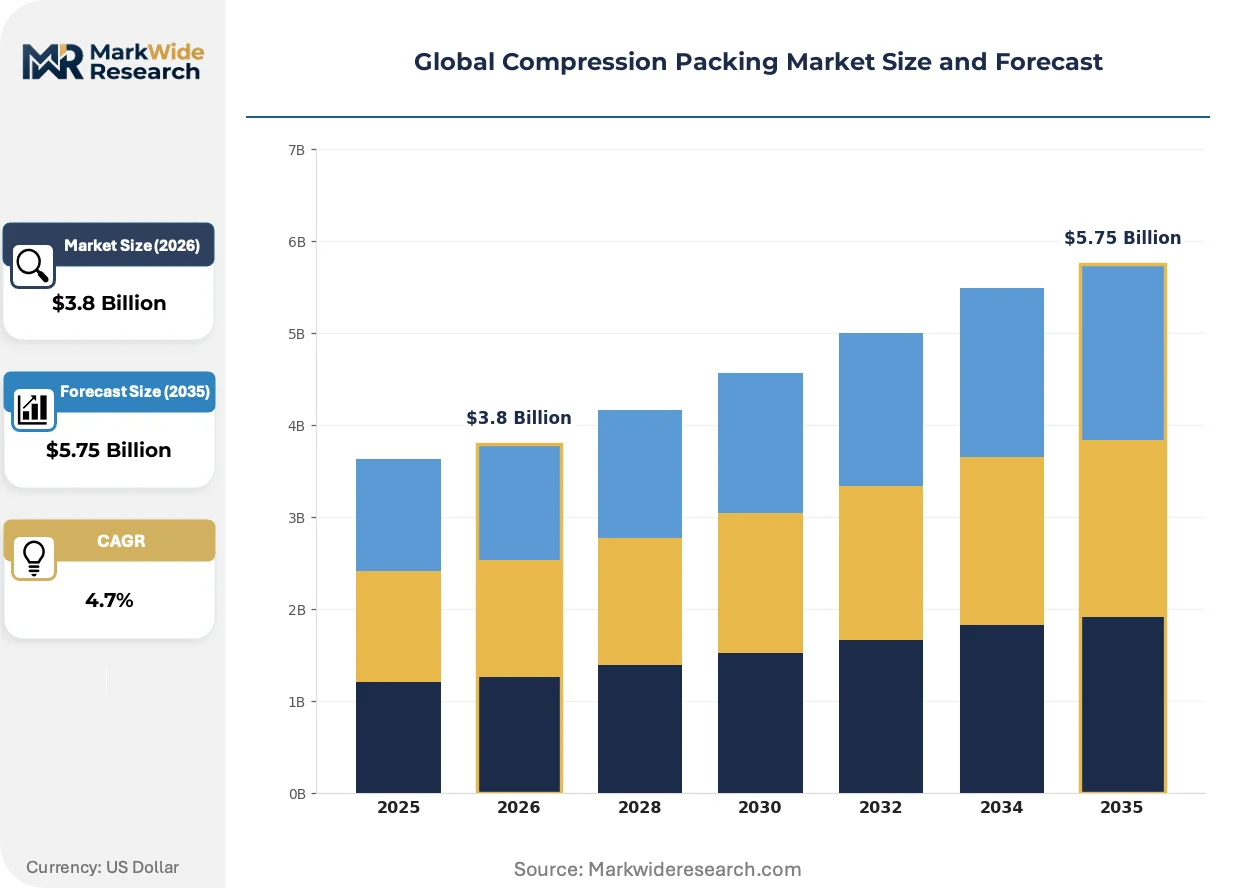
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Rubber, PTFE, Graphite, Fiber End User: Oil & Gas, Automotive, Chemical Processing, Power Generation Type: Circular, Spiral Wound, Sheet, Seal Rings Application: Pumps, Valves, Compressors, Heat Exchangers |
| Companies Covered | Garlock, Chesterton Customseal, EagleBurgmann, Freudenberg Sealing Technologies, John Crane, James Walker Group, Flexitallic, Trelleborg Sealing Solutions, Klinger Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compression Packing Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine performance benchmarks across compression packing categories, with thermal management and emissions containment now co-equal design priorities.
Expanded graphite yarn reinforced with inconel wire mesh is integrating into high-temperature valve stem sealing for combined cycle power plants. Operators in Texas and Florida specify these hybrid constructions for boiler feedwater applications above 350°C. The technology is integrating thermal shock resistance with oxidation stability, compressing the viable temperature envelope for traditional carbon fiber alternatives.
EU F-Gas Regulation amendments tighten leakage thresholds for fluorinated greenhouse gases in stationary equipment, directly affecting PTFE-based packing formulations in chemical processing. The industrial consequence is a qualification race toward graphite and bio-based alternatives that maintain chemical inertness without perfluorinated content. German and Belgian chemical clusters are responding fastest, with engineering contractors now requiring REACH-compliant material declarations before bid submission.
Aftermarket channel consolidation is compressing distributor margins and elevating direct OEM service contracts. End-users in US refining and petrochemical sectors increasingly specify packing replacement through pump manufacturer service agreements rather than independent MRO procurement. This shift concentrates volume with John Crane and Flowserve service networks, marginalizing regional distributors in Texas, Louisiana, and California markets.
Global Compression Packing Market Segmentation
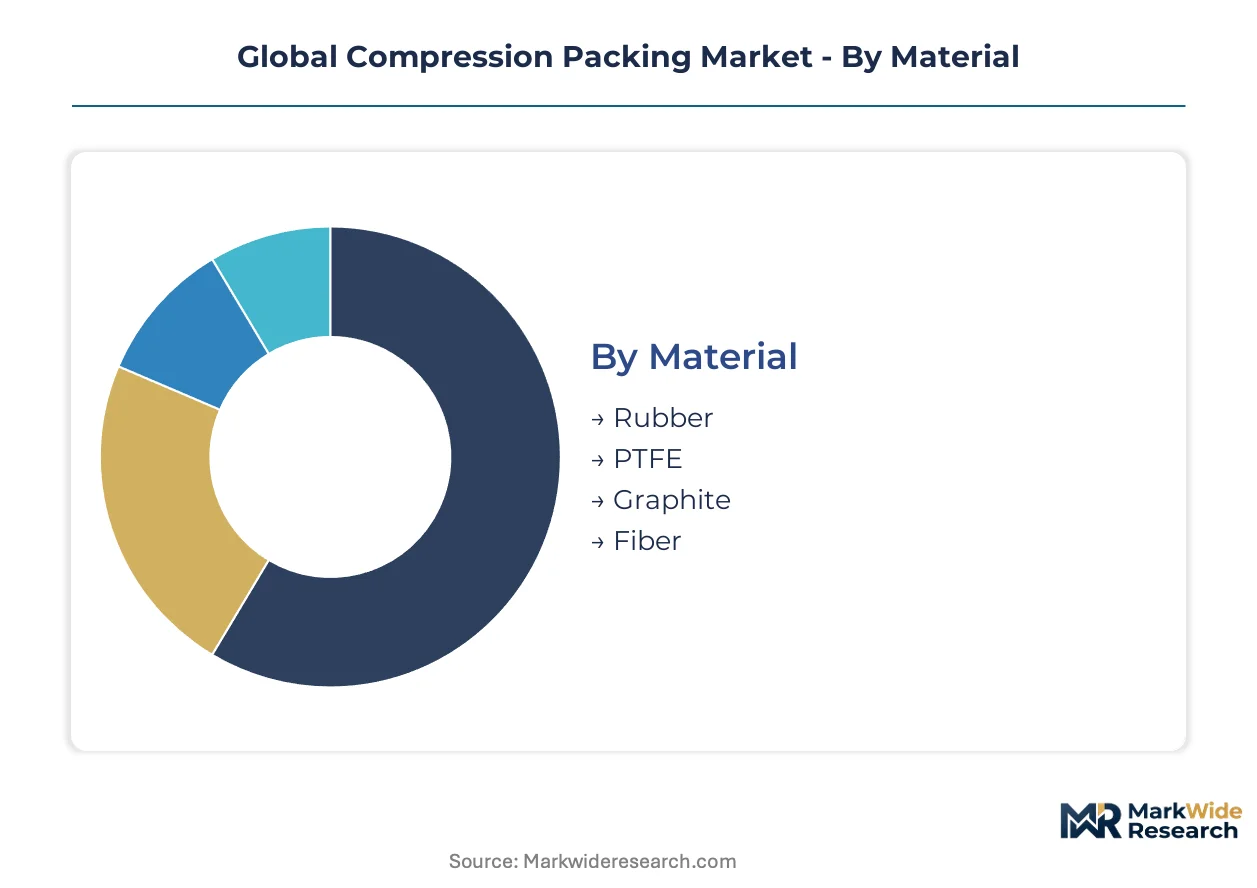
Material composition dictates thermal limits, chemical compatibility, and regulatory compliance pathways across compression packing procurement. End-use specifications cascade from these material choices, with power generation and chemical processing imposing the most stringent emissions and temperature requirements.
Material:
Graphite feedstock concentration in Chinese mining operations shapes converter economics and supply security across all formulation tiers.
- PTFE:Fluoropolymer formulations deliver chemical inertness and friction coefficients below 0.05, qualifying them for pharmaceutical and food-grade pump installations where FDA compliance is mandatory. Demand clusters in Texas and Louisiana LNG export facilities where cryogenic compatibility and methane emission containment under EPA New Source Performance Standards drive specification.
- Graphite:Expanded graphite yarn, often inconel-reinforced, conducts heat away from valve stem interfaces in superheated steam applications exceeding 350°C. Power generation operators in Florida and Texas specify these constructions to prevent localized burnout, displacing legacy asbestos formulations.
- Rubber:Fiber-reinforced compounds serve cost-sensitive automotive water pumps and HVAC compressors with moderate duty cycles and temperature envelopes below 150°C.
- Fiber:Aramid and cellulose-derived alternatives satisfy EU REACH perfluorinated substance restrictions for chemical processing applications requiring bio-based material declarations.
Graphite absorbs the bulk of installed capacity in high-temperature power generation; PTFE is expanding most quickly in LNG and pharmaceutical specification windows.
End User:
Application temperature and pressure thresholds segment customer procurement budgets into three distinct cost tiers.
- Oil & Gas:Upstream wellhead equipment and midstream compression stations specify API 622-qualified packing sets under EPA methane leakage mandates. US Gulf Coast operators in Texas and Louisiana sustain replacement volume through refinery turnaround cycles and LNG export capacity buildouts.
- Power Generation:Combined cycle plants and superheated steam systems demand graphite-PTFE hybrid formulations rated for thermal shock resistance above 350°C. Boiler feedwater valve applications in Florida and Texas represent the most demanding specification environment.
- Chemical Processing:German and Belgian chemical clusters require REACH-compliant material declarations before bid submission, redirecting demand toward graphite and bio-based fiber alternatives.
- Automotive:Water pump and air conditioning compressor applications favor molded elastomer seals over braided packing, capping price realization in high-volume, cost-sensitive segments.
Oil & Gas commands the premium pricing tier; Power Generation is climbing the fastest as coal-to-gas conversion accelerates boiler feedwater valve replacement.
Type:
Manufacturing process complexity and gland geometry compatibility determine margin structures across construction categories.
- Spiral Wound:Metal-reinforced graphite windings accommodate radial thermal expansion in high-pressure valve applications. Power generation and petrochemical facilities in Texas specify these for superheated steam service.
- Circular:Molded ring constructions suit standardized pump stuffing boxes with predictable gland dimensions. Automotive and general industrial applications dominate volume.
- Sheet:Die-cut sheet packing serves heat exchanger flange sealing and low-pressure valve bonnet applications where custom geometry is required.
- Seal Rings:Precision-machined rings integrate with mechanical seal systems in API 682-qualified pump configurations specified by German engineering contractors.
Spiral Wound holds the largest share of high-pressure installed base; Seal Rings are gaining share fastest through OEM pump manufacturer service contract consolidation.
Application:
Equipment duty cycle and accessibility for maintenance reshape replacement frequency and channel strategy across installation types.
- Valves:Stem sealing in fugitive-prone installations faces the strictest EPA methane emissions enforcement. Low-emission packing sets qualify under API 641 test protocols with 6-12 month certification timelines.
- Pumps:Stuffing box configurations in refinery and chemical processing rely on braided PTFE or graphite constructions permitting axial adjustment during operation. Aftermarket channel consolidation favors OEM service networks.
- Compressors:Reciprocating rod packing in high-pressure natural gas service requires materials rated for embrittlement resistance in emerging hydrogen infrastructure projects.
- Heat Exchangers:Gasket and sheet packing applications in lower-pressure, lower-temperature service represent the most price-sensitive specification tier.
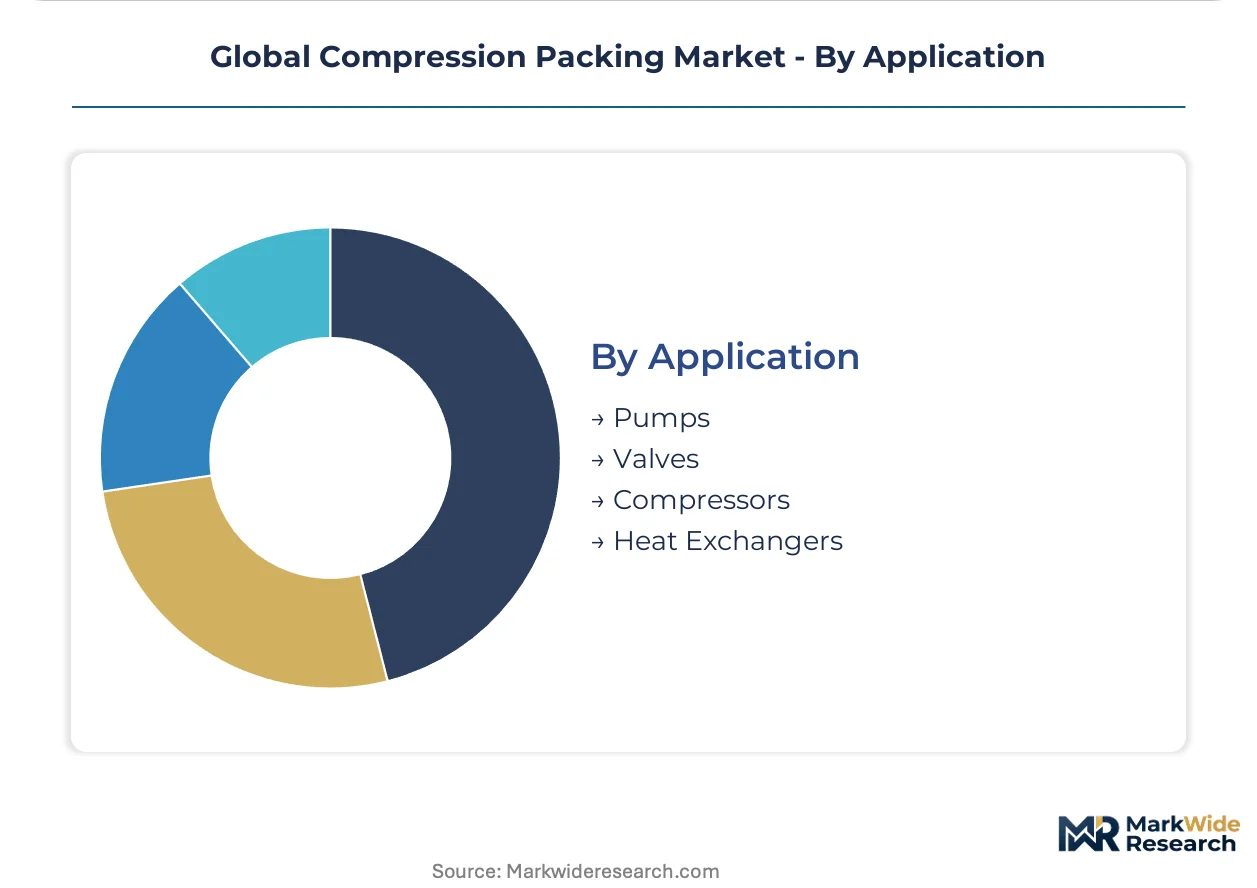
Valves concentrate regulatory compliance investment; Compressors are expanding most quickly through hydrogen pipeline deployment in Germany and the Netherlands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for compression packing concentrates in industrial corridors where refinery turnarounds, LNG export buildouts, and power generation upgrades coincide with tightening emissions regulations. The United States, Germany, China, India, and Saudi Arabia anchor procurement volume across distinct application clusters.
United States
Gulf Coast petrochemical operators in Texas and Louisiana sustain replacement cycles for PTFE and graphite packing through LNG export capacity expansions and refinery maintenance programs. EPA New Source Performance Standards enforce methane leakage limits that mandate low-emission packing sets in upstream valve installations. Houston-area engineering contractors specify API 622-qualified materials for wellhead equipment procurement.
Germany
Industrial valve and pump manufacturers in the Rhine-Ruhr and Bavarian chemical clusters drive specification for REACH-compliant graphite alternatives to perfluorinated formulations. The EU F-Gas Regulation tightens leakage thresholds for fluorinated greenhouse gases in stationary equipment. Hydrogen pipeline projects in the Netherlands-Germany corridor favor graphite-PTFE hybrid constructions rated for embrittlement resistance.
China
Power generation operators in the Yangtze River Delta and Pearl River Delta specify expanded graphite yarn for superheated steam applications above 350°C. The Ministry of Ecology and Environment enforces emissions standards that accelerate material upgrades in coal-to-gas conversion projects. Shandong Province petrochemical complexes import high-purity flake graphite despite domestic mining concentration.
India
Reliance Industries and Indian Oil Corporation turnaround programs in Gujarat and Maharashtra create specification windows for API-qualified packing suppliers. The Bureau of Indian Standards issues pressure equipment regulations that elevate certification requirements for refinery installations. Mumbai-Pune industrial corridor pump manufacturers expand technical service capabilities to capture aftermarket replacement volume.
Saudi Arabia
Aramco-operated facilities in the Eastern Province specify high-pressure wellhead packing for upstream and downstream integration projects. The national petroleum regulator mandates emissions containment standards that align with API 641 test protocols. Jubail Industrial City petrochemical complexes sustain demand for thermal shock-resistant valve stem sealing in superheated steam service.
Global Compression Packing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated sealing system providers commanding premium positions in aftermarket channels while regional fabricators compete on turnaround responsiveness. The vendor base organizes into three tiers: multinational OEM-affiliated service networks, independent material specialists with in-house braiding capabilities, and regional converters dependent on imported yarn feedstock. Consolidation pressures favor backward integration into carbon fiber and graphite yarn production, alongside direct OEM service contract expansion that marginalizes traditional distribution.
Among Germany-based engineering-intensive suppliers, EagleBurgmann occupies a position exemplifying API-qualified pusher seal and packing combination expertise, while Freudenberg Sealing Technologies anchors diversified polymer and composite sealing portfolios. John Crane represents the OEM-integrated service network archetype, with global field presence capturing specification lock-in through pump manufacturer maintenance agreements. These three entities illustrate distinct competitive positioning vectors: specialized qualification depth, materials science breadth, and channel control scale.
| Leading Market Players |
|---|
| Garlock |
| Chesterton Customseal |
| EagleBurgmann |
| Freudenberg Sealing Technologies |
| John Crane |
| James Walker Group |
| Flexitallic |
| Trelleborg Sealing Solutions |
| Klinger Group |
| Others |
Supply Flow & Price Mechanics
Skilled braiding technicians concentrated in Germany's Rhine-Ruhr industrial corridor command wage premiums that propagate through three-tier pricing spreads across API-qualified and non-certified packing tiers. Labor-cost differentials between European engineering centers and Asian converter operations sustain pricing gaps that buyers navigate through specification-grade trade-offs.
Pricing Analysis
Volume-mass segments in automotive water pumps and HVAC compressors run on thin margins, while API 622-qualified graphite and PTFE formulations for refinery valves capture premium realization through certification-linked pricing stratification. Price differentiation hinges on emissions-test qualification status and inconel-reinforcement density in high-temperature constructions. Cost compression in fiber-reinforced rubber tiers is intensifying as molded elastomer seals displace braided alternatives in cost-sensitive applications. Chemical processing operators in Belgium and Germany exhibit the lowest price sensitivity due to REACH compliance mandates, whereas automotive OEM procurement teams drive the hardest volume discounts.
Supply Chain Analysis
Single-source vulnerability sits with Chinese mining and processing operations for high-purity flake graphite feedstock that converters in Japan, Germany, and the United States draw from for expanded yarn production. Raw material dependencies span carbon fiber precursor chemicals, PTFE resin grades, and aramid fiber pulp. Export restriction risks from Chinese graphite processing quotas expose downstream braiding operations to feedstock interruption. Distribution runs through OEM-affiliated service networks that consolidate replacement volume away from independent MRO channels in Texas, Louisiana, and California refining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA methane rules and EU REACH restrictions erect barrier-to-entry moats that favor incumbents with established Type Approval certifications and in-house testing capabilities.
For Market Incumbents: Anchor specification lock-in through backward integration into carbon fiber and graphite yarn production that secures feedstock autonomy against Chinese export volatility. Expand direct service contracts with pump OEMs in the US Gulf Coast to marginalize regional distributor channels. API 641 certification investment represents the critical defensive lever against low-cost Asian converters attempting refinery qualification. For New Entrants and Emerging Players: EU F-Gas Regulation amendments in Germany and Belgium open a window for REACH-compliant bio-based fiber formulations that bypass perfluorinated substance restrictions. Target Indian refinery turnaround programs in Gujarat and Maharashtra where Reliance Industries and Indian Oil Corporation procurement cycles lack established local technical service depth. A joint-venture braiding facility with domestic carbon fiber suppliers offers the fastest qualification path. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing captive graphite yarn production and API 622 test protocols given consolidation pressure from OEM service network expansion. Long-term viability favors targets with hydrogen infrastructure exposure in the Netherlands-Germany corridor. The signal to watch is Bureau of Indian Standards pressure equipment regulation enforcement that elevates certification requirements and concentrates share with qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Yarn | Captive feedstock supply insulates converters from Chinese export quota volatility. |
| API 641 Certification Investment | Third-party emissions qualification unlocks refinery procurement lists at engineering contractors. |
| OEM Service Contract Expansion | Direct pump manufacturer agreements concentrate replacement volume away from MRO distributors. |
| Bio-Based Fiber R&D Program | EU Green Deal funding accelerates REACH-compliant alternatives to PTFE formulations. |
| Hydrogen Infrastructure Qualification | Graphite-PTFE hybrid testing for embrittlement resistance captures Netherlands-Germany pipeline deployment. |
Methodological Framework
Multi-period observation of refinery turnaround cycles, LNG export capacity buildouts, and emissions regulation enforcement timelines anchored the trend analysis, supplemented by interviews with maintenance directors at US Gulf Coast petrochemical facilities, procurement leads at German chemical clusters, technical R&D directors at braiding operations, and aftermarket service heads at pump OEMs. Secondary validation drew from EPA New Source Performance Standards filings, EU ECHA REACH substance restriction updates, API 622 and API 641 test protocol documentation, and customs trade data for graphite feedstock flows. Bottom-up segment sizing triangulated against top-down industrial equipment installed base estimates.
The input-output matrix framed demand as a function of replacement frequency by equipment type, material specification grade, and regulatory compliance tier across the projection horizon. Segmentation dimensions modeled include material composition, end-use industry, construction type, and application equipment category. CAGRs were derived from regression analysis of historical replacement volumes against industrial capacity expansion and regulatory phase-in schedules. Hydrogen infrastructure deployment timelines and coal-to-gas conversion acceleration in Chinese power generation served as scenario-weighted forecast inputs.
Caveats apply where Chinese graphite export restrictions, EU F-Gas Regulation amendments, or API certification timeline delays could materially shift the outlook for material substitution rates and supplier qualification windows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Valves in Oil and Gas Industry Market
Valves
Middle East and Africa Machined Seals Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Lined Valves Market
Valves
Electronic Expansion Valves Market
Valves
Penstock Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Fluid Transfer Solutions Market
Valves
Motorized Valves Market
Valves
Harmonic Dampers Market
Valves
Global Valve Positioners Market
Valves
Reciprocating Compressor Components Market
Valves
Emergency Venting System Market
Valves
Gas Equipment Market
Valves
Valve Seat Inserts Market
Valves
Deluge Valve Market