
 Automotive Evaporators and Blowers Market | 2026-2036
Automotive Evaporators and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Evaporators and Blowers Market Insights
Multi-source procurement for thermal management subassemblies is hardening across Tier-1 supplier networks. Denso Corporation leverages its captive semiconductor capacity to secure blower motor controller supply. Valeo anchors its position through integrated evaporator-blower module design for European OEM platforms. Hanon Systems competes aggressively in under-dash installation configurations for Korean and North American vehicle programs.
Automotive evaporators and blowers comprise heat transfer surfaces and forced-air distribution mechanisms engineered to refrigerant pressures between 15 and 35 bar, with blower motors typically rated 50–400W depending on cabin volume and climate zone. The assembly's primary purpose is to extract cabin heat via refrigerant phase change and distribute conditioned air through ducted plenums. Evaporator demand concentrates in OEM channels where platform standardization locks in multi-year supply agreements, while aftermarket providers capture margin in replacement cycles for aging vehicle parcs. Electrical blower technology leads new platform adoption as 48V and high-voltage architectures displace mechanical drive systems.
EPA tailpipe and fuel economy rules, NHTSA safety standards for HVAC system accessibility, and EU F-Gas Regulation on refrigerant global warming potential collectively shape product design thresholds and material selection. China's MIIT new energy vehicle mandates add a parallel compliance layer for domestic and export-bound suppliers. Stakeholders must monitor refrigerant chemistry transitions and voltage architecture shifts to align R&D roadmaps with pending certification requirements.
Market Dynamics
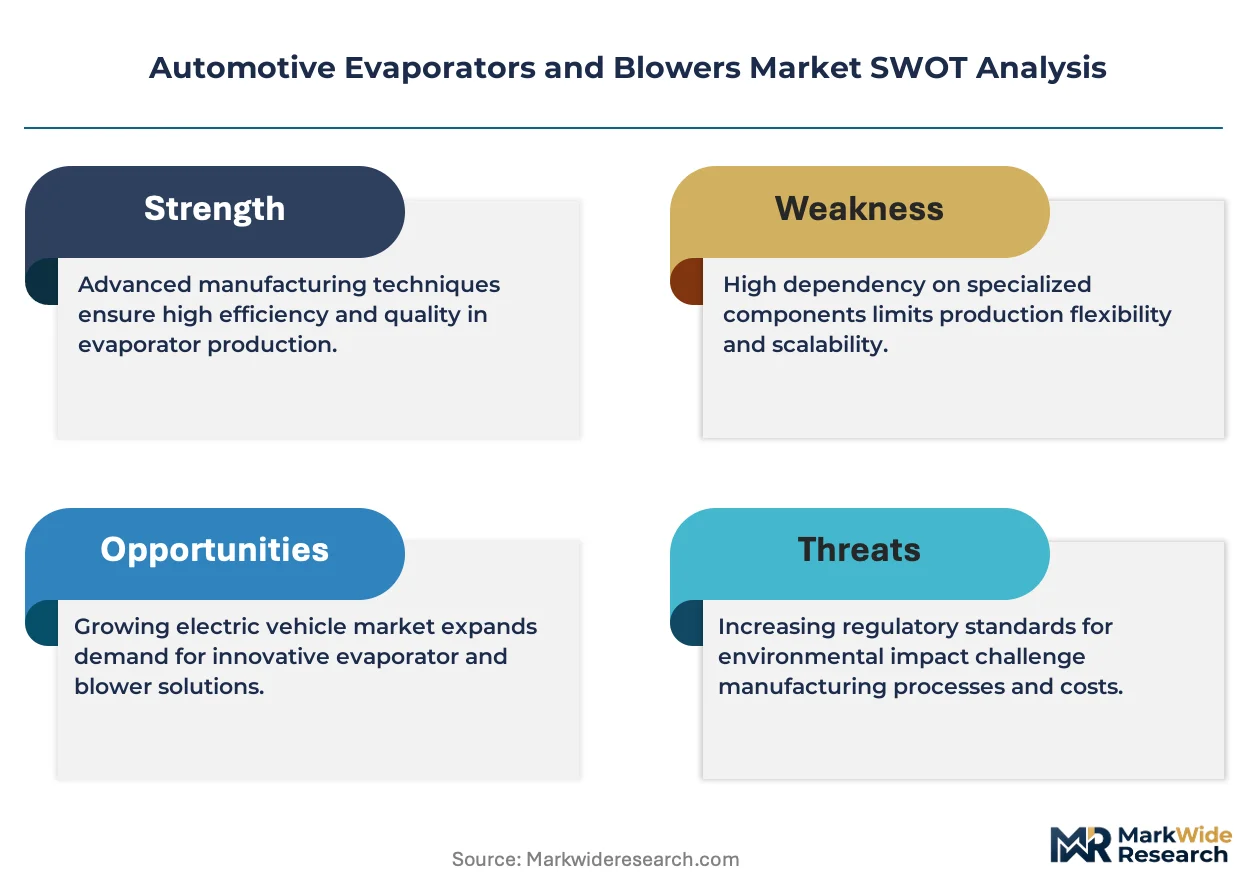
Platform electrification is compressing HVAC packaging envelopes while simultaneously elevating thermal load management complexity. Automakers now specify evaporator-blower assemblies that must serve battery cooling loops alongside cabin conditioning, forcing redesigns of refrigerant circuitry and motor efficiency targets.
Growth Catalysts
- MIIT new energy vehicle mandates:China's production quotas for battery-electric and plug-in hybrid platforms require dedicated cabin and battery thermal management architectures. OEMs source compact, high-efficiency blower-evaporator modules to meet dual-zone cooling demands within constrained front-compartment space.
- 48V electrical architecture proliferation:Mild-hybrid vehicle programs across European and North American lineups replace belt-driven compressor and blower systems with electrified variants. This transition expands addressable volume for brushless DC blower motors and integrated power electronics.
- Refrigerant chemistry transition:The EU F-Gas Regulation and parallel EPA Significant New Alternatives Policy drive adoption of lower-global-warming-potential refrigerants. Evaporator designs must accommodate R-1234yf and emerging R-744 (CO2) pressure regimes, creating upgrade cycles for legacy aluminum fin-and-tube configurations.
Market Restraints
- Aluminum price volatility:Evaporator cores rely on microchannel aluminum extrusions and brazed assemblies. LME aluminum price swings above historical baselines compress margin for suppliers locked into annual price-down agreements with OEMs.
- Semiconductor dependency for motor control:Brushless DC blower systems require dedicated gate drivers and MOSFET arrays. Foundry capacity concentration in Taiwan and South Korea exposes Tier-1 suppliers to allocation risk during automotive chip shortage recurrence.
- Refrigerant handling certification barriers:EPA Section 608 technician certification requirements and EU F-Gas personnel qualification mandates limit service channel expansion for aftermarket evaporator replacement, constraining independent workshop participation.
Strategic Opportunities
- India passenger vehicle HVAC upgrade:Domestic OEMs and joint ventures in India currently specify lower-cost mechanically actuated blower systems. Electrification of entry-level vehicle platforms creates whitespace for 12V and 48V blower module suppliers to displace legacy architectures.
- Refrigerant leak detection integration:EU F-Gas mandatory leak checking protocols for systems above specific charge thresholds incentivize evaporator designs with embedded sensor ports. Suppliers offering pre-integrated refrigerant monitoring interfaces capture specification preference from compliance-focused OEMs.
- Service contract unbundling:Fleet operators and mobility-as-a-service providers are separating HVAC maintenance from powertrain service agreements. Independent thermal management specialists gain channel access through outcome-based cabin comfort uptime contracts.
Industry Challenges
- Multi-physics simulation talent scarcity:Evaporator-blower module development now requires coupled thermal, fluid, and acoustic modeling. OEM engineering teams and supplier R&D groups compete for limited pools of computational fluid dynamics specialists with automotive HVAC experience.
- Dual refrigerant platform validation:Suppliers supporting both R-1234yf and R-744 architectures must duplicate pressure-cycle testing, corrosion validation, and burst-pressure certification. Parallel qualification timelines strain capital equipment utilization and engineering bandwidth.
- Legacy 12V integration friction:Electrified blower motors with integrated controllers must communicate with aging body control modules via LIN or PWM protocols. Backward compatibility testing for vehicle programs spanning multiple electrical architecture generations extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Evaporators and Blowers Market |
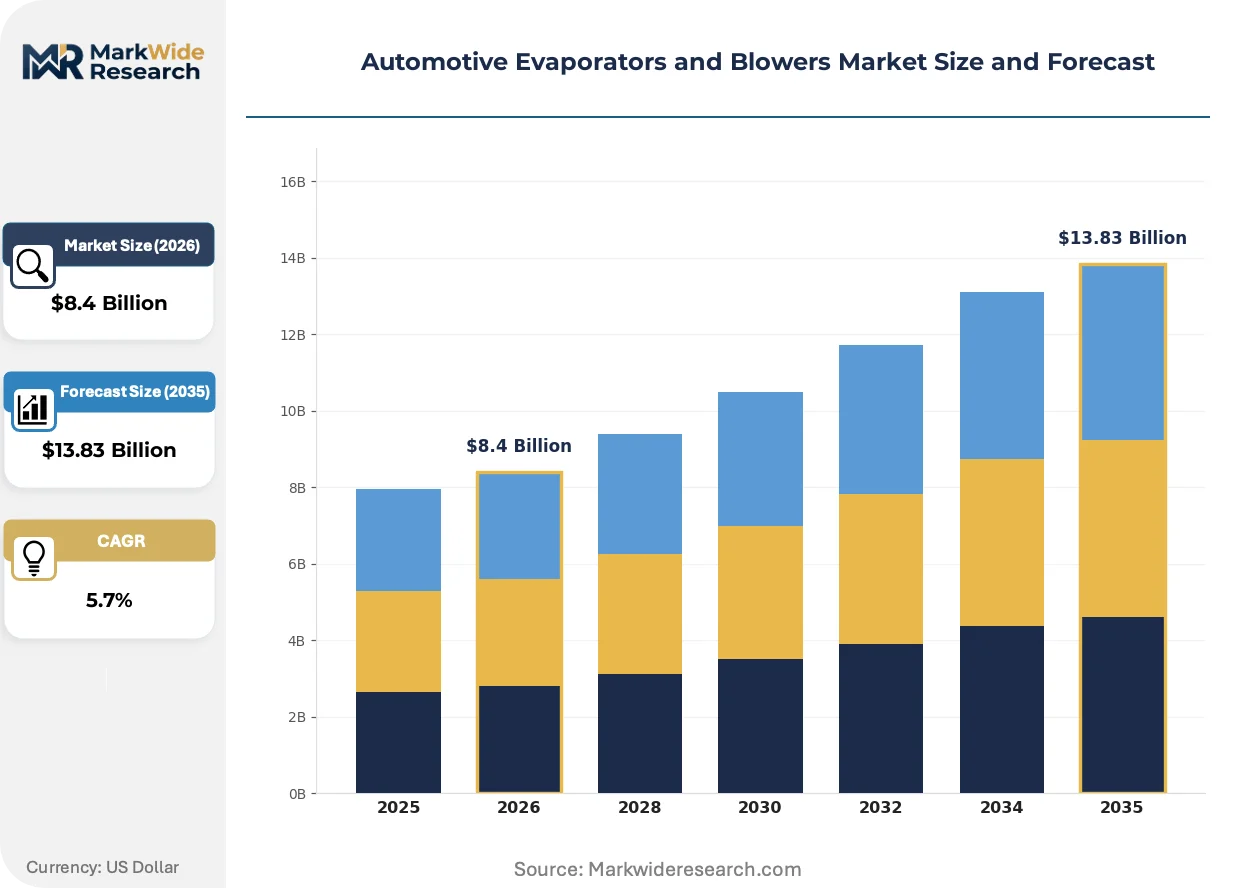
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporators, Blowers, Heat Exchangers, Condensers End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Mechanical, Electrical, Hybrid, Pneumatic Installation Type: Roof-Mounted, Under-Dash, Front-Mounted, Rear-Mounted |
| Companies Covered | Denso Corporation, Valeo, MAHLE GmbH, Hanon Systems, Sanden Holdings Corporation, ebm-papst, Nidec Corporation, Brose Fahrzeugteile, Continental Automotive GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Evaporators and Blowers Market Trends and Innovations
Refrigerant pressure boundaries and voltage architecture choices are now co-determining evaporator and blower design specifications. Suppliers must engineer for simultaneous compliance with divergent regulatory and electrification pathways.
Microchannel aluminum evaporator cores with integrated refrigerant distribution headers are modularizing across electric vehicle platforms. Packagers specify these units for under-dash, rear-console, and battery-cooling loop positions with minimal design variation. The approach compresses tooling investment per vehicle program while enabling volume scaling across multiple OEM customers. Platform engineering teams at German and Korean automakers are accelerating this specification pattern.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is forcing evaporator redesigns for higher-pressure CO2 transcritical cycles. Equipment suppliers must qualify new aluminum alloys and brazing processes for 100+ bar operating regimes. European HVAC module integrators are most exposed, with R-744-compatible evaporator volumes projected to dominate their 2030 production mix.
Fleet procurement teams are consolidating thermal management subsystem sourcing under single-supplier responsibility contracts. Direct OEM-to-module-maker agreements are displacing multi-Tier sourcing for blower and evaporator combinations. North American commercial vehicle and European premium passenger car segments exhibit this pattern most prominently, with procurement specifications now bundling performance warranties across the integrated assembly.
Automotive Evaporators and Blowers Market Segmentation
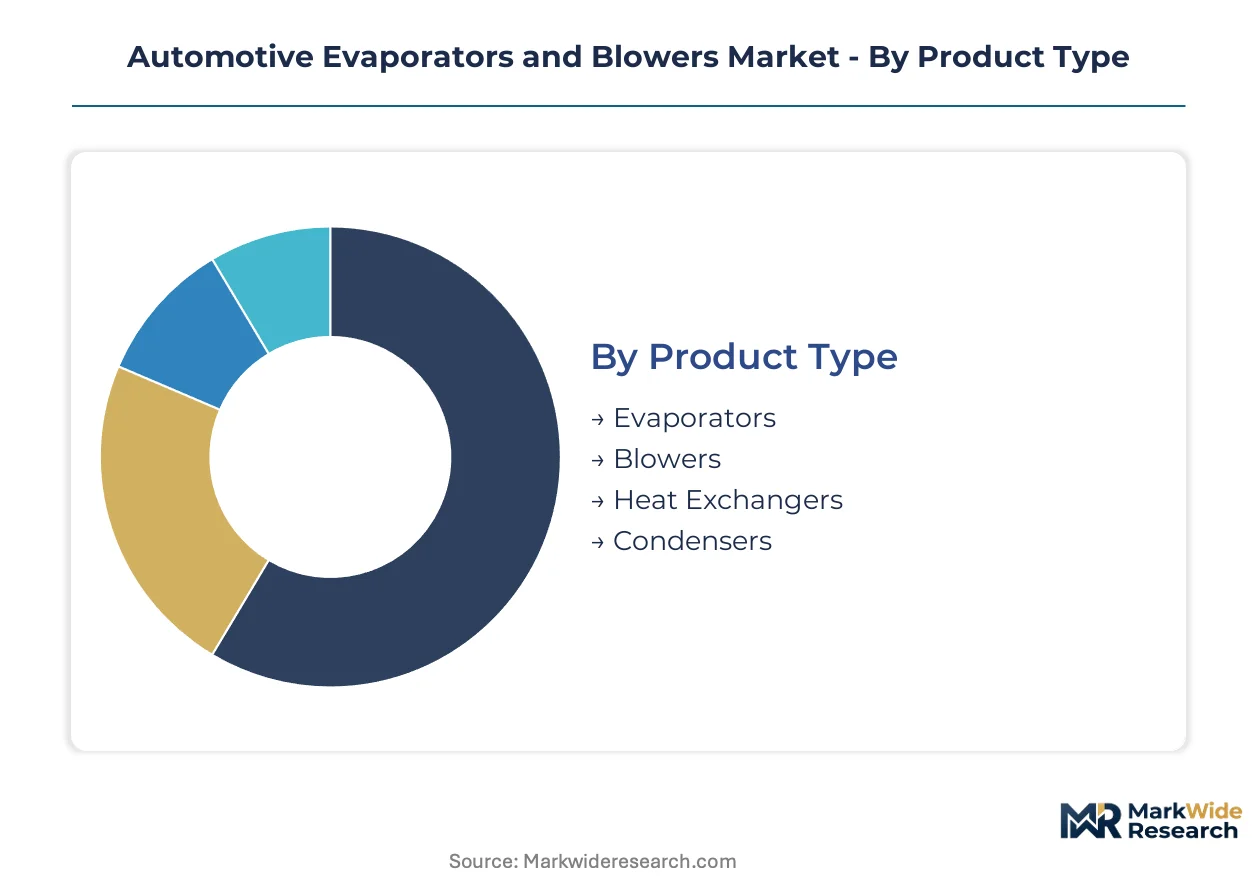
Segmentation in automotive evaporators and blowers reveals how certification burdens, electrification roadmaps, and platform packaging constraints fragment procurement specifications across vehicle programs. Suppliers must align product architectures with divergent regulatory and thermal load requirements.
Product Type:
EPA Section 608 certification governs evaporator replacement and refrigerant handling, while NHTSA FMVSS 103 visibility standards affect blower placement near windshields. EU F-Gas Regulation mandates leak detection integration for systems above specific refrigerant charge thresholds.
- Evaporators:Aluminum microchannel cores with brazed headers facilitate refrigerant phase change at 15–35 bar operating pressures. Demand concentrates in German and Korean OEM platforms where battery-cooling loop integration requires compact multi-zone configurations. Dual refrigerant qualification for R-1234yf and R-744 strains supplier validation bandwidth.
- Blowers:Brushless DC motors rated 50–400W displace mechanical drive systems under 48V and high-voltage architectures. Chinese and North American vehicle programs specify these for under-dash and rear-console positions where cabin volume and climate zone dictate airflow requirements. Semiconductor dependency for motor controllers exposes supply chains to foundry allocation risk.
- Heat Exchangers:Plate-and-fin configurations serve secondary thermal loops in battery thermal management.
- Condensers:Aluminum tube-and-fin assemblies reject heat to ambient air in front-compartment installations.
Leading the category by volume: Evaporators. Growing fastest: Blowers.
End User:
Cost tier stratification separates captive in-house production from outsourced module procurement, with warranty liability terms varying sharply across contract structures.
- OEMs:Platform standardization locks in multi-year supply agreements with dedicated thermal management module specifications. German and US automakers consolidate sourcing under single-supplier responsibility contracts bundling evaporator-blower performance warranties.
- Aftermarket Providers:Independent distributors capture replacement cycles for aging vehicle parcs in North America and Europe. EPA Section 608 technician certification requirements and EU F-Gas personnel qualification mandates constrain service channel expansion.
- Vehicle Assemblers:Contract manufacturers rely on Tier-1 module supply for HVAC subsystem integration.
- Tier-1 Suppliers:Thermal management specialists integrate blower-evaporator combinations for multiple OEM customers.
Dominant by contract value: OEMs. Expanding most quickly: Aftermarket Providers facing refrigerant handling compliance barriers.
Technology:
Application context determines voltage architecture compatibility, with powertrain electrification tier dictating motor and controller specifications.
- Mechanical:Belt-driven compressor linkages persist in entry-level internal combustion platforms. Indian domestic OEMs specify these for cost-sensitive vehicle programs where 12V electrical budgets constrain electrification.
- Electrical:Integrated brushless DC motors with LIN and PWM protocol compatibility serve 48V mild-hybrid and battery-electric architectures. European and North American lineups drive specification volume as electrified blower motors displace legacy mechanical systems.
- Hybrid:Dual-mode systems switch between mechanical and electrical drive depending on powertrain state.
- Pneumatic:Compressed air actuation serves specialized commercial vehicle applications with existing air brake infrastructure.
Highest shipment volume: Electrical. Steepest expansion trajectory: Hybrid configurations bridging architecture generations.
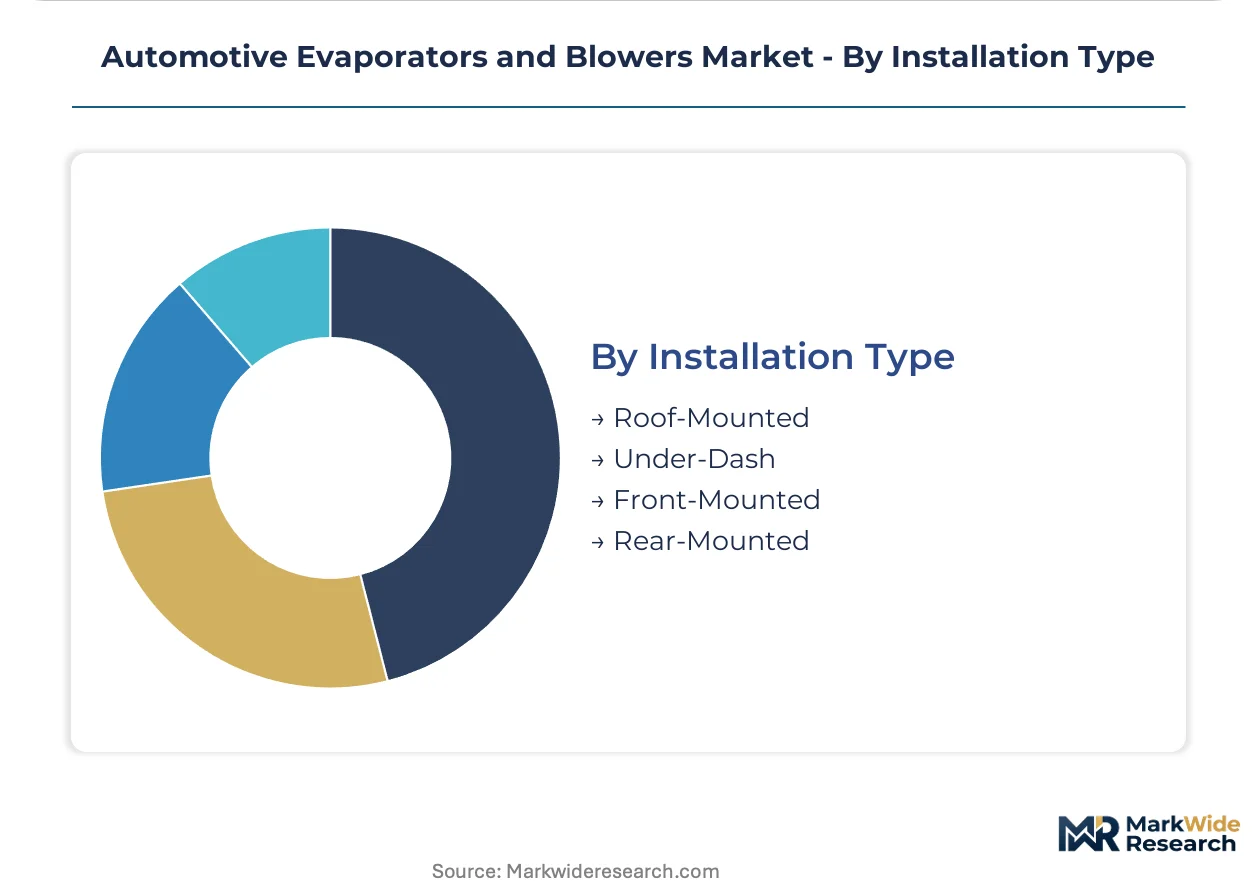
Installation Type:
Customer type segmentation separates passenger vehicle packaging constraints from commercial vehicle cabin configurations, with fleet procurement patterns driving standardization.
- Under-Dash:Compact blower-evaporator modules fit constrained front-compartment envelopes in battery-electric platforms. Korean and North American vehicle programs specify these configurations where dual-zone cooling must coexist with reduced packaging space.
- Front-Mounted:Engine-bay evaporator and condenser placements serve conventional internal combustion thermal management loops. Chinese OEM platforms concentrate demand here for domestic market vehicle programs.
- Roof-Mounted:Overhead HVAC units serve commercial vehicle and bus applications with extended cabin lengths.
- Rear-Mounted:Auxiliary cooling modules support multi-zone passenger car configurations and battery thermal management.
Primary volume position: Under-Dash. Gaining share fastest: Rear-Mounted for battery cooling integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum microchannel extrusion capacity in Guangdong Province anchors Asia-Pacific supply chains for evaporator cores. German engineering clusters around Stuttgart and Munich concentrate blower motor controller development. Detroit-area thermal management R&D facilities shape North American platform specifications.
China
MIIT new energy vehicle production quotas drive dual-zone evaporator-blower module procurement for battery-electric platforms. The F-Gas Regulation's refrigerant phasedown pressures domestic suppliers toward R-744-compatible designs. Shenzhen and Shanghai engineering centers validate compact under-dash configurations for export-bound OEM programs.
Germany
KBA type-approval requirements for HVAC system accessibility influence blower placement standards across European lineups. The EU Green Deal's embedded carbon rules reshape aluminum sourcing for evaporator cores. Stuttgart-area module integrators consolidate single-supplier responsibility contracts with premium passenger car OEMs.
United States
NHTSA FMVSS 103 visibility standards constrain blower motor packaging near windshields in light-truck platforms. EPA Section 608 technician certification limits aftermarket service channel expansion for evaporator replacement. Michigan-based engineering teams specify 48V brushless DC systems for domestic electrified vehicle programs.
Japan
METI carbon neutrality roadmaps accelerate R-1234yf evaporator adoption in domestic vehicle lineups. JIS standards for refrigerant pressure containment shape validation protocols for microchannel aluminum assemblies. Nagoya-area suppliers coordinate blower motor controller development with captive semiconductor fabrication.
South Korea
Domestic OEM platform electrification elevates demand for compact rear-mounted blower modules serving battery thermal loops. MFDS-equivalent refrigerant handling regulations align technician training with EU F-Gas personnel qualification frameworks. Gyeonggi Province manufacturing clusters specialize in under-dash installation configurations for North American export programs.
Automotive Evaporators and Blowers Market Competitive Landscape
Global majors compete with regional champions across thermal management module integration and refrigerant system architecture. The vendor base stratifies between full-line HVAC module integrators, component specialists in motor control or heat exchange, and captive in-house production at volume OEMs. Three archetypes dominate: integrated module suppliers bundling evaporator-blower combinations, discrete component manufacturers supplying subassemblies to Tier-1 integrators, and semiconductor-capable motor controller developers. Competitive moves center on single-supplier responsibility contract capture and backward integration into aluminum microchannel extrusion capacity.
Among Asia-Pacific-based module integrators, Denso Corporation and Hanon Systems occupy positions spanning evaporator core fabrication through blower motor controller integration. Valeo exemplifies the European integrated-module archetype with evaporator-blower combinations engineered for OEM platform standardization. These three anchors represent divergent geographic emphases—Japanese-Korean engineering concentration versus European premium passenger car specification leadership—while sharing strategic exposure to refrigerant chemistry transitions and voltage architecture proliferation.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo |
| MAHLE GmbH |
| Hanon Systems |
| Sanden Holdings Corporation |
| ebm-papst |
| Nidec Corporation |
| Brose Fahrzeugteile |
| Continental Automotive GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor fabrication at Denso Corporation and Valeo's integrated evaporator-blower module production anchor pricing power through in-house controller supply and reduced Tier-2 dependency. This backward integration insulates leading suppliers from aluminum price volatility while locking OEM customers into multi-year performance warranty contracts that bundle hardware and thermal management uptime guarantees.
Pricing Analysis
Performance warranty bundling dominates contract structures, with single-supplier responsibility agreements covering evaporator-blower combinations against thermal system failure rates. Price differentiation separates premium R-744-compatible modules from standard R-1234yf configurations, with certification grade for EU F-Gas leak detection integration adding tier separation. Cost compression in entry-level 12V blower systems is intensifying because Indian domestic OEMs specify mechanically actuated alternatives. Fleet procurement teams show least price sensitivity, prioritizing cabin comfort uptime over per-unit hardware cost.
Supply Chain Analysis
Reverse logistics for remanufactured blower motors and refrigerant recovery flows concentrate servicing revenue at authorized dealer networks, constraining independent aftermarket participation. Microchannel aluminum extrusion capacity clusters in China, Germany, and the United States, with brazed assembly operations feeding Tier-1 module integrators. Semiconductor gate drivers and MOSFET arrays draw from Taiwan and South Korea foundries, exposing brushless DC blower production to allocation risk. Distribution runs through OEM captive channels and contracted thermal management specialists rather than open aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification and dual refrigerant qualification burdens are forcing consolidation among subscale suppliers lacking captive aluminum extrusion or semiconductor controller capacity. Market incumbents with integrated module capabilities will capture displaced volume as weaker players exit.
For Market Incumbents: Hedge refrigerant transition exposure by qualifying parallel R-1234yf and R-744 evaporator architectures now, before European OEMs mandate CO2 transcritical systems. Secure captive aluminum microchannel extrusion capacity in Guangdong Province or Stuttgart engineering clusters to defend margin position against LME price volatility. Denso Corporation's semiconductor fabrication model demonstrates the defensive value of controller supply chain control.
For New Entrants and Emerging Players: Begin with India's electrifying entry-level passenger vehicle segment, where 12V and 48V blower module demand is displacing mechanically actuated legacy systems. Target under-dash installation configurations for Korean OEM export programs, where compact packaging requirements exceed incumbent capacity. Pursue fleet service contract unbundling as the go-to-market angle, offering outcome-based cabin comfort uptime agreements that separate HVAC maintenance from powertrain service.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to full-line HVAC module integrators seeking aluminum extrusion capacity and refrigerant system expertise. Long-term viability favors suppliers with validated dual refrigerant platforms and captive semiconductor controller development. Monitor EU F-Gas Regulation phasedown enforcement velocity and MIIT new energy vehicle production quota achievement rates as inflection indicators for R-744 evaporator demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Refrigerant Platform Qualification | Validates evaporator designs for both R-1234yf and R-744 pressure regimes ahead of EU F-Gas mandates. |
| Captive Aluminum Microchannel Extrusion | Secures upstream control over evaporator core fabrication against LME price volatility and supply disruption. |
| Integrated Blower Motor Controller Development | Reduces semiconductor foundry dependency through in-house gate driver and MOSFET array design. |
| Single-Supplier Responsibility Contract Capture | Bundles evaporator-blower performance warranties to displace multi-Tier sourcing at German and US OEMs. |
| Refrigerant Leak Detection Sensor Integration | Pre-integrates monitoring interfaces to meet EU F-Gas mandatory checking protocols above charge thresholds. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and thermal management R&D directors. EPA Section 608 certification databases, EU F-Gas Regulation implementation reports, and MIIT new energy vehicle production statistics provided validation anchors. Bottom-up vehicle program analysis and top-down thermal module demand estimation were cross-checked for triangulation consistency.
Granularity-level modeling tracked evaporator and blower demand by vehicle class, propulsion architecture, refrigerant chemistry, and regional production cluster across the projection horizon. CAGRs were derived from production volume forecasts weighted by content-per-vehicle thermal management intensity. Voltage architecture proliferation curves and refrigerant transition timelines served as scenario inputs for sensitivity testing.
Aluminum price volatility, semiconductor allocation recurrence, and refrigerant chemistry transition delays are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about MIIT quota enforcement and EU F-Gas phasedown adherence. Practitioners should monitor LME aluminum futures, automotive foundry capacity utilization, and KBA type-approval timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market