
 Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market Insights
Buyer concentration among Chinese original equipment manufacturers is repositioning procurement leverage toward vertically integrated cell suppliers. CATL leverages its Ningxia production base to dominate LFP supply for domestic automakers. BYD Company Limited anchors its position through in-house cathode and cell production. LG Energy Solution Ltd competes by sustaining high-nickel NMC output for premium export-oriented EV platforms.
Asia-Pacific lithium-ion battery for electric vehicle denotes rechargeable electrochemical cells using lithium-based intercalation compounds with nominal voltages of 3.2–3.7 V and energy densities exceeding 250 Wh/kg at the pack level, manufactured through electrode coating, calendering, and electrolyte filling processes for traction power in electrified road transport. Prismatic formats lead in passenger vehicle integration due to space efficiency and thermal management compatibility, while pouch designs occupy niche positions in premium European-export platforms where weight minimization commands priority. LFP chemistry dominates commercial vehicle and two-wheeler segments where cost-per-cycle metrics override energy density requirements, whereas NMC retains margin concentration in long-range passenger applications.
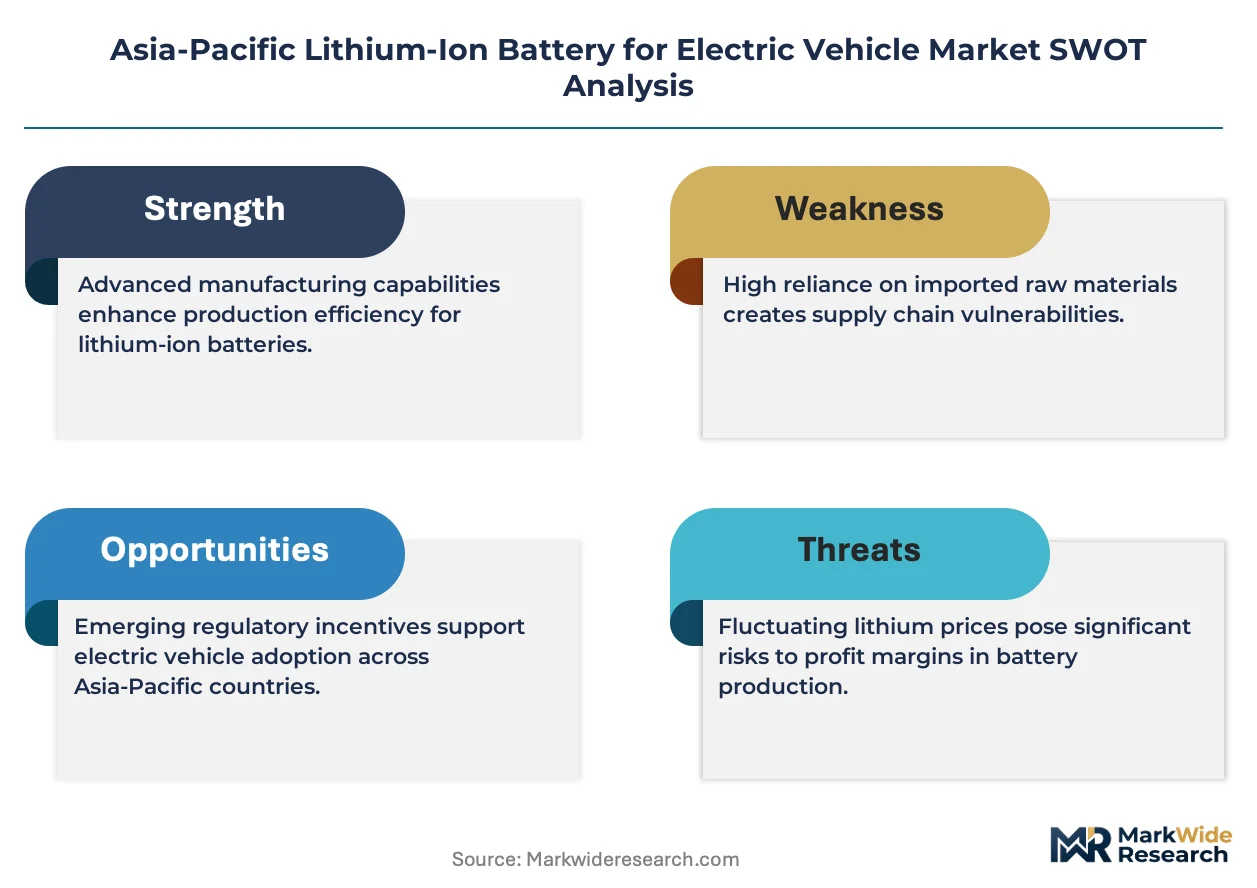
China's MIIT enforces GB/T battery safety and recycling standards that mandate cell-level traceability, while Japan's METI coordinates national solid-state battery roadmaps through public-private consortia. South Korea's MFDS and KATS frameworks govern cell quality certification for domestic OEM supply eligibility. Stakeholders must monitor divergence between China's LFP-centric standardization path and South Korea-Japan high-nickel technology commitments when allocating R&D and capacity investments across the region.
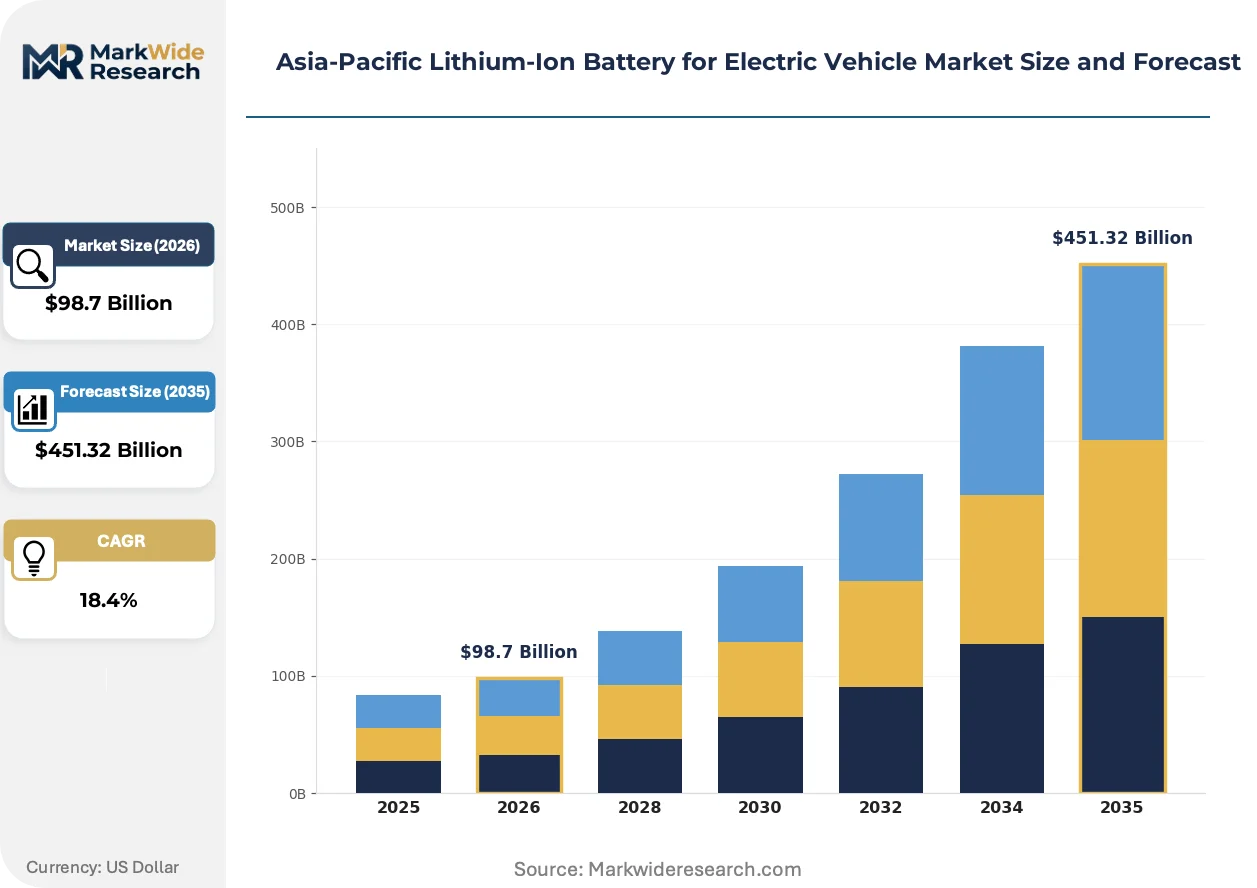
Market Dynamics
China's MIIT battery standards are tightening cell energy density thresholds while Southeast Asian passenger fleets scale electrification programs, compressing procurement timelines and repositioning buyer leverage toward vertically integrated cell suppliers.
Growth Catalysts
- Dual Carbon Goals:China's national carbon neutrality targets mandate fleet electrification timelines that pull forward battery procurement cycles across Jiangsu-Zhejiang manufacturing corridors.
- GB/T Traceability Mandates:MIIT-enforced cell-level tracking requirements are standardizing quality tiers and accelerating supplier consolidation toward certified producers.
- LFP Chemistry Maturation:Iron-phosphate cathode formulations have achieved cost-parity with incumbent technologies in commercial vehicle duty cycles, unlocking two-wheeler and bus segments.
Market Restraints
- Lithium Carbonate Volatility:Raw material input costs swing with Qinghai and Salar de Atacama extraction rates, compressing cathode producer margins unpredictably.
- High-Nickel Supply Concentration:NMC precursor refining capacity clusters in Indonesian nickel-processing zones and South Korean chemical parks, creating single-point vulnerability.
- Solid-State Timeline Uncertainty:Sulfide-electrolyte manufacturing scalability remains unproven, delaying energy density breakthroughs promised for long-range passenger platforms.
Strategic Opportunities
- Thailand EV Incentive Window:Board of Investment tax holidays for battery cell factories are attracting tier-2 suppliers to Eastern Economic Corridor industrial zones.
- Second-Life Stationary Storage:Retired automotive packs with 70-80% state-of-health are repurposing for grid-scale frequency regulation across Australian and Japanese utilities.
- Silicon-Anode Integration:Pre-lithiated silicon composite anodes converging with dry electrode coating processes promise 400 Wh/kg cell-level targets by decade-end.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Fluorinated solvent and additive expertise concentrates in legacy Japanese chemical firms, constraining new entrant R&D velocity.
- Gigafactory Capex Intensity:Dry room construction, electrode coating lines, and formation cycling equipment demand multi-billion-dollar commitments before revenue recognition.
- Cross-Border GB/T-UN38.3 Harmonization:Divergent thermal runaway test protocols between Chinese domestic and export certification paths extend product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $451.32 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Module End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: LFP, NMC, NCA, LMO Application: Energy Storage Systems, EV Charging Stations, Power Tools, Robotics |
| Companies Covered | Contemporary Amperex Technology Co. Ltd (CATL), Panasonic Corporation, LG Energy Solution Ltd, Samsung SDI Co., Ltd., BYD Company Limited, Tianjin Lishen Battery Joint-Stock Co., Ltd., SK Innovation Co., Ltd., AESC Group Ltd, GS Yuasa International Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Cell architecture standardization and regulatory pressure on carbon intensity are compressing technology cycles while reshaping how battery systems integrate with vehicle platforms and energy infrastructure.
Cell-to-pack designs are eliminating module housings and redundant structural elements. Domestic Chinese automakers are adopting these architectures fastest, with prismatic LFP configurations now shipping without intermediate module assemblies. This simplification is modularizing how battery systems scale across vehicle classes, enabling shared thermal management hardware across sedans and SUVs.
China's MIIT is enforcing GB/T battery passport requirements that mandate full lifecycle carbon disclosure from mining through recycling. Industrial consequence includes mandatory supplier auditing and embodied carbon thresholds for subsidy eligibility. Export-oriented NMC producers are most affected, accelerating investment in Indonesian nickel hydrometallurgy to reduce Scope 3 emissions.
Fleet operators are consolidating procurement through direct cell supplier contracts rather than tiered automotive supplier hierarchies. Bus and commercial vehicle segments are bypassing pack integrators, negotiating volume commitments directly with CATL and BYD production bases. This disintermediation is most visible across Southeast Asian markets where state-owned transit authorities aggregate demand into single-tender structures.
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market Segmentation
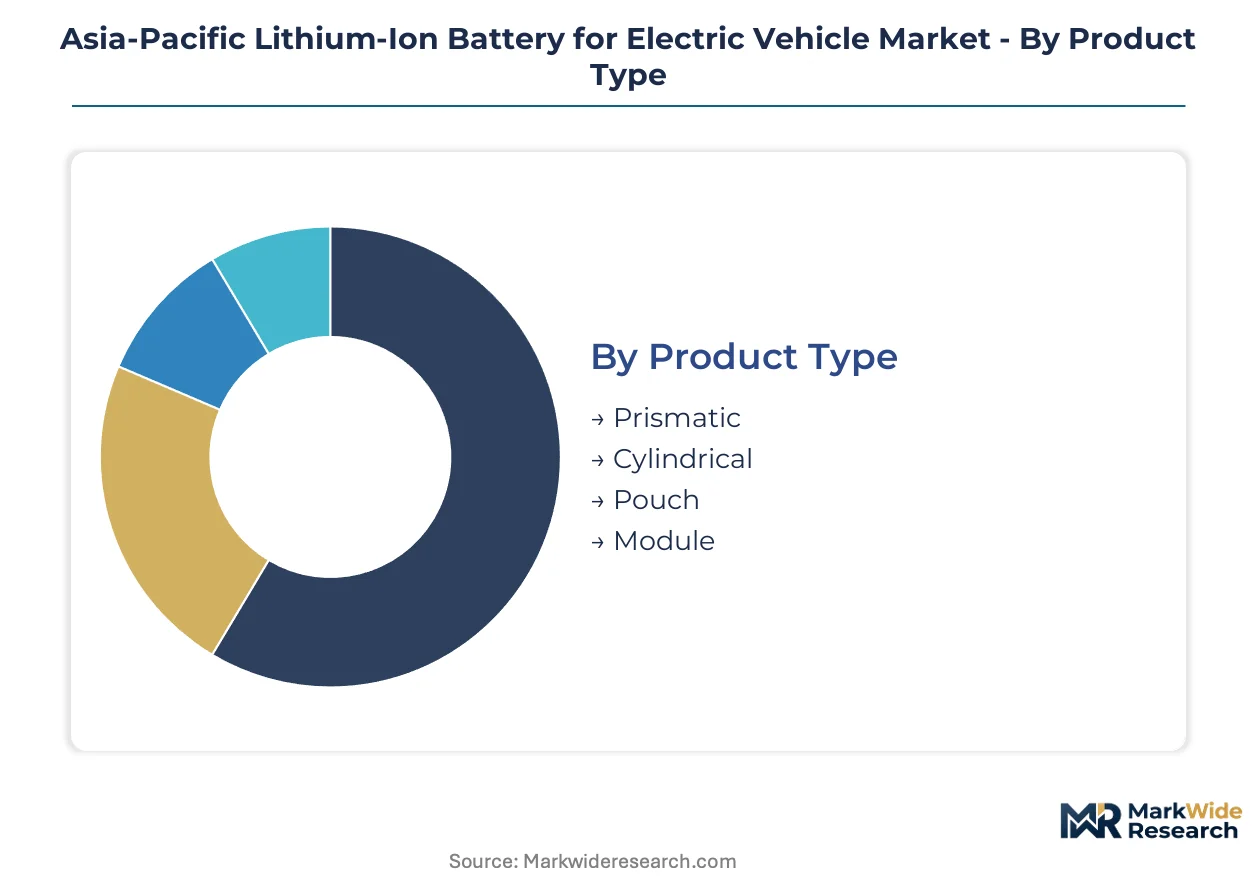
Cell format selection and chemistry choices in Asia-Pacific EV battery procurement reflect divergent upgrade cycles across vehicle platforms. Fleet operators and OEMs calibrate replacement timelines against duty-cycle intensity, thermal management requirements, and regulatory compliance windows.
Product Type:
Upgrade cycles for battery enclosures track closely with vehicle platform refresh schedules and thermal system redesigns across Chinese and Southeast Asian manufacturing bases.
- Prismatic:Aluminum-housed rectangular cells with stacked or wound electrode configurations deliver superior space utilization and structural rigidity. Jiangsu-Zhejiang corridor automakers specify prismatic LFP formats for new passenger vehicle platforms, compressing module elimination timelines through cell-to-pack architectures.
- Cylindrical:Rolled electrode assemblies in steel or aluminum cans tolerate high internal pressures and enable automated winding production. Korean suppliers deploy cylindrical 2170 and 4680 formats for premium export-oriented EV platforms, where manufacturing consistency overrides pack-level volumetric efficiency.
- Pouch:Laminated polymer-aluminum foil enclosures maximize gravimetric energy density through flexible form factors. Japanese and Korean producers reserve pouch designs for limited-volume luxury applications where weight minimization commands engineering priority.
- Module:Intermediate assemblies of grouped cells with integrated thermal management and electrical interconnection. Commercial vehicle and bus segments retain modular architectures to simplify field replacement and extend service interval flexibility.
Volume placements concentrate in prismatic formats; the faster expansion belongs to cylindrical formats as 4680-scale production scales.
End User:
Customer-type segmentation reveals how procurement scale and duty-cycle severity reshape supplier engagement models across mobility categories.
- Passenger Vehicles:Private and fleet-operated sedans, SUVs, and crossovers demanding 300-700 km range targets. Chinese OEMs dominate procurement volume through CATL and BYD supply agreements, with state-backed purchase subsidies accelerating replacement-cycle compression.
- Commercial Vehicles:Light, medium, and heavy-duty trucks requiring high cycle-life tolerance under variable load profiles. Southeast Asian logistics operators are consolidating tender structures to negotiate direct cell contracts, bypassing traditional pack integrators.
- Two-Wheelers:Electric motorcycles and scooters with sub-5 kWh pack requirements. Indian and Southeast Asian markets specify swappable LFP configurations for last-mile delivery fleets, where battery-as-a-service models decouple asset ownership from utilization.
- Buses:Urban transit and intercity coaches with megawatt-hour-scale stationary charging infrastructure. State-owned transit authorities across Thailand and Indonesia aggregate demand into single-source procurement, leveraging volume concentration for price positioning.
Procurement scale concentrates with passenger vehicle OEMs; commercial vehicle direct-sourcing is climbing the fastest.
Technology:
Cost-tier differentiation between cathode chemistries maps to application-specific performance thresholds and margin structures.
- LFP:Lithium iron phosphate cathodes with olivine crystal structure and 3.2 V nominal voltage. Cost-parity achievement in commercial duty cycles has unlocked bus and two-wheeler segments across China and Southeast Asia, where cycle-life economics override energy density specifications.
- NMC:Nickel-manganese-cobalt layered oxides optimizing energy density through nickel content escalation. Korean and Japanese producers sustain NMC 811 and 9½ formulations for long-range passenger platforms, though Indonesian nickel processing concentration creates supply vulnerability.
- NCA:Nickel-cobalt-aluminum cathodes delivering highest gravimetric energy density among commercialized technologies. Limited deployment persists in premium Japanese OEM platforms where cathode cost absorption maintains margin viability.
- LMO:Lithium manganese spinel chemistry offering thermal stability and cost advantages at reduced energy density. Niche applications in power tools and hybrid electric vehicles retain LMO procurement where discharge rate tolerance commands priority.
Production volume concentrates in LFP; NMC high-nickel formulations are gaining share fastest in export-oriented premium segments.
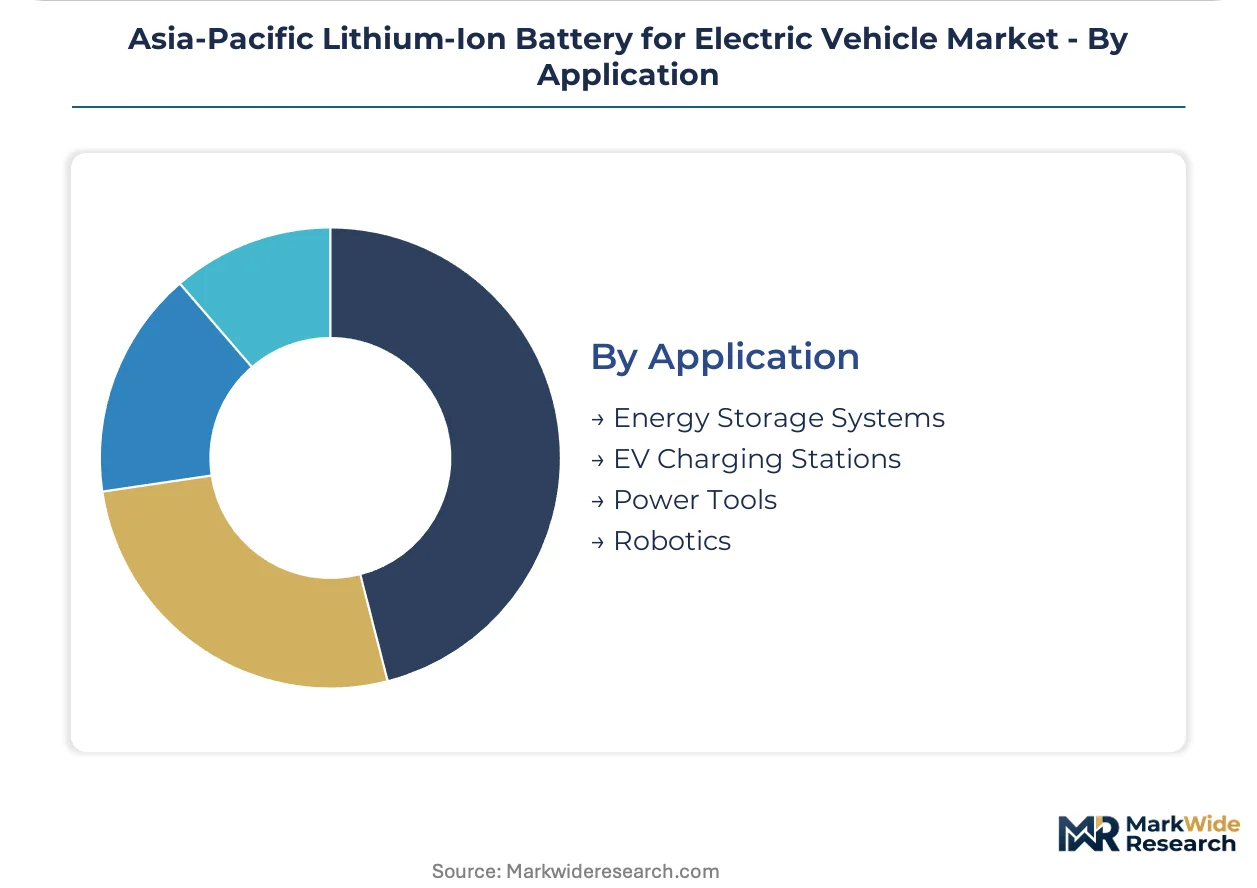
Application:
Segment maturity varies across stationary and mobile energy storage, with repurposing channels creating secondary demand streams.
- Energy Storage Systems:Grid-scale and behind-the-meter stationary installations utilizing retired automotive packs. Australian and Japanese utilities are contracting for second-life LFP supply with 70-80% state-of-health thresholds, establishing circular procurement pathways.
- EV Charging Stations:Buffer storage at fast-charging hubs to mitigate grid demand charges. Chinese charging infrastructure operators are integrating on-site battery buffers across Eastern Economic Corridor developments, though deployment scale trails vehicle-integrated volumes.
- Power Tools:Cordless professional equipment demanding high discharge rates. Cylindrical cell formats dominate this segment, with manufacturing overlap to EV supply creating capacity allocation tension during demand surges.
- Robotics:Automated guided vehicles and mobile manipulation platforms requiring compact energy density. Industrial automation adoption in Korean and Japanese manufacturing is pulling specialized pouch and cylindrical procurement outside traditional automotive channels.
Installed base concentrates in energy storage systems; robotics applications are expanding most quickly as manufacturing automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among Chinese OEMs dominates regional demand, with Jiangsu-Zhejiang manufacturing corridors pulling cell supply from captive and third-party sources. Southeast Asian electrification programs are compressing procurement timelines across Thailand, Indonesia, and Vietnam.
China
Passenger vehicle OEMs in the Yangtze River Delta are scaling LFP procurement for domestic platforms while NMC volumes serve export-oriented premium segments. MIIT enforces GB/T battery passport requirements mandating full lifecycle carbon disclosure from mining through recycling. Ningxia and Fujian production bases anchor CATL's supply dominance for state-backed automakers.
South Korea
High-nickel NMC formulations sustain Korean producers' positioning in long-range passenger applications for European and North American export markets. MFDS and KATS frameworks govern cell quality certification for domestic OEM supply eligibility. Gyeonggi-do and Chungcheongnam-do chemical parks concentrate precursor refining capacity, creating single-point vulnerability.
Japan
Premium OEM platforms retain niche demand for highest-energy-density chemistries where cathode cost absorption maintains margin viability. METI coordinates national solid-state battery roadmaps through public-private consortia targeting sulfide-electrolyte manufacturing scalability. Kansai and Kyushu manufacturing bases host specialized pouch cell production for luxury vehicle integration.
Thailand
State-owned transit authorities are aggregating bus fleet demand into single-tender structures to negotiate direct cell contracts. Board of Investment tax holidays for battery cell factories are attracting tier-2 suppliers to Eastern Economic Corridor industrial zones. Rayong and Chonburi provinces are emerging as pack assembly hubs for regional commercial vehicle deployment.
Australia
Utilities are contracting for second-life LFP supply with 70-80% state-of-health thresholds, establishing circular procurement pathways for grid-scale frequency regulation. State-level renewable energy targets are accelerating stationary storage deployment timelines. Queensland and New South Wales mining operations are expanding spodumene extraction to feed regional cathode supply chains.
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
Chinese producers anchor the volume tier; Korean and Japanese specialists hold premium-chemistry positions. The vendor base concentrates around vertically integrated cell suppliers with captive cathode production, compressing margins for non-integrated pack assemblers. Three archetypes dominate: state-linked domestic champions, export-oriented high-nickel specialists, and captive automotive producers. Capacity expansion and backward integration into precursor refining represent the dominant competitive moves across the region.
Among Chinese producers, Contemporary Amperex Technology Co. Ltd exemplifies the state-linked domestic champion archetype through its Ningxia production base dominance. LG Energy Solution Ltd and Samsung SDI Co., Ltd. occupy positions within the export-oriented high-nickel specialist tier, serving premium platform requirements. BYD Company Limited represents the captive automotive producer model through in-house cathode and cell manufacturing integration.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Ltd (CATL) |
| Panasonic Corporation |
| LG Energy Solution Ltd |
| Samsung SDI Co., Ltd. |
| BYD Company Limited |
| Tianjin Lishen Battery Joint-Stock Co., Ltd. |
| SK Innovation Co., Ltd. |
| AESC Group Ltd |
| GS Yuasa International Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive cathode production at CATL and BYD anchors both supply security and pricing power for Chinese OEMs, compressing margins for non-integrated pack assemblers while enabling aggressive LFP pricing in commercial vehicle tenders.
Pricing Analysis
Volume placements concentrate in contract-based long-term offtake structures for passenger vehicle OEMs, while spot-market exposure persists in two-wheeler and commercial vehicle segments. Price differentiation stems from certification grade under MIIT GB/T standards and volume scale commitments exceeding gigawatt-hour annual thresholds. Cost compression in LFP tiers is intensifying because iron-phosphate cathode oversupply in Jiangsu-Zhejiang corridors has eliminated material scarcity premiums. State-owned transit authorities exhibit highest price sensitivity through consolidated tender structures, whereas premium export-oriented platforms absorb NMC cathode cost premiums with least negotiation leverage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Chinese automakers, bypassing traditional tiered automotive supplier hierarchies. Raw material dependencies center on Indonesian nickel laterite for NMC precursor refining, Australian spodumene for lithium hydroxide conversion, and Qinghai brine extraction for domestic Chinese carbonate supply. Distribution runs through Ningxia and Fujian production bases for LFP output, with South Korean chemical parks anchoring high-nickel cathode supply for export markets. Single-source vulnerability concentrates in Indonesian nickel-processing zones, where hydrometallurgy capacity expansion lags precursor demand acceleration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where cathode precursor control determines margin retention against raw material volatility. Players are pursuing backward integration into Indonesian nickel refining and Australian lithium extraction to secure cost-positioning.
For Market Incumbents: Anticipate margin compression from state-backed OEM consolidation by locking multi-year offtake agreements before tender structures harden. Defensive priorities center on GB/T certification maintenance against MIIT traceability mandates, and captive precursor refining in Indonesian industrial zones to offset South Korean chemical park concentration risk. For New Entrants and Emerging Players: Tier-2 commercial vehicle pack integrators represent the most penetrable channel partner type for establishing initial revenue traction. White-space targets include Thailand Eastern Economic Corridor assembly operations and second-life stationary storage contracting with Australian utilities. Go-to-market positioning should emphasize LFP cell-to-pack architectures for bus fleet operators bypassing incumbent module suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by OEMs seeking captive supply security. Long-term viability favors producers with demonstrated GB/T certification and Indonesian nickel-processing joint ventures. The inflection signal to watch is MIIT subsidy threshold adjustments tightening embodied carbon requirements, which would accelerate consolidation toward certified low-carbon producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Indonesian nickel hydrometallurgy investments reduce Scope 3 exposure for NMC export eligibility under EU carbon border mechanisms. |
| Cell-to-Pack Architecture Adoption | Elimination of module housings cuts pack-level costs for Jiangsu-Zhejiang corridor automakers standardizing across sedan and SUV platforms. |
| GB/T Certification Investment | MIIT-enforced traceability mandates require cell-level tracking systems that non-certified producers cannot retrofit without capital-intensive line upgrades. |
| Second-Life Storage Partnership | Australian utility contracts for 70-80% state-of-health LFP packs establish circular revenue streams outside automotive replacement cycles. |
| Solid-State R&D Consortium Participation | METI-coordinated sulfide-electrolyte programs in Japan position participants for post-lithium-ion chemistry transitions in premium segments. |
Research Methodology
MIIT regulatory filings, customs trade databases, and OEM production disclosures formed the secondary backbone for supply-side capacity and demand mapping. Primary interviews with cell procurement directors at Chinese OEMs, cathode plant managers in Jiangsu-Zhejiang corridors, and utility storage planners in Australian state grids validated secondary estimates. Bottom-up and top-down triangulation reconciled facility-level production data against vehicle registration flows.
Bottom-up modeling aggregated cell-format and chemistry-specific production capacities across identified manufacturing bases, while top-down approaches cross-checked against vehicle platform electrification timelines and national fleet targets. Segmentation dimensions included cell format, cathode chemistry, vehicle class, and regional production cluster. CAGRs were derived from fitted growth curves against policy-mandated electrification schedules and raw material supply expansion trajectories. Forecast inputs incorporated MIIT subsidy phase-out assumptions and Indonesian nickel project commissioning timelines.
Caveats apply where lithium carbonate spot volatility or Indonesian export policy shifts could materially shift the outlook for cathode cost structures. Forecasts reflect assumptions around GB/T certification compliance timelines and Southeast Asian incentive program continuity. Periodic stress-testing of base assumptions is recommended against MIIT threshold adjustments and solid-state manufacturing scalability breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Middle-East E-Bike Market