
 Electric Three Wheeler Market | 2026-2036
Electric Three Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Three Wheeler Market Intelligence
ARAI certification for electric three-wheelers is unwinding the competitive field as smaller assemblers struggle to meet crash-test and homologation requirements. Mahindra Electric Mobility Limited leverages its integrated powertrain development to sustain product pipeline depth across passenger and cargo variants. Bajaj Auto Ltd anchors its position through established ICE-to-electric channel migration and service network density in Indian urban markets.
An electric three-wheeler is a battery-powered motorized vehicle with three wheels, typically featuring a gross vehicle weight under 1,500 kg, hub-mounted or axle-driven electric motors, and lithium-ion or lead-acid battery packs delivering 60-120 km per charge, designed primarily for short-haul urban passenger transport and last-mile goods delivery. Passenger E-rickshaws dominate unit volumes across South Asian markets where unorganized fleet operators prioritize low capital outlay over total cost of ownership, while Delivery E-vans capture expanding margin pools as organized logistics providers specify telematics integration and refrigerated compartments for temperature-sensitive cargo.
India's Ministry of Heavy Industries administers the FAME II subsidy framework that directly reduces electric three-wheeler purchase prices, while the Bureau of Indian Standards enforces IS 17017 charging protocol compatibility that shapes product design and infrastructure interoperability. The Central Pollution Control Board's emission jurisdiction over conventional three-wheelers creates regulatory pressure for fleet conversion in metropolitan areas. Stakeholders must monitor how state-level electric vehicle policies diverge on road tax waivers and parking privileges as these variations will determine profitable geographic prioritization.
Market Dynamics
Fleet electrification mandates from India's Ministry of Heavy Industries are compressing the conversion timeline for last-mile logistics operators, while ARAI certification barriers simultaneously filter out smaller assemblers from volume participation.
Growth Catalysts
- FAME II subsidy framework:Direct purchase price reductions administered by India's Ministry of Heavy Industries accelerate fleet replacement cycles among organized logistics providers and passenger fleet operators.
- Hub-mounted motor architectures:Simplified drivetrain designs reduce maintenance intervals and parts inventory burdens for unorganized fleet operators across South Asian urban corridors.
- Tier-2 and tier-3 city density:Narrow street infrastructure and sub-50 km daily duty cycles in India's secondary urban centers create structural preference for compact electric cargo configurations over four-wheel alternatives.
Market Restraints
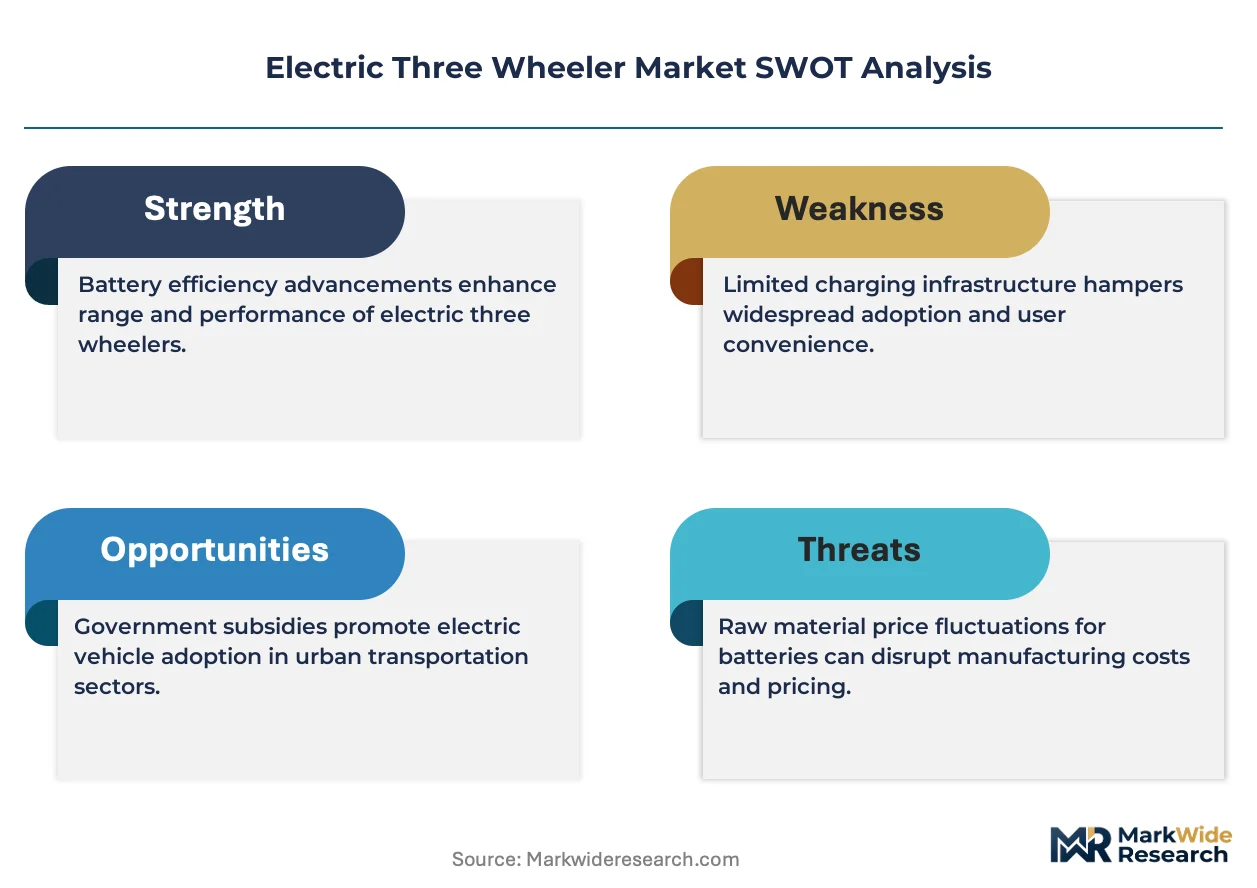
- Lithium-cell import dependence:India's battery pack assemblers face raw material cost volatility tied to concentrated cathode precursor supply from Chinese processing facilities.
- ARAI homologation timeline:Crash-test certification requirements extend product development cycles by 8-14 months for passenger variant entrants lacking established testing partnerships.
- Lead-acid residual fleet:Sub-100 km range lead-acid configurations retain 40-45% of unit volumes in price-sensitive unorganized segments, delaying lithium-ion upgrade penetration.
Strategic Opportunities
- Refrigerated compartment integration:Temperature-controlled cargo variants capture margin expansion from pharmaceutical and fresh-produce logistics chains specifying telematics-enabled cold chain verification.
- State-level EV policy divergence:Road tax waivers and parking privilege variations across Maharashtra, Gujarat, and Tamil Nadu create geographic arbitrage for fleet operators optimizing registration location.
- Solar-assisted charging infrastructure:Off-grid photovoltaic integration at depot locations addresses grid reliability constraints in semi-urban distribution nodes.
Industry Challenges
- Powertrain calibration expertise:Hub motor torque mapping and regenerative braking optimization require scarce embedded systems engineering talent concentrated among incumbent automotive suppliers.
- BIS charging protocol compliance:IS 17017 interoperability testing delays product launches when connector and communication stack revisions cascade through supplier tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Three Wheeler Market |
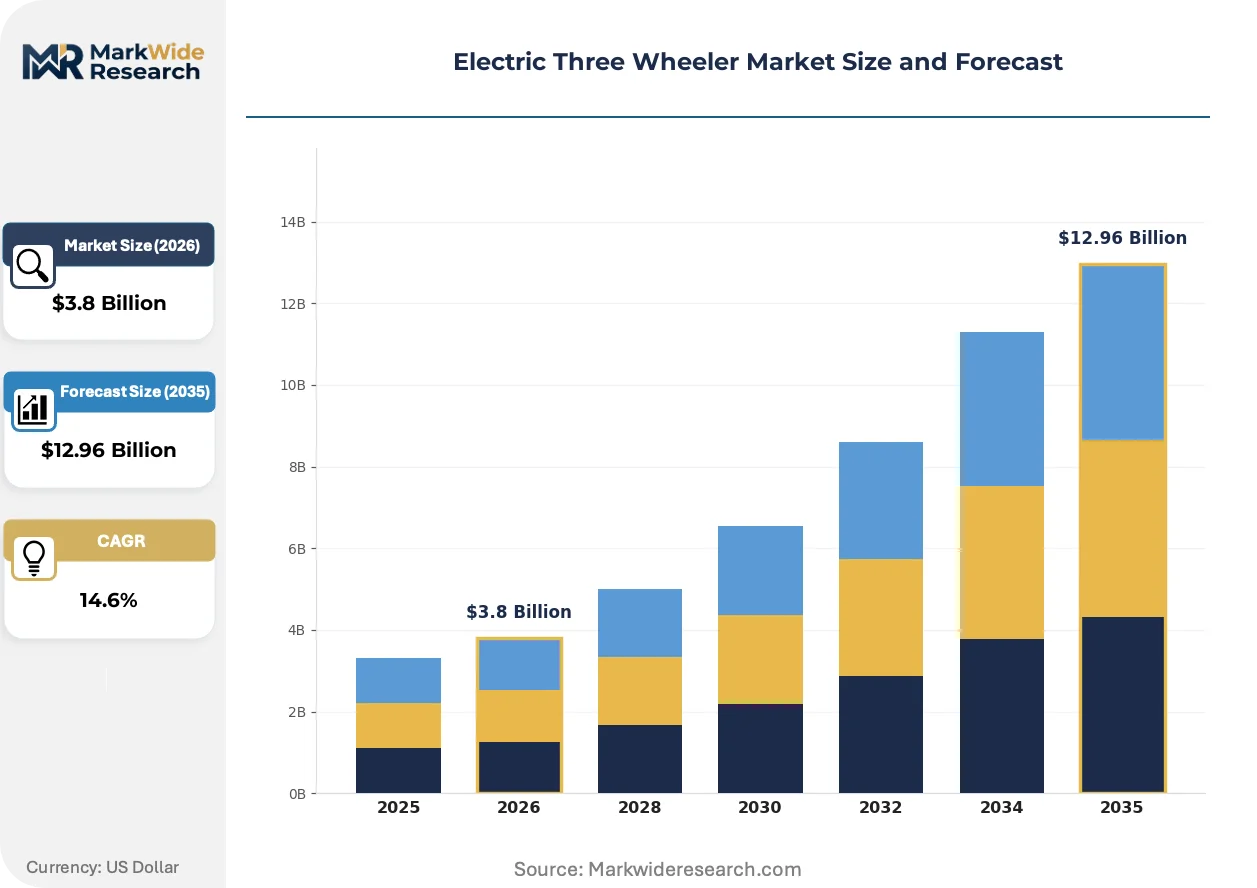
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger E-rickshaws, Delivery E-vans, Cargo E-vehicles, Custom E-vehicles End User: Logistics Providers, Taxi Services, Personal Use, Commercial Fleets Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Others Charging Infrastructure: Fast Charging Stations, Standard Charging Points, Home Charging Solutions, Workplace Chargers |
| Companies Covered | Mahindra Electric Mobility Limited, YC Electric Vehicle, Piaggio Group, Bajaj Auto Ltd, Saera Electric Auto Pvt Ltd, Atul Auto Limited, Kinetic Green Energy & Power Solutions Ltd, Omega Seiki Pvt Ltd, Terra Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Three Wheeler Market Strategic Shifts & Innovations
Powertrain architecture standardization and telematics integration are compressing the feature gap between organized logistics specifications and unorganized fleet economics.
Lithium-iron-phosphate cell chemistry is supplanting lead-acid and nickel-manganese-cobalt alternatives in cargo variants above 80 km rated range. Organized logistics providers with centralized fleet management mandate this chemistry for thermal stability during multi-shift operations. The shift is compressing battery replacement revenue pools for aftermarket service networks while extending vehicle depreciation schedules.
India's Bureau of Indian Standards enforcement of IS 17017 charging protocol compatibility is mandating CAN bus communication between vehicle and infrastructure. This industrial consequence forces hardware redesigns for legacy connector suppliers and excludes non-compliant imported units from subsidy eligibility. Cargo variants with telematics integration are most affected, as fleet operators now specify real-time state-of-charge visibility as a procurement requirement.
Consolidated fleet procurement contracts are displacing individual owner-operator purchases in last-mile logistics. Organized providers with 500-plus unit deployments now negotiate direct manufacturer relationships, bypassing traditional dealer networks. This pattern is most visible in Maharashtra and Karnataka, where e-commerce fulfillment density supports dedicated charging depot investments.
Electric Three Wheeler Market Segmentation
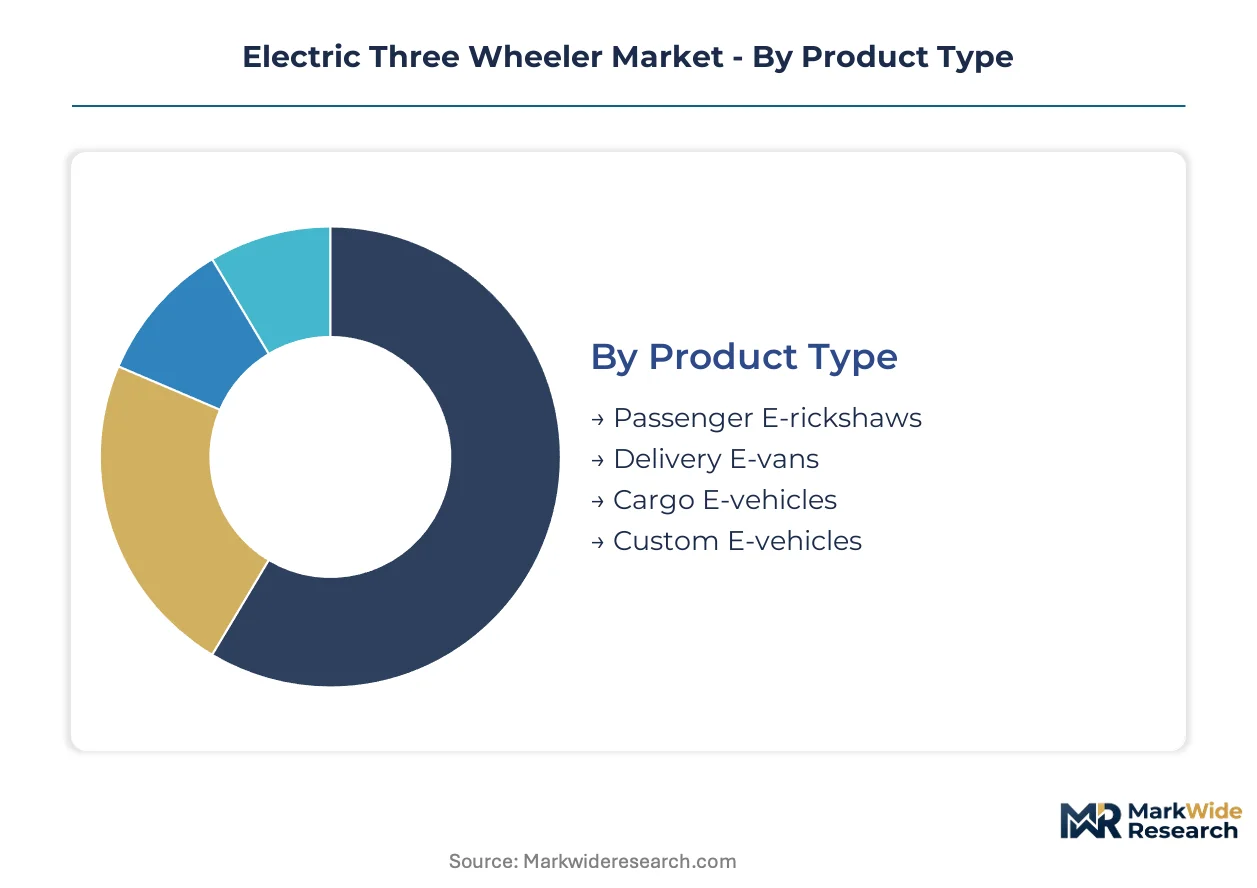
Segmentation in the Electric Three Wheeler Market reveals how subsidy eligibility, battery chemistry, and fleet procurement patterns concentrate margin pools across distinct product configurations. Understanding these divides allows manufacturers to prioritize R&D spending and channel investments toward segments with sustainable pricing power.
Product Type:
Margin pools concentrate in cargo variants where organized logistics providers specify telematics integration and cold-chain capabilities, while passenger segments compete on acquisition cost.
- Passenger E-rickshaws:Hub-mounted motor architectures with 60-100 km range dominate unit volumes across South Asian urban corridors. Unorganized fleet operators in India's tier-2 and tier-3 cities prioritize low capital outlay over total cost of ownership, compressing manufacturer margins despite high volume throughput.
- Delivery E-vans:Telematics-enabled configurations with refrigerated compartments capture expanding margin pools from pharmaceutical and fresh-produce logistics chains. Organized providers in Maharashtra and Karnataka now mandate real-time state-of-charge visibility as a procurement requirement, differentiating compliant manufacturers.
- Cargo E-vehicles:Open-bed and enclosed-box variants serve construction material transport and intra-city freight distribution.
- Custom E-vehicles:Specialized configurations for municipal waste collection and mobile vending applications address niche procurement tenders.
Passenger E-rickshaws hold installed capacity. Delivery E-vans is rotating up the share rankings.
End User:
Procurement concentration determines pricing leverage, with consolidated fleet contracts displacing individual owner-operator purchases in volume terms.
- Logistics Providers:Organized last-mile operators with 500-plus unit deployments negotiate direct manufacturer relationships, bypassing traditional dealer networks. E-commerce fulfillment density in Maharashtra supports dedicated charging depot investments that lock in multi-year supply agreements.
- Taxi Services:Aggregator-platform fleets in Indian metropolitan areas specify ARAI-certified passenger variants with GPS tracking and panic buttons for regulatory compliance.
- Personal Use:Individual ownership remains limited to urban commuter segments with reliable home charging access.
- Commercial Fleets:Corporate shuttle services and institutional transport operators prioritize standardized maintenance protocols across distributed vehicle pools.
Logistics Providers command volume pricing. Commercial Fleets is climbing the fastest in procurement sophistication.
Battery Type:
Chemistry selection directly determines thermal stability, cycle life, and subsidy eligibility under FAME II framework specifications.
- Lithium-ion:Lithium-iron-phosphate cell chemistry is supplanting nickel-manganese-cobalt alternatives in cargo variants above 80 km rated range. Organized logistics providers mandate this chemistry for thermal stability during multi-shift operations, extending vehicle depreciation schedules while compressing aftermarket replacement revenue.
- Lead-acid:Sub-100 km range configurations retain 40-45% of unit volumes in price-sensitive unorganized segments, delaying upgrade penetration despite higher lifetime operating costs.
- Nickel-metal Hydride:Transitional chemistry persists in early-generation fleet deployments awaiting replacement cycles.
- Others:Sodium-ion and solid-state prototypes remain pre-commercial for three-wheeler duty cycles.
Lithium-ion holds technology leadership. Lead-acid is defending share through price positioning.
Charging Infrastructure:
Infrastructure type shapes depot layout economics and vehicle utilization rates across fleet operating models.
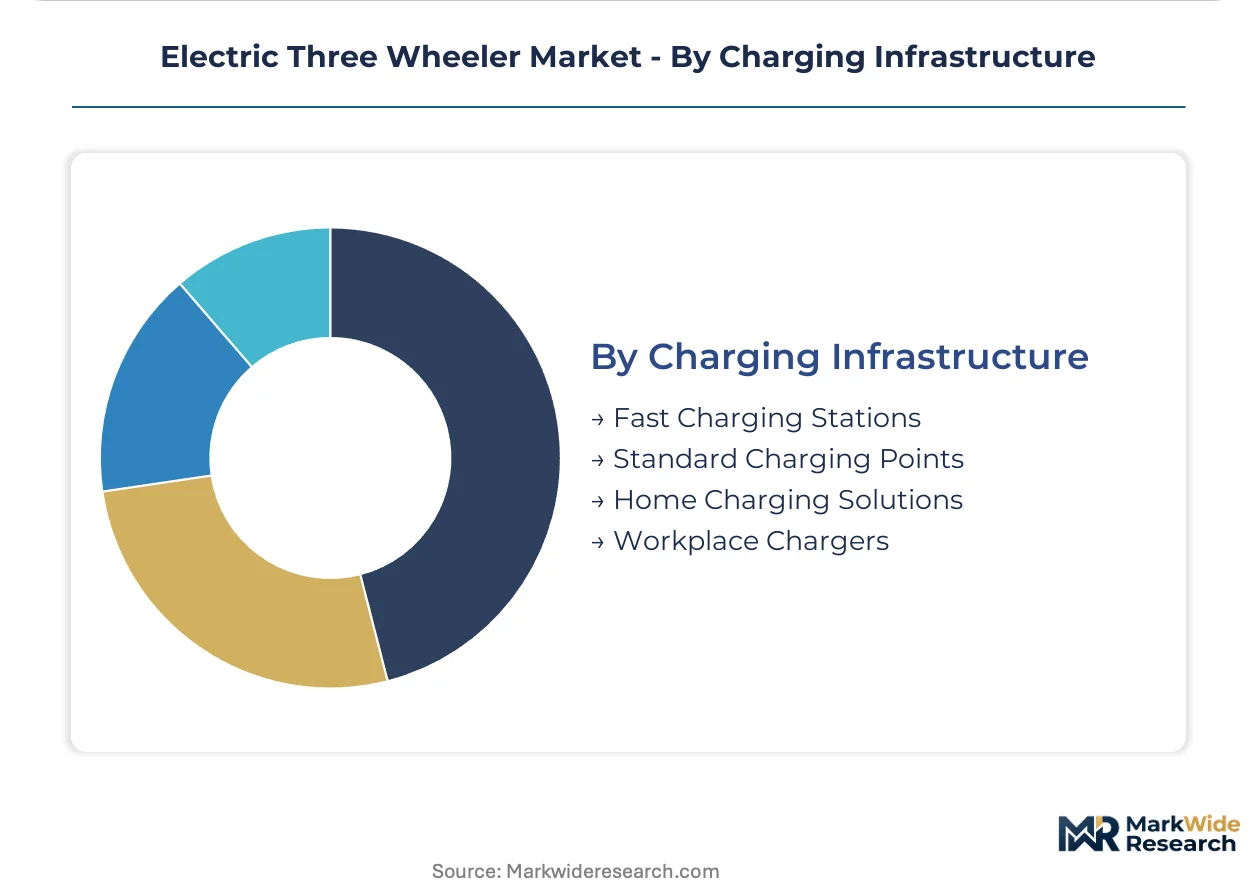
- Fast Charging Stations:30-60 minute DC charging enables multi-shift operations for organized logistics providers with centralized fleet management. Grid reliability constraints in semi-urban distribution nodes limit deployment density.
- Standard Charging Points:Overnight AC charging at 3-7 kW dominates unorganized fleet economics where vehicles return to fixed depots.
- Home Charging Solutions:Residential 230V single-phase installations support personal use and small taxi operator segments.
- Workplace Chargers:Employer-subsidized installations serve corporate shuttle and last-mile delivery staff parking.
Standard Charging Points hold installed base. Fast Charging Stations is gaining share fastest among organized fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Heavy Industries' FAME II subsidy scheme compresses acquisition costs across South Asian corridors. Fleet operators in dense urban agglomerations exploit state-level variations in road tax waivers and parking privileges. Charging infrastructure deployment concentrates near logistics hubs and e-commerce fulfillment centers.
India
Last-mile logistics providers in Maharashtra and Karnataka expand fleet electrification through direct manufacturer relationships. The Bureau of Indian Standards enforces IS 17017 charging protocol compatibility that shapes product design and infrastructure interoperability. Tier-2 cities including Indore, Lucknow, and Coimbatore favor compact electric cargo configurations for narrow street navigation.
China
Hub-mounted motor manufacturers supply battery pack assemblers across the Yangtze River Delta manufacturing belt. The Ministry of Industry and Information Technology administers GB standards for electric vehicle safety and performance. Zhengzhou and Shandong industrial clusters concentrate low-speed electric vehicle production for domestic last-mile distribution.
Bangladesh
Unorganized fleet operators in Dhaka and Chittagong prioritize low capital outlay for passenger E-rickshaw procurement. The Bangladesh Road Transport Authority regulates vehicle registration and safety standards for three-wheeler categories. Narayanganj's assembly workshops convert imported kits for urban passenger transport.
Vietnam
Motorcycle-to-electric conversion demand accelerates in Ho Chi Minh City and Hanoi metropolitan areas. The Vietnam Register administers type approval and homologation requirements for electric vehicle categories. Hai Phong's port logistics operators pilot electric cargo fleets for intra-city freight distribution.
Indonesia
Two-wheeler dominated markets show emerging three-wheeler adoption for goods delivery in Jakarta and Surabaya. The Ministry of Industry's electric vehicle roadmap targets domestic manufacturing capacity expansion. Batam's free trade zone attracts component assembly operations for regional export.
Electric Three Wheeler Market Key Industry Players
Listed leaders compete with private specialists across subsidy eligibility and certification compliance. The vendor base stratifies between integrated automotive conglomerates with established dealer networks and emerging assemblers targeting price-sensitive unorganized segments. Two dominant archetypes emerge: legacy two-wheeler and three-wheeler manufacturers migrating ICE-to-electric portfolios, and pure-play electric vehicle specialists leveraging hub motor simplicity. Competitive moves center on ARAI certification partnerships to compress homologation timelines and state-level fleet procurement contracts that bypass traditional distribution.
Within the integrated automotive tier, Mahindra Electric Mobility Limited and Bajaj Auto Ltd occupy positions shaped by established service network density and channel migration capabilities. Among specialist assemblers, Omega Seiki Pvt Ltd and Saera Electric Auto Pvt Ltd exemplify the private capital-backed archetype targeting organized logistics specifications. YC Electric Vehicle represents the regional fabricator segment serving price-sensitive unorganized demand in North Indian corridors.
| Leading Market Players |
|---|
| Mahindra Electric Mobility Limited |
| YC Electric Vehicle |
| Piaggio Group |
| Bajaj Auto Ltd |
| Saera Electric Auto Pvt Ltd |
| Atul Auto Limited |
| Kinetic Green Energy & Power Solutions Ltd |
| Omega Seiki Pvt Ltd |
| Terra Motors |
| Others |
Cost & Logistics Intelligence
Capacity utilization at lithium-cell processing facilities in China's Yangtze River Delta shapes both supply concentration and price floors for Indian battery pack assemblers. Tier-1 manufacturers with captive cathode precursor sourcing maintain margin buffers that tier-2 assemblers cannot replicate under FAME II subsidy pressure.
Pricing Analysis
Certification level under ARAI crash-test protocols creates the primary spread between organized logistics procurement and unorganized fleet acquisition. Three-tier pricing structure across ARAI-certified, state-homologated, and kit-assembled configurations reflects compliance investment differentials. Cost compression in kit-assembled tiers is intensifying because lead-acid residual fleets delay lithium-ion upgrade penetration. Unorganized owner-operators in tier-3 cities exhibit highest price sensitivity, while organized logistics providers with 500-plus unit deployments prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Just-in-time inventory strategies dominate hub motor procurement from Zhengzhou manufacturing clusters, while strategic stockpiling of lithium carbonate persists among battery pack assemblers facing raw material volatility. Cathode precursor supply draws from Chinese processing facilities, with separator membranes and electrolyte solvents sourced from South Korea and Japan. Single-source vulnerability in cathode chemistry creates exposure to export license restrictions. Distribution runs through state-level dealer networks for passenger variants and direct manufacturer relationships for organized logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against four-wheel electric cargo vans as last-mile logistics providers evaluate payload-capacity tradeoffs. Compressed three-wheeler margins require strategic repositioning toward telematics-enabled cold-chain specifications.
For Market Incumbents: Shield ARAI-certified product pipelines by accelerating crash-test partnership investments that smaller assemblers cannot replicate. Consolidate service network density in Maharashtra and Karnataka to lock in multi-year fleet procurement contracts before four-wheel electric alternatives achieve cost parity. Channel control through captive financing partnerships represents the critical defensive lever against price-sensitive kit-assembled entrants.
For New Entrants and Emerging Players: Anchor in refrigerated compartment integration for pharmaceutical logistics chains where temperature-controlled cargo specifications command premium positioning. Tier-2 cities including Indore and Lucknow present the most penetrable geography given narrow street infrastructure and sub-50 km duty cycles that favor compact configurations. Direct depot-level relationships with 50-100 vehicle fleet operators bypass established dealer networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-enabled cargo specialists with multi-shift fleet management contracts. Long-term viability over the projection horizon hinges on lithium-iron-phosphate chemistry migration and IS 17017 charging protocol compliance. Acquisition targets should demonstrate established ARAI certification partnerships and state-level subsidy registration capabilities. The signal to watch is consolidation of lead-acid residual fleet replacement cycles into organized lithium-ion procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| ARAI Certification Partnership | Crash-test homologation compresses product development timelines for passenger variant entrants. |
| Lithium-Iron-Phosphate Chemistry Migration | Thermal stability specifications from organized logistics providers extend vehicle depreciation schedules. |
| Telematics Platform Integration | Real-time state-of-charge visibility meets procurement mandates from Maharashtra-based fleet operators. |
| Direct Fleet Procurement Contract | Bypassing dealer networks captures margin pools from 500-plus unit logistics deployments. |
| Solar-Assisted Charging Depot | Off-grid photovoltaic integration addresses grid reliability constraints in semi-urban distribution nodes. |
Research Approach
A spread of perspectives from fleet operations managers, battery pack procurement leads, ARAI certification engineers, state transport authority officials, and dealer network heads converged on the working assumptions underlying this analysis. Primary interviews with logistics providers and component assemblers combined with secondary validation from BIS technical specifications, FAME II subsidy disbursement records, Ministry of Heavy Industries policy circulars, and vehicle registration databases. Bottom-up unit shipment estimates and top-down value aggregation triangulated across these sources.
Segmentation dimensions modeled include product type, battery chemistry, end-user procurement pattern, and charging infrastructure type across the analysis window. CAGRs derived from logistic curve penetration modeling applied to lithium-ion replacement cycles and fleet electrification mandates. Industry-specific forecast inputs incorporated state-level EV policy divergence on road tax waivers and ARAI homologation timeline compression.
Material uncertainties — lithium-cell import tariff adjustments, state subsidy scheme modifications, and grid reliability degradation — sit outside the modeled envelope. Forecasts reflect assumptions about FAME II continuity and IS 17017 enforcement trajectory. Revision becomes warranted when lead-acid residual fleet replacement acceleration crosses thresholds that invalidate lithium-ion penetration curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Denmark Solar E-Bike Market