
 E-Bike Accessories Market | 2026-2036
E-Bike Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Accessories Market Analysis
Market Context
Taiwan is rewriting component supply dynamics for e-bike accessories through its established bicycle manufacturing cluster and precision metalworking infrastructure. Bosch leverages in-house motor-controller integration to anchor premium drivetrain accessory demand across European OEM channels. Shimano competes on scale by sustaining dominant positions in braking and gearing systems for both factory-fit and aftermarket replacement. Specialized differentiates through proprietary battery form factors and integrated smart displays that tighten ecosystem loyalty.
Technical Definition and Segment Structure
E-bike accessories comprise auxiliary components and systems that extend the functionality, safety, or serviceability of electrically assisted bicycles, including lithium-ion battery packs rated for 36V to 48V architectures, LED lighting modules with IPX5 weather sealing, and smart locking mechanisms with Bluetooth proximity activation. Their primary commercial purpose centers on enabling reliable daily mobility, protecting rider welfare, and reducing total cost of ownership through replaceable subsystems. Batteries occupy the largest margin pool within product type segmentation due to cell chemistry costs and replacement frequency, while delivery services represent the fastest-expanding end user category as logistics electrification accelerates fleet refresh cycles. Carbon fiber material adoption concentrates in premium helmets and structural components where gram reduction justifies unit price premiums over aluminum and plastic alternatives.
Regulatory Environment and Outlook
The EU Green Deal and F-Gas Regulation shape battery thermal management standards and refrigerant-based cooling accessory designs across European markets, while REACH compliance mandates material disclosure for rubber grips and plastic housings sold into EU member states. The EPA and NHTSA in the United States influence headlamp luminosity thresholds and reflectivity requirements that accessory manufacturers must certify before interstate commerce. Stakeholders should monitor evolving battery transport classification rules from ICAO and IATA, as lithium-cell shipping restrictions directly impact aftermarket distribution economics and cross-border inventory positioning.
Market Dynamics
Fleet electrification mandates across European logistics operators are compressing replacement cycles for high-wear accessories while battery thermal management requirements reshape supplier qualification thresholds.
Growth Catalysts
- EU Green Deal implementation:Carbon reduction targets for urban freight operators accelerate procurement of durable lighting and locking systems rated for commercial duty cycles.
- Last-mile delivery electrification:Courier and food-delivery fleets in Germany and the Netherlands generate concentrated demand for reinforced racks and weather-sealed control interfaces.
- Solid-state battery prototyping:Early manufacturing trials for ceramic electrolyte cells are expanding R&D accessory budgets among premium OEM development programs.
Market Restraints
- Lithium carbonate price volatility:Cell material cost swings compress margin pools for battery pack assemblers serving price-sensitive aftermarket channels.
- Taiwan component concentration:Precision metalworking and motor-controller fabrication clusters create single-source vulnerability for European and North American brands.
- REACH compliance complexity:Rubber compound and plastic housing disclosure requirements extend product development timelines for accessories sold into EU member states.
Strategic Opportunities
- India urban mobility subsidies:State-level electric two-wheeler incentive programs create first-mover positioning for helmet and lighting suppliers establishing local assembly.
- Battery-as-a-service models:Swappable pack architectures enable recurring revenue streams for charging infrastructure operators expanding into accessory financing.
- 5G-V2X integration:Connected vehicle protocols are converging with e-bike telemetry to open subscription-based safety and theft-recovery service bundles.
Industry Challenges
- Power electronics engineering scarcity:Motor-controller firmware and battery management system design talent pools remain shallow relative to OEM hiring demand.
- IP fragmentation across connector standards:Proprietary battery form factors and communication protocols create integration barriers for third-party accessory developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Accessories Market |
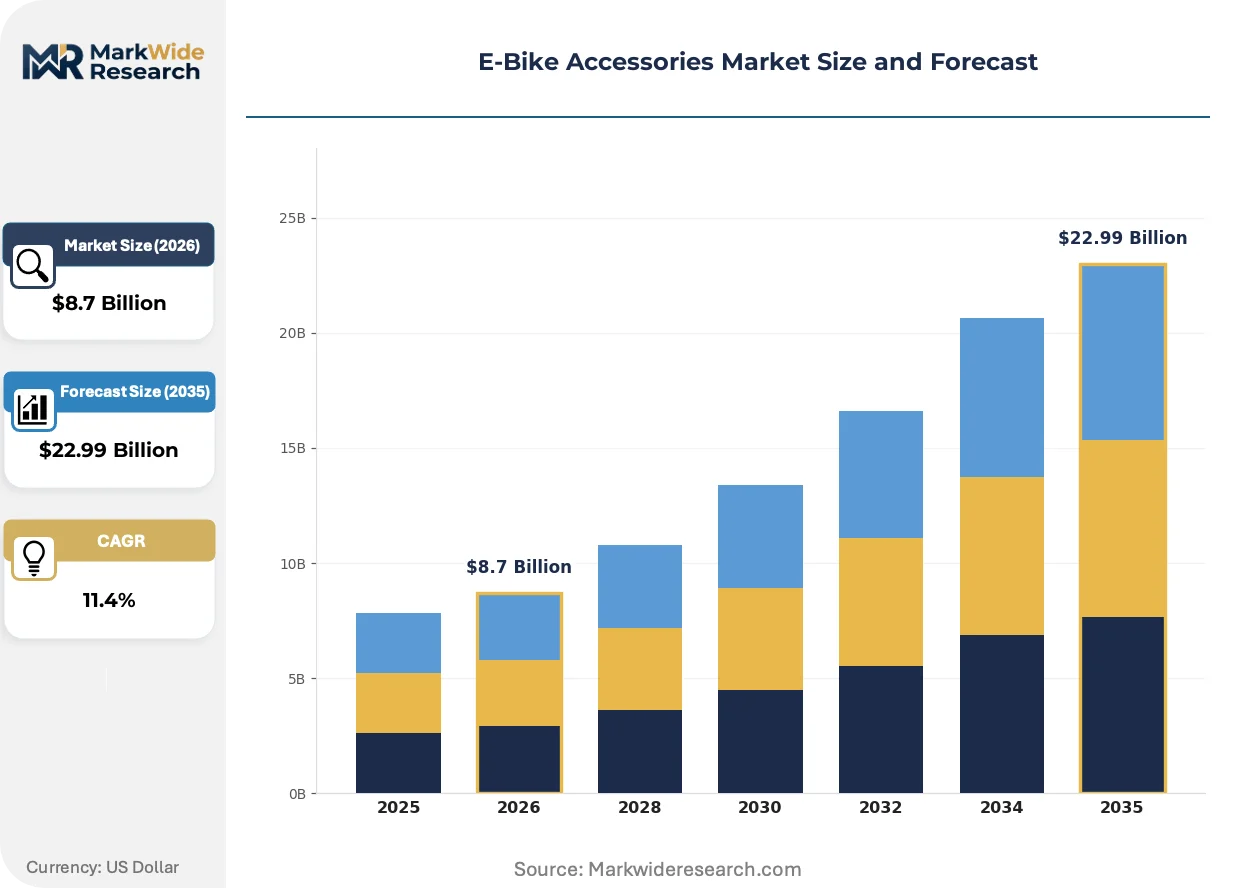
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Helmets, Lights, Locks Material: Aluminum, Carbon Fiber, Plastic, Rubber End User: Sports Enthusiasts, Commuters, Delivery Services, Tourists Service Type: Repair Services, Maintenance Packages, Customization, Rental Services |
| Companies Covered | Specialized, Giant, Bosch, Aventon, Rad Power Bikes, Shimano, Trek, Riese & Müller, Yamaha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Accessories Market Emerging Trajectories
Accessory architectures are fragmenting between closed OEM ecosystems and modular open standards, with thermal management and connectivity emerging as the primary axes of technical differentiation.
Silicon carbide (SiC) power semiconductors are reducing switching losses in motor controllers by thirty to fifty percent versus silicon IGBTs. High-performance e-bike drivetrain suppliers in Germany and Switzerland are adopting SiC modules for their flagship 85 Nm torque-rated systems. The technology is migrating from aviation and automotive auxiliary drives into premium e-bike segments, compressing thermal management component counts while extending peak power duration.
REACH substance restrictions are tightening disclosure thresholds for phthalates and heavy metals in rubber grips and cable sheathing sold into EU markets. Accessory manufacturers must reformulate compound recipes and revalidate supplier certifications ahead of 2025 enforcement windows. Helmets and lighting housings face the steepest compliance costs due to polymer content density and skin-contact proximity.
Direct-to-fleet sales channels are displacing traditional distributor networks for high-volume delivery operator accounts. Specialized procurement teams at logistics companies in the Netherlands and Denmark now negotiate frame-integrated battery and telematics bundles directly with OEM accessory divisions. This concentration is most visible in Copenhagen and Amsterdam, where municipal zero-emission delivery zones have consolidated purchasing authority among fewer than fifteen fleet operators.
E-Bike Accessories Market Segmentation
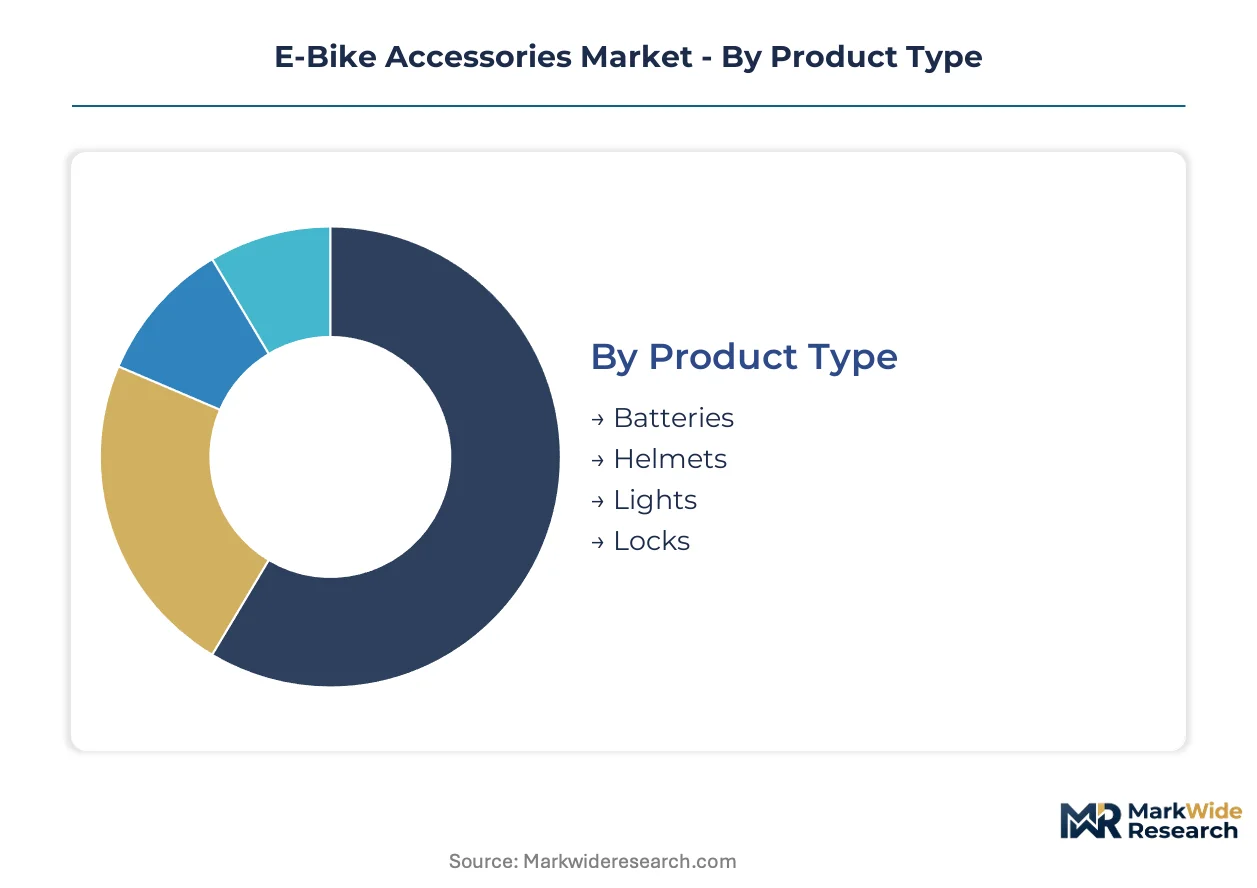
E-bike accessory purchasing patterns diverge sharply between fleet operators optimizing for total cost of ownership and individual riders prioritizing convenience aesthetics. Understanding these segment boundaries clarifies where premium pricing power concentrates versus where volume scale dominates procurement economics.
Product Type:
Accessories span power systems, protective equipment, visibility hardware, and security devices with distinct replacement cycles and margin profiles.
- Batteries:Lithium-ion packs rated for 36V to 48V architectures constitute the largest revenue pool due to cell chemistry costs and mandatory replacement intervals. Demand concentrates among German delivery fleets where thermal management specifications from OEM supplier networks drive premium procurement.
- Helmets:Protective headgear incorporating MIPS rotational impact systems and integrated LED lighting commands price premiums in urban commuter segments. Carbon fiber reinforced shells from Swiss and Italian manufacturers dominate high-performance positioning where gram reduction justifies unit cost multiples over ABS alternatives.
- Lights:LED modules with IPX5 weather sealing address regulatory compliance for nighttime operation across EU member states.
- Locks:Bluetooth proximity activation and hardened steel shackles serve theft-prone metropolitan parking environments.
The dominant share belongs to Batteries, while Lights is closing the gap fastest as municipal safety mandates expand across European urban cores.
Material:
Component material selection trades manufacturing cost against performance durability with divergent supply chain implications.
- Carbon Fiber:Woven composite structures deliver maximum strength-to-weight ratios for premium helmets and structural rack components. Production concentrates in Taiwan's precision metalworking clusters where filament winding expertise supports tier-one OEM qualification.
- Aluminum:Extruded and CNC-machined alloys dominate mid-market rack systems and motor housings where corrosion resistance and cost equilibrium meet fleet procurement specifications.
- Plastic:Injection-molded ABS and polycarbonate enclosures serve lighting housings and display bezels with REACH compliance complexity driving reformulation timelines.
- Rubber:Compound formulations for grips and cable sheathing face phthalate disclosure thresholds under tightening EU substance restrictions.
Aluminum commands the highest volume throughput, though Carbon Fiber delivers the steepest margin expansion trajectory among premium positioning strategies.
End User:
User archetypes range from performance-oriented recreational riders to commercial operators with standardized fleet specifications.
- Delivery Services:Courier and food-delivery fleets generate concentrated demand for reinforced racks, weather-sealed control interfaces, and rapid-replace battery architectures. Municipal zero-emission zones in Amsterdam and Copenhagen have consolidated purchasing authority among fewer than fifteen major logistics operators.
- Commuters:Daily urban mobility riders prioritize integrated lighting, smart locking, and ergonomic contact points with direct-to-consumer channels displacing traditional retail for replacement accessories.
- Sports Enthusiasts:Performance-oriented riders demand gram-optimized components with proprietary compatibility from premium OEM ecosystems.
- Tourists:Rental fleet and vacation-use segments drive seasonal procurement spikes for durable, low-maintenance configurations.
Delivery Services anchors absolute revenue scale, while Commuters is expanding most quickly as gasoline price volatility accelerates modal shift in German and Dutch metropolitan regions.
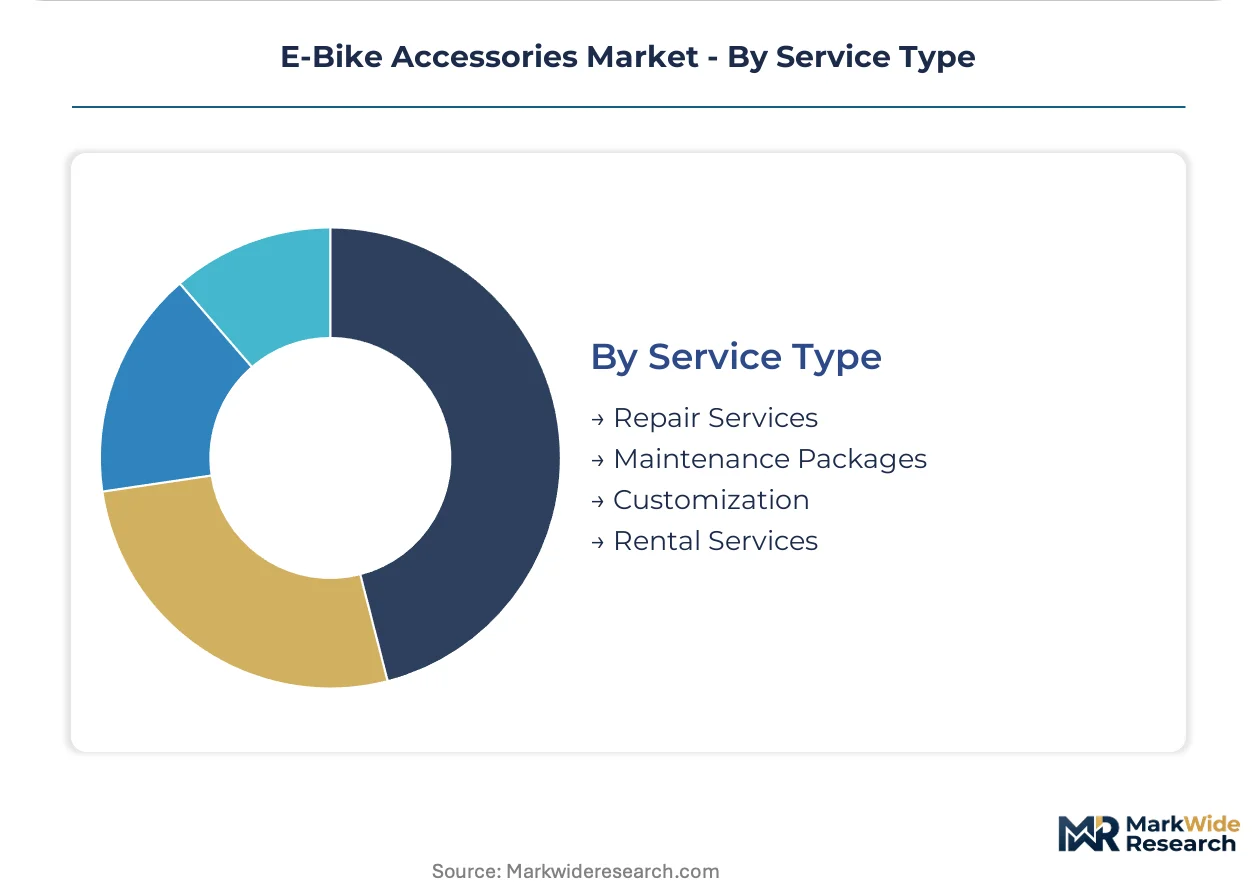
Service Type:
Post-purchase revenue streams span repair, preventive maintenance, aesthetic modification, and temporary access models.
- Maintenance Packages:Scheduled inspection and component replacement programs reduce fleet downtime for commercial operators. Dutch logistics companies negotiate frame-integrated battery and telematics bundles directly with OEM accessory divisions.
- Repair Services:Diagnostic and corrective work on battery management systems and motor controllers addresses warranty expiration and out-of-network failure.
- Customization:Aesthetic and ergonomic modifications including saddle swaps, handlebar upgrades, and paint protection serve enthusiast segments with discretionary spending capacity.
- Rental Services:Temporary access models for tourists and trial users require durable, standardized configurations with simplified user interfaces.
Maintenance Packages capture the recurring revenue premium, while Rental Services is gaining share fastest as tourism recovery and micromobility-as-a-service platforms expand European urban deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's electrified hinterland freight corridors anchor European e-bike accessory distribution, while Taiwan's Kaohsiung container terminals handle precision component exports that supply assembly plants across three continents.
Germany
Last-mile delivery fleet standardization drives procurement of weather-sealed battery enclosures and reinforced cargo racks. KBA vehicle type approval mandates thermal runaway containment specifications for commercial e-bike battery systems. Stuttgart's precision engineering cluster hosts motor-controller firmware development for premium drivetrain suppliers serving Dutch and Danish logistics operators.
Netherlands
Municipal zero-emission delivery zones in Amsterdam and Utrecht consolidate purchasing authority among fewer than fifteen major courier fleets. EU Green Deal carbon reduction targets accelerate replacement cycles for LED lighting and smart locking systems rated for commercial duty. Eindhoven's high-tech manufacturing corridor supplies integrated telematics modules for frame-embedded battery architectures.
United States
Class 1-3 e-bike adoption in urban commuter corridors generates aftermarket demand for MIPS-equipped helmets and Bluetooth-enabled security devices. EPA and NHTSA headlamp luminosity thresholds shape LED module certification requirements for interstate commerce. Seattle and Portland metropolitan procurement offices negotiate direct-to-fleet maintenance contracts with OEM accessory divisions.
Taiwan
Precision metalworking clusters in Taichung and Kaohsiung dominate carbon fiber filament winding and motor-controller fabrication for tier-one OEM qualification. The country's national standards bureau aligns bicycle component testing protocols with ISO and IEC frameworks for export market access. Taoyuan's aerotropolis logistics zone expedites lithium-cell battery pack shipments to European and North American aftermarket channels.
India
State-level electric two-wheeler incentive programs in Maharashtra and Karnataka create first-mover positioning for helmet and lighting suppliers establishing local assembly. BIS certification requirements for lithium-ion battery safety and electromagnetic compatibility extend product development timelines for imported accessories. Gurugram's automotive component corridor attracts Taiwanese joint ventures for domestic motor-controller production.
E-Bike Accessories Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structures around three concentration layers: closed OEM ecosystems with proprietary battery form factors, open-standard suppliers serving aftermarket channels, and fleet-direct procurement teams negotiating bundled telematics contracts. Strategic archetypes include premium drivetrain developers, scale-driven braking and gearing manufacturers, and direct-to-consumer e-bike brands with captive accessory lines. Competitive moves center on backward integration into cell pack assembly and geographic expansion through local certification partnerships.
Within the premium drivetrain tier, Bosch and Shimano exemplify divergent scale positions: the German GmbH anchors motor-controller integration for European OEM channels, while the Japanese manufacturer sustains dominant positions in braking and gearing systems across factory-fit and replacement markets. Among North American direct-to-consumer brands, Rad Power Bikes occupies a position representing fleet-direct sales channel innovation. Specialized, the California-based manufacturer, sits within the closed ecosystem archetype through proprietary battery architectures and integrated smart displays that tighten rider loyalty.
| Leading Market Players |
|---|
| Specialized |
| Giant |
| Bosch |
| Aventon |
| Rad Power Bikes |
| Shimano |
| Trek |
| Riese & Müller |
| Yamaha |
| Others |
Supply Flow & Price Mechanics
Taiwan component concentration risk determines both battery pack pricing tier spreads and supply chain shape, as single-source dependency for precision metalworking and motor-controller fabrication forces European and North American brands into premium qualification premiums or volume-driven standard tier acceptance.
Pricing Analysis
Volume-discount tiering separates fleet-direct procurement from aftermarket retail channels, with Dutch and German logistics operators capturing 40-60% unit cost reductions on frame-integrated battery and telematics bundles. Certification grade under REACH and KBA thermal runaway standards creates premium-mid-economy pricing differentiation, while lithium carbonate volatility compresses margins for price-sensitive aftermarket assemblers. Cost compression in standard-tier battery packs is intensifying because cell material swings transfer directly to pack pricing, and delivery services exhibit lowest price sensitivity due to total cost of ownership optimization versus individual commuters facing discretionary trade-offs.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment and advanced battery cell technology limit flows from Taiwan and South Korea to Chinese pack assemblers, reshaping component sourcing patterns. Production gravity centers on Taiwan for carbon fiber filament winding and motor-controller fabrication, China for lithium-ion cell assembly, and Germany for premium drivetrain system integration. The network rests on rare earth magnet supply from Chinese separation facilities, ceramic electrolyte precursors from Japanese chemical producers, and precision aluminum extrusions from Taiwanese mills. Single-source vulnerability in Taichung precision clusters threatens European OEM qualification timelines. Distribution runs through Rotterdam's electrified hinterland corridors for European last-mile fulfillment and Kaohsiung container terminals for trans-Pacific aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-bike accessory demand follows fleet refresh cycles tied to municipal zero-emission zone enforcement, positioning the market for cyclical expansion as logistics electrification mandates tighten across Amsterdam, Copenhagen, and German urban cores.
For Market Incumbents: Harden motor-controller firmware development capabilities against power electronics engineering scarcity by acquiring specialized BMS design houses in Stuttgart's precision cluster. Deepen backward integration into lithium-cell pack assembly to defend margin position against Taiwan component concentration risk and capture fleet-direct pricing power through captive thermal management specification control.
For New Entrants and Emerging Players: Pursue state-level electric two-wheeler incentive programs in Maharashtra and Karnataka through local helmet and lighting assembly partnerships with Gurugram automotive component corridors. Target maintenance package bundling for Dutch logistics operators as the most penetrable service segment, leveraging direct procurement team access at consolidated fleet operators in Amsterdam and Utrecht.
For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors component specialists with ISO-certified thermal management capabilities and established OEM supplier network relationships. Long-term viability over the next decade hinges on solid-state battery prototyping trajectories and 5G-V2X subscription service attach rates. Monitor ICAO lithium-cell shipping restriction enforcement as the critical inflection signal for aftermarket distribution economics and cross-border inventory positioning strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Platform Launch | Enables recurring revenue streams for charging infrastructure operators expanding into accessory financing across European logistics corridors. |
| Silicon Carbide Power Semiconductor Adoption | Reduces switching losses by thirty to fifty percent for premium German and Swiss drivetrain suppliers developing 85 Nm torque-rated systems. |
| REACH Compliance Reformulation Program | Extends product development timelines for rubber grip and cable sheathing manufacturers ahead of tightened phthalate disclosure thresholds. |
| Direct-to-Fleet Telematics Bundling | Consolidates purchasing authority among fewer than fifteen major courier operators in Copenhagen and Amsterdam zero-emission zones. |
| Taiwan Joint Venture for Motor-Controller Production | Attracts domestic manufacturing investment to Gurugram's automotive component corridor under Indian BIS certification requirements. |
Methodological Framework
Desk research of customs trade records, SEC filings from bicycle component manufacturers, and EU regulatory databases preceded structured interviews with OEM accessory division procurement directors, fleet operations managers at Dutch and German logistics companies, thermal management system engineers, and aftermarket distribution channel heads. Primary fieldwork combined with secondary validation against KBA type approval documentation, REACH substance restriction filings, and Taiwan Bicycle Association export statistics supported bottom-up and top-down triangulation across volume and value estimates.
Forecast assumptions held fixed the current EU Green Deal carbon reduction target trajectory and existing ICAO lithium-cell shipping classification rules, while varying fleet electrification mandate enforcement intensity and solid-state battery prototyping timelines across the analysis window. Segmentation dimensions modeled included product type tier, material grade, end-user archetype, and service delivery model, with CAGRs derived from replacement cycle compression rates and premium positioning elasticity. Industry-specific inputs incorporated municipal zero-emission zone expansion schedules and Taiwan precision cluster capacity utilization rates.
Sensitivities concentrate around lithium carbonate price volatility, Taiwan semiconductor equipment export control enforcement, and REACH substance restriction timeline acceleration. Forecasts reflect documented assumptions regarding fleet procurement standardization and thermal management specification adoption. Material shifts in EU battery transport classification or German KBA thermal runaway containment standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
India E-Bike Market