
 South America Electric Vehicle (EV) Fluids Market | 2026-2036
South America Electric Vehicle (EV) Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle (EV) Fluids Market Insights
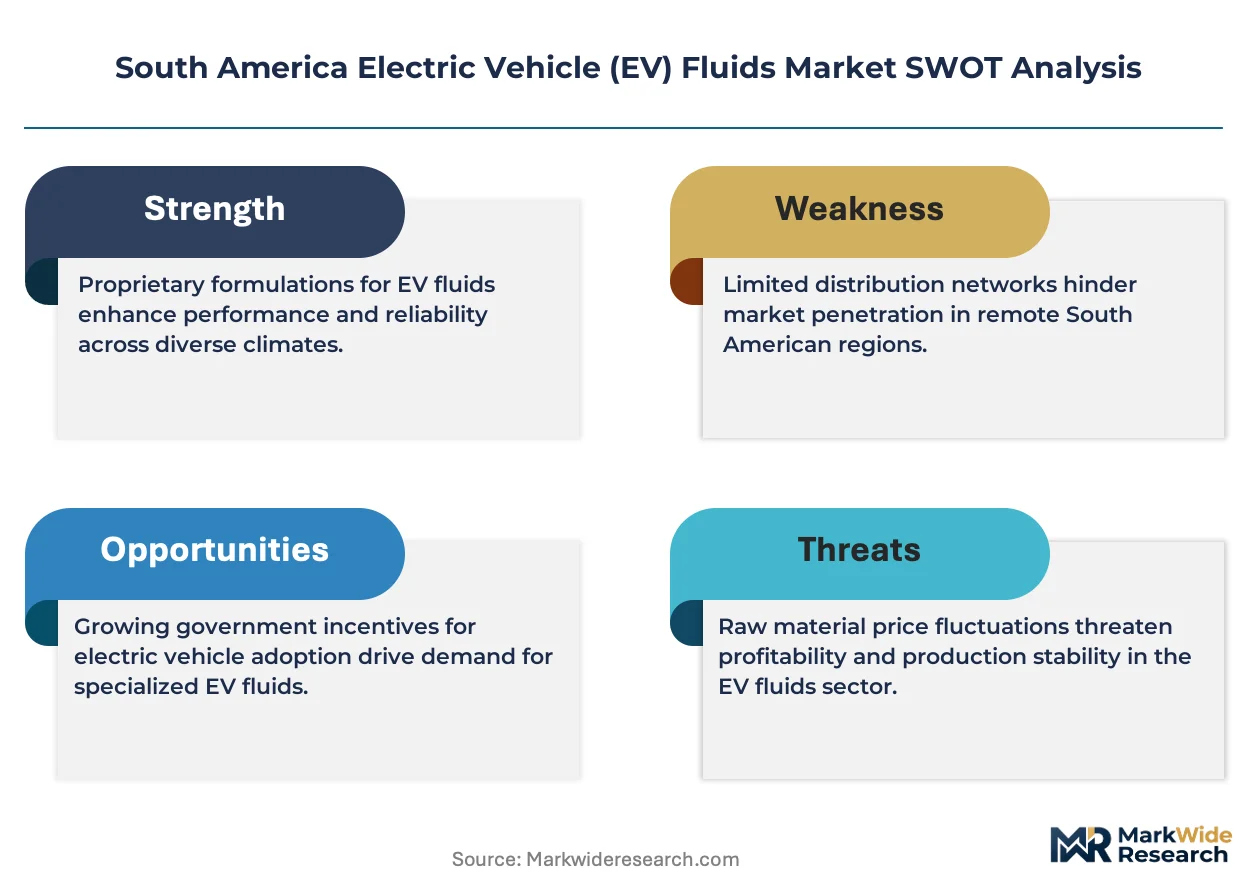
API SP and OEM-specific EV fluid certifications are redrawing competitive boundaries in the South America Electric Vehicle (EV) Fluids Market. Shell plc leverages its backward integration into base oil refining to secure supply reliability across Brazilian distribution channels. TotalEnergies anchors its position through dedicated EV fluid laboratories in Argentina. CASTROL LIMITED differentiates via partnerships with European OEM assembly plants in the Mercosur zone.
Electric vehicle fluids encompass coolants, lubricants, brake fluids, and transmission fluids formulated with low-conductivity, high-dielectric-strength base stocks and additive packages engineered for thermal stability in electrified powertrains. These fluids manage battery pack temperatures, reduce friction in e-axle gearboxes, and ensure reliable braking performance in regenerative systems. Synthetic fluid grades command the widest margin pools due to extended drain intervals and OEM warranty compliance requirements. Aftermarket providers represent the fastest-growing end-user channel as Brazil's installed EV base ages beyond factory fill periods. Cooling system applications lead volume absorption, driven by liquid-cooled battery architectures dominating regional OEM specifications.
Brazil's ANP biofuel blending mandates intersect with CONMETRO certification requirements, pressuring suppliers to validate biodegradability claims for coolant chemistries. Argentina's INTI standards institute enforces thermal conductivity testing protocols that filter out uncertified imports. ANVISA oversight of workplace chemical exposure adds compliance layers to service center fluid handling procedures. Stakeholders must track how Mercosur harmonization negotiations reshape cross-border technical standards before committing to single-country formulation strategies.
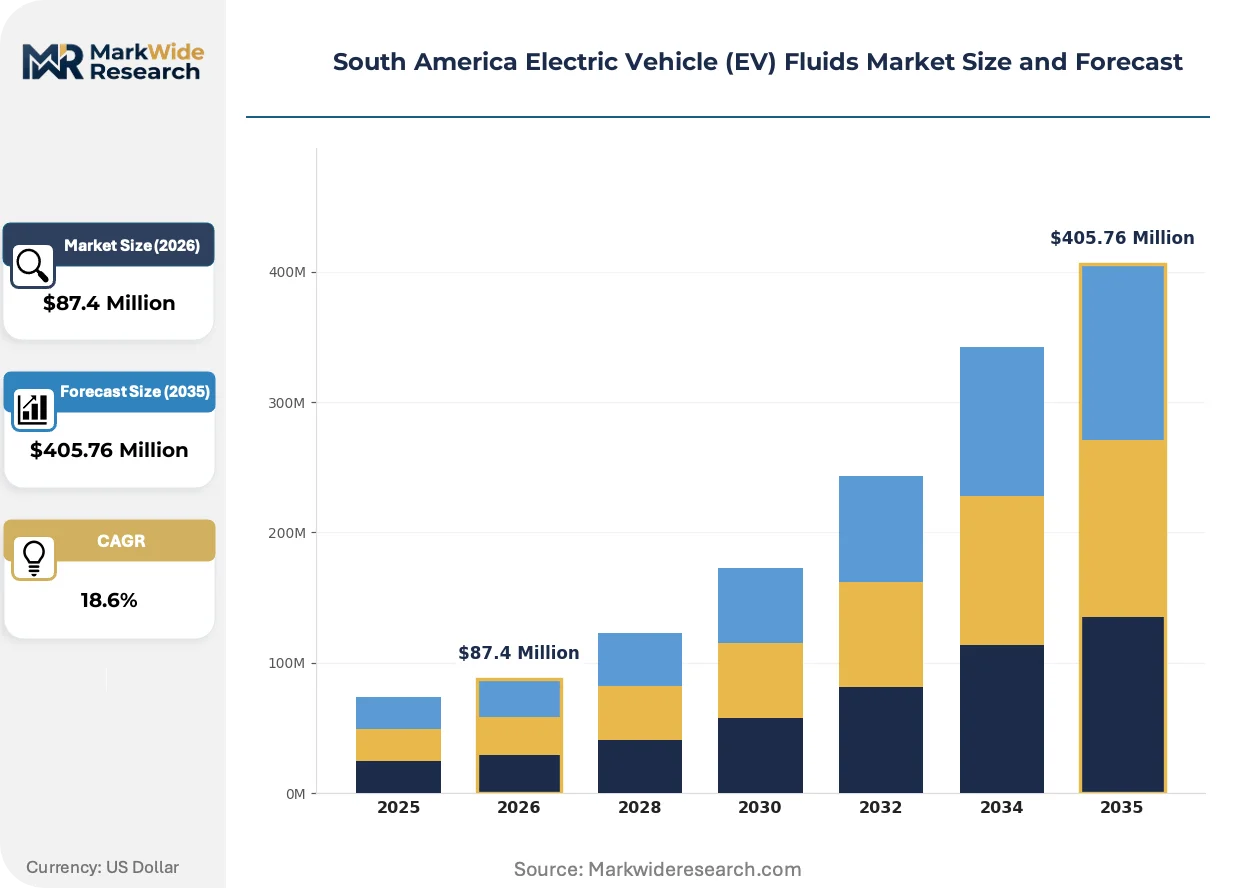
Market Dynamics
Fleet electrification across Brazilian logistics corridors is compressing fluid procurement cycles from annual to quarterly volumes, forcing suppliers to reconfigure distribution networks around São Paulo's OEM service clusters.
Growth Catalysts
- CONAE Protocol Enforcement:Argentina's energy efficiency mandates tighten thermal management standards, compelling coolant reformulation for liquid-cooled battery packs.
- Fleet Operator Procurement:Brazilian last-mile delivery consolidators are standardizing EV fluid specifications across multi-brand vehicle pools.
- Dielectric Fluid Advancement:Synthetic base stocks with enhanced high-voltage stability are extending drain intervals beyond conventional mineral formulations.
Market Restraints
- Import Dependency:Additive package supply concentrates in Asian specialty chemical producers, exposing formulators to currency volatility.
- Biodegradability Validation Costs:ANP biofuel blending mandates intersect with CONMETRO certification, requiring expensive aquatic toxicity testing for coolant chemistries.
- Technical Substitution Risk:Air-cooled battery architectures in entry-level urban mobility segments reduce coolant volume requirements per vehicle.
Strategic Opportunities
- Aftermarket Channel Expansion:Brazil's aging installed EV base is crossing factory fill warranty thresholds, opening independent service center demand.
- INTI Thermal Conductivity Alignment:Argentina's standards institute protocols create first-mover advantage for certified suppliers versus uncertified imports.
- Service Contract Bundling:Fluid-as-a-service models integrating predictive thermal monitoring are penetrating São Paulo fleet management contracts.
Industry Challenges
- Electrification Skill Shortage:Service technicians require high-voltage safety certification alongside fluid handling competency, constraining workshop capacity expansion.
- Multi-Standard Formulation Complexity:Mercosur harmonization delays force parallel product lines for Brazil's ANP requirements versus Argentina's INTI protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle (EV) Fluids Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $405.76 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolants, Lubricants, Brake Fluids, Transmission Fluids End User: OEMs, Aftermarket Providers, Fleet Operators, Service Centers Fluid Grade: Standard, Premium, Synthetic, Biodegradable Application: Cooling System, Brake System, Transmission System, Power System |
| Companies Covered | Shell plc, Exxon Mobil Corporation, TotalEnergies, CASTROL LIMITED, FUCHS, Valvoline Global Operations, BP Plc, Repsol, Petroliam Nasional Berhad (PETRONAS), Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle (EV) Fluids Market Trends and Innovations
Electrified powertrain architectures are redefining fluid performance specifications, with thermal management systems absorbing the largest formulation R&D investment across South American suppliers.
Dielectric coolant technology is fragmenting competitive positioning in the market. These fluids maintain electrical isolation while conducting heat away from battery cells and power electronics. Fleet operators in São Paulo's industrial corridor are specifying OEM-certified grades to preserve warranty coverage. The technology is fragmenting supplier tiers into certified premium formulators versus uncertified commodity producers.
CONAE energy efficiency protocols in Argentina are mandating standardized thermal conductivity testing for all imported EV fluids. Industrial consequence includes exclusion of uncertified Asian imports from formal procurement channels. Battery cooling system suppliers are responding by pre-qualifying only INTI-certified fluid partners in their technical documentation.
Aftermarket procurement patterns are compressing traditional distribution hierarchies. Independent service centers in Brazil are bypassing regional distributors to source directly from formulators with ANVISA-compliant handling certifications. São Paulo's dense OEM service network exhibits the most advanced disintermediation, with fluid suppliers establishing captive last-mile delivery to workshop clusters.
South America Electric Vehicle (EV) Fluids Market Segmentation
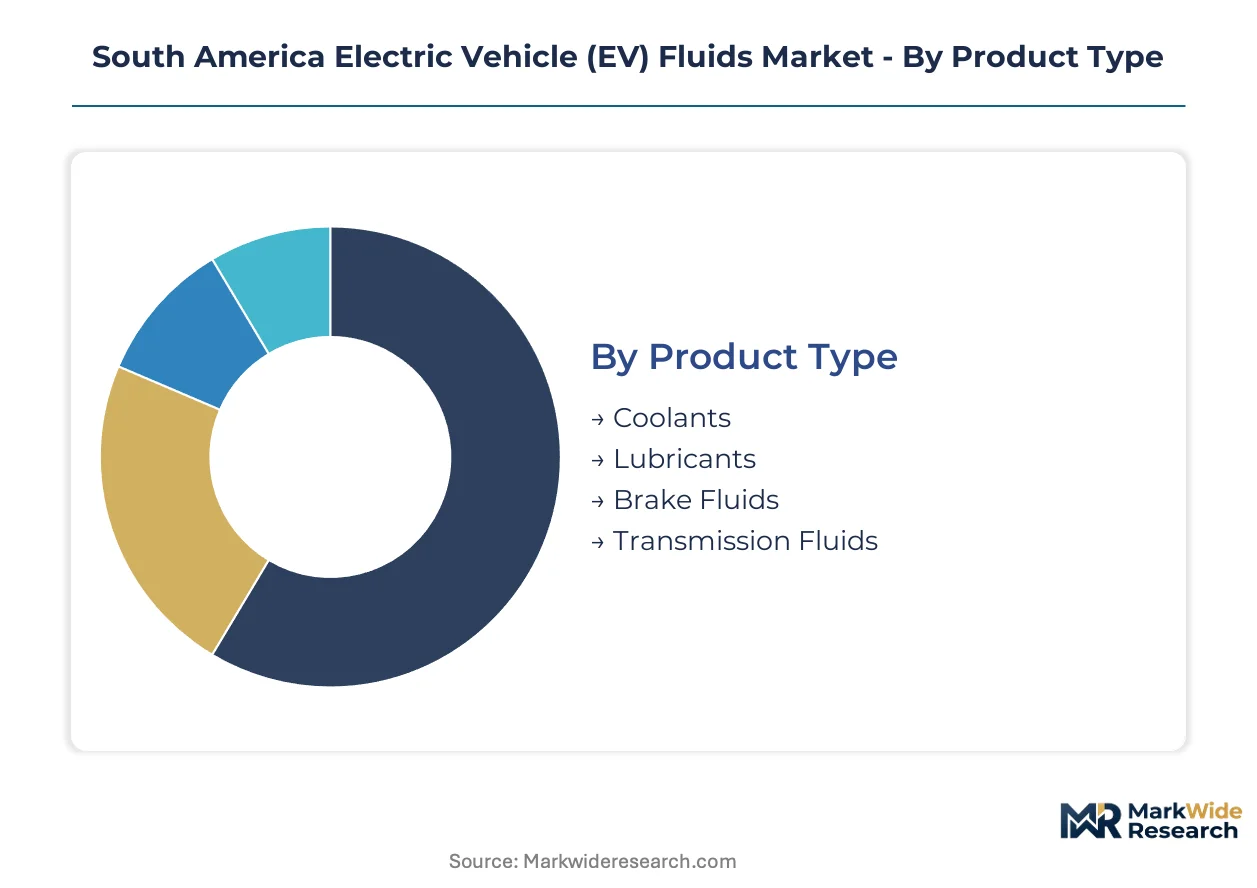
Fluid specifications diverge sharply across South American markets as Brazil's ANP biofuel mandates and Argentina's INTI thermal protocols force parallel formulation tracks. Segment boundaries harden around certification requirements rather than performance alone.
Product Type:
Domestic production concentrates in São Paulo's chemical corridor, while additive packages for premium grades arrive primarily through Argentine import channels.
- Coolants:Dielectric formulations with low electrical conductivity dominate liquid-cooled battery architectures. Fleet operators across Brazil's last-mile logistics corridors specify OEM-certified grades to preserve warranty coverage. ANP biodegradability mandates add validation costs for ethylene glycol alternatives.
- Lubricants:E-axle gearbox fluids require high thermal stability under regenerative braking torque loads. Argentine assembly plants sourcing from Mercosur partners drive specification alignment with European OEM standards. INTI certification filters out uncertified Asian imports.
- Brake Fluids:DOT 4 and DOT 5.1 silicone formulations serve regenerative braking systems in São Paulo's urban mobility fleets.
- Transmission Fluids:Single-speed reduction gearboxes in EVs reduce complexity versus multi-speed architectures, compressing volume per vehicle.
Coolants hold the largest share; momentum sits with lubricants as e-axle complexity rises.
End User:
Procurement cycles compress from annual to quarterly volumes as fleet electrification accelerates, reshaping distributor relationships.
- OEMs:Factory fill specifications lock in multi-year supply agreements with ANVISA-certified formulators. Brazilian passenger vehicle assemblers pre-qualify fluid partners during platform development phases.
- Fleet Operators:Multi-brand standardization across delivery vehicle pools creates bulk purchasing leverage. São Paulo's logistics consolidators negotiate direct supply contracts bypassing traditional distribution tiers.
- Aftermarket Providers:Independent service centers source directly from formulators with compliant handling certifications. Brazil's aging installed EV base crosses warranty thresholds, opening channel expansion.
- Service Centers:High-voltage safety certification requirements constrain workshop capacity expansion across both markets.
Fleet operators command the largest share; aftermarket providers are climbing the fastest as vehicle populations mature.
Fluid Grade:
Margin pools stratify sharply between mineral base stocks and synthetic formulations with extended drain intervals.
- Synthetic:Polyalphaolefin and ester base stocks deliver thermal stability for high-voltage battery cooling loops. OEM warranty compliance requirements lock in premium pricing versus mineral alternatives.
- Biodegradable:ANP mandates intersect with CONMETRO aquatic toxicity testing, validating environmental claims for coolant chemistries. Argentine import protocols favor certified biodegradable grades in public procurement.
- Premium:Semi-synthetic blends occupy middle-tier pricing for independent service centers seeking warranty-safe alternatives.
- Standard:Mineral-based formulations face margin compression as synthetic production scales in regional refineries.
Synthetic grades hold the largest share; biodegradable formulations gain share fastest on regulatory tailwinds.
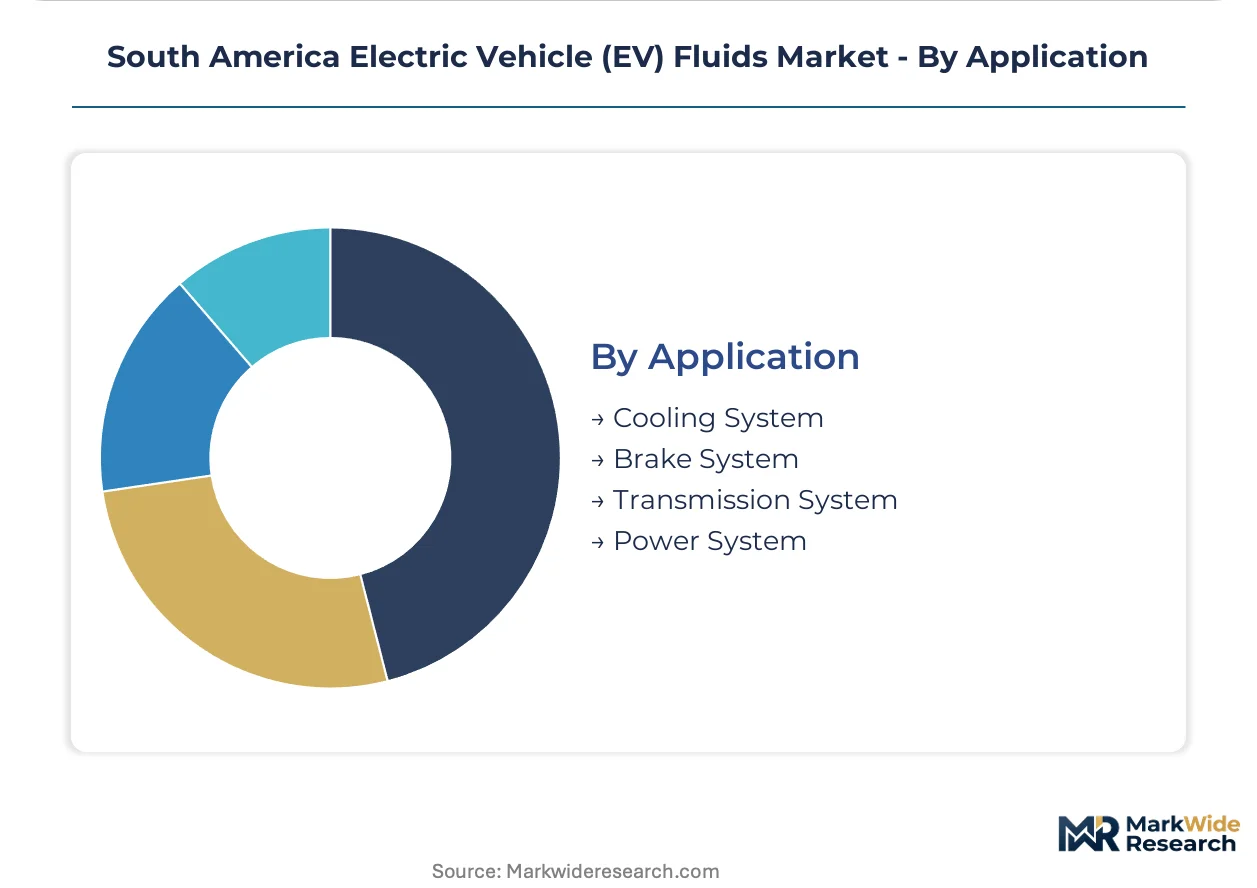
Application:
Thermal management absorbs the dominant formulation investment as liquid-cooled architectures displace air-cooled alternatives.
- Cooling System:Battery pack and power electronics cooling drives dielectric fluid innovation. CONAE protocols in Argentina mandate standardized thermal conductivity testing, excluding uncertified imports.
- Power System:Inverter and onboard charger thermal management requires compatibility with high-voltage isolation standards. Brazilian OEM service networks specify dedicated power electronics coolants separate from battery loops.
- Brake System:Regenerative braking reduces mechanical brake wear but demands hydraulic fluid stability under intermittent thermal cycling.
- Transmission System:E-axle lubrication requirements vary by motor integration architecture, fragmenting specification standards.
Cooling system applications hold the largest share; power system applications show the steepest expansion trajectory as inverter densities rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining capacity clusters in Brazil's São Paulo industrial corridor, while Argentina's INTI-certified laboratories anchor thermal conductivity testing for regional coolant formulations. Chile and Colombia import finished fluid grades through Pacific and Caribbean ports respectively.
Brazil
Fleet electrification across São Paulo's logistics corridors drives quarterly fluid procurement cycles for last-mile delivery operators. ANP biofuel blending mandates intersect with CONMETRO certification requirements, pressuring suppliers to validate biodegradability claims for coolant chemistries. The São Paulo industrial corridor hosts OEM service networks where Shell plc and CASTROL LIMITED maintain captive distribution to workshop clusters.
Argentina
CONAE energy efficiency protocols enforce standardized thermal conductivity testing for all imported EV fluids, filtering out uncertified Asian products. The country's national standards institute mandates pre-qualification of INTI-certified fluid partners in battery cooling system technical documentation. Buenos Aires assembly plants sourcing from Mercosur partners drive specification alignment with European OEM thermal management standards.
Chile
Copper mining electrification initiatives stimulate demand for heavy-duty EV coolant formulations in northern extraction zones. The country's national energy commission promotes lithium-ion battery supply chain integration, indirectly supporting fluid demand for power electronics cooling. Santiago's urban mobility fleet operators specify DOT 4 brake fluids for regenerative braking systems in electric bus deployments.
Colombia
Bogotá's TransMilenio bus rapid transit electrification creates institutional procurement channels for dielectric coolant volumes. The country's national environmental licensing authority enforces aquatic toxicity standards for industrial fluid disposal, favoring biodegradable formulations. Caribbean port infrastructure facilitates import distribution to Andean cities where aftermarket service networks are consolidating.
Uruguay
Montevideo's renewable energy surplus supports grid-tied EV charging infrastructure expansion, indirectly stimulating fluid demand through vehicle stock growth. The country's national oil refinery explores synthetic base stock production partnerships with Brazilian chemical corridors. Mercosur trade protocols enable duty-free fluid movement across the Río de la Plata to Uruguayan fleet operators.
South America Electric Vehicle (EV) Fluids Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the South America Electric Vehicle (EV) Fluids Market. Vertically integrated oil majors leverage captive base oil refining to secure supply reliability across Brazilian distribution channels, while specialty chemical formulators compete on INTI certification speed and biodegradable formulation expertise. Three archetypes dominate: integrated energy conglomerates with backward integration into refining, dedicated lubricant specialists with OEM laboratory partnerships, and regional distributors with ANVISA-compliant handling certifications. Competitive intensity centers on M&A activity targeting Argentine thermal testing capabilities and direct-to-workshop distribution bypassing traditional tiers.
Within the integrated energy tier, Shell plc anchors premium positioning through São Paulo corridor distribution control, while TotalEnergies exemplifies laboratory-centric strategy via dedicated EV fluid facilities in Argentina. CASTROL LIMITED occupies the OEM partnership archetype, aligning specifications with European assembly plants in the Mercosur zone. These three companies represent distinct competitive vectors: refining integration, certification infrastructure, and transnational OEM relationships.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| TotalEnergies |
| CASTROL LIMITED |
| FUCHS |
| Valvoline Global Operations |
| BP Plc |
| Repsol |
| Petroliam Nasional Berhad (PETRONAS) |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between São Paulo fleet operators and ANVISA-certified formulators lock in supply access while anchoring price visibility across quarterly procurement cycles. These arrangements compress working capital exposure for buyers and secure volume commitments for suppliers navigating Argentina's INTI certification costs.
Pricing Analysis
ANP biofuel blending mandates dictate the pricing tier structure by forcing parallel validation tracks for biodegradable coolant chemistries. Three-tier pricing structure across premium synthetic, certified biodegradable, and standard mineral levels reflects CONMETRO aquatic toxicity testing costs and OEM warranty compliance requirements. Cost compression in standard mineral tiers is intensifying as Brazilian refineries scale synthetic base stock production. Fleet operators exhibit highest price sensitivity due to multi-brand standardization pressures, while OEM service networks prioritize certification grade over unit cost.
Supply Chain Analysis
Brazil and Argentina anchor regional EV fluid production through São Paulo's chemical corridor and Buenos Aires assembly plant networks. Formulation draws from Asian specialty chemical producers for additive packages, European base stock suppliers for synthetic grades, and domestic refineries for mineral oils. Single-source vulnerability concentrates in dielectric additive imports exposed to currency volatility. Distribution runs through captive last-mile delivery to OEM workshop clusters in São Paulo, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as Brazil's installed EV base ages beyond factory fill warranty thresholds, opening independent aftermarket demand channels.
For Market Incumbents: Fortify ANVISA-certified handling infrastructure to defend against direct-to-workshop disintermediation by uncertified imports. Deepen backward integration into São Paulo base oil refining to secure margin control as synthetic production scales. Prioritize INTI thermal conductivity certification speed to exclude commodity competitors from Argentine procurement channels. For New Entrants and Emerging Players: Predictive thermal monitoring service gaps in São Paulo fleet management contracts offer white-space entry points. Target aftermarket service centers in Colombia's Andean cities where biodegradable formulation demand outpaces certified supply. Pursue ANVISA compliance partnerships with regional distributors lacking high-voltage fluid handling credentials. For Investors and Strategic Acquirers: Argentine thermal testing laboratories with INTI accreditation represent priority acquisition targets given certification bottleneck dynamics. Long-term viability hinges on Mercosur harmonization outcomes reshaping cross-border formulation standards. Monitor CONAE protocol expansion timelines as inflection indicators for certified supplier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| INTI Certification Investment | Argentina's standards institute protocols create defensive moats against uncertified Asian imports. |
| Backward Integration into Base Oil Refining | São Paulo chemical corridor captive supply secures formulation cost control and volume reliability. |
| Direct-to-Workshop Distribution Buildout | ANVISA-compliant last-mile delivery bypasses distributor tiers in dense OEM service clusters. |
| Biodegradable Formulation R&D Partnership | ANP mandates intersect with CONMETRO testing to validate environmental claims for coolant chemistries. |
| Fleet Service Contract Bundling | Fluid-as-a-service models integrate predictive thermal monitoring into São Paulo logistics contracts. |
Research Methodology
Operator-level perspectives from fleet procurement managers, OEM service network directors, ANVISA compliance officers, and aftermarket workshop owners anchored the qualitative base. Secondary validation drew from ANP regulatory filings, INTI thermal conductivity protocols, CONAE energy efficiency documentation, and Mercosur trade harmonization records. Bottom-up volume estimates from fluid consumption rates per vehicle class triangulated against top-down market sizing from production and import data.
Sensitivity analysis tested forecast robustness across adoption scenario variants over the projection horizon. Segmentation dimensions modeled include fluid type, end-user channel, synthetic versus mineral grade tier, and cooling versus power system application. CAGRs derived from vehicle stock growth curves, drain interval extension trends, and fleet electrification penetration rates across Brazilian logistics corridors and Argentine assembly plant sourcing patterns.
Underlying assumptions cover CONAE protocol enforcement continuity, ANP biodegradability mandate stability, and Mercosur technical standard harmonization progress, with deviation risk concentrated in air-cooled battery architecture substitution and Asian import tariff volatility. Recalibration cycles align with material shifts in fleet electrification procurement patterns and regulatory certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
GCC Electric Vehicle Market