
 India Intra-City Logistics Market | 2026-2036
India Intra-City Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
India Intra-City Logistics Market Foresight
The shift from captive in-house fleets to outsourced, multi-vendor logistics networks is realigning how e-commerce and retail enterprises structure urban fulfillment. Delhivery leverages its technology stack to manage high-velocity sortation across dense metro catchments. Shadowfax anchors the gig-powered last-mile segment with a distributed rider model that flexes with intraday demand spikes. Allcargo Gati competes through its intermodal rail-road connectivity that feeds into final city distribution.
India intra-city logistics encompasses the planning, execution, and control of goods movement within metropolitan boundaries, typically covering radial distances under 100 kilometers using vehicles ranging from two-wheelers to light commercial trucks with payload capacities of 0.5 to 3.5 tonnes. The primary purpose is time-definite fulfillment of business-to-consumer and business-to-business shipments, with service-level agreements dictating delivery windows as narrow as two hours for express segments. Last-mile delivery occupies the largest value pool given its labor intensity and customer-touch frequency, while same-day delivery represents the fastest-expanding service tier as urban consumers prioritize immediacy over cost. Freight transport using trucks sustains higher margins due to contractual volume commitments from enterprise shippers, though motorcycle-based parcel movement dominates unit economics for small-format e-commerce orders.
BIS vehicle safety standards and CEA electrical infrastructure norms shape fleet electrification timelines, while state-level RTO compliance mandates govern commercial vehicle operating permits and emission classifications across Indian cities. The PLI scheme for automobile and auto component manufacturing accelerates domestic EV production, directly affecting total cost of ownership calculations for logistics fleet operators. Stakeholders must monitor how state-level EV policies and charging infrastructure buildouts alter the competitive balance between diesel, CNG, and electric vehicle deployment models.
Market Dynamics
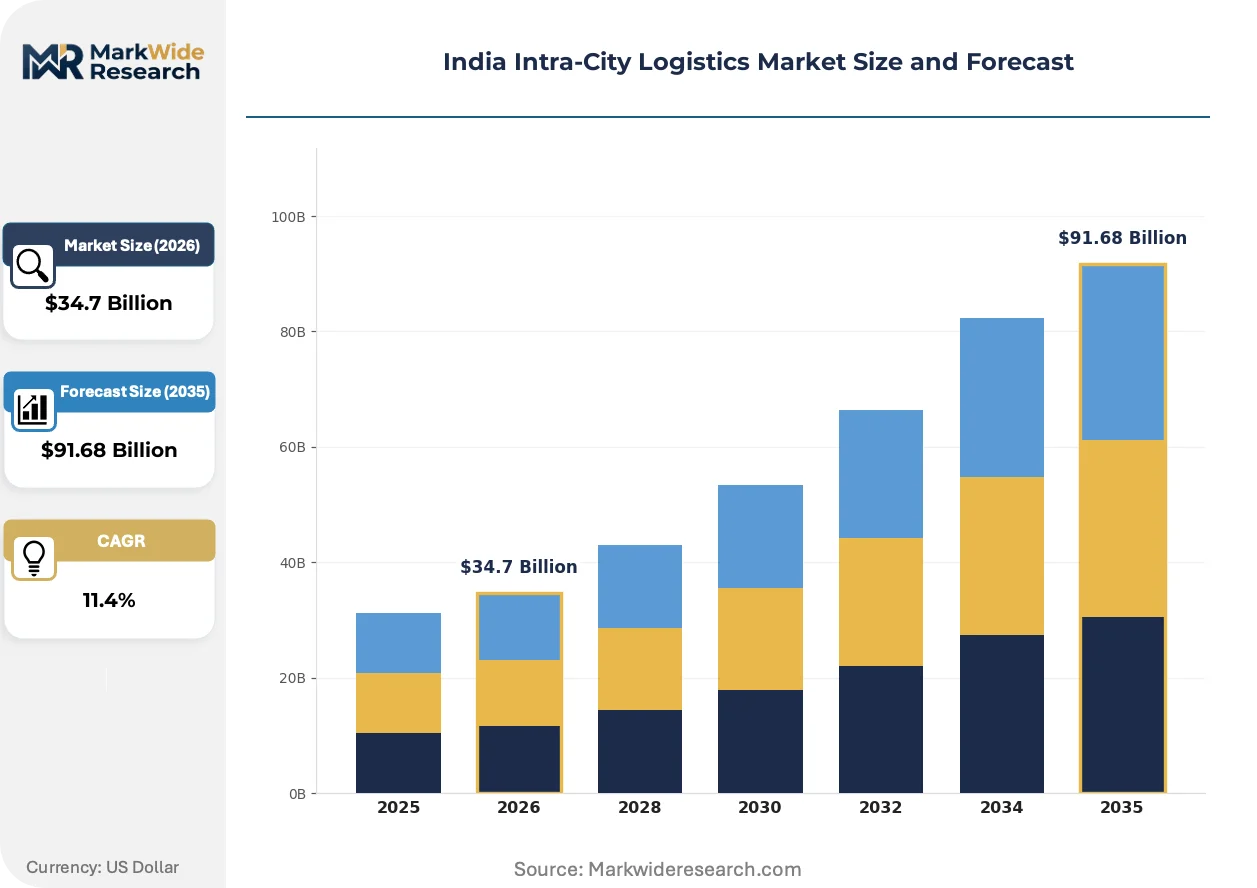
Fleet electrification is compressing total cost of ownership curves across urban delivery networks as the PLI scheme for automobile manufacturing accelerates domestic EV production and state-level RTO emission mandates harden operational compliance thresholds.
Growth Catalysts
- E-commerce Fulfillment Velocity:Same-day delivery SLAs from online retail platforms are pulling dedicated last-mile capacity into dense metro catchments. Mumbai-Pune and Delhi-NCR warehouse clusters concentrate demand pull.
- PLI Scheme for Auto Manufacturing:Production-linked incentives for EV and component manufacturing are lowering acquisition costs for electric two-wheelers and light commercial vehicles. Fleet operators are expanding electric pilot programs.
- BIS Safety Standards:Mandated vehicle safety certifications for commercial transport are standardizing fleet quality. Compliance investments are filtering out informal operators and formalizing market structure.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell and pack supply chains concentrate in East Asian manufacturing hubs. Indian logistics operators face import dependency and currency exposure on critical powertrain components.
- CEA Grid Infrastructure Gaps:Central Electricity Authority norms for commercial charging depots lag fleet electrification timelines. Distribution network upgrades in tier-2 cities remain capital-constrained.
- CNG Price Volatility:Compressed natural gas pricing fluctuates with global LNG benchmarks and domestic subsidy adjustments. Operators with mixed-fuel fleets face margin compression during price spike cycles.
Strategic Opportunities
- Tier-2 City Network Expansion:Underpenetrated urban agglomerations like Indore, Kochi, and Chandigarh lack organized last-mile density. First-mover operators can anchor hub-and-spoke infrastructure ahead of e-commerce saturation.
- Rail-Last-Mile Intermodal:Dedicated freight corridors terminating at city peripheries create white space for electric truck-based final distribution. Allcargo Gati's rail-road model demonstrates transferable architecture.
- State EV Policy Arbitrage:Gujarat, Karnataka, and Tamil Nadu offer accelerated depreciation and road tax waivers for commercial electric vehicles. Fleet registration strategies can optimize incentive capture across state boundaries.
Industry Challenges
- Charging Infrastructure Capex Intensity:Depot electrification requires transformer upgrades, land leasing, and hardware installation. Balance sheet capacity constraints limit mid-size operators from scaling beyond pilot fleets.
- Driver Skill Transition:Electric vehicle operation and basic maintenance training lags deployment timelines. Gig-economy rider pools accustomed to internal combustion platforms require reskilling investments.
- Interstate Permit Fragmentation:State RTO commercial vehicle regulations vary on emission classifications, fitness certification cycles, and cross-border movement permissions. National fleet standardization faces bureaucratic friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Intra-City Logistics Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last-Mile Delivery, Freight Transport, Same-Day Delivery, Express Delivery Vehicle Type: Motorcycle, Van, Truck, Bicycle End User: E-commerce, Retail, Food & Beverage, Healthcare Technology: GPS Tracking, Route Optimization, Mobile Apps, IoT Devices |
| Companies Covered | Ekart Logistics, XpressBees, Delhivery, TCI Express, Ecom Express, Blue Dart Express, DTDC Express, Allcargo Gati, Shadowfax, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Intra-City Logistics Market Shifts & Advancements
Urban logistics infrastructure is bifurcating between asset-heavy electrified hubs and asset-light gig-powered distribution, with technology stacks determining competitive position more than vehicle ownership scale.
Electric two-wheeler fleets with swappable battery architecture are electrifying last-mile parcel economics in Indian metros. E-commerce platforms and quick-commerce operators are deploying these vehicles at scale for sub-5-kilometer delivery radii. The technology is compressing per-stop energy costs and enabling 18-hour operational windows without depot downtime.
The PLI scheme for automobile and auto component manufacturing is hardening domestic EV supply chain foundations. Component localization mandates are pulling battery pack assembly and power electronics manufacturing into Indian industrial corridors. Logistics fleet operators are the immediate beneficiaries through shortened replacement part lead times and reduced import duty exposure.
Quick-commerce platforms are unbundling traditional warehousing from last-mile fulfillment through dark store proliferation in residential micro-markets. Shadowfax's distributed rider model exemplifies the gig-powered response to 10-15 minute delivery promises. Delhi-NCR and Bengaluru are the primary geographies where this consumption pattern shift is most visible, with apartment complexes now expecting dedicated delivery windows.
India Intra-City Logistics Market Segmentation
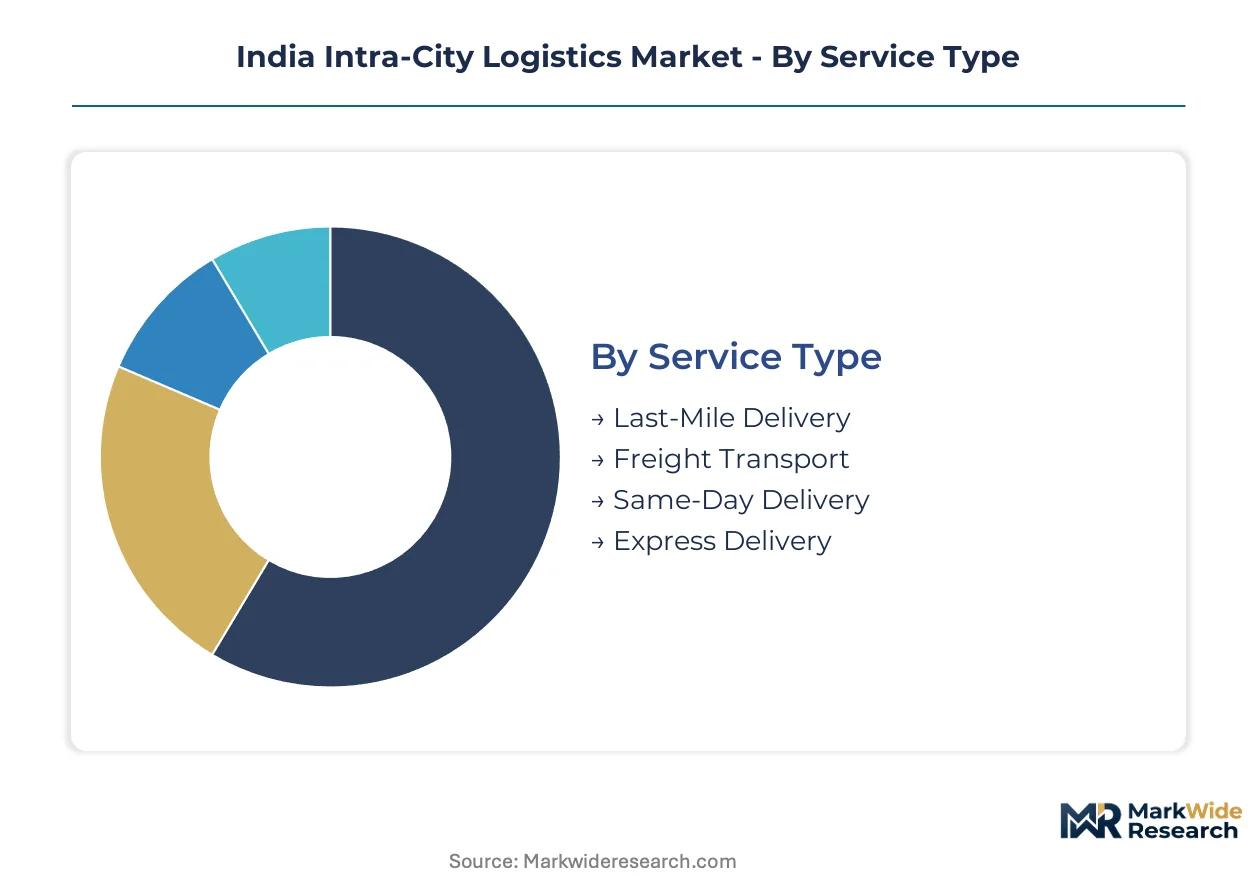
Intra-city logistics operators structure service portfolios around vehicle-technology pairings and end-use velocity requirements. Segmentation discipline separates high-frequency last-mile operations from scheduled freight movements, each demanding distinct fleet configurations and digital infrastructure investments.
Service Type:
Supply concentration in e-commerce fulfillment has pulled capacity investment toward time-definite service tiers, compressing delivery windows from next-day to same-day and express segments.
- Last-Mile Delivery:Final-leg parcel movement from urban distribution hubs to residential and commercial endpoints, typically executed via two-wheeler fleets across sub-5-kilometer radii. Mumbai-Pune and Delhi-NCR warehouse clusters generate the densest route consolidation opportunities, though rider wage inflation and gig-economy churn constrain margin expansion.
- Same-Day Delivery:Order fulfillment within customer-mandated daylight windows, requiring inventory positioning at forward dark stores and predictive demand staging. Quick-commerce platforms in Bengaluru and Hyderabad are pulling dedicated capacity into residential micro-markets, forcing traditional operators to match velocity or cede share.
- Freight Transport:Scheduled business-to-business cargo movement using light commercial trucks and vans, governed by contractual volume commitments rather than on-demand dispatch.
- Express Delivery:Premium-tier shipment handling with narrow two-to-four-hour delivery guarantees, priced at multiples of standard service rates.
Last-Mile Delivery absorbs the bulk of installed capacity; Same-Day Delivery is expanding most quickly.
Vehicle Type:
Cost tier differentiation separates asset-light two-wheeler operations from capital-intensive truck deployments, with electrification timelines varying sharply across vehicle classes.
- Motorcycle:Dominant platform for parcel and food delivery, offering maneuverability through dense urban traffic and minimal parking friction. E-commerce and quick-commerce operators in Delhi-NCR and Bengaluru are electrifying these fleets fastest, driven by state-level EV incentives and BIS safety standard compliance requirements.
- Truck:Light commercial vehicles with 0.5-to-3.5-tonne payloads sustain freight transport margins through enterprise contract density. The PLI scheme for automobile manufacturing is accelerating domestic electric truck availability, though charging infrastructure gaps in tier-2 cities delay widespread deployment.
- Van:Mid-capacity vehicles serving B2B distribution and bulk retail replenishment, positioned between motorcycle agility and truck volume.
- Bicycle:Human-powered option for zero-emission zones and short-radius document or small-parcel movement, concentrated in historic city cores with vehicle access restrictions.
Truck-based freight commands the highest revenue per vehicle; motorcycle fleets are gaining share fastest in parcel delivery.
End User:
Application-specific requirements dictate fleet composition, with e-commerce velocity standards forcing technology and labor model adaptations that other verticals selectively adopt.
- E-commerce:Online retail platforms demanding same-day and next-day fulfillment at scale, with service-level agreements driving investment in sortation automation and rider management systems. Mumbai-Pune corridor warehouse density creates the deepest fulfillment pools, though fulfillment cost absorption remains contested between platforms and logistics providers.
- Food & Beverage:Restaurant and cloud kitchen delivery with sub-30-minute windows, relying on gig-powered motorcycle fleets with real-time order matching. Temperature-controlled packaging requirements and peak-hour demand spikes differentiate operational economics from standard parcel movement.
- Retail:Traditional brick-and-mortar replenishment and click-and-collect services, mixing scheduled van deliveries with on-demand customer fulfillment.
- Healthcare:Pharmaceutical and diagnostic sample transport with chain-of-custody documentation and temperature integrity mandates, governed by CDSCO distribution guidelines.
E-commerce commands the largest logistics spend; Food & Beverage is climbing the fastest on quick-commerce proliferation.
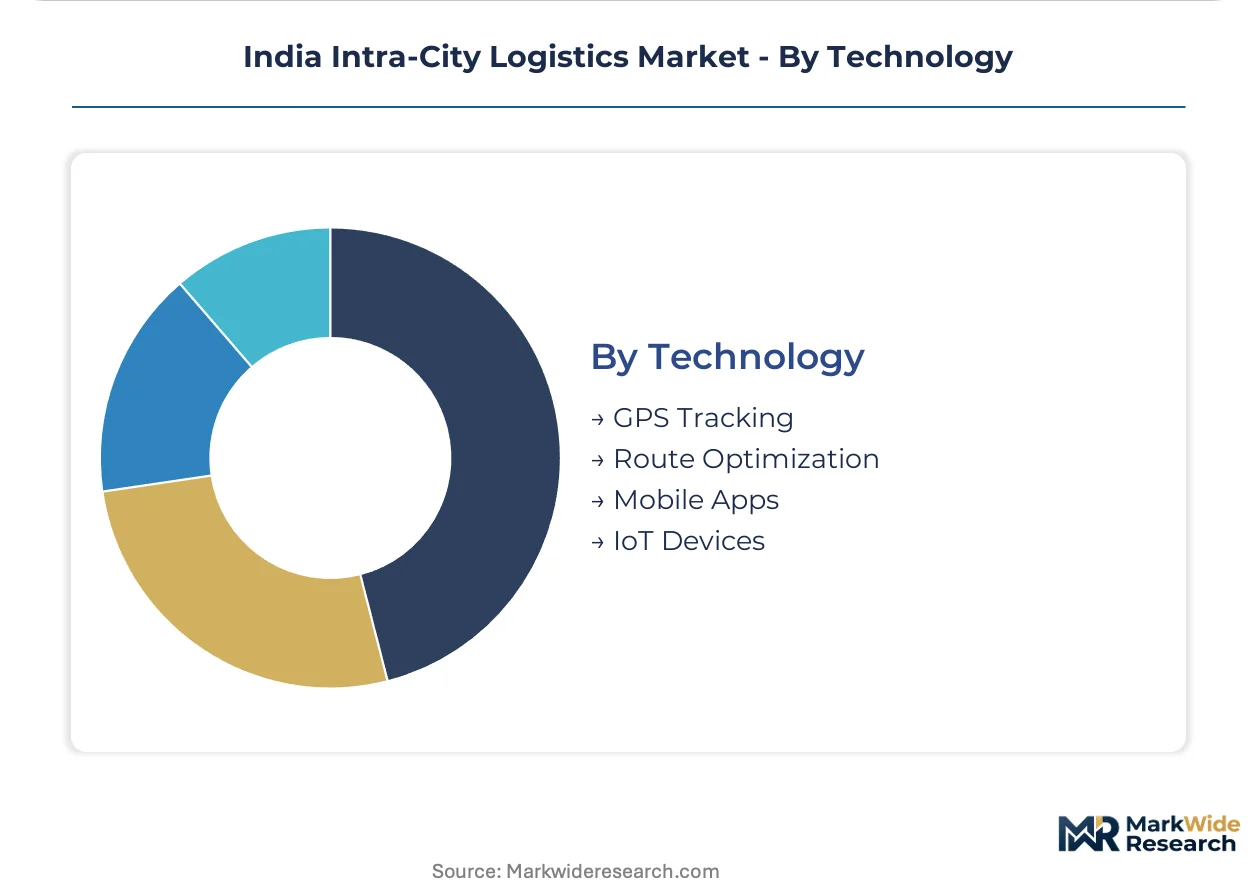
Technology:
Customer type stratification separates enterprise shippers requiring system integration from small merchants using off-the-shelf dispatch tools, with technology stack depth determining competitive position.
- Route Optimization:Algorithmic sequencing of delivery stops to minimize distance and time exposure, with machine learning models incorporating real-time traffic and customer availability windows. Large fleet operators in Delhi-NCR and Bengaluru deploy proprietary systems, while mid-size players license SaaS platforms.
- Mobile Apps:Driver-facing interfaces for order acceptance, navigation, and proof-of-delivery capture, plus customer-facing tracking portals. Gig-economy rider pools depend entirely on app-based dispatch, with platform switching costs low and multi-apping common.
- GPS Tracking:Real-time vehicle location monitoring for fleet visibility and customer communication, now standard across organized operators.
- IoT Devices:Sensor-enabled cargo monitoring for temperature, shock, and tamper detection, concentrated in healthcare and high-value retail verticals.
Route Optimization absorbs the deepest R&D investment; Mobile Apps are penetrating fastest across informal operator formalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diesel refining capacity along the Mumbai-Pune corridor anchors western India's logistics density. Coal-fired thermal belts in Chhattisgarh and Odisha feed eastern freight corridors. The PLI scheme for automobile manufacturing redistributes fleet electrification incentives across state boundaries.
Maharashtra
E-commerce fulfillment centers and quick-commerce dark stores cluster around Mumbai and Pune. The state RTO mandates commercial vehicle fitness certification cycles that compress fleet turnover timelines. The Mumbai-Pune Expressway corridor concentrates warehouse automation investments from organized third-party logistics operators.
Delhi-NCR
Cross-border freight from Haryana and Uttar Pradesh terminates at regional distribution hubs in Gurgaon and Noida. The Delhi government's EV policy mandates last-mile electrification for commercial vehicles entering municipal boundaries. Okhla and Bhiwandi warehouse clusters generate the densest same-day delivery route consolidation in northern India.
Karnataka
Bengaluru's technology sector generates high-value express document and electronics shipment volumes. Karnataka's EV policy offers road tax waivers and accelerated depreciation for commercial electric vehicle registration. The Electronic City and Whitefield industrial corridors attract temperature-controlled logistics capacity for pharmaceutical and biotech verticals.
Gujarat
Port-centric manufacturing in Mundra and Hazira generates containerized freight requiring last-mile distribution into Ahmedabad and Surat. Gujarat's EV policy provides capital subsidies for commercial charging infrastructure deployment. The Delhi-Mumbai Industrial Corridor terminates at Dholera, creating greenfield logistics park opportunities.
Tamil Nadu
Automotive and electronics manufacturing clusters in Sriperumbudur and Oragadam generate scheduled B2B freight demand. Tamil Nadu's EV policy exempts commercial electric vehicles from motor vehicle tax for five years. The Chennai metropolitan area concentrates cold chain logistics capacity for seafood and dairy distribution.
India Intra-City Logistics Market Competitive Landscape
Global majors compete with regional champions across technology integration and fleet electrification timelines. The market structure fragments across asset-heavy integrated operators, asset-light gig-powered platforms, and specialized intermodal providers. Three archetypes dominate: technology-first integrators managing high-velocity sortation, gig-economy aggregators flexing with intraday demand spikes, and rail-road intermodal specialists feeding city peripheries. Competitive moves concentrate on EV fleet pilot scaling and dark store network densification.
Within the technology-integrated tier, Delhivery anchors proprietary sortation automation across dense metro catchments. Shadowfax exemplifies the gig-powered archetype with distributed rider models responding to quick-commerce velocity demands. Allcargo Gati occupies the intermodal position, leveraging rail connectivity into final urban distribution. These three represent distinct strategic bets on electrification timing, labor model structure, and infrastructure ownership intensity.
| Leading Market Players |
|---|
| Ekart Logistics |
| XpressBees |
| Delhivery |
| TCI Express |
| Ecom Express |
| Blue Dart Express |
| DTDC Express |
| Allcargo Gati |
| Shadowfax |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up logistics specialists anchor fleet ownership patterns across Indian metros, compressing per-kilometer rates through asset utilization discipline while externalizing charging infrastructure costs to third-party depot operators. This ownership structure tightens pricing discipline in Mumbai-Pune and Delhi-NCR corridors where warehouse density enables route consolidation economies.
Pricing Analysis
Warranty and service bundling separates premium fleet contracts from unbundled spot-market transactions, with annual maintenance contracts and battery replacement guarantees commanding 15-20% rate premiums over bare-metal leasing. Three-tier pricing structure across premium, standard, and economy levels stratifies by vehicle technology—electric two-wheelers with swappable batteries sit at premium tiers, CNG mid-capacity vans occupy standard bands, and aging diesel trucks populate economy segments. Pricing pressure stems from gig-economy rider wage inflation and state-level EV mandate compliance costs. Quick-commerce platforms exhibit lowest price sensitivity due to 10-15 minute SLA premiums, while traditional retail replenishment buyers negotiate hardest on per-kilometer rates.
Supply Chain Analysis
Dual-sourcing requirements from enterprise shippers mandate logistics operators qualify battery pack suppliers across at least two vendor relationships, buffering against lithium-ion cell concentration in China, South Korea, and Japan. Domestic EV component manufacturing draws from the PLI scheme for automobile and auto component manufacturing, though power electronics and battery management systems still rest on East Asian import channels. Single-source vulnerability concentrates in lithium carbonate refining and permanent magnet motors. Distribution runs through hub-and-spoke configurations terminating at city-periphery railheads, with final-mile legs executed via franchised depots or gig-powered rider pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where fleet operators are pursuing captive charging infrastructure to lock in energy cost advantages against grid-tariff volatility and third-party depot margin extraction.
For Market Incumbents: Lock in dark store real estate ahead of quick-commerce saturation in Bengaluru and Hyderabad micro-markets. Secure multi-year battery supply agreements with PLI-qualified domestic assemblers to buffer against lithium-ion import dependency and currency exposure. Shadowfax's distributed rider model demonstrates how gig-economy labor pools resist vertical integration, making technology stack differentiation the priority lever against asset-heavy competitors. For New Entrants and Emerging Players: Enter via temperature-controlled pharmaceutical distribution in Chennai and Hyderabad, where CDSCO compliance requirements and cold chain infrastructure gaps create defendable moats. Target healthcare and diagnostic sample transport segments where chain-of-custody documentation mandates favor specialized operators over generalist parcel carriers. A licensing partnership with established hospital networks offers the fastest go-to-market path against entrenched incumbents. For Investors and Strategic Acquirers: State EV policy arbitrage across Gujarat, Karnataka, and Tamil Nadu is the leading indicator that fleet registration strategies can extract 15-20% total cost of ownership advantages through accelerated depreciation and road tax waivers. Viable acquisition targets include mid-size operators with depot electrification pilots and established state RTO compliance track records. Watch for charging infrastructure capex intensity forcing distressed exits among operators that overextended on transformer upgrades and land leasing without matching revenue commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Electrification | CEA grid compliance and BIS safety standards harden competitive moats for early movers in Delhi-NCR. |
| Rail-Last-Mile Intermodal | Dedicated freight corridor terminations at city peripheries enable Allcargo Gati's transferable hub-and-spoke architecture. |
| Dark Store Network Densification | Quick-commerce 10-15 minute SLAs pull inventory positioning into residential micro-markets ahead of e-commerce saturation. |
| Gig-Economy Rider Platform | Shadowfax's distributed model flexes with intraday demand spikes without fixed labor cost absorption. |
| State EV Policy Arbitrage | Gujarat and Tamil Nadu road tax waivers compress total cost of ownership for commercial electric vehicle fleets. |
Research Methodology
Document review covered PLI scheme filings, state RTO commercial vehicle regulations, CEA grid infrastructure norms, and BIS safety certifications, complemented by interviews with fleet operations directors at third-party logistics providers, quick-commerce supply chain heads, EV component procurement managers, and charging infrastructure developers. Secondary validation drew from Central Electricity Authority distribution network reports, Ministry of Road Transport emission compliance databases, and customs import records for lithium-ion cells. Bottom-up fleet size estimates triangulated against top-down e-commerce fulfillment volume projections across the analysis window.
Historical utilization rates and panel input from logistics operators were cross-referenced to model segment-level growth trajectories across service type, vehicle technology, end-use vertical, and regional warehouse cluster dimensions. CAGRs were derived from trend extrapolation of same-day delivery SLA penetration, EV fleet pilot scaling timelines, and quick-commerce dark store deployment velocity. Industry-specific forecast inputs included state-level EV incentive sunset clauses and BIS safety standard compliance phase-in schedules.
Revisions become necessary when lithium-ion supply chain disruptions, CEA grid infrastructure delays, or state RTO emission mandate accelerations materially alter fleet electrification economics. A model refresh is warranted upon material change in PLI scheme localization requirements or quick-commerce platform consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Czech Republic Road Freight Transport Market