
 Global Industrial Electric Vehicle Market | 2026-2036
Global Industrial Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Electric Vehicle Market Intelligence
Technician expertise in high-voltage battery systems and diagnostics is rotating from a niche skill toward a core requirement for equipment maintenance providers. BYD Company Ltd. leverages its extensive battery manufacturing capabilities to offer integrated solutions for material handling equipment. Volkswagen Group extends its modular electric platform strategy to influence industrial vehicle designs within its logistics network. This technology transfer from the automotive sector pressures incumbent industrial equipment manufacturers.
Industrial electric vehicles are mobile machines powered by onboard batteries, designed for material handling and logistics within contained commercial or industrial environments. They utilize high-torque electric motors for zero tailpipe emissions, serving to enhance productivity and safety in applications from warehouse operations to port logistics. Lithium-ion batteries are rapidly displacing lead-acid technology due to superior energy density and lifecycle costs. Among vehicle types, electric forklifts constitute a mature segment, while automated guided vehicles show the highest growth potential.
Regulations from the U.S. Environmental Protection Agency (EPA) on indoor air quality incentivize shifts from internal combustion engines. In Europe, the Machinery Directive governs safety standards for CE marking, while China's 'dual carbon' goals provide policy support for industrial electrification. Stakeholders must now decide whether to retrofit existing fleets or invest in new, purpose-built electric platforms with integrated automation.
Market Dynamics
The convergence of advanced lithium-ion battery technology and stringent global regulations on indoor air quality is the central force reshaping the industrial electric vehicle market. This dynamic compels operators to move beyond simple equipment replacement toward a complete rethinking of warehouse and logistics workflows.
Growth Catalysts
- Regulatory Mandates:Regulations from bodies like the U.S. Environmental Protection Agency (EPA) on indoor air quality create powerful incentives for facilities to transition from internal combustion engines to zero-emission electric alternatives, particularly in enclosed spaces like warehouses and distribution centers.
- Battery Technology Advancement:Continuous improvements in the energy density of lithium-ion batteries enable longer operational hours and faster charging times. This reduces vehicle downtime and closes the performance gap with fossil-fueled counterparts, making electric options more viable for multi-shift operations.
- National Industrial Policies:Government initiatives, such as China's 'dual carbon' goals and Germany's support for manufacturing modernization under the EU Green Deal, provide policy support and subsidies that accelerate the adoption of electric industrial vehicles within their extensive manufacturing and logistics sectors.
Market Restraints
- High Initial Capital Outlay:The upfront investment for new, purpose-built electric industrial vehicles and the requisite charging infrastructure is substantially higher than for traditional internal combustion engine models, posing a significant barrier for smaller enterprises or those with tight capital budgets.
- Infrastructure Deficiencies:Many older industrial facilities and warehouses lack the electrical infrastructure required to support large fleets of high-voltage electric vehicles, necessitating costly and time-consuming site upgrades to install sufficient charging capacity.
- Battery Supply Chain Concentration:The global supply of high-performance lithium-ion battery cells is heavily concentrated in a few countries in Asia. This creates vulnerability to geopolitical tensions, trade policy shifts, and logistical disruptions, which can impact vehicle availability and cost.
Strategic Opportunities
- Integrated Automation Systems:There is a significant opportunity in offering fully integrated solutions that combine automated guided vehicles (AGVs) with warehouse management software (WMS) and robotics, providing a seamless, highly efficient system for material flow from receiving to shipping.
- Specialized Vehicle Development:Designing industrial EVs for niche, high-value applications such as cold storage facilities, cleanrooms for pharmaceuticals or electronics manufacturing, and hazardous environments can command premium pricing and create a strong competitive moat.
- Battery-as-a-Service (BaaS) Models:Offering batteries on a subscription or leasing basis can lower the initial purchase price of the vehicle, making electric technology more accessible. This model also creates recurring revenue streams and simplifies battery lifecycle management for the end-user.
Industry Challenges
- Technical Skill Gaps:A shortage of technicians with expertise in diagnosing and servicing high-voltage DC power systems, complex battery management systems, and vehicle control software creates a bottleneck for maintenance and repair, leading to increased equipment downtime.
- Interoperability and Standardization:The lack of industry-wide standards for charging connectors, communication protocols, and battery formats across different manufacturers complicates the management of mixed fleets and leads to vendor lock-in for customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Electric Vehicle Market |
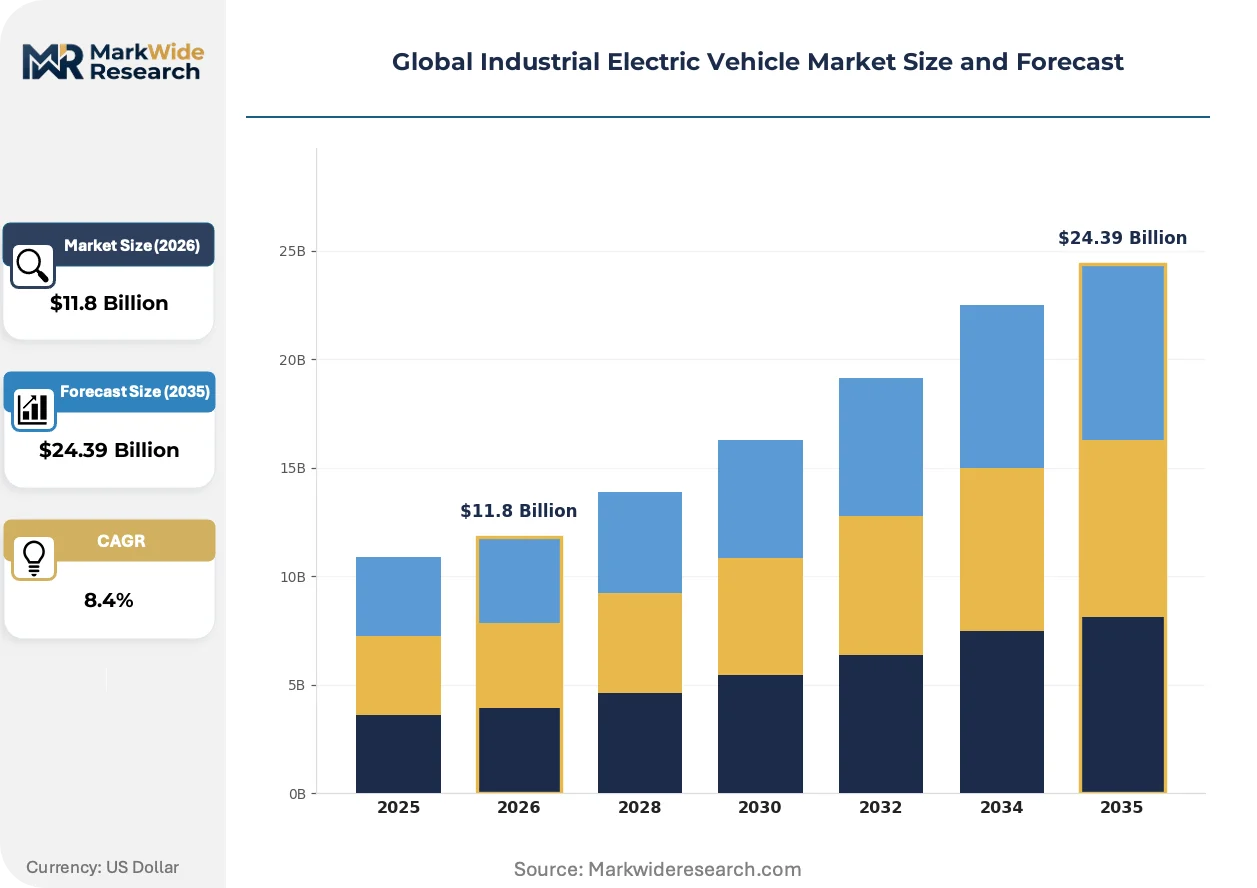
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Forklift, Battery Electric Tractor, Automated Guided Vehicle, Electric Utility Cart, Electric Pallet Jack Power Source: Lithium-ion Battery, Lead Acid Battery, Nickel-Metal Hydride Battery, Solid State Battery, Supercapacitor Application: Warehouse Operations, Material Handling, Port Logistics, Construction Sites, Mining Facilities End User Industry: Manufacturing Plants, Distribution Centers, Agricultural Enterprises, Energy Production Facilities, Food Processing Units |
| Companies Covered | Tesla, BYD Company Ltd., Volkswagen Group, General Motors, Zhejiang Geely Holding Group, Hyundai Motor Group, BMW, Mercedes-Benz, Kia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Electric Vehicle Market Strategic Shifts & Innovations
The market is defined by a fundamental transition from purely mechanical systems to software-defined, connected machines. This evolution influences not only vehicle design but also operational models, maintenance protocols, and the competitive hierarchy among equipment manufacturers and technology providers.
Technology Bifurcation
Lithium-ion battery chemistry provides superior energy density, longer cycle life, and faster charging capabilities compared to legacy lead-acid technology. Large-scale logistics and retail distribution centers are rapidly adopting this technology to support high-throughput operations. This advancement is bifurcating the market between new, high-performance electric platforms and lower-cost equipment, often with less advanced battery systems, for less intensive applications.
Regulatory-Driven Safety Integration
Europe's Machinery Directive, which governs the requirements for CE marking, is compelling manufacturers to integrate more sophisticated safety systems. This directive results in the standard inclusion of features like pedestrian detection, automated braking, and load stability monitoring. Automated Guided Vehicles (AGVs) are most impacted, as their autonomous operation within European facilities demands strict compliance with these enhanced safety protocols.
Fleet-as-a-Service Adoption
A notable shift toward usage-based fleet acquisition models is altering traditional purchasing behaviors. This trend disrupts the standard capital expenditure purchase by allowing customers to pay for vehicle access and performance through subscription contracts that bundle maintenance, software, and battery management. This model is gaining the most traction within the highly competitive third-party logistics (3PL) sector in North America.
Global Industrial Electric Vehicle Market Segmentation
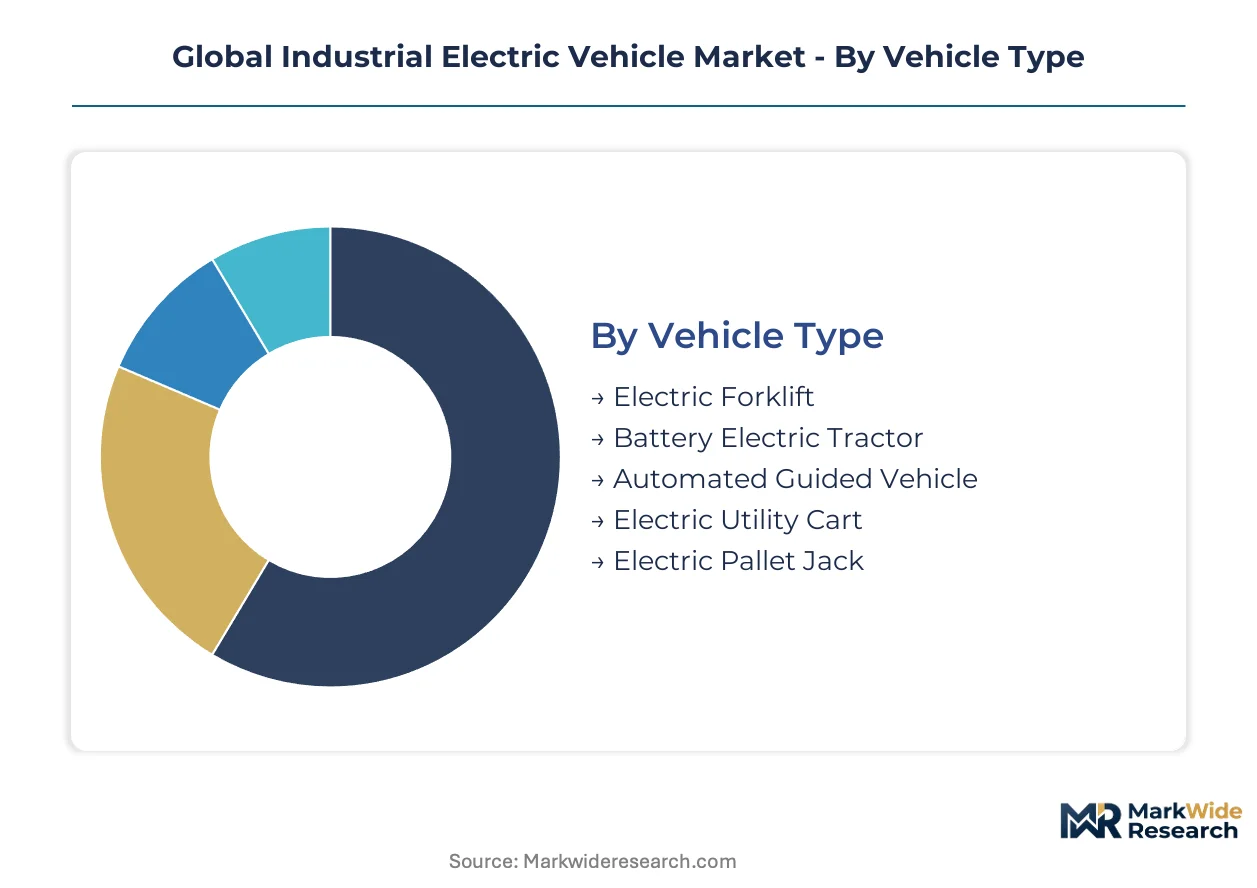
Segmenting the industrial electric vehicle market by vehicle type, power source, application, and end-user industry reveals distinct demand patterns and technological preferences. This granular analysis is crucial for understanding specific operational requirements and investment priorities across diverse industrial environments.
Vehicle Type:
The distribution of industrial electric vehicles often aligns with specific operational workflows, dictating the most suitable vehicle types for material movement within facilities.
- Electric Forklift:These vehicles are standard for lifting and transporting heavy loads in warehouses, utilizing electric motors for quiet, emission-free operation. Demand concentrates in large distribution centers across Germany, driven by stringent indoor air quality regulations.
- Automated Guided Vehicle:AGVs are autonomous systems designed for repetitive material transport on predefined paths, integrating with warehouse management software. Their expansion concentrates in advanced logistics hubs in the US, where labor cost reduction is a primary driver.
- Battery Electric Tractor:These robust vehicles are engineered for towing heavy loads over long distances within industrial complexes, supporting efficient inter-facility logistics.
- Electric Utility Cart:Compact electric carts are used for personnel transport and light material delivery across various industrial sites, enhancing operational efficiency.
- Electric Pallet Jack:Essential for horizontal movement of palletized goods, these electric jacks improve ergonomic conditions for workers in retail backrooms and small warehouses.
Electric Forklifts dominate the installed base of industrial electric vehicles. Automated Guided Vehicles are where expansion concentrates.
Power Source:
The maturity and technological advancement of power sources directly influence the performance characteristics and total cost of ownership for industrial electric vehicles.
- Lithium-ion Battery:These batteries offer high energy density and extended cycle life, enabling longer operational shifts and rapid charging capabilities. Adoption is accelerating in high-throughput warehouse operations in China, driven by efficiency demands.
- Solid State Battery:Representing a next-generation technology, solid-state batteries promise higher energy density, improved safety, and faster charging compared to liquid electrolyte counterparts. Research and development efforts are concentrating in Japan, aiming for breakthrough industrial applications.
- Lead Acid Battery:A mature and cost-effective battery technology, lead-acid batteries provide reliable power for less intensive industrial electric vehicle applications.
- Nickel-Metal Hydride Battery:These batteries offer a balance of energy density and cycle life, finding niche applications where specific performance profiles are required.
- Supercapacitor:Supercapacitors provide rapid charge and discharge cycles, primarily used in hybrid systems or for applications requiring bursts of power.
Lithium-ion Batteries command a significant market share due to their performance advantages. Solid State Batteries demonstrate the steepest expansion trajectory for future power solutions.
Application:
The specific operational environment and the primary demand drivers dictate the suitability and deployment patterns of industrial electric vehicles across various applications.
- Warehouse Operations:Industrial electric vehicles are fundamental for efficient material flow, order picking, and storage within large-scale warehouse facilities. Demand is particularly strong in e-commerce fulfillment centers in the US, driven by automation targets.
- Material Handling:This segment encompasses a wide range of tasks involving the movement, storage, control, and protection of materials throughout manufacturing and distribution processes. Its expansion concentrates in automotive manufacturing plants in Germany, where lean production principles are paramount.
- Port Logistics:Electric vehicles are increasingly utilized in port environments for container handling and cargo movement, supporting emission reduction goals.
- Construction Sites:Electric heavy equipment on construction sites reduces noise pollution and local emissions, particularly for indoor or urban projects.
- Mining Facilities:Specialized electric vehicles are employed in underground mining to improve air quality and reduce operational costs associated with ventilation systems.
Warehouse Operations currently account for the largest volume of industrial electric vehicle deployments. Material Handling represents the highest value opportunity due to diverse equipment requirements.
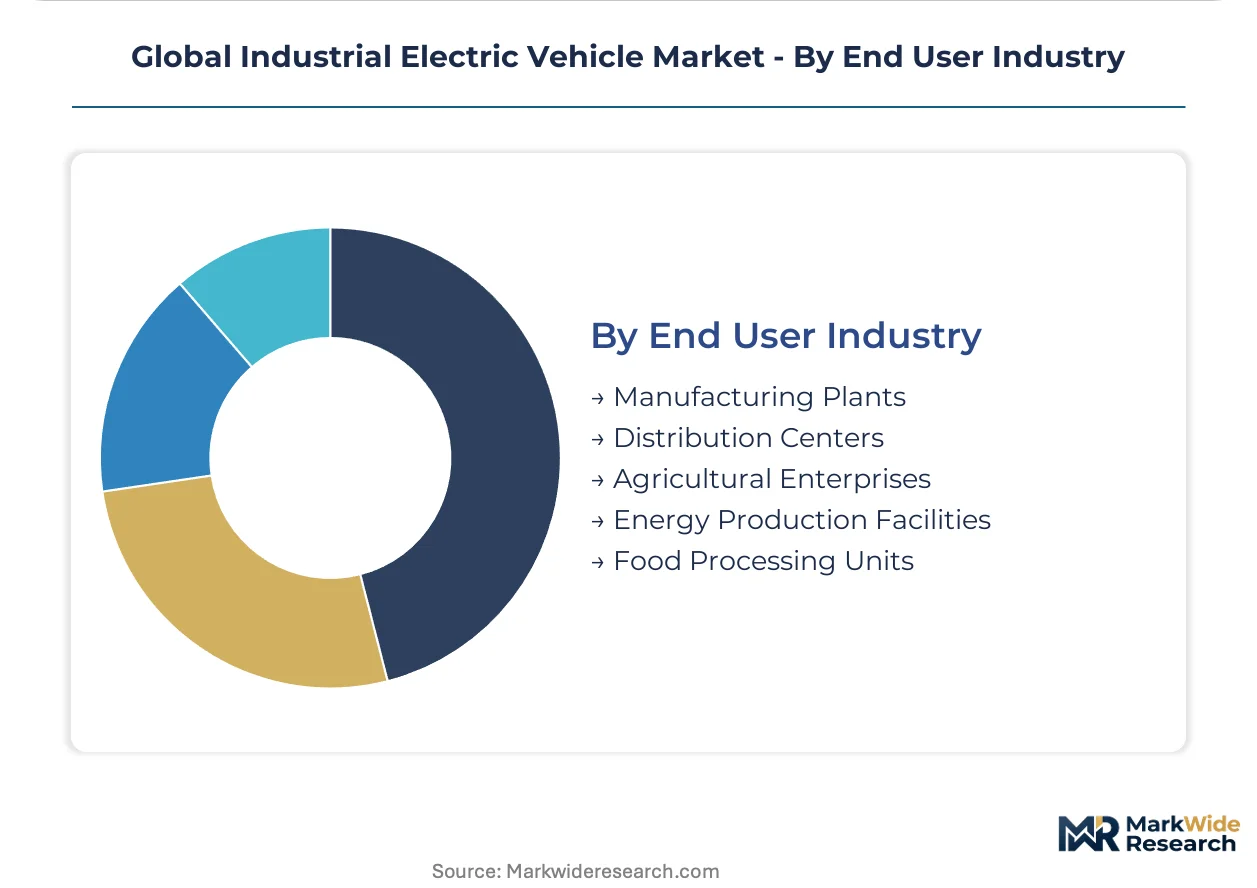
End User Industry:
Regulatory compliance and the investment capacity within each end-user industry significantly influence the adoption rates and technological sophistication of industrial electric vehicles.
- Manufacturing Plants:These facilities utilize industrial electric vehicles for internal logistics, assembly line support, and finished goods transport. Adoption is robust in automotive and electronics manufacturing in South Korea, driven by efficiency and sustainability mandates.
- Distribution Centers:Distribution centers rely on electric vehicles for rapid material movement, order fulfillment, and cross-docking activities to meet tight delivery schedules. Expansion is accelerating in large retail distribution networks in the UK, responding to e-commerce growth.
- Agricultural Enterprises:Electric utility vehicles and smaller tractors are finding applications in agricultural settings for quieter operations and reduced emissions.
- Energy Production Facilities:Industrial electric vehicles are used for maintenance, personnel transport, and material handling within power plants and renewable energy sites.
- Food Processing Units:Electric vehicles ensure hygienic operations and minimize contamination risks in temperature-controlled food processing and storage environments.
Manufacturing Plants exhibit a mature market for industrial electric vehicles with established operational models. Distribution Centers are driving innovation through the integration of advanced automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal, a comprehensive regulatory framework, significantly influences the adoption of industrial electric vehicles across Europe. The U.S. Environmental Protection Agency (EPA) also drives demand through indoor air quality regulations. China's 'dual carbon' goals provide substantial policy support for industrial electrification.
Germany
Germany's extensive manufacturing base creates strong demand for industrial electric vehicles, especially in material handling. The EU Green Deal and the Machinery Directive compel manufacturers to integrate advanced safety features. Automotive manufacturing plants in Bavaria, a key industrial cluster, are rapidly modernizing their internal logistics with electric fleets.
United States
In the United States, e-commerce fulfillment centers are a primary demand driver for electric forklifts and automated guided vehicles. U.S. Environmental Protection Agency (EPA) regulations on indoor air quality incentivize the shift from internal combustion engines. Advanced logistics hubs in California are spearheading the integration of these electric systems to enhance operational efficiency.
China
China's high-throughput warehouse operations and efficiency demands accelerate the adoption of lithium-ion battery-powered industrial vehicles. The country's 'dual carbon' goals provide robust policy support and subsidies for industrial electrification. Large distribution centers in the Yangtze River Delta region are rapidly deploying advanced electric material handling solutions.
South Korea
South Korea exhibits strong demand for industrial electric vehicles driven by efficiency and sustainability mandates in its advanced manufacturing sector. National industrial policies support the modernization of factory logistics with electric fleets. Automotive and electronics manufacturing facilities in the Seoul Capital Area are leading the deployment of these technologies.
The United Kingdom
The United Kingdom's rapid e-commerce growth and expanding retail distribution networks fuel demand for electric vehicles in rapid material movement and order fulfillment. Environmental regulations and policy support for logistics modernization encourage fleet electrification. Large retail distribution networks around London are actively integrating automated electric solutions to meet tight delivery schedules.
Global Industrial Electric Vehicle Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global industrial electric vehicle market. The market structure is evolving, characterized by a tiered approach where some companies focus on high-performance, integrated solutions while others target cost-effective, foundational equipment. Strategic archetypes include specialized industrial equipment manufacturers, automotive giants leveraging EV platforms, and dedicated battery technology providers. Competitive moves center on strategic partnerships for technology integration and portfolio diversification to capture varied customer needs.
BYD Company Ltd. represents integrated solutions, leveraging its extensive battery manufacturing capabilities to offer comprehensive material handling equipment. Volkswagen Group exemplifies automotive companies extending their modular electric platform strategy to influence industrial vehicle designs within their logistics networks. General Motors also occupies a position among traditional automotive players, signaling a broader industry shift towards electric solutions. These companies often bring significant R&D capabilities and established supply chains to the industrial electric vehicle sector.
| Leading Market Players |
|---|
| Tesla |
| BYD Company Ltd. |
| Volkswagen Group |
| General Motors |
| Zhejiang Geely Holding Group |
| Hyundai Motor Group |
| BMW |
| Mercedes-Benz |
| Kia |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts for lithium-ion battery cells lock in both supply access and price visibility for industrial electric vehicle manufacturers. This contract structure mitigates volatility from raw material markets, providing stability for vehicle production planning. However, it also creates rigidity in adapting to rapid technological shifts in battery chemistry.
Pricing Analysis
Geographic price spreads for industrial electric vehicles reflect regional manufacturing costs and regulatory compliance burdens. The dominant pricing model is a value-based approach, often incorporating a premium for advanced features like integrated automation and enhanced safety certifications. Price differentiation stems from battery chemistry (lithium-ion vs. lead-acid) and the level of after-sales service bundling. Pricing softness reflects intense competition from traditional internal combustion engine alternatives, particularly for lower-intensity applications. Smaller enterprises exhibit higher price sensitivity, while large logistics operators prioritize total cost of ownership over initial capital outlay.
Supply Chain Analysis
Inbound logistics costs, particularly for high-performance lithium-ion battery cells, are influenced by shipping routes from Asia and container availability. The supply of these critical components concentrates heavily in China, South Korea, and Japan. Raw material dependencies include lithium, cobalt, and nickel, which are subject to commodity price volatility. A structural supply chain risk is single-source vulnerability for specialized motor components or control electronics. Downstream, the dominant distribution model runs through established industrial equipment dealerships and direct sales channels, often bundled with maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant service-attach opportunity, with Battery-as-a-Service (BaaS) models expanding faster than hardware sales. BaaS offers recurring revenue streams and simplifies battery lifecycle management for end-users, enhancing total value proposition.
For Market Incumbents: Consolidate market share by integrating advanced software and automation capabilities into existing vehicle platforms. This approach counters the threat from automotive giants leveraging their EV platforms and addresses rising customer demand for integrated solutions. Invest in vertical integration for critical components like electric motors and control systems to secure supply and manage costs.
For New Entrants and Emerging Players: Differentiate on specialized vehicle development for niche, high-value applications such as cold storage or cleanrooms. This strategy targets underpenetrated segments with specific performance requirements, allowing for premium pricing. A strong go-to-market angle involves offering comprehensive Battery-as-a-Service models, reducing initial capital outlay for customers in North America's 3PL sector.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized industrial equipment manufacturers with strong intellectual property in automation software or advanced battery management systems. These companies possess the technical expertise required for next-generation industrial electric vehicles. A signal to watch is the widespread adoption of standardized charging protocols, indicating market maturity and reduced infrastructure risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and enables faster product development cycles across vehicle types. |
| Battery Supply Agreements | Secures long-term access to critical lithium-ion cells and mitigates raw material price volatility. |
| Software-Defined Vehicle Investment | Enhances vehicle functionality, enables over-the-air updates, and integrates with warehouse management systems. |
| Niche Vehicle Development | Addresses specific operational requirements in high-value segments like cold storage or hazardous environments. |
| Battery-as-a-Service Rollout | Lowers customer acquisition costs and creates predictable, recurring revenue streams for manufacturers. |
Research Approach
Operator-level perspectives from warehouse managers, logistics directors, industrial equipment procurement leads, and battery engineers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary validation from EPA reports, EU Green Deal documents, company financial filings, and industry association reports. This dual approach ensured both bottom-up granular insights and top-down market validation.
Sensitivity analysis framed the forecast framework, modeling market dynamics across the projection horizon. Segmentation dimensions modeled included vehicle type, power source, application, end-user industry, and regional policy support. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected future adoption rates. Industry-specific forecast inputs included lithium-ion battery cost trends and regulatory enforcement levels for indoor air quality.
The analysis sits within stated boundaries; outcomes outside major geopolitical events impacting supply chains or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions documented regarding market growth drivers and regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market