
 Electric Vehicle Thermal Management Market | 2026-2036
Electric Vehicle Thermal Management Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Thermal Management Market Analysis
A capital-intensity divergence between integrated thermal module suppliers and component specialists is rotating competitive advantage toward full-system architects. DENSO Corporation leverages its power electronics heritage to bundle inverter cooling with battery thermal loops. MAHLE GmbH anchors European OEM relationships through localized R&D centers and test facilities. BorgWarner Inc. competes by extending its e-mobility portfolio into integrated heat pump modules that merge cabin and battery conditioning.
Electric vehicle thermal management encompasses the engineered systems that regulate temperature across battery packs, electric motors, power electronics, and passenger cabins to preserve performance, safety, and range. Liquid cooling circuits with glycol-water mixtures and refrigerant-based heat pumps represent the dominant technical approaches, operating across temperature bands from minus forty degrees Celsius to one hundred twenty degrees Celsius depending on cell chemistry and drive cycle. Cooling systems command the largest product-type revenue pool given their centrality to battery longevity and fast-charging capability, while heat pumps represent the fastest-growing technology segment as cold-climate range preservation becomes a purchase determinant. OEMs capture the dominant end-user value share through platform-standardized designs, though tier-1 suppliers increasingly occupy the engineering interface as thermal architectures merge with vehicle-level energy management.
The EPA tailpipe rules and NHTSA CAFE standards in the United States, alongside China's MIIT new-energy vehicle technical thresholds and the EU F-Gas Regulation, collectively mandate tighter thermal efficiency and lower-global-warming-potential refrigerants. These frameworks shape supplier qualification requirements and accelerate R&D spending on CO2 heat pumps and propane-based alternatives. Stakeholders must monitor how refrigerant transition timelines in Europe and North America diverge from China's parallel GB standards development, as misalignment risks fragmenting platform engineering and supplier certification costs.
Market Dynamics
Platform consolidation around dedicated EV architectures is compressing thermal system variety, forcing suppliers to engineer modular solutions that scale across multiple vehicle segments without redesign.
Growth Catalysts
- China MIIT new-energy vehicle technical thresholds:These mandates accelerate heat pump adoption by linking subsidy eligibility to cold-climate range performance, pulling investment toward integrated cabin-battery conditioning systems.
- Battery cell manufacturing clusters:Co-location of gigafactories with vehicle assembly in Germany, South Korea, and the United States creates localized demand for thermal engineering services and just-in-time component supply.
- 800V electrical architectures:Higher-voltage platforms enable faster charging rates that intensify cooling load requirements, expanding the addressable market for high-performance liquid cooling circuits and predictive thermal control software.
Market Restraints
- Refrigerant supply concentration:European F-Gas Regulation phase-down schedules and parallel Chinese GB standards development create misaligned certification timelines, fragmenting supplier qualification costs across regions.
- Copper and aluminum price volatility:Heat exchanger and coolant circuit manufacturing remains exposed to base metal commodity swings, compressing margin visibility for component specialists without long-term supply agreements.
- Silicon carbide inverter thermal limits:Power electronics operating at higher switching frequencies generate concentrated heat fluxes that exceed conventional cooling capacity, requiring expensive ceramic substrate materials.
Strategic Opportunities
- India PLI scheme for automotive:Localized cell manufacturing incentives under this framework will require thermal management infrastructure, opening white space for suppliers with cost-optimized heat pump designs.
- Vehicle-to-grid integration:Bidirectional charging creates new thermal loads during extended stationary discharge cycles, enabling aftermarket service contracts for battery conditioning system upgrades.
- CO2 heat pump convergence with battery preconditioning:Merging transcritical refrigerant cycles with predictive route-based thermal planning reduces energy consumption across both cabin and pack conditioning.
Industry Challenges
- Systems integration engineering shortage:The intersection of HVAC, battery electrochemistry, and power electronics expertise remains scarce, extending development timelines for integrated thermal module programs.
- Multi-standard refrigerant certification:Engineers must validate designs against divergent EPA SNAP approvals, EU F-Gas compliance categories, and evolving Chinese GB specifications simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Thermal Management Market |
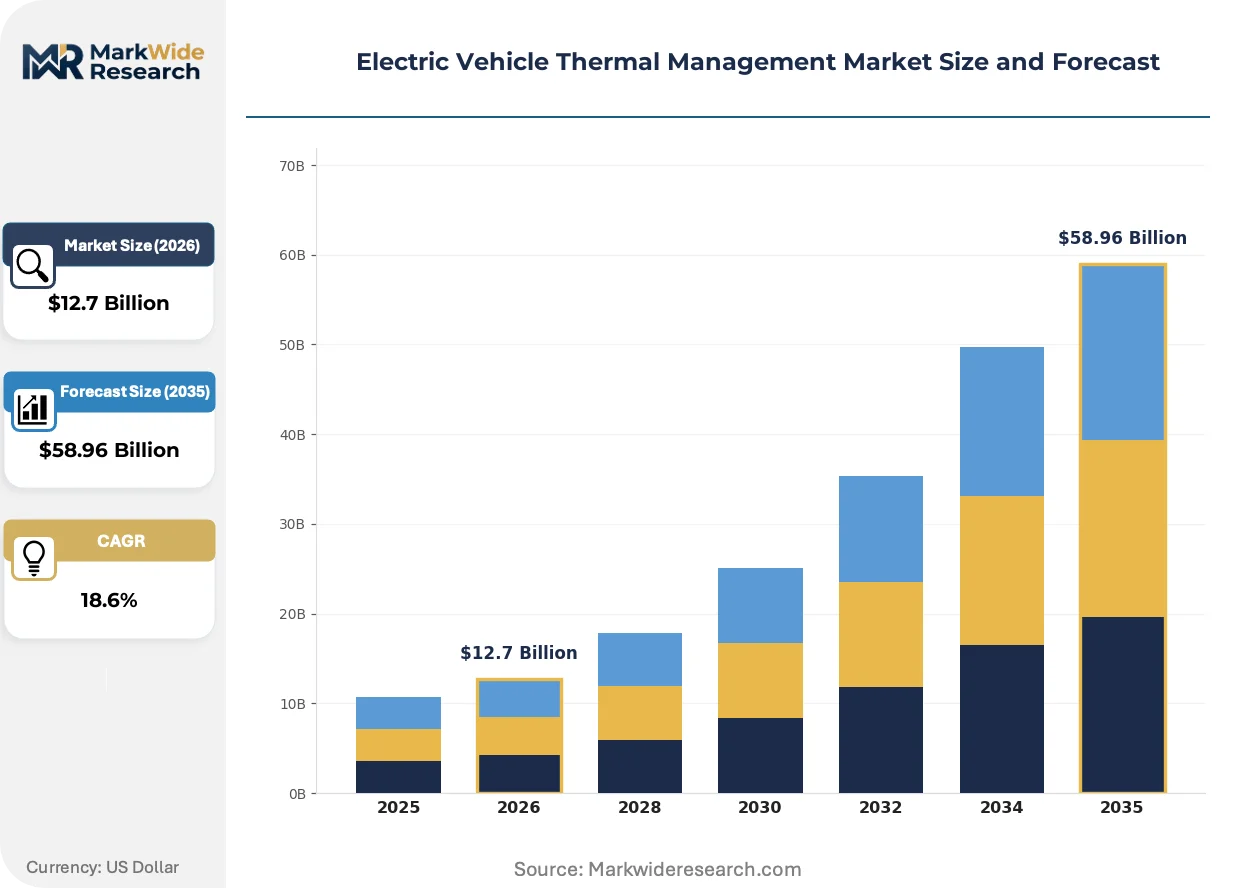
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.96 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Heating Systems, Thermal Insulation, Control Units Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Heat Pumps Application: Battery Cooling, Cabin Heating, Power Electronics, Motor Cooling End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | MAHLE GmbH, Sanden Holdings Corporation, DENSO Corporation, Continental AG, BorgWarner Inc., Hanon Systems, Sanhua Intelligent Controls, Robert Bosch GmbH, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Thermal Management Market Emerging Trajectories
Refrigerant chemistry and control software are converging to redefine system efficiency benchmarks. Suppliers now compete on predictive thermal algorithms rather than hardware specifications alone.
CO2 transcritical heat pump cycles are supplanting R-134a and R-1234yf systems in European premium EV platforms. Volkswagen Group and BMW have committed production volumes to this transition by 2027. The technology is supplanting conventional vapor-compression architectures by delivering cabin heating at minus twenty degrees Celsius without resistive drain, preserving range in Nordic markets.
The EU F-Gas Regulation mandates an eighty percent cut in hydrofluorocarbon consumption by 2030 against 2015 baseline levels. This forces OEMs to redesign service networks for flammable natural refrigerants and retrain technician workforces. Battery electric passenger vehicles face the steepest compliance cost escalation, driving accelerated partnerships between automakers and chemical suppliers.
Fleet operators now specify thermal performance guarantees in total-cost-of-ownership procurement frameworks rather than equipment-first capital expenditure models. Leasing companies and mobility-as-a-service providers in Germany and California are displacing traditional OEM-direct purchasing for volume commitments. This behavior concentrates buying power among fewer decision-makers, compressing supplier margins while extending contract durations.
Electric Vehicle Thermal Management Market Segmentation
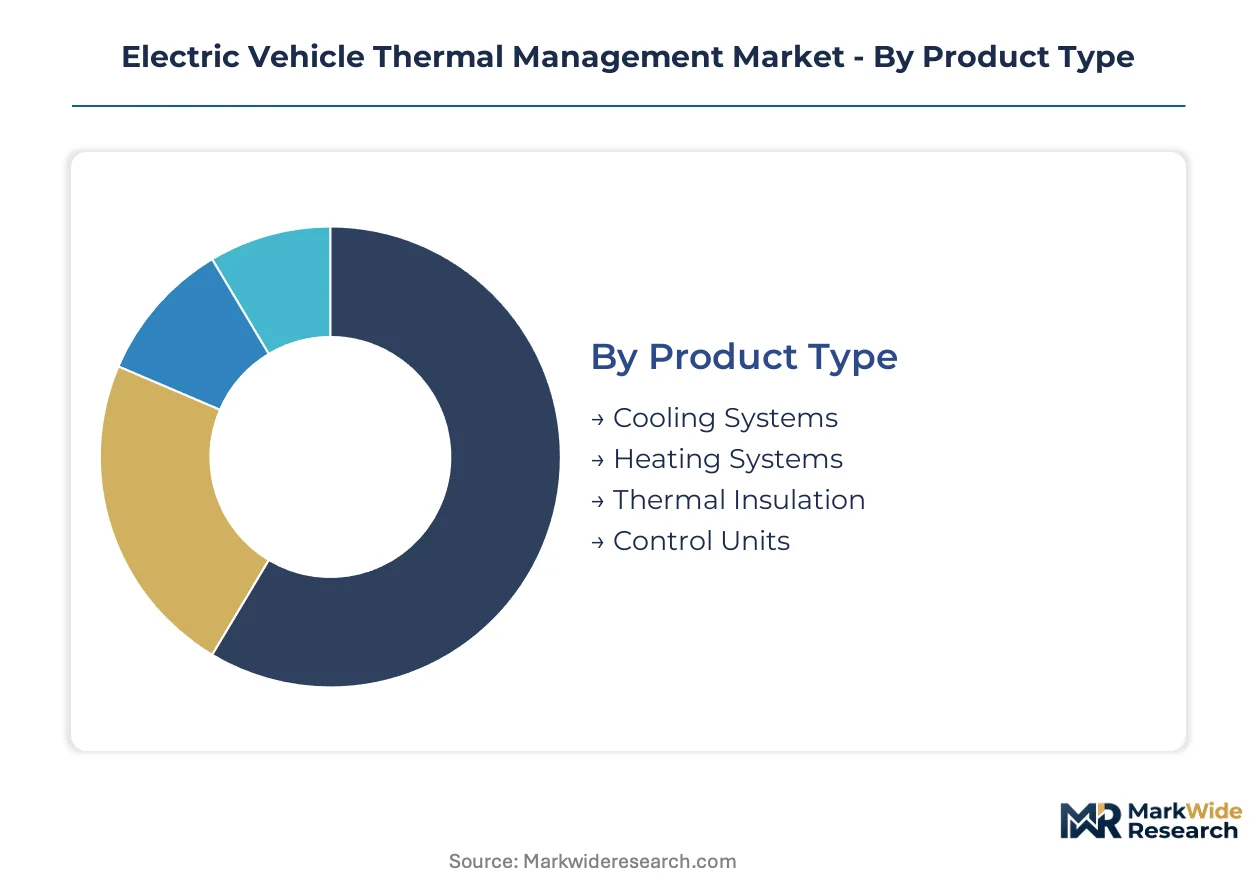
Thermal management architectures diverge sharply across vehicle platforms, with cooling load intensity and refrigerant chemistry driving supplier specialization. Segmentation reveals where engineering margins concentrate and which technology transitions command capital allocation.
Product Type:
Component sourcing channels split between integrated module suppliers serving platform-standardized programs and specialists delivering discrete subsystems to regional assembly plants.
- Cooling Systems:Glycol-water circuits and refrigerant loops regulate battery pack, motor, and inverter temperatures across minus forty to one hundred twenty degree Celsius operating bands. Demand clusters in Germany, South Korea, and the United States where cell manufacturing and vehicle assembly co-locate, with fast-charging capability requirements intensifying heat exchanger specifications.
- Heating Systems:Resistive heaters and heat pump compressors maintain cabin and battery temperatures in cold climates, with CO2 transcritical cycles displacing R-134a in European premium platforms. China's MIIT new-energy vehicle technical thresholds pull investment toward integrated cabin-battery conditioning by linking subsidy eligibility to cold-climate range performance.
- Thermal Insulation:Aerogel blankets and phase-change material enclosures minimize parasitic heat loss in battery packs and cabin envelopes.
- Control Units:Predictive thermal algorithms and sensor arrays orchestrate multi-loop conditioning strategies across battery, cabin, and power electronics domains.
By volume, Cooling Systems leads. By growth pace, Heating Systems is ahead.
Technology:
Cost tier stratification separates premium platforms adopting advanced refrigerant cycles from mass-market vehicles retaining conventional liquid architectures.
- Liquid Cooling:Dominant approach using propylene glycol-water mixtures circulated through cold plates and jacketed channels, scalable from compact passenger cars to commercial vehicles. Cell manufacturers in Germany and South Korea specify high-flow-rate designs supporting sustained fast-charging protocols.
- Heat Pumps:Fastest-expanding technology segment as cold-climate range preservation becomes a purchase determinant, with transcritical CO2 systems delivering cabin heating at minus twenty degrees Celsius without resistive drain. Volkswagen Group and BMW have committed production volumes to this transition.
- Air Cooling:Simplified blower and duct configurations retained in cost-optimized urban mobility platforms with lower thermal loads.
- Phase Change Materials:Latent heat storage media integrated into battery enclosures for transient thermal buffering during peak discharge events.
By installed base, Liquid Cooling dominates. By technology transition momentum, Heat Pumps is climbing the fastest.
Application:
Application priority follows battery energy density escalation, with thermal load intensity dictating engineering resource allocation across vehicle subsystems.
- Battery Cooling:Cell-level thermal regulation preserves cycle life and enables fast-charging acceptance rates, commanding the largest engineering investment pool. China's dual carbon goals and the EU F-Gas Regulation tighten refrigerant and energy efficiency standards for this application.
- Cabin Heating:Heat pump integration with battery conditioning loops reduces energy consumption in Nordic markets, with CO2 cycles supplanting conventional vapor-compression architectures.
- Power Electronics:Silicon carbide inverter thermal management requires ceramic substrates and concentrated cooling capacity for high switching frequency operation.
- Motor Cooling:Stator jacketing and rotor shaft cooling maintain magnetic performance in permanent magnet and induction motor designs.
By revenue concentration, Battery Cooling leads. By regulatory pressure intensity, Cabin Heating is gaining share fastest.
End User:
Procurement authority is shifting from OEM captive engineering to tier-1 suppliers as thermal architectures merge with vehicle-level energy management systems.
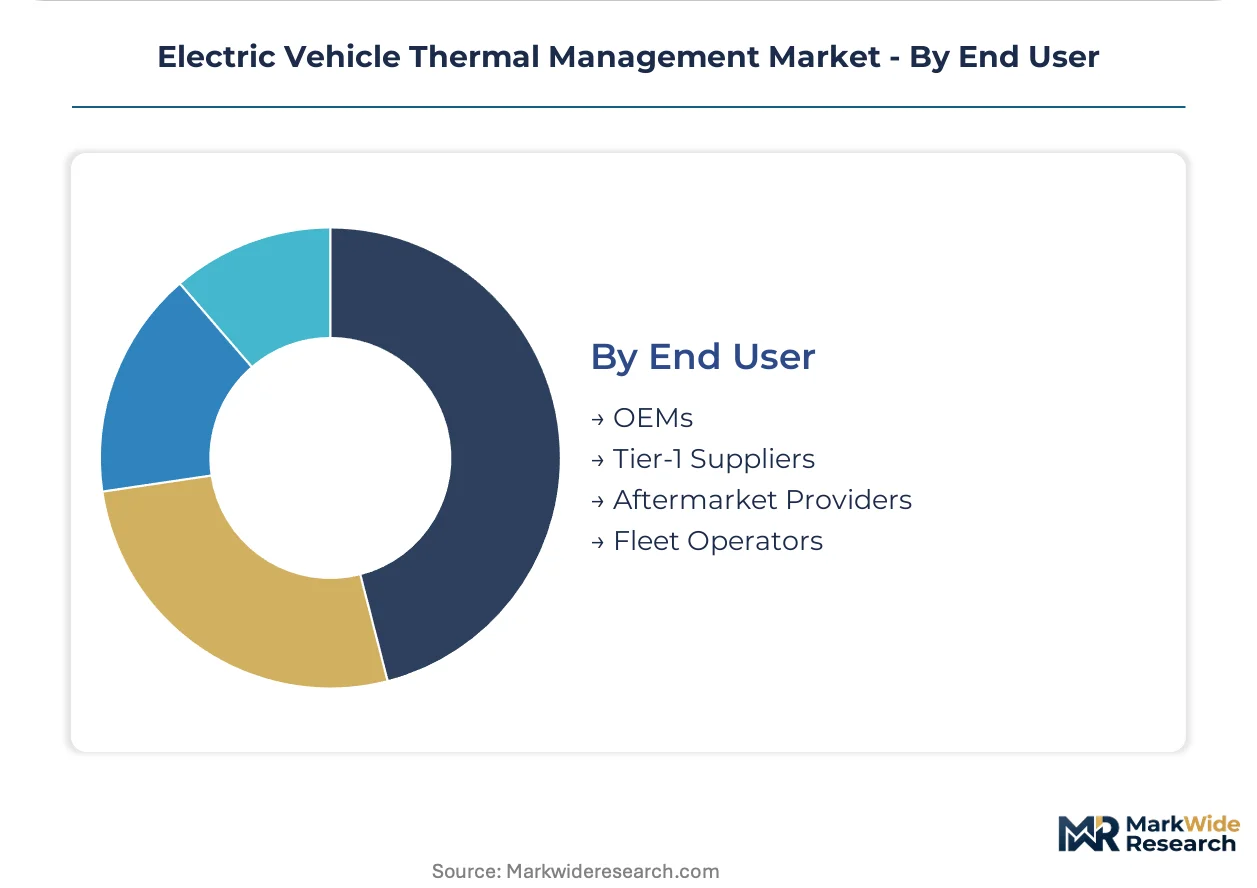
- OEMs:Platform-standardized designs retain dominant value share through dedicated EV architecture consolidation, compressing thermal system variety and forcing modular scaling across segments.
- Tier-1 Suppliers:Engineering interface occupation accelerates as integrated thermal modules bundle inverter cooling with battery loops, with DENSO Corporation and MAHLE GmbH anchoring relationships through localized R&D centers.
- Aftermarket Providers:Service network expansion for flammable natural refrigerants under EU F-Gas Regulation mandates technician retraining and equipment retrofit.
- Fleet Operators:Total-cost-of-ownership procurement frameworks displace equipment-first capital expenditure models in Germany and California, concentrating buying power among leasing companies and mobility-as-a-service providers.
By contract volume, OEMs lead. By margin expansion trajectory, Tier-1 Suppliers is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where OEM captive engineering commands premium module rates, while Chinese suppliers compete on heat pump cost curves that undercut European equivalents by double-digit percentages.
China
MIIT new-energy vehicle technical thresholds tie subsidy eligibility to cold-climate range performance, accelerating heat pump adoption across domestic EV platforms. The country's dual carbon goals and parallel GB standards development tighten refrigerant specifications independently from European timelines. Cell manufacturing clusters in Ningde and Shenzhen co-locate with vehicle assembly plants, creating localized demand for thermal engineering services.
Germany
The EU F-Gas Regulation mandates an eighty percent hydrofluorocarbon consumption cut by 2030, forcing OEMs to redesign service networks for flammable natural refrigerants. Volkswagen Group and BMW have committed production volumes to CO2 transcritical heat pump transitions by 2027. Stuttgart and Munich anchor European R&D concentration, with MAHLE GmbH operating localized test facilities that validate integrated thermal modules.
United States
EPA tailpipe rules and NHTSA CAFE standards mandate tighter thermal efficiency benchmarks across battery electric platforms. IRA manufacturing incentives pull gigafactory investment toward Nevada and Texas, co-locating cell production with vehicle assembly. Detroit engineering centers retain platform-standardization authority even as tier-1 suppliers occupy increasing thermal system interface roles.
South Korea
Battery cell manufacturing clusters in Ulsan and Gwangju create concentrated demand for high-flow-rate liquid cooling designs supporting sustained fast-charging protocols. Domestic OEMs specify thermal performance guarantees that compress supplier margins while extending contract durations. Hanon Systems anchors regional supply relationships through captive production of integrated HVAC-battery conditioning modules.
India
The PLI scheme for automotive manufacturing incentivizes localized cell production, opening white space for cost-optimized heat pump suppliers. Maharashtra and Tamil Nadu vehicle assembly hubs require thermal management infrastructure as domestic EV platforms scale. BIS standards development lags European and Chinese regulatory timelines, creating temporary certification flexibility for module suppliers.
Electric Vehicle Thermal Management Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated module suppliers commanding engineering premiums while component specialists compete on manufacturing scale. The market structure tilts toward consolidation as platform-standardized designs compress thermal system variety across vehicle segments. Three archetypes dominate: full-system architects bundling inverter cooling with battery loops, regional component fabricators serving assembly plant proximity requirements, and refrigerant technology specialists navigating multi-standard certification complexity. M&A activity concentrates on heat pump module acquisitions, while strategic partnerships proliferate between automakers and chemical suppliers for refrigerant transition roadmaps.
Within the full-system architect tier, DENSO Corporation and MAHLE GmbH occupy positions that exemplify divergent geographic anchoring strategies. BorgWarner Inc. represents the portfolio diversification archetype, extending legacy powertrain relationships into e-mobility thermal modules. These three entities illustrate how competitive positioning fragments across engineering integration depth, regional OEM relationship density, and refrigerant technology transition timing.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Sanden Holdings Corporation |
| DENSO Corporation |
| Continental AG |
| BorgWarner Inc. |
| Hanon Systems |
| Sanhua Intelligent Controls |
| Robert Bosch GmbH |
| Valeo |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with tier-1 module suppliers lock in both refrigerant-grade aluminum access and price visibility for OEMs navigating EU F-Gas transition timelines. These agreements concentrate procurement leverage among German and South Korean manufacturers while compressing margin buffers for component specialists exposed to spot copper markets.
Pricing Analysis
The customization-premium spread between configured-to-order thermal modules and standard liquid cooling circuits runs wide across the Electric Vehicle Thermal Management Market. Project-based pricing dominates integrated heat pump programs where CO2 transcritical architectures command certification-grade premiums, while commodity spot dynamics govern heat exchanger components. Price differentiation stems from ISO 26262 functional safety tiers and volume scale commitments, with cost compression in mass-market battery cooling intensifying due to Chinese supplier capacity additions. Fleet operators in Germany exhibit highest price sensitivity through total-cost-of-ownership frameworks, whereas premium OEM captive engineering tolerates engineering premiums for localized R&D integration.
Supply Chain Analysis
Inventory buffers for ceramic substrates and refrigerant-grade copper tubing stretch to six months as lead times for silicon carbide inverter cooling components extend. Manufacturing concentration centers on China, Germany, and South Korea where cell manufacturing clusters co-locate with module assembly. Raw material feeds draw from Chilean copper cathodes, Australian aluminum smelters, and Chinese rare earth processing for permanent magnet motor thermal management. Single-source vulnerability in CO2 compressor castings from European suppliers creates tariff exposure under divergent EU-China refrigerant certification timelines. Distribution runs through just-in-time pipelines serving gigafactory-adjacent assembly plants with minimal safety stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Thermal Management Market operates as a substitution defense against air-cooled legacy architectures and internal combustion thermal systems that cede range performance in cold climates. Incumbents must navigate heat pump technology transitions that threaten to commoditize liquid cooling specialists.
For Market Incumbents: Shield integrated module revenues by deepening backward integration into refrigerant compressor manufacturing and securing exclusive CO2 heat pump supply agreements with European premium OEMs. Vertical integration into ceramic substrate production addresses silicon carbide inverter thermal limits that exceed conventional cooling capacity. Capacity reservation contracts with Chilean copper suppliers defend margin position against base metal volatility.
For New Entrants and Emerging Players: EPA SNAP fast-track certification for propane-based refrigerant alternatives opens white space in North American aftermarket service networks retraining for flammable natural refrigerant handling. India PLI scheme thermal infrastructure requirements represent the most penetrable geography for cost-optimized heat pump designs. Target fleet operator procurement frameworks in California with performance-guarantee contracts displacing traditional OEM-direct purchasing.
For Investors and Strategic Acquirers: Refrigerant technology specialists navigating multi-standard certification complexity present acquisition targets with defensible regulatory moats. Long-term viability hinges on convergence with battery preconditioning software and vehicle-to-grid thermal load management. Watch for CO2 transcritical heat pump adoption inflection in Nordic markets as cabin heating range preservation becomes a purchase determinant.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Dedicated EV architectures compress thermal system variety across Volkswagen Group and BMW production volumes. |
| Battery Supply Agreement | Long-term offtake contracts with Ningde and Ulsan cell manufacturers secure localized thermal engineering access. |
| Software-Defined Vehicle Investment | Predictive thermal algorithms merge battery preconditioning with route-based energy management in integrated control units. |
| Geographic Manufacturing Footprint | Nevada and Texas gigafactory co-location with vehicle assembly creates IRA-compliant thermal module demand clusters. |
| Charging Infrastructure Partnership | Fast-charging network operators specify cooling performance guarantees for 800V platform thermal load intensity. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, thermal system R&D directors, and fleet operator asset managers anchored the qualitative base for this study. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs trade records. Bottom-up sizing of cooling system, heating system, and control unit segments triangulated against top-down OEM platform-standardization trends.
Sensitivity analysis framed volume and value outputs across the projection horizon by modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth rate convergence with battery energy density escalation and fast-charging protocol adoption curves. Forecast inputs incorporated MIIT subsidy threshold compliance rates and EU F-Gas Regulation phase-down schedules without year-specific anchoring.
Underlying assumptions cover refrigerant transition timeline alignment, copper price band stability, and silicon carbide inverter penetration curves, with deviation risk concentrated in Chinese GB standards development diverging from European certification categories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Special Purpose Electric Vehicle Market