
 Spain Solar E-Bike Market | 2026-2036
Spain Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Solar E-Bike Market Insights
EN 15194 certification for electrically power assisted cycles is redrawing competitive boundaries for solar-integrated variants. Orbea S.Coop. leverages its Basque manufacturing heritage to anchor premium positioning in urban mobility. BH Bikes Europe SL competes through sustained investment in lightweight frame architectures that accommodate photovoltaic surfaces. DECATHLON dominates mass-market accessibility with vertically controlled distribution across Spanish retail corridors.
A solar e-bike combines pedal-assist electric propulsion with onboard photovoltaic panels that recharge the battery during daylight exposure, typically achieving 15-25% range extension under optimal irradiance conditions for last-mile logistics and recreational transport. City E-Bikes occupy the largest volume share as Barcelona and Madrid expand lane infrastructure, while Mountain E-Bikes capture emerging demand from Andalusian trail tourism operators seeking off-grid charging independence. Lithium-Ion battery technology sustains the dominant technology position due to superior energy density compatibility with solar trickle-charging profiles.
Spain's Directorate General for Traffic enforces type-approval frameworks that classify solar e-bikes within L1e-A vehicle categories, while the Institute for Energy Diversification and Saving administers MOVES III subsidy allocations that directly reduce consumer acquisition costs. The Spanish Association for Standardization develops UNE protocol adaptations for photovoltaic integration safety. Stakeholders must monitor pending revisions to urban access restrictions and subsidy exhaustion timelines that will determine channel prioritization between direct retail and fleet procurement.
Market Dynamics
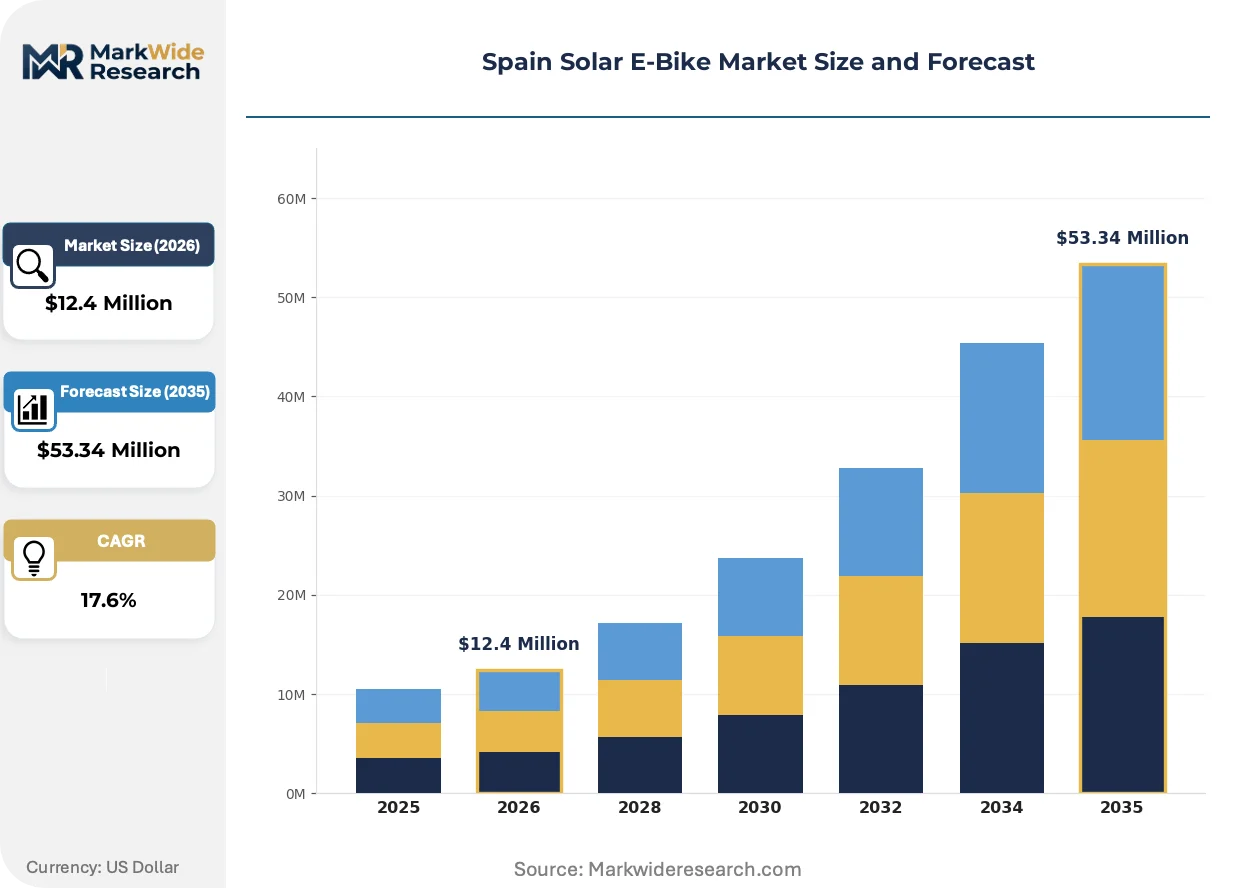
MOVES III subsidy allocations from Spain's Institute for Energy Diversification and Saving are compressing payback periods for fleet operators while redirecting consumer purchasing cycles toward solar-integrated variants. This fiscal mechanism is restructuring channel economics between direct retail and municipal procurement.
Growth Catalysts
- MOVES III Incentive Framework:Direct purchase subsidies reduce acquisition costs for light electric vehicles, accelerating adoption among last-mile delivery operators in Barcelona and Madrid urban corridors.
- Photovoltaic Efficiency Gains:Improved monocrystalline cell conversion rates extend effective range for solar-assisted bicycles, particularly benefiting Andalusian coastal tourism rental fleets.
- Municipal Fleet Electrification Mandates:Barcelona and Madrid city councils are expanding procurement quotas for zero-emission delivery vehicles, creating dedicated demand for solar e-bike configurations.
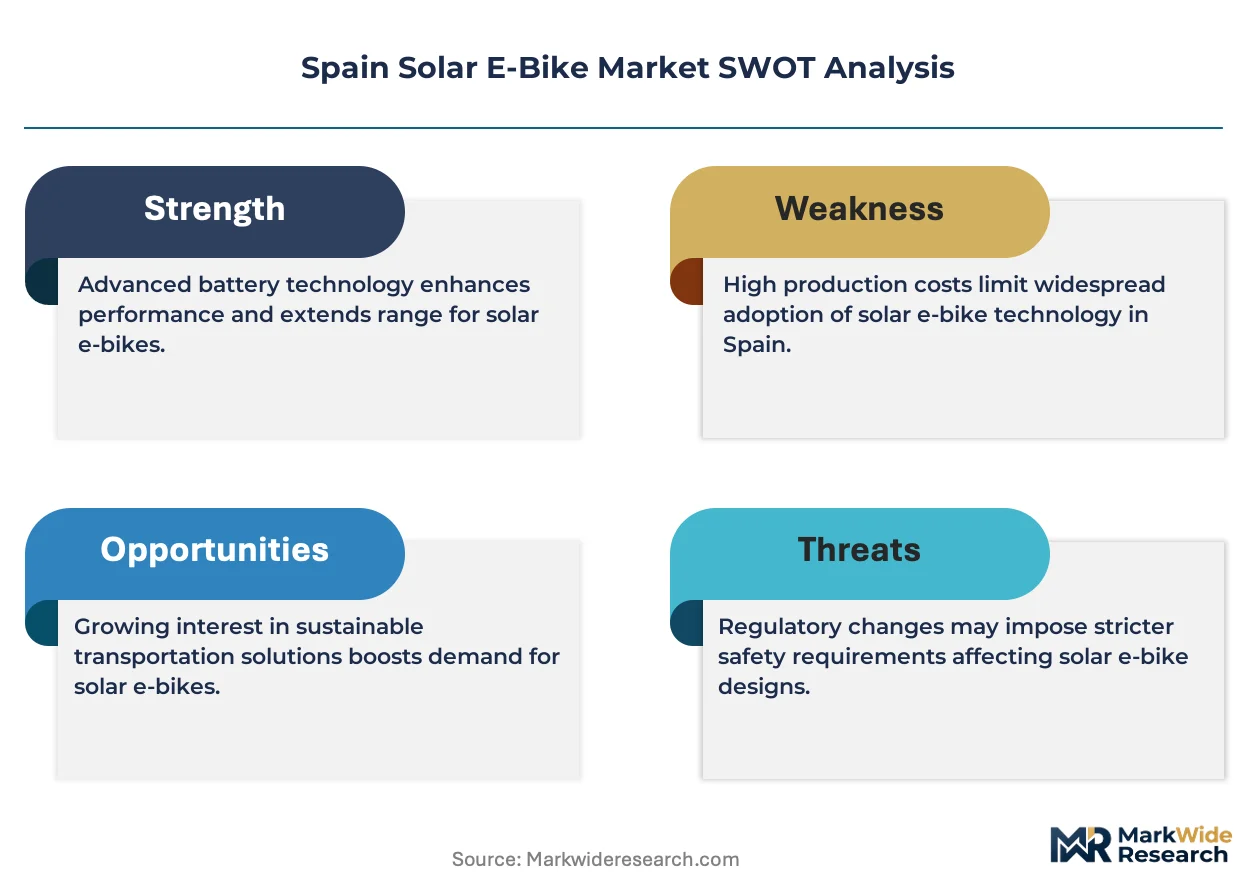
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell sourcing dependencies on East Asian manufacturers create input cost volatility and supply security exposures for Spanish assemblers.
- Photovoltaic Surface Area Constraints:Frame-integrated solar panels face fundamental physics limitations on energy capture rates, capping range extension potential under real-world irradiance variability.
- Type-Approval Friction:Spain's Directorate General for Traffic L1e-A classification requirements impose certification timelines and testing costs that disadvantage smaller domestic manufacturers.
Strategic Opportunities
- Andalusian Tourism Corridors:Coastal municipalities from Málaga to Cádiz present underpenetrated rental market potential for sun-charged e-bike fleets serving trail and beach access routes.
- Basque Manufacturing Cluster:Concentrated frame production capabilities around Vitoria-Gasteiz enable localized supply chain integration for premium solar-integrated urban mobility products.
- UNE Standardization Protocols:Pending photovoltaic integration safety standards from the Spanish Association for Standardization will create first-mover certification advantages for compliant manufacturers.
Industry Challenges
- Photovoltaic-Electronics Integration Expertise:Shortages of engineers skilled in solar cell encapsulation and power management system design constrain product development velocity for domestic brands.
- EN 15194 Certification Timelines:Extended testing protocols for electrically power assisted cycles with solar charging interfaces delay market entry and compress effective sales windows before subsidy exhaustion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Solar E-Bike Market |
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $53.34 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cruiser E-Bikes Battery Technology: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Lithium-Polymer Application: Commuting, Recreation, Delivery, Tourism Customer Type: Individual Consumers, Rental Services, Corporate Fleet, Government Programs |
| Companies Covered | Orbea S.Coop., BH Bikes Europe SL, CUBE Bikes, Giant Manufacturing Co. Ltd., Merida Industry Co. Ltd., Trek Bicycle Corporation, Accell Group, Scott Sports, DECATHLON, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Solar E-Bike Market Trends and Innovations
Photovoltaic integration architectures are reconfiguring competitive differentiation around energy autonomy rather than raw performance metrics. This shift favors manufacturers with systems integration capabilities over traditional mechanical engineering competencies.
Flexible thin-film solar cell technology is miniaturizing frame-integrated photovoltaic surfaces while maintaining energy capture efficiency. Last-mile logistics operators in Madrid are adopting these configurations for multi-shift operations without grid dependency. The technology is compressing total cost of ownership calculations by reducing charging infrastructure requirements for fleet managers.
Spain's Directorate General for Traffic is tightening enforcement of L1e-A type-approval documentation for solar-assisted variants, extending homologation timelines. This regulatory pressure is filtering out non-compliant imports while rewarding domestic manufacturers with established certification relationships. Urban mobility segments with high fleet turnover are absorbing these compliance costs most aggressively.
Tourism rental operators are consolidating procurement decisions around solar charging independence for off-grid trail access. This buyer concentration is displacing fragmented individual consumer purchasing as the primary volume channel in Andalusian markets. Coastal municipalities from Granada to Almería are witnessing the most pronounced shift toward fleet-based acquisition models.
Spain Solar E-Bike Market Segmentation
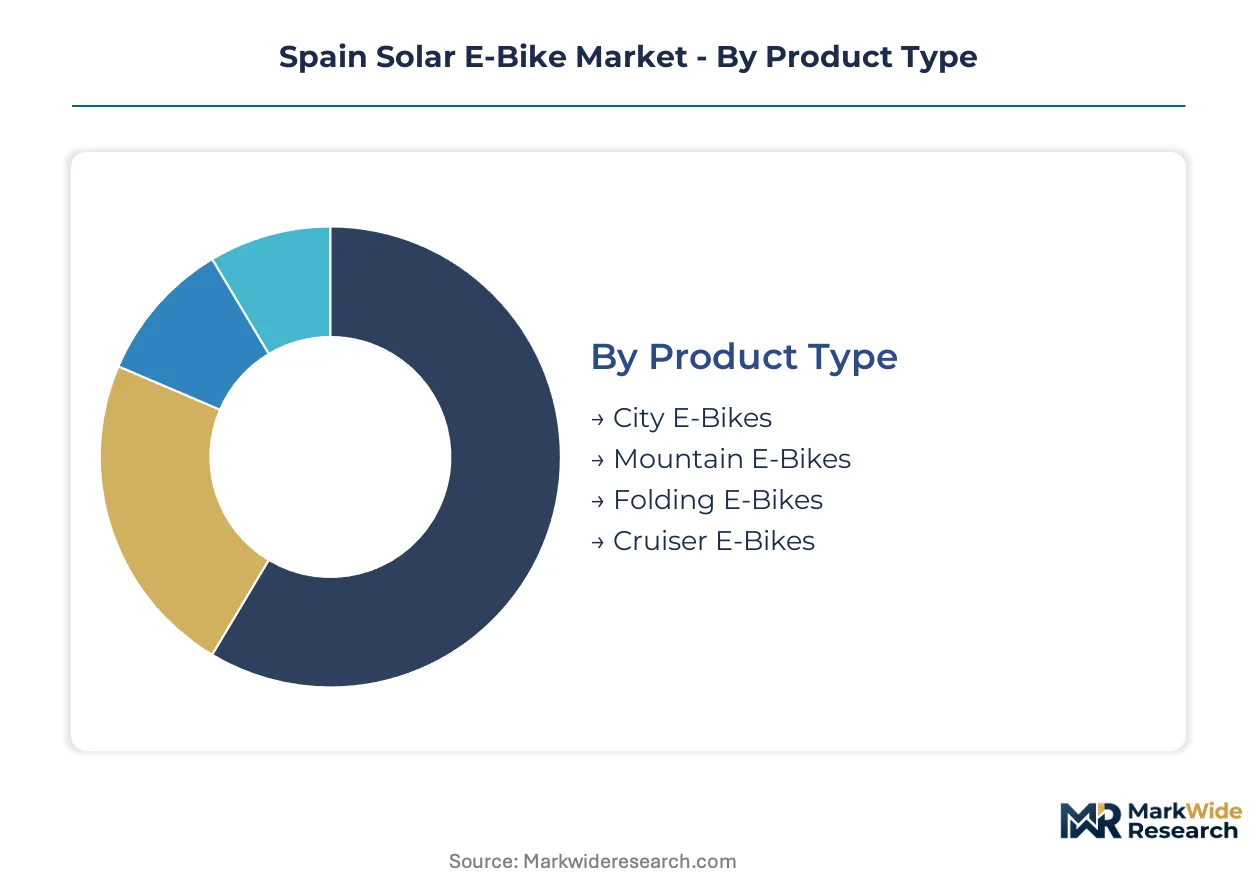
Segmentation in the Spain Solar E-Bike Market reveals distinct regulatory and demand patterns across product configurations, battery chemistries, and end-use applications. Spain's Directorate General for Traffic applies differential L1e-A type-approval requirements depending on vehicle classification, while MOVES III subsidy eligibility varies by customer category and intended use case.
Product Type:
Spain's L1e-A vehicle classification framework treats urban-focused solar e-bikes differently from off-road variants, with stricter speed and power limits applied to city-legal configurations. This regulatory differentiation shapes manufacturer R&D allocation and homologation investment priorities.
- City E-Bikes:Frame-integrated monocrystalline panels on step-through and commuter geometries prioritize range extension for Barcelona and Madrid last-mile logistics. MOVES III fleet procurement quotas concentrate demand here, with municipal operators absorbing premium pricing for EN 15194-certified configurations.
- Mountain E-Bikes:Reinforced frame architectures accommodate flexible thin-film photovoltaic surfaces for Andalusian trail tourism operators seeking charging independence at remote access points. Rental fleet consolidation in Málaga and Granada provinces drives volume.
- Folding E-Bikes:Compact hinge mechanisms limit surface area for solar integration, restricting range extension to 10-15% under optimal conditions. Individual Barcelona commuters represent the core demand cluster.
- Cruiser E-Bikes:Step-over beach geometries with rear-rack panel mounting serve Cádiz and Almería coastal tourism corridors. Lower power assist ratings align with relaxed recreational use cases.
Established volume favors City E-Bikes; emerging adoption favors Mountain E-Bikes.
Battery Technology:
Cost tier differentiation separates premium solar-integrated configurations from mass-market alternatives, with battery chemistry determining photovoltaic compatibility and total cost of ownership calculations for Spanish fleet operators.
- Lithium-Ion:Superior energy density enables optimal pairing with trickle-charging solar profiles. Basque manufacturing clusters around Vitoria-Gasteiz source cylindrical and prismatic cells for premium urban mobility products serving Madrid corporate fleets.
- Lithium-Polymer:Pouch formats allow custom shaping within frame tubes for aerodynamic solar e-bike designs. Emerging demand from Barcelona rental services prioritizes weight reduction over absolute cycle life.
- Nickel-Metal Hydride:Lower energy density limits solar range extension effectiveness. Budget-conscious individual consumers in secondary Spanish cities represent residual demand.
- Lead Acid:Prohibitive weight penalties exclude meaningful solar integration. Minimal presence in Spanish market due to MOVES III incentive minimum technical requirements.
Procurement concentration favors Lithium-Ion; technology transition favors Lithium-Polymer.
Application:
Customer workflow requirements determine solar panel sizing, with continuous daily operation demanding greater energy autonomy than intermittent recreational use.
- Delivery:Multi-shift urban logistics operators in Barcelona and Madrid deploy solar-assisted fleets to minimize charging downtime. MOVES III subsidies compress payback periods for last-mile courier services.
- Tourism:Andalusian coastal municipalities from Málaga to Cádiz procure sun-charged e-bike rentals for trail and beach access routes. Fleet-based acquisition displaces individual purchasing in this segment.
- Commuting:Individual Barcelona and Madrid residents utilize solar range extension for round-trip workplace travel without midday charging. Lane infrastructure expansion supports adoption.
- Recreation:Weekend riders in Basque Country and Catalonia prioritize cost over photovoltaic integration depth. Standard e-bike configurations dominate here.
Revenue scale favors Delivery; expansion trajectory favors Tourism.
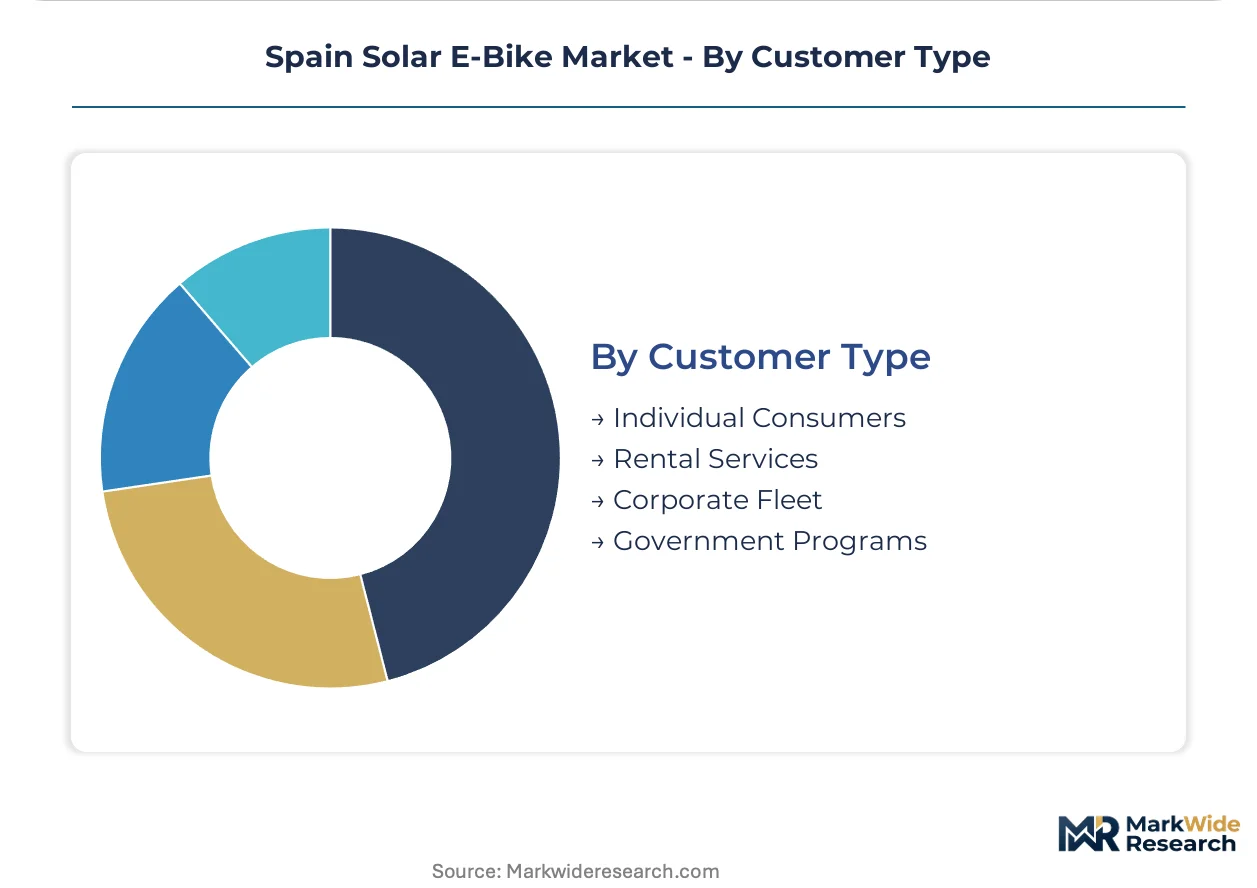
Customer Type:
Subsidy access and procurement scale create divergent channel economics, with institutional buyers capturing fiscal advantages unavailable to individual purchasers.
- Corporate Fleet:Madrid and Barcelona logistics operators leverage MOVES III allocations for volume solar e-bike procurement. Total cost of ownership calculations incorporate reduced charging infrastructure investment.
- Rental Services:Andalusian tourism corridor operators consolidate decisions around off-grid charging independence. Málaga-based fleet managers specify flexible thin-film configurations for multi-location deployment.
- Government Programs:Municipal procurement quotas for zero-emission vehicles create dedicated demand channels. City council specifications increasingly mandate solar-assisted variants.
- Individual Consumers:Price-sensitive purchasers in secondary Spanish cities face subsidy exhaustion timelines. Retail channel economics disadvantage this segment versus fleet procurement.
Policy leverage favors Government Programs; margin structure favors Corporate Fleet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mediterranean Rail Corridor links Madrid to Barcelona and underwrites Iberian logistics integration for solar-assisted last-mile fleets. This infrastructure backbone channels procurement decisions toward electrified urban mobility corridors.
Madrid
Corporate delivery operators dominate solar e-bike procurement across the capital's consolidated logistics zones. Spain's Directorate General for Traffic enforces L1e-A type-approval frameworks that classify solar-assisted variants within regulated vehicle categories. The MOVES III subsidy program administered by the Institute for Energy Diversification and Saving compresses acquisition costs for fleet managers in the Madrid metropolitan area.
Catalonia
Barcelona's expanding segregated lane infrastructure supports commuter adoption of solar range-extended bicycles for workplace travel. The Catalan regional government aligns with national MOVES III allocations while administering complementary municipal procurement quotas. Manufacturing concentration around Girona supplies frame components to assemblers serving the urban mobility segment.
Basque Country
Vitoria-Gasteiz anchors premium frame production capabilities for solar-integrated urban mobility products. EN 15194 certification requirements from European standardization bodies filter competitive entry, rewarding established Basque cooperatives with compliance infrastructure. Local manufacturing heritage supports photovoltaic-electronics integration expertise development.
Andalusia
Coastal tourism corridors from Málaga to Cádiz generate rental fleet demand for sun-charged e-bikes serving trail and beach access routes. Andalusian municipalities procure solar-assisted configurations to minimize grid dependency at remote rental locations. Fleet-based acquisition displaces individual purchasing across Granada and Almería provinces.
Spain Solar E-Bike Market Competitive Landscape
Listed leaders compete with private specialists across certification access and subsidy channel positioning. The vendor base fragments between mass-market retailers with vertically controlled distribution and cooperative manufacturers with regional heritage positioning. Three archetypes dominate: premium frame-integrated specialists, mass-market accessibility providers, and fleet procurement optimizers. Competitive moves concentrate on EN 15194 certification acceleration and MOVES III subsidy channel capture.
Within the cooperative manufacturing tier, Orbea S.Coop. exemplifies Basque heritage positioning, while BH Bikes Europe SL occupies a fabrication-focused position. At the mass-market vector, DECATHLON anchors accessibility through retail corridor density. These three entities represent distinct competitive approaches to solar integration: heritage engineering, lightweight architecture specialization, and scale-driven consumer reach.
| Leading Market Players |
|---|
| Orbea S.Coop. |
| BH Bikes Europe SL |
| CUBE Bikes |
| Giant Manufacturing Co. Ltd. |
| Merida Industry Co. Ltd. |
| Trek Bicycle Corporation |
| Accell Group |
| Scott Sports |
| DECATHLON |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements for lithium-ion cells lock in both supply access and price visibility for Spanish assemblers navigating MOVES III subsidy timelines. These contractual structures compress procurement risk for fleet operators while exposing smaller domestic manufacturers to working capital constraints.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by EN 15194 certification grade and volume procurement scale. Basque cooperative manufacturers command brand premiums for heritage positioning, while DECATHLON anchors economy tiers through captive retail distribution. Price erosion runs through standard tiers as East Asian imports compress margins. Individual consumers in secondary Spanish cities exhibit highest price sensitivity; municipal fleet buyers absorb premiums for compliance documentation.
Supply Chain Analysis
China and South Korea anchor cylindrical cell production for Spanish solar e-bike assemblers. Frame-integrated monocrystalline panels draw from Taiwanese wafer fabrication, while Basque manufacturing clusters around Vitoria-Gasteiz source aluminum extrusions domestically. Single-source vulnerability concentrates in battery management system semiconductors. Distribution runs through vertically controlled retail corridors for mass-market access and direct fleet procurement channels for municipal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain Solar E-Bike Market represents high-growth disruption as photovoltaic-electronics integration expertise becomes the decisive competitive moat. MOVES III subsidy exhaustion timelines compress the window for channel positioning.
For Market Incumbents: Consolidate certification infrastructure around EN 15194 homologation to filter import competition. Deepen backward integration into frame-integrated photovoltaic assembly through Basque manufacturing partnerships. The Directorate General for Traffic's tightening L1e-A enforcement threatens non-compliant entrants; established relationships with the Spanish Association for Standardization reward first-mover positioning on pending UNE protocols. For New Entrants and Emerging Players: EN 15194 fast-track certification unlocks municipal procurement channels before subsidy exhaustion. Andalusian tourism corridors from Málaga to Cádiz present the most penetrable white space, with rental fleet consolidation displacing fragmented individual purchasing. Flexible thin-film solar configurations offer a differentiated go-to-market angle for off-grid trail access operators. For Investors and Strategic Acquirers: Capital is best deployed toward cooperative manufacturers with established Basque fabrication heritage and existing certification relationships. The five-to-ten-year viability window favors entities with photovoltaic-electronics integration capabilities over pure mechanical engineering plays. Watch MOVES III allocation exhaustion rates as the inflection signal for channel economics shift from subsidy-driven to pure TCO competition.| Strategic Initiative | Industry Significance |
|---|---|
| EN 15194 Certification Acceleration | Filters import competition through Directorate General for Traffic homologation timelines. |
| Photovoltaic-Electronics Integration Investment | Captures range-extension differentiation as monocrystalline efficiency gains mature. |
| Andalusian Tourism Corridor Fleet Partnerships | Locks in rental demand from Málaga to Cádiz municipal procurement quotas. |
| Basque Manufacturing Cluster Expansion | Localizes supply chain control for premium urban mobility configurations. |
| MOVES III Channel Capture Program | Redirects procurement economics toward institutional buyers before subsidy exhaustion. |
Research Methodology
Desk research of trade customs data, SEC filings from listed bicycle manufacturers, and Directorate General for Traffic type-approval registries preceded structured interviews with fleet procurement managers at Barcelona and Madrid logistics operators, product directors at Basque cooperative manufacturers, and subsidy administrators at the Institute for Energy Diversification and Saving. Bottom-up volume triangulation across product segments was validated against top-down macroeconomic indicators for light electric vehicle adoption.
Variance decomposition across the projection horizon isolates drivers by product type, battery chemistry, end-use application, and customer category. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate MOVES III allocation trajectories and urban lane infrastructure buildout schedules from Barcelona and Madrid metropolitan planning documents.
Decision-makers should treat outputs as directional under sustained subsidy availability and lithium-ion supply continuity assumptions; material deviation would warrant model refresh. Specific risks include photovoltaic cell sourcing disruptions and regulatory reclassification of L1e-A vehicle categories. Recalibration cycles align with material shifts in subsidy exhaustion timelines and UNE standardization protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Europe Electric Bus Market