
 France E-Bike Market | 2026-2036
France E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
France E-Bike Market Foresight
Subscription-based battery-swapping and maintenance packages are expanding what French consumers purchase alongside hardware. Giant Manufacturing Co. Ltd. leverages its manufacturing scale to supply frames and drive systems to European assemblers. Decathlon S.A. anchors the mass-market channel through its nationwide sporting-goods retail network and private-label e-bike lines.
An e-bike is a bicycle equipped with an integrated electric motor providing pedal assistance or throttle propulsion, typically powered by lithium-ion battery packs with energy densities between 400 and 700 watt-hours, designed to extend range and reduce physical exertion for urban commuting, cargo hauling, and recreational travel. Pedal-assist configurations dominate unit sales across France, while cargo e-bikes command premium pricing due to reinforced frames and higher torque requirements. Lithium-ion battery technology leads the power-source category, though solid-state chemistries are attracting R&D investment for improved thermal stability and cycle life.
France's national regulator ANSM oversees product safety compliance, while EU frameworks including CE marking and the F-Gas Regulation govern electrical standards and refrigerant-based thermal management systems in battery cooling. The EU AI Act will soon classify predictive battery-management algorithms as high-risk applications, adding conformity-assessment burdens for connected e-bike platforms. Stakeholders must monitor how Paris municipal authorities integrate e-bike infrastructure into the Grand Paris Express corridor planning and whether battery-recycling mandates tighten material-sourcing requirements.
Market Dynamics
French municipal authorities are embedding e-bike infrastructure into the Grand Paris Express corridor planning, redirecting transport investment from automotive capacity toward electrified micromobility networks. This spatial reconfiguration is compressing last-mile logistics costs and altering household vehicle ownership patterns across Île-de-France.
Growth Catalysts
- EU Green Deal alignment:France's national low-emission mobility framework tightens vehicle-emission standards and redirects consumer spending toward electrified personal transport.
- Urban bike-lane expansion:Paris, Lyon, and Bordeaux municipal networks widen dedicated cycling infrastructure, reducing perceived safety barriers for commuter adoption.
- Lithium-ion energy density gains:Battery pack configurations between 400 and 700 watt-hours extend practical range for suburban cargo applications.
Market Restraints
- Critical mineral concentration:Lithium and cobalt supply chains concentrate in limited extraction geographies, exposing French assemblers to input cost volatility.
- Thermal management complexity:F-Gas Regulation constraints on refrigerant-based battery cooling systems limit design flexibility for high-torque cargo platforms.
- Second-car substitution ceiling:Households in rural départements retain internal-combustion vehicles for intercity distances beyond e-bike practical range.
Strategic Opportunities
- Subscription service models:Battery-swapping and maintenance packages expand recurring revenue streams beyond hardware sales.
- Last-mile logistics electrification:Delivery operators in dense urban cores replace van fleets with cargo e-bikes, unlocking fleet-scale procurement contracts.
- ANSM safety framework evolution:Product compliance standardization creates first-mover advantage for domestic assemblers with established certification pathways.
Industry Challenges
- EU AI Act conformity assessment:Predictive battery-management algorithms face high-risk classification, adding validation timelines for connected platforms.
- Technician training gaps:Specialized repair skills for integrated drive systems and solid-state battery diagnostics outpace vocational program updates.
- Recycling mandate readiness:Pending material-sourcing requirements for end-of-life battery recovery demand reverse-logistics infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France E-Bike Market |
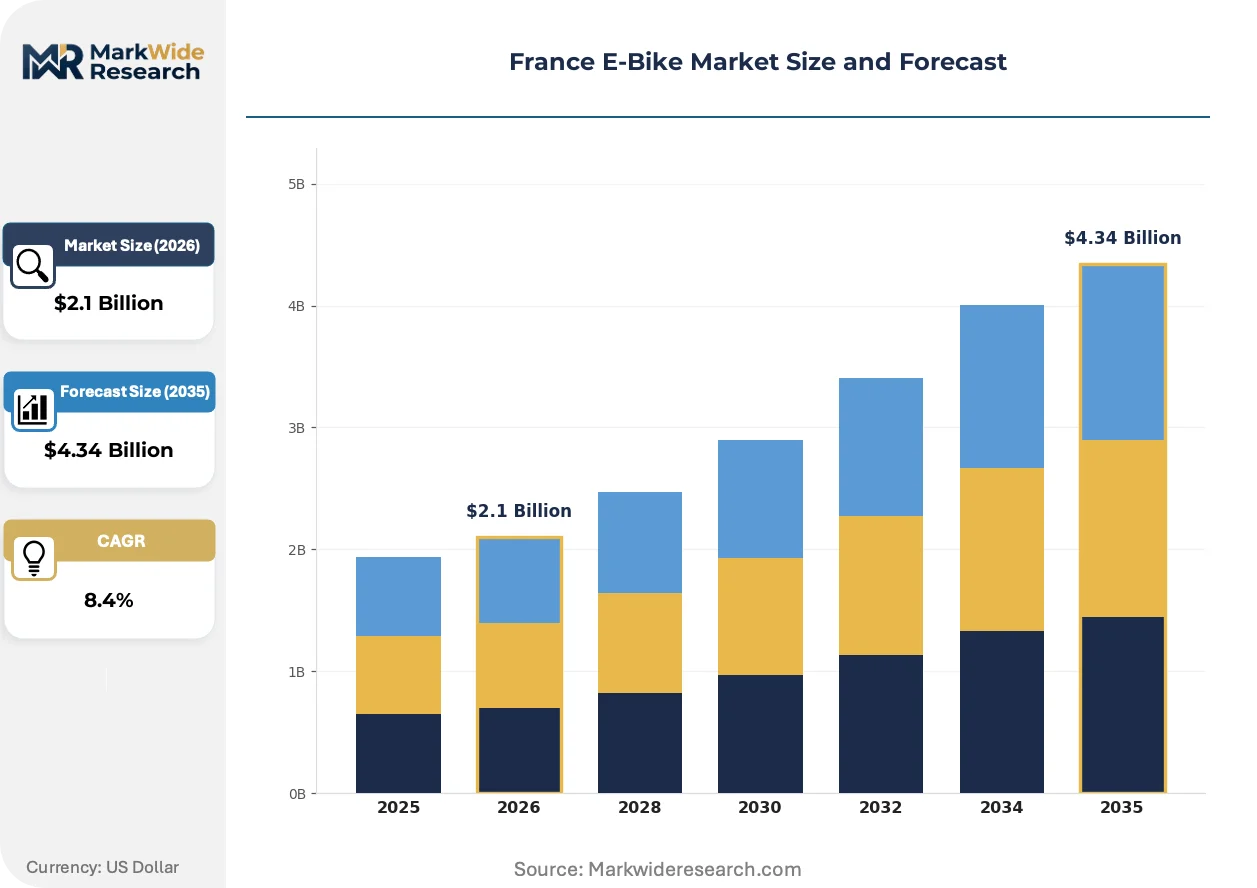
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal-Assist, Throttle-Controlled, Speed Pedelec, Folding, Cargo, Cruiser Battery Technology: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State, Zinc-Air, Lithium-Polymer End User: Commuters, Delivery Services, Tour Operators, Senior Citizens, Students, Recreational Riders Sales Channel: Specialty Retailers, Online Platforms, Department Stores, Bicycle Dealers, Sporting Goods Stores, Direct Sales |
| Companies Covered | Giant Manufacturing Co. Ltd., Decathlon S.A., Trek Bicycle Corporation, Moustache Bikes, Lapierre, Riese & Müller, O2feel, KTM Bike Industries, Reine Bike, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France E-Bike Market Shifts & Advancements
Solid-state battery chemistries are attracting concentrated R&D investment across French and European research consortia, promising thermal stability improvements that could reshape powertrain design constraints. These material advances intersect with regulatory pressure on algorithmic systems and shifting procurement behaviors among fleet operators.
Silicon-anode lithium-ion configurations are expanding into premium cargo and family-transport segments. Suburban households replacing second cars demand higher energy density for loaded hill-climbing performance. This chemistry transition is expanding into applications previously reserved for larger electric vehicles, compressing the performance gap between micromobility and light automotive.
The EU AI Act classification framework imposes conformity-assessment burdens on predictive battery-management algorithms deployed in connected e-bike platforms. Manufacturers must document algorithmic decision pathways for state-of-charge estimation and thermal runaway prediction. Cargo fleet operators integrating telematics face the steepest compliance costs, driving consolidation toward larger platform providers with dedicated regulatory affairs functions.
French delivery cooperatives and logistics subsidiaries are unbundling vehicle ownership from operational service, preferring operational lease structures with bundled maintenance and battery refresh guarantees. This procurement evolution displaces traditional retail channel dominance in the commercial segment. Paris-based last-mile operators exhibit the fastest transition velocity, with Lyon and Bordeaux networks following twelve to eighteen months behind.
France E-Bike Market Segmentation
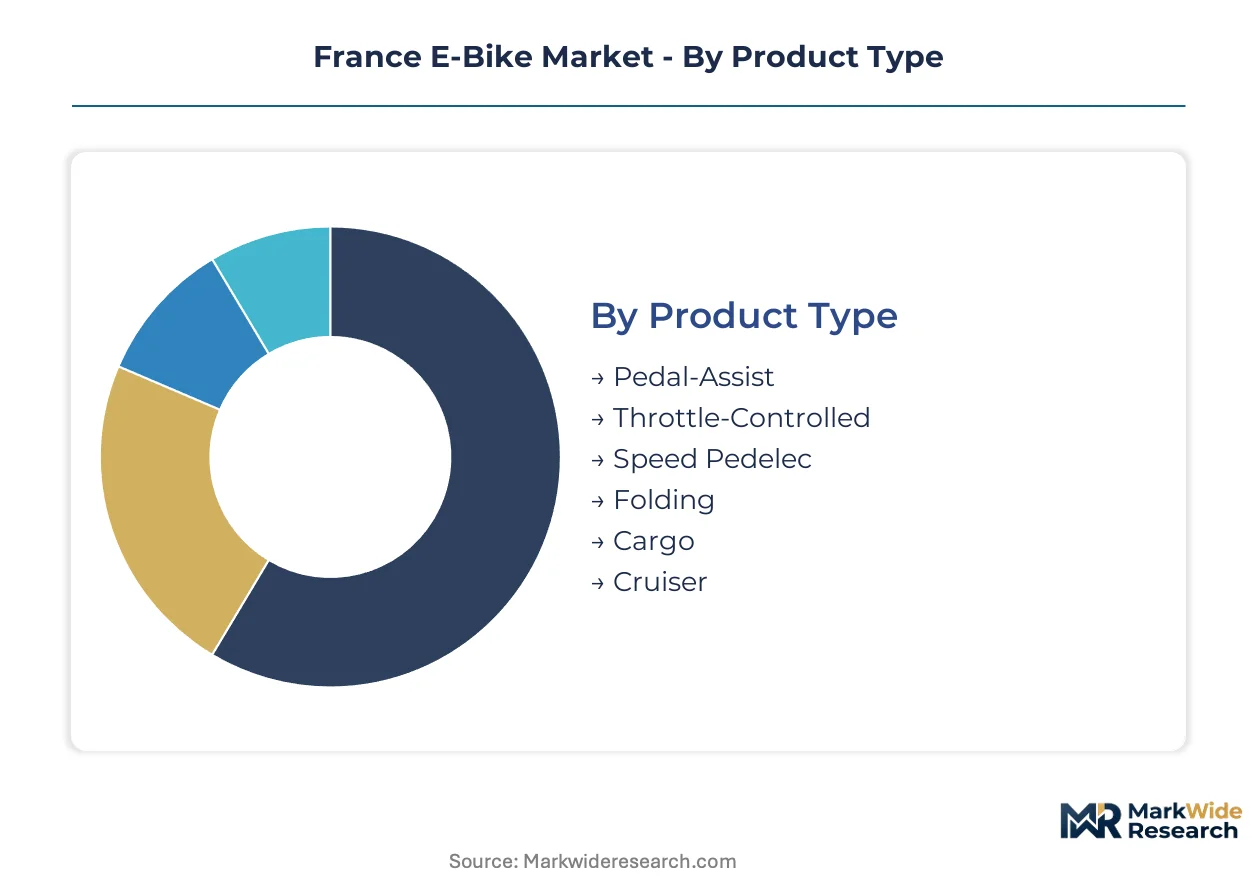
Segmentation in the France E-Bike Market reveals how regulatory frameworks, infrastructure investments, and household mobility patterns concentrate demand across distinct technical configurations and user profiles. Understanding these divides exposes where procurement volumes cluster and which specifications command premium positioning.
Product Type:
Technical specification differentiates propulsion architecture, frame geometry, and load-bearing capacity across French urban and suburban use cases.
- Pedal-Assist:Electric motor supplements rider pedaling effort through torque or cadence sensors, with power cut-off thresholds set by EU type-approval regulations. Paris and Lyon commuter corridors concentrate unit volume as municipal bike-lane networks reduce safety friction for daily travel.
- Cargo:Reinforced frames and extended wheelbases accommodate 100-200kg payloads with high-torque mid-drive systems. Île-de-France last-mile delivery operators and suburban households replacing second cars drive fleet-scale procurement and premium pricing.
- Throttle-Controlled:Twist-grip or thumb-activated motor engagement without mandatory pedaling, subject to stricter registration requirements under French road safety codes.
- Speed Pedelec:Motor assistance extends to 45 km/h with mandatory helmet use, license plates, and insurance under EU L1e-B classification.
- Folding:Hinge-frame designs collapse for multi-modal transit integration, concentrated among Paris Métro commuters with limited home storage.
- Cruiser:Upright riding position with step-through frames, prioritizing comfort over efficiency for recreational coastal and riverside routes.
Mature deployment sits with Pedal-Assist configurations across French commuter networks. Newer deployment is concentrated in Cargo variants as logistics electrification accelerates.
Battery Technology:
Energy storage chemistry determines thermal stability, cycle life, and recyclability obligations under evolving EU material-sourcing mandates.
- Lithium-Ion:NMC and LFP cathode configurations dominate with 400-700 watt-hour energy densities. French assemblers source cells from East Asian suppliers, exposing cost structures to lithium and cobalt price volatility.
- Solid-State:Ceramic or polymer electrolytes replace liquid organic solvents, promising improved thermal stability and extended cycle life. French research consortia and European OEM pilot programs concentrate R&D investment, though manufacturing scale remains limited.
- Nickel-Metal Hydride:Mature chemistry with lower energy density, retained in budget commuter segments where purchase price sensitivity outweighs range requirements.
- Lead-Acid:Heavy, short-cycle batteries relegated to low-speed utility applications and aftermarket replacement markets with minimal regulatory compliance burdens.
- Zinc-Air:Metal-air architecture using atmospheric oxygen as cathode reactant, attracting experimental deployment for ultra-long-range cargo prototypes.
- Lithium-Polymer:Pouch-cell form factors enable flexible frame integration, concentrated in premium folding and step-through designs.
Established volume sits with Lithium-Ion across mass-market French assembly. Steepest expansion trajectory belongs to Solid-State as ANSM safety frameworks tighten thermal runaway prevention standards.
End User:
Operational intensity and route predictability segment procurement patterns across commercial fleet operators and individual households.
- Delivery Services:High-utilization fleets operating 8-12 hour shifts with guaranteed battery refresh requirements. Paris-based last-mile operators exhibit fastest transition velocity, with Lyon and Bordeaux networks following twelve to eighteen months behind.
- Commuters:Daily trip distances of 5-15 kilometers with weather-dependent modal switching. Grand Paris Express corridor planning embeds e-bike infrastructure, compressing perceived safety barriers.
- Tour Operators:Seasonal rental fleets in Provence-Alpes-Côte d'Azur and Loire Valley wine regions with standardized maintenance protocols.
- Senior Citizens:Step-through frame preference with throttle-assist options for hill-climbing assistance in hilly rural départements.
- Students:Price-sensitive segment concentrated in university towns with campus bike-share integration.
- Recreational Riders:Weekend trail and canal-path usage with lower utilization intensity and higher accessory attachment rates.
Commercial procurement concentrates with Delivery Services. Individual ownership is expanding fastest among Commuters as Île-de-France suburban rail connections improve.
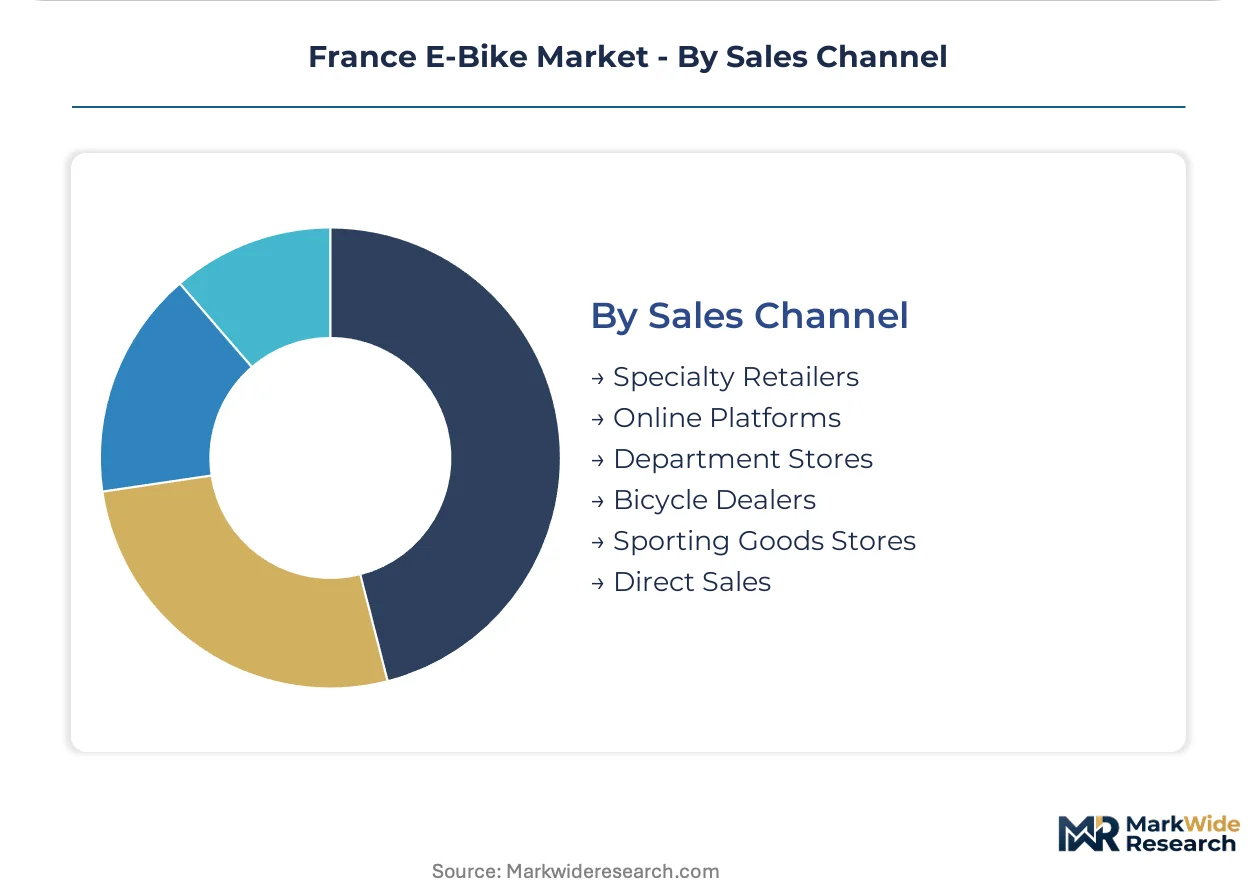
Sales Channel:
Channel structure reflects service bundling requirements and customer touchpoint preferences across hardware, maintenance, and financing.
- Specialty Retailers:Independent bike shops with certified technician networks for drive system diagnostics and warranty service. High-touch model suits cargo e-bike buyers requiring load-rack customization.
- Online Platforms:Direct-to-consumer fulfillment with third-party assembly partnerships. Subscription-based battery-swapping and maintenance packages expand what French consumers purchase alongside hardware.
- Department Stores:Mass-market volume with limited after-sales service, concentrated in entry-level pedal-assist segments.
- Bicycle Dealers:Traditional independent retailers with regional brand relationships and trade-in programs.
- Sporting Goods Stores:Decathlon S.A. anchors this channel through nationwide retail network and private-label e-bike lines with standardized component ecosystems.
- Direct Sales:Manufacturer-owned experience centers and mobile test-ride fleets, concentrated in premium cargo and speed pedelec segments.
Volume concentration rests with Specialty Retailers for service-intensive cargo applications. Channel expansion is climbing the fastest in Online Platforms as subscription service models displace traditional ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates e-bike consumption within its metropolitan corridors, while component sourcing and battery cell production remain concentrated in East Asian supply bases. The national market's expansion trajectory depends on municipal infrastructure commitments across distinct regional economies.
Île-de-France
Grand Paris Express corridor planning embeds dedicated cycling infrastructure alongside suburban rail extensions, compressing last-mile logistics costs for delivery operators. ANSM product safety compliance creates certification concentration among Paris-based assemblers. The Petite Couronne and Grande Couronne suburbs exhibit fastest household second-car substitution rates.
Auvergne-Rhône-Alpes
Lyon's municipal bike-lane network expansion reduces perceived safety barriers for commuter adoption across the Rhône corridor. EU Green Deal alignment redirects regional transport investment from automotive capacity toward electrified micromobility. Grenoble's research consortia concentrate solid-state battery R&D investment.
Provence-Alpes-Côte d'Azur
Tour operator rental fleets standardize maintenance protocols for seasonal coastal and wine-region usage. The F-Gas Regulation constrains refrigerant-based thermal management systems for high-torque cargo platforms. Nice and Marseille logistics subsidiaries prefer operational lease structures with bundled battery refresh guarantees.
Nouvelle-Aquitaine
Bordeaux municipal authorities widen dedicated cycling infrastructure in parallel with tram network extensions. Rural départements retain internal-combustion vehicles for intercity distances beyond e-bike practical range, capping penetration in landes and Périgord territories. The Arcachon Basin recreational corridor drives cruiser segment demand.
Hauts-de-France
Lille's cross-border metropolitan integration with Belgian Flanders creates procurement pattern spillover for cargo fleet electrification. Battery-recycling mandates tighten material-sourcing requirements for end-of-life recovery infrastructure. The Dunkirk logistics cluster exhibits emerging delivery cooperative formation for last-mile van replacement.
France E-Bike Market Competitive Landscape
Top-tier vendors anchor premium cargo and speed pedelec segments, while mass-market volume concentrates through sporting-goods retail networks. Mid-tier specialists occupy service-intensive niches requiring certified technician networks for drive system diagnostics. The vendor landscape segments across manufacturing scale, retail channel control, and subscription service bundling. Competitive moves center on operational lease structure deployment and reverse-logistics infrastructure investment for battery lifecycle management.
Within the manufacturing-scale archetype, Giant Manufacturing Co. Ltd. represents upstream frame and drive system supply to European assemblers. Decathlon S.A. anchors mass-market channel control through nationwide retail network density. Moustache Bikes occupies a position within the domestic specialist tier, exemplifying French assembly operations with established ANSM certification pathways. These three entities collectively illustrate how competitive positioning stratifies across supply chain function, retail reach, and regulatory compliance specialization.
| Leading Market Players |
|---|
| Giant Manufacturing Co. Ltd. |
| Decathlon S.A. |
| Trek Bicycle Corporation |
| Moustache Bikes |
| Lapierre |
| Riese & Müller |
| O2feel |
| KTM Bike Industries |
| Reine Bike |
| Others |
Supply & Pricing Matrix
French delivery cooperatives unbundling vehicle ownership from operational service force assemblers toward operational lease structures with bundled maintenance and battery refresh guarantees, compressing upfront hardware margins while extending revenue recognition timelines across the contract lifecycle.
Pricing Analysis
Margin tightening in the cargo segment reflects fleet-scale procurement contracts displacing retail channel premiums. Three-tier pricing structure across premium, standard, and economy levels separates ANSM-certified cargo platforms with guaranteed refresh cycles from entry-level pedal-assist commuter units. Price differentiation traces to certification grade and after-sales service bundling. Delivery operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while student segments in university towns drive economy-tier volume.
Supply Chain Analysis
CE marking and ANSM safety framework compliance gates French market access for East Asian cell suppliers and European frame assemblers. Lithium-ion cell production concentrates in China, South Korea, and Japan, with French assemblers drawing from these geographies for NMC and LFP cathode configurations. Raw material dependencies center on lithium carbonate, cobalt sulfate, and rare-earth magnets for mid-drive systems. Single-source vulnerability in cathode active material supply creates input cost volatility. Distribution runs through Decathlon's nationwide retail network and independent specialty retailers with certified technician capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk classification for predictive battery-management algorithms erects a cost-of-compliance moat favoring domestic assemblers with established regulatory affairs functions and documented algorithmic decision pathways.
For Market Incumbents: Anchor market position through backward integration into solid-state battery R&D partnerships with Grenoble research consortia, insulating against thermal runaway liability exposure while the EU AI Act conformity assessment burdens slow challenger platform launches. Defend against subscription-service entrants by captive supply of battery-swapping infrastructure within Grand Paris Express corridor planning zones. For New Entrants and Emerging Players: Begin with operational lease structuring for last-mile delivery cooperatives in Lyon and Bordeaux, where Paris-based operator transition velocity creates twelve-to-eighteen-month follow-on demand windows. Target the senior citizen segment in hilly rural départements with throttle-assist step-through configurations underserved by existing pedal-assist commuter focus. For Investors and Strategic Acquirers: Re-rating potential sits with ANSM-certified domestic assemblers given EU AI Act implementation accelerating consolidation toward regulatory-compliant platform providers. Long-term viability favors entities with reverse-logistics infrastructure investment for pending battery-recycling mandates. The signal to watch is tightening material-sourcing requirements for end-of-life recovery triggering acquisition premiums for compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Service Launch | Battery-swapping packages expand recurring revenue beyond hardware sales for Paris fleet operators. |
| Solid-State R&D Partnership | Ceramic electrolyte development with Grenoble consortia addresses ANSM thermal stability standards. |
| Reverse-Logistics Infrastructure | End-of-life battery recovery networks preempt EU material-sourcing mandate compliance costs. |
| Operational Lease Structuring | Delivery cooperatives in Lyon and Bordeaux prefer bundled maintenance with guaranteed refresh cycles. |
| Algorithmic Compliance Investment | Documented state-of-charge estimation pathways satisfy EU AI Act high-risk classification requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with e-bike assemblers, fleet procurement managers at delivery cooperatives, ANSM certification specialists, and specialty retailer service technicians. Bottom-up triangulation against top-down macroeconomic indicators validated volume estimates across the projection horizon.
Data-stream reconciliation combined unit shipment databases with value-chain markup analysis across the modeling period. Segmentation dimensions modeled include propulsion architecture, battery chemistry tier, end-user operational intensity, and sales channel service bundling. CAGRs derived from curve-fitting historical adoption patterns against infrastructure investment timelines and regulatory phase-in schedules. Forecast inputs incorporated Grand Paris Express corridor planning milestones and EU AI Act implementation velocity.
Lithium and cobalt price volatility, ANSM safety framework evolution, and EU AI Act enforcement discretion are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in battery-recycling mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Belgium E-Bike Market