
 Global Lubrication Pumps Market | 2026-2036
Global Lubrication Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lubrication Pumps Market Outlook
REACH compliance is hardening material certification requirements for lubrication pump manufacturers serving European industrial buyers. SKF Group leverages its integrated bearing-lubrication platform to dominate precision applications across Nordic manufacturing corridors. Graco Inc. sustains technology leadership in electric pump architectures through dedicated R&D facilities in Minnesota and Shanghai.
Lubrication pumps are positive-displacement or centrifugal devices engineered to deliver metered lubricant at controlled pressures, typically operating between 10 and 350 bar depending on industrial duty cycles. These systems reduce mechanical wear in rotating equipment by maintaining continuous oil or grease films between friction surfaces. Positive displacement pumps capture the dominant margin pool in heavy equipment applications, while electric pump technology is displacing pneumatic alternatives in automated manufacturing lines due to energy efficiency advantages and tighter ISO 4406 cleanliness integration.
The EPA enforces machinery fluid containment standards that shape pump sealing specifications in US industrial markets, while China's MEE implements dual carbon goals that tighten energy efficiency benchmarks for domestic pump manufacturers. ISO 4406 and DIN 51524 collectively define fluid cleanliness and lubricant compatibility thresholds that determine product eligibility across OECD procurement frameworks. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading impact on lubrication system lifecycle costing.
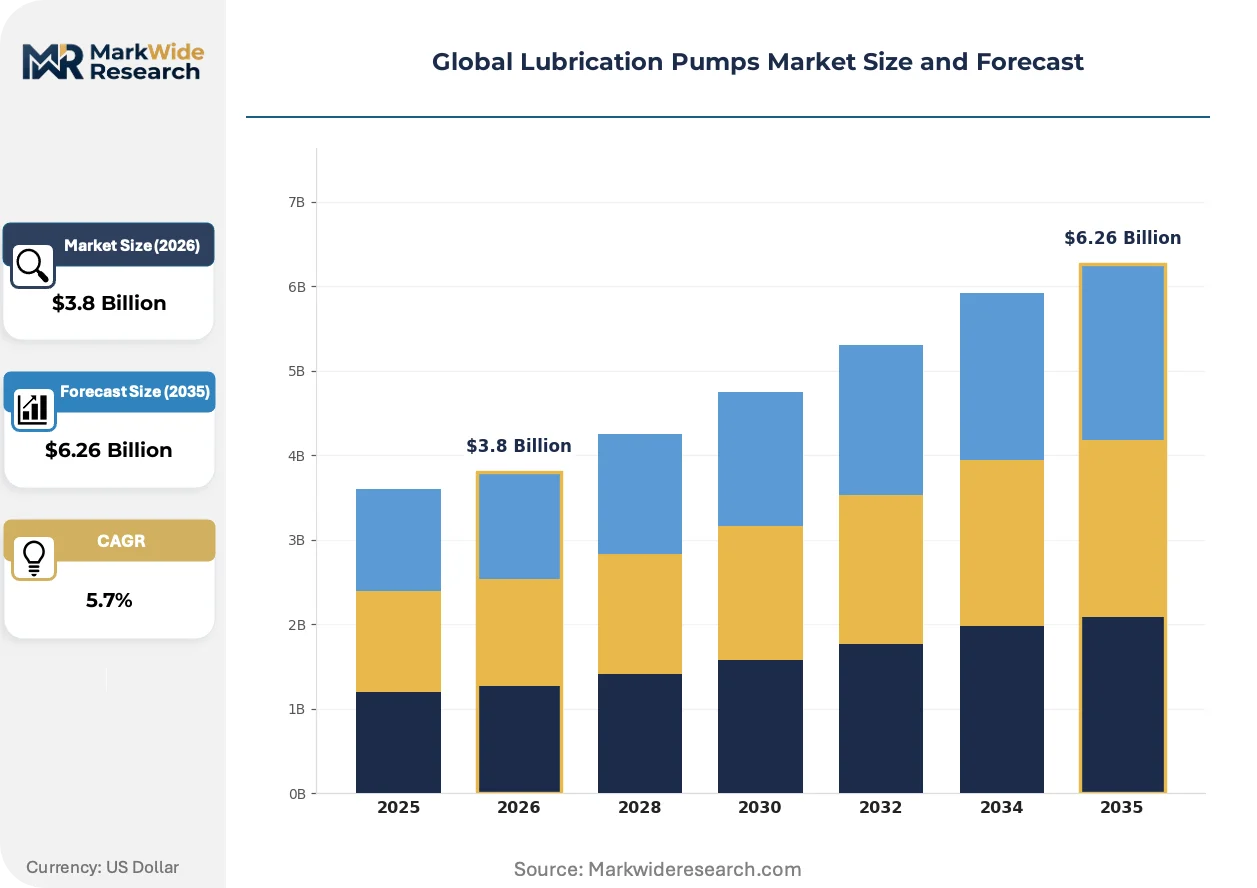
Market Dynamics
Electric pump architectures are displacing pneumatic systems across automated manufacturing lines, driven by ISO 4406 cleanliness mandates and dual carbon goals tightening energy efficiency benchmarks in industrial clusters worldwide.
Growth Catalysts
- EU F-Gas Regulation:Machinery efficiency mandates in Germany and Japan accelerate automated lubrication adoption, forcing precision pump upgrades in automotive and heavy equipment sectors.
- East Asian industrial clusters:South Korean automotive manufacturing hubs concentrate demand for metered lubricant systems operating at controlled pressures between 10 and 350 bar.
- Positive-displacement technology:Heavy equipment applications favor these pumps for maintaining continuous oil films between friction surfaces, capturing dominant margin pools in mining and construction.
Market Restraints
- Specialized alloy inputs:REACH compliance hardens material certification requirements, elevating raw material scrutiny for European-bound pump manufacturers.
- Nordic supply concentration:Integrated bearing-lubrication platforms dominate precision applications, creating dependency on specialized component suppliers in Scandinavian manufacturing corridors.
- Pneumatic legacy infrastructure:Existing pneumatic installations in mature industrial bases create switching cost barriers despite electric efficiency advantages.
Strategic Opportunities
- Carbon border adjustment mechanisms:Evolving EU trade instruments will recalibrate lifecycle costing for lubrication systems, favoring suppliers with documented carbon footprints.
- Indian manufacturing expansion:PLI scheme incentives for domestic industrial equipment production create white space for pump system localization under BIS standards.
- IoT-enabled condition monitoring:Convergence of sensor networks with electric pump architectures enables predictive maintenance contracts in semiconductor fabrication facilities.
Industry Challenges
- ISO 4406 integration complexity:Fluid cleanliness thresholds require recalibration of legacy sealing specifications, extending certification timelines for EPA-compliant US market entry.
- Cross-standard harmonization:DIN 51524 lubricant compatibility thresholds conflict with emerging OECD procurement frameworks, forcing dual-certification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lubrication Pumps Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Centrifugal, Gear, Diaphragm End User: Manufacturing, Automotive, Aerospace, Marine Technology: Electric, Pneumatic, Hydraulic, Manual Application: Heavy Equipment, Industrial Machinery, Automotive Maintenance, Food Processing |
| Companies Covered | Bijur Delimon International, Trico Corporation, SKF Group, Cenlub Systems, Groeneveld-BEKA, Lincoln Industrial, DropsA USA, Flowserve Corporation, Graco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lubrication Pumps Market Strategic Shifts
Digitalization and regulatory stringency are compressing product development cycles while elevating performance benchmarks across lubrication system architectures.
Smart electric pump systems with embedded flow sensors and edge computing capabilities are expanding into semiconductor cleanroom environments and precision machining centers. Medical device manufacturers in Switzerland and pharmaceutical equipment builders in Ireland adopt these systems at accelerated procurement cycles. The technology is expanding into applications previously served by centralized hydraulic systems, fragmenting the addressable market by performance tier.
China's MEE dual carbon goals and tightening GB standards enforce energy efficiency benchmarks that domestic pump manufacturers must meet for state-owned enterprise procurement eligibility. Industrial buyers now require documented power consumption curves and carbon intensity disclosures in tender documentation. Domestic champions in Shanghai and Shenzhen industrial parks accelerate R&D spending to maintain qualification under evolving national standards.
After-sales service unbundling is disrupting traditional distributor relationships in North American industrial supply chains. End-users in Minnesota automotive plants and Texas oilfield service operations now procure pumps directly from specialized system integrators, bypassing legacy distribution networks. This pattern concentrates most visibly in capital-intensive sectors where downtime costs exceed equipment purchase price multiples.
Global Lubrication Pumps Market Segmentation
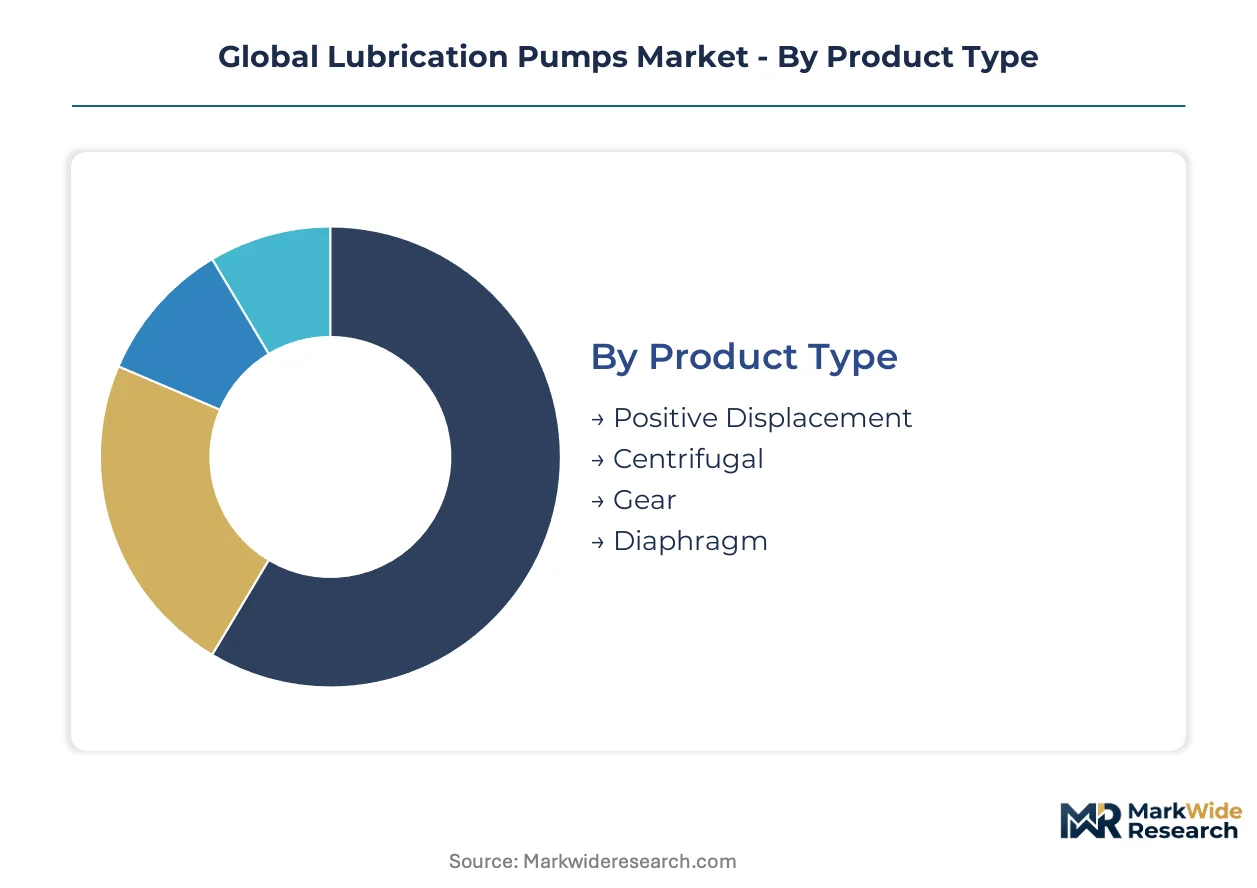
Segmentation in lubrication pumps reflects divergent engineering requirements across pressure ratings, automation levels, and contamination sensitivity. Technical specifications determine margin structures, while regulatory alignment shapes procurement eligibility in automotive and aerospace verticals.
Product Type:
Positive-displacement mechanisms dominate where precise volumetric delivery intersects with high-pressure tolerance.
- Positive Displacement:Reciprocating or rotary mechanisms meter fixed fluid volumes per cycle, achieving pressures up to 350 bar in mining haul trucks. German automotive stamping lines specify these for continuous film maintenance in progressive die systems.
- Centrifugal:Rotodynamic impellers generate flow through velocity conversion, suited for lower-pressure circulation in turbine lube oil consoles. Japanese thermal power operators favor these for their tolerance of ISO 4406 18/16/13 cleanliness grades without precision filtration.
- Gear:Intermeshing rotors provide steady pulseless flow for small-scale machine tool spindles requiring 10-40 bar delivery.
- Diaphragm:Flexible membrane isolation suits aggressive lubricant chemistries in chemical processing equipment where seal compatibility limits conventional architectures.
Positive Displacement leads on scale; Diaphragm leads on momentum in specialty chemical applications.
End User:
Capital intensity and downtime costs determine specification stringency across buyer categories.
- Manufacturing:Automated assembly lines in South Korean electronics plants demand electric pumps with embedded flow sensors for predictive maintenance contracts.
- Automotive:Powertrain assembly requires synchronized multi-point lubrication during engine block machining, with OEMs mandating DIN 51524 HLPD compatibility for centralized systems.
- Aerospace:MRO facilities in Singapore and Hamburg specify lightweight titanium-alloy pumps for aircraft engine overhaul, where F-Gas Regulation compliance constrains refrigerant-lubricant interactions.
- Marine:Slow-speed two-stroke engines in container shipping fleets use high-viscosity cylinder oil pumps designed for IMO 2020 sulfur compliance and extended at-sea service intervals.
Automotive commands procurement volume; Aerospace commands specification premium.
Technology:
Energy efficiency mandates and cleanliness standards are accelerating architecture transitions.
- Electric:Brushless DC motors with integrated drives enable precise flow control and IoT connectivity, displacing legacy systems in Minnesota automotive plants seeking EPA-aligned energy benchmarks.
- Pneumatic:Compressed-air actuation persists in explosive atmospheres and legacy installations where spark ignition risks override efficiency considerations.
- Hydraulic:Fluid-power drives survive in heavy mobile equipment where pump-motor integration simplifies circuit design for excavator swing mechanisms.
- Manual:Hand-operated pumps retain niche positions in maintenance access points and emergency backup systems for critical rotating equipment.
Electric captures investment flow; Manual retains residual function.
Application:
Duty cycle severity and contamination exposure dictate pump material selection and sealing architecture.
- Heavy Equipment:Articulated haulers and hydraulic mining shovels specify positive-displacement pumps with hardened steel gears for 250-bar peak pressures in abrasive environments.
- Industrial Machinery:Paper machine dryer sections and steel rolling mills require continuous-duty pumps with thermal management for 80°C+ operating temperatures.
- Automotive Maintenance:Quick-lube service bays favor compact electric pumps with rapid cycle capability for high-throughput oil change operations.
- Food Processing:NSF H1-certified pumps with 316 stainless steel wetted parts serve conveyor lubrication in dairy and beverage packaging lines under FDA and EU hygiene mandates.
Heavy Equipment anchors replacement demand; Food Processing climbs fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering talent and Japanese mechatronics expertise anchor regional demand concentration for high-specification lubrication systems across industrial corridors.
United States
EPA machinery fluid containment standards reshape pump sealing specifications for domestic industrial buyers. Minnesota automotive plants and Texas oilfield operations drive electric pump procurement for energy benchmark alignment. After-sales service unbundling concentrates in capital-intensive sectors where downtime costs exceed equipment purchase multiples.
Germany
Automotive stamping lines and progressive die systems specify positive-displacement pumps for continuous film maintenance. EU F-Gas Regulation and REACH compliance harden material certification requirements for machinery efficiency mandates. Nordic manufacturing corridors host integrated bearing-lubrication platforms dominating precision applications.
China
MEE dual carbon goals enforce energy efficiency benchmarks for state-owned enterprise procurement eligibility. Shanghai and Shenzhen industrial parks accelerate R&D spending to maintain qualification under tightening GB standards. Domestic manufacturers document power consumption curves and carbon intensity disclosures in tender documentation.
Japan
Thermal power operators favor centrifugal pumps for tolerance of ISO 4406 cleanliness grades without precision filtration. METI efficiency mandates accelerate automated lubrication adoption across automotive and heavy equipment sectors. Nagoya and Osaka industrial clusters concentrate demand for metered lubricant systems.
South Korea
Automotive manufacturing hubs concentrate demand for electric pumps with embedded flow sensors for predictive maintenance contracts. MFDS-aligned procurement frameworks shape specification stringency in pharmaceutical equipment adjacent sectors. Seoul metropolitan industrial parks host electronics plants demanding synchronized multi-point lubrication systems.
Global Lubrication Pumps Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between integrated industrial groups with cross-product platforms and dedicated pump manufacturers with narrow application expertise. Three archetypes dominate: bearing-lubrication integrators, electric pump technology specialists, and regional fabrication houses serving legacy pneumatic installations. Competitive moves center on R&D facility expansion and strategic partnerships for IoT-enabled condition monitoring capabilities.
Within the integrated technology tier, SKF Group and Graco Inc. exemplify divergent strategic positioning. SKF anchors precision applications through bearing-lubrication platform integration. Graco occupies a position in electric pump architecture development with dedicated technical facilities. Lincoln Industrial and DropsA USA sit within the specialized distribution-focused segment serving North American industrial supply chains. Bijur Delimon International represents the international diversification archetype with broad geographic coverage.
| Leading Market Players |
|---|
| Bijur Delimon International |
| Trico Corporation |
| SKF Group |
| Cenlub Systems |
| Groeneveld-BEKA |
| Lincoln Industrial |
| DropsA USA |
| Flowserve Corporation |
| Graco Inc. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access for lubrication pump manufacturers, forcing carbon intensity documentation and specialized alloy certification that stratifies vendor tiers across European procurement frameworks. Buyers in German automotive stamping lines and Japanese thermal power clusters now require lifecycle cost disclosures that embed supply chain carbon footprints into contract valuations.
Pricing Analysis
Bundled after-sales service contracts command 15-25% premiums over unbundled equipment-only transactions in North American capital-intensive sectors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 4406-certified electric architectures from legacy pneumatic systems and basic manual pumps. Cost compression in mid-tier electric pumps is intensifying because domestic Chinese manufacturers undercut European incumbents on documented power consumption curves. Automotive OEMs exhibit lowest price sensitivity due to downtime cost multiples, while small-scale machine tool operators in emerging industrial clusters drive procurement volume at economy tiers.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to European industrial corridors is reshaping regional sourcing strategies for specialized alloy inputs. Supply concentrates in Germany, China, and Japan for precision-machined pump housings and hardened steel gear components. Hardened alloy steel, titanium alloys for aerospace applications, and NSF H1-certified stainless steel draw from concentrated metallurgical suppliers in Nordic and East Asian corridors. Single-source vulnerability persists for REACH-compliant seal compounds qualified under EU material certification frameworks. Distribution runs through specialized system integrators in North America and authorized distributor networks in European industrial supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lubrication Pumps Market functions as a stable compounder anchored by machinery efficiency mandates that perpetually refresh installed base demand across automotive and heavy equipment verticals.
For Market Incumbents: Anticipate margin compression from domestic Chinese electric pump manufacturers by deepening captive supply of precision-machined housings and embedded sensor modules. Prioritize certification investment in ISO 4406 cleanliness integration and MEE-aligned carbon intensity documentation to defend procurement eligibility in state-owned enterprise tenders. Channel control through direct system integrator relationships in Minnesota and Texas oilfield markets insulates against after-sales service unbundling.
For New Entrants and Emerging Players: IoT-enabled condition monitoring architectures offer technology-first wedge into semiconductor fabrication and pharmaceutical equipment sectors where predictive maintenance contracts command specification premiums. Target Indian manufacturing expansion under PLI scheme incentives, where BIS standards compliance creates localization white space against established European incumbents. Pursue joint development agreements with domestic industrial park operators in Shanghai and Shenzhen to accelerate GB standards qualification.
For Investors and Strategic Acquirers: Roll-up economics work for specialized electric pump technology specialists because customer concentration in automotive and aerospace verticals rewards scale in application engineering and aftermarket service infrastructure. Five-to-ten year viability rests on automation penetration curves in East Asian industrial clusters and carbon border adjustment mechanism implementation timelines. Monitor carbon intensity disclosure requirements in EU tender documentation as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive production of hardened steel gear components insulates margin from REACH-compliant alloy cost volatility. |
| IoT Sensor Module Development | Embedded flow sensors enable predictive maintenance contracts in South Korean semiconductor fabrication facilities. |
| Joint Venture for Indian Localization | PLI scheme qualification under BIS standards opens state-owned enterprise procurement channels. |
| Carbon Footprint Certification Program | Documented lifecycle costing aligns with EU carbon border adjustment mechanisms in German automotive tenders. |
| Direct System Integrator Partnership | Bypassing legacy distributors captures after-sales value in Minnesota automotive and Texas oilfield operations. |
Study Parameters
Direct dialogue with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across automotive, aerospace, and heavy equipment verticals grounded qualitative demand assessment. Secondary validation drew from SEC 10-K filings of diversified industrial conglomerates, customs and trade data for lubrication equipment imports, ISO certification registry databases, and EPA machinery fluid containment enforcement records. Bottom-up unit economics triangulated against top-down industrial production indices across the analysis window.
Bottom-up segment modeling projected positive-displacement, centrifugal, gear, and diaphragm pump architectures across manufacturing, automotive, aerospace, and marine end-use categories. Technology transition curves for electric, pneumatic, hydraulic, and manual drive systems anchored penetration assumptions throughout the forecast period. CAGRs derived from machinery efficiency mandate implementation timelines and automation adoption rates in East Asian industrial clusters.
The model holds under stable regulatory enforcement of ISO 4406 and DIN 51524 standards; deviation in carbon border adjustment mechanism scope or REACH material certification timelines would shift competitive positioning assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Automatic Tank Cleaning Systems Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Air Compressor Controller Market