
 Spiral Classifier Market | 2026-2036
Spiral Classifier Market Size, Share, and Industry Trends Forecast 2026-2036
Spiral Classifier Market Analysis
Modular equipment bundling is decoupling spiral classifier procurement from fixed-plant commitments across greenfield mining projects. Metso Outotec leverages its integrated minerals processing portfolio to anchor large-scale copper concentrator contracts in South America. FLSmidth & Co. A/S sustains technology leadership through advanced wear-liner materials that extend classifier service intervals. Weir Group PLC competes on aftermarket density, positioning dense local service networks as a counter to lower-cost Asian suppliers.
A spiral classifier is a mechanical separation device employing a continuously rotating helical screw within an inclined trough to sort solid particles by size and specific gravity, typically processing slurries at densities between 15% and 40% solids by weight; its primary purpose is to dewater, deslime, and size-classify mineral feed streams ahead of grinding or concentration circuits. High-efficiency spiral classifiers capture premium pricing in copper-gold operations where fine particle recovery directly impacts downstream flotation yields. Submerged configurations dominate iron ore installations where coarse sand separation at high tonnages remains the operational priority. Portable installation types are gaining traction in remote lithium brine evaporation projects across South America's salt flat regions.
ISO 15236 standards for bulk materials handling equipment shape mechanical design requirements across export-oriented manufacturing bases. Australia's state-based mine safety regulators enforce mandatory guarding and emergency-stop protocols on rotating classifier assemblies. China's SAMR implements conformity assessment procedures for mineral processing machinery sold under domestic tender processes. Stakeholders must monitor how evolving critical minerals security frameworks in North America and Europe redirect capital toward domestic beneficiation capacity.
Market Dynamics
Automated classification systems are decoupling procurement from fixed-plant commitments across greenfield mining projects, reshaping how operators deploy capital and structure maintenance contracts.
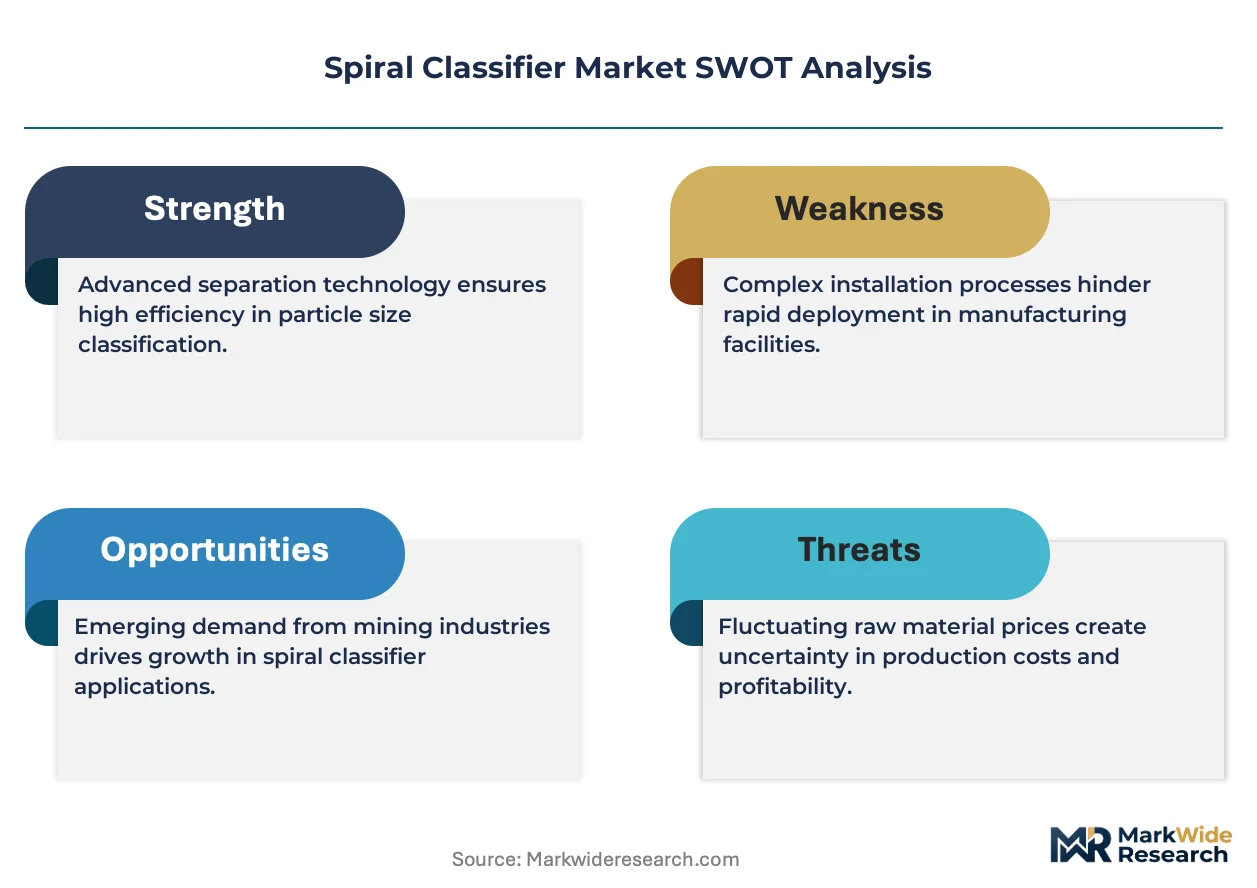
Growth Catalysts
- Australia's iron ore corridor expansion:Mining operators in Western Australia are expanding procurement of automated spiral classifiers to process high-tonnage coarse sand streams ahead of beneficiation circuits.
- China's GB emission thresholds:Tightening particulate emission standards under SAMR conformity assessment procedures are forcing domestic beneficiation facilities to upgrade classification equipment.
- Copper-gold recovery economics:High-efficiency spiral classifiers capture premium positioning in copper-gold operations where fine particle recovery directly impacts downstream flotation yields.
Market Restraints
- High-grade manganese liner costs:Advanced wear-liner materials extend service intervals but concentrate input cost volatility in specialty alloy supply chains.
- Asian supplier price pressure:Dense local service networks in established mining jurisdictions face structural margin compression from lower-cost equipment imports.
- Submerged configuration limitations:Iron ore installations requiring coarse sand separation at extreme tonnages face technical ceiling constraints on single-unit throughput capacity.
Strategic Opportunities
- Lithium brine evaporation projects:Portable installation types are gaining traction in remote salt flat regions across South America where fixed infrastructure is economically unviable.
- Critical minerals security frameworks:North American and European capital redirection toward domestic beneficiation capacity creates new demand pockets for modular classification systems.
- Sensor-augmented classification:Integration of real-time particle size analyzers with spiral classifier controls enables closed-loop optimization in copper concentrator circuits.
Industry Challenges
- Rotating assembly safety compliance:Australia's state-based mine safety regulators enforce mandatory guarding and emergency-stop protocols that extend commissioning timelines.
- ISO 15236 mechanical certification:Bulk materials handling equipment standards shape export-oriented manufacturing requirements across multiple certification bodies.
- Legacy flotation circuit integration:Greenfield automated classifiers must interface with existing grinding and concentration infrastructure without process disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiral Classifier Market |
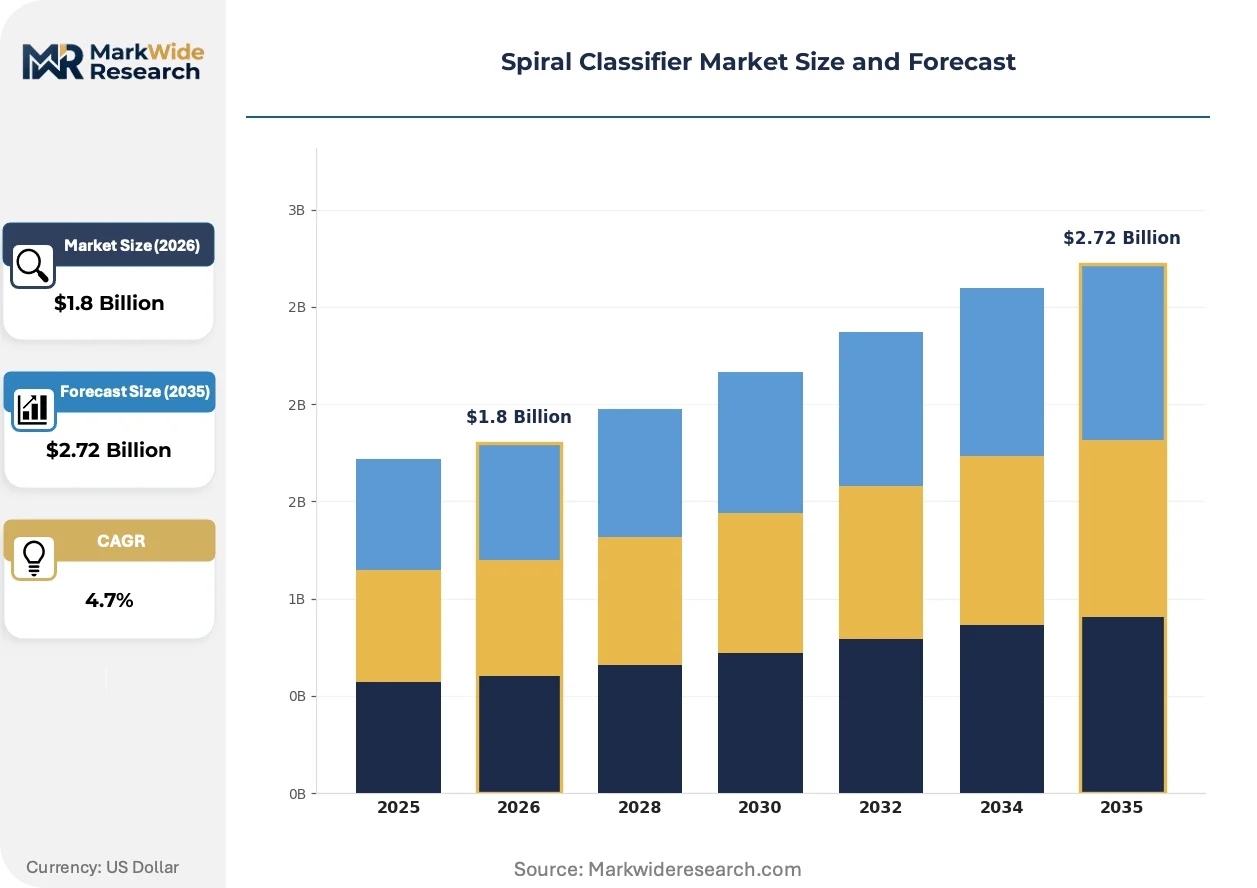
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Efficiency, Submerged, Dehydration, Hydraulic Installation Type: Stationary, Portable, Mobile, Modular End User: Mining, Wastewater Treatment, Chemical Processing, Construction Operation Mode: Continuous, Batch, Automated, Manual |
| Companies Covered | Metso Outotec, FLSmidth & Co. A/S, Weir Group PLC, Multotec, Xinhai, Thyssenkrupp AG, Binder+Co, Henan Zhengzhou Mining Machinery, HOT Mining, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiral Classifier Market Emerging Trajectories
Real-time process control, regulatory emission compression, and unbundled service models are actively reshaping how spiral classification equipment is specified, deployed, and maintained across mining jurisdictions.
Machine vision-based particle size analyzers integrated with variable-speed drive mechanisms are automating cut-point adjustment in spiral classifier operations. Copper-gold concentrators in high-altitude South American installations are adopting these systems fastest, typically achieving closed-loop control within eighteen months of commissioning. This convergence is automating the traditional operator-dependent tuning cycle and compressing response latency to ore variability.
China's SAMR has implemented expanded conformity assessment procedures for mineral processing machinery sold through domestic tender processes. The industrial consequence is a bifurcation between export-oriented manufacturers holding ISO 15236 certification and domestic suppliers pursuing parallel GB standard compliance. Western Australia's iron ore beneficiation corridors are most affected, as Chinese-owned mine operators must navigate dual certification requirements when sourcing from mainland equipment vendors.
After-sales service unbundling is fragmenting traditional full-service contracts into componentized maintenance, spare parts, and remote monitoring subscriptions. Dense local service networks in established mining clusters are being displaced by OEM-direct remote diagnostics paired with third-party field technician dispatch. This pattern is most visible in Chile's copper belt, where concentrator operators now separately negotiate wear liner supply, mechanical overhaul, and predictive analytics access.
Spiral Classifier Market Segmentation
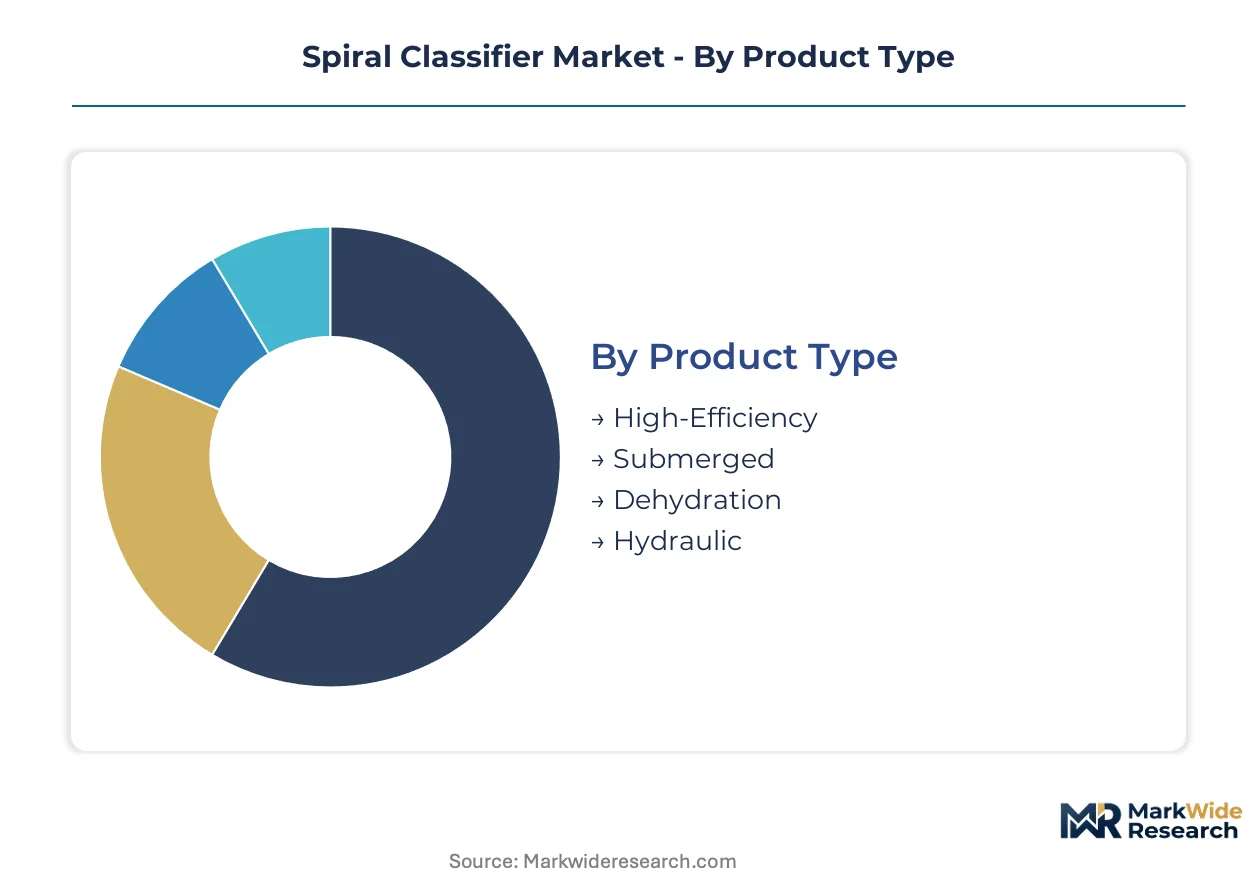
Spiral classifier procurement patterns diverge sharply across operational contexts, with capital intensity and mobility requirements driving fundamentally different equipment specifications. Mining operators prioritize throughput reliability over flexibility, while chemical processors balance precision against batch cycle economics.
Product Type:
Capital intensity peaks in high-efficiency configurations, where precision engineering and advanced wear materials concentrate upfront investment. Submerged designs trade some performance for durability in abrasive slurry environments.
- High-Efficiency:These units employ optimized helix geometries and variable-speed drives to achieve cut-point precision below 75 microns. Copper-gold concentrators in Chile's high-altitude operations specify these for fine particle recovery ahead of flotation circuits, where downstream yield sensitivity justifies premium procurement.
- Submerged:The screw mechanism operates below the slurry surface, enabling coarse sand separation at densities up to 40% solids by weight. Western Australia's iron ore beneficiation corridors deploy these for high-tonnage dewatering where abrasive wear dominates lifecycle economics.
- Dehydration:Specialized for solid-liquid separation in tailings management applications.
- Hydraulic:Uses water pressure differentials rather than mechanical rotation for particle classification.
Most installed capacity flows through Submerged configurations. Expansion is steepest in High-Efficiency units.
Installation Type:
Site permanence dictates foundation requirements and structural steel tonnage, with stationary installations representing the heaviest capital commitment per unit of throughput.
- Stationary:Fixed concrete foundations anchor these systems for decades-long service in permanent concentrator facilities. Brazil's Carajás iron ore complex and Western Australia's Pilbara hubs standardize on this architecture where ore body longevity exceeds equipment depreciation schedules.
- Portable:Skid-mounted or containerized frames enable rapid redeployment between satellite deposits. Argentina's lithium brine evaporation projects in the Puna region favor these for remote salt flat operations where road access precludes heavy-lift infrastructure.
- Mobile:Trailer-mounted units serve construction aggregates and short-life mining contracts.
- Modular:Pre-engineered subsystems integrate with standardized plant footprints.
Stationary systems retain the largest installed base. Portable configurations are climbing the fastest as exploration shifts to remote jurisdictions.
End User:
Volume concentration and ore abrasiveness create divergent equipment specifications across mineral processing versus fluid treatment applications.
- Mining:Iron ore, copper, and gold operations drive the bulk of demand, with beneficiation circuits requiring continuous classification ahead of grinding and concentration stages. Australia's state-based mine safety regulators enforce mandatory guarding standards that shape equipment design for this segment.
- Wastewater Treatment:Municipal and industrial effluent facilities employ smaller-capacity units for grit removal and primary solids separation.
- Chemical Processing:Fertilizer and specialty mineral producers use batch-configured classifiers for controlled crystallization and product sizing.
- Construction:Aggregate producers deploy portable units for sand classification and fines recovery.
Mining absorbs the majority of new capacity. Wastewater treatment is gaining share fastest as infrastructure investment accelerates in emerging economies.
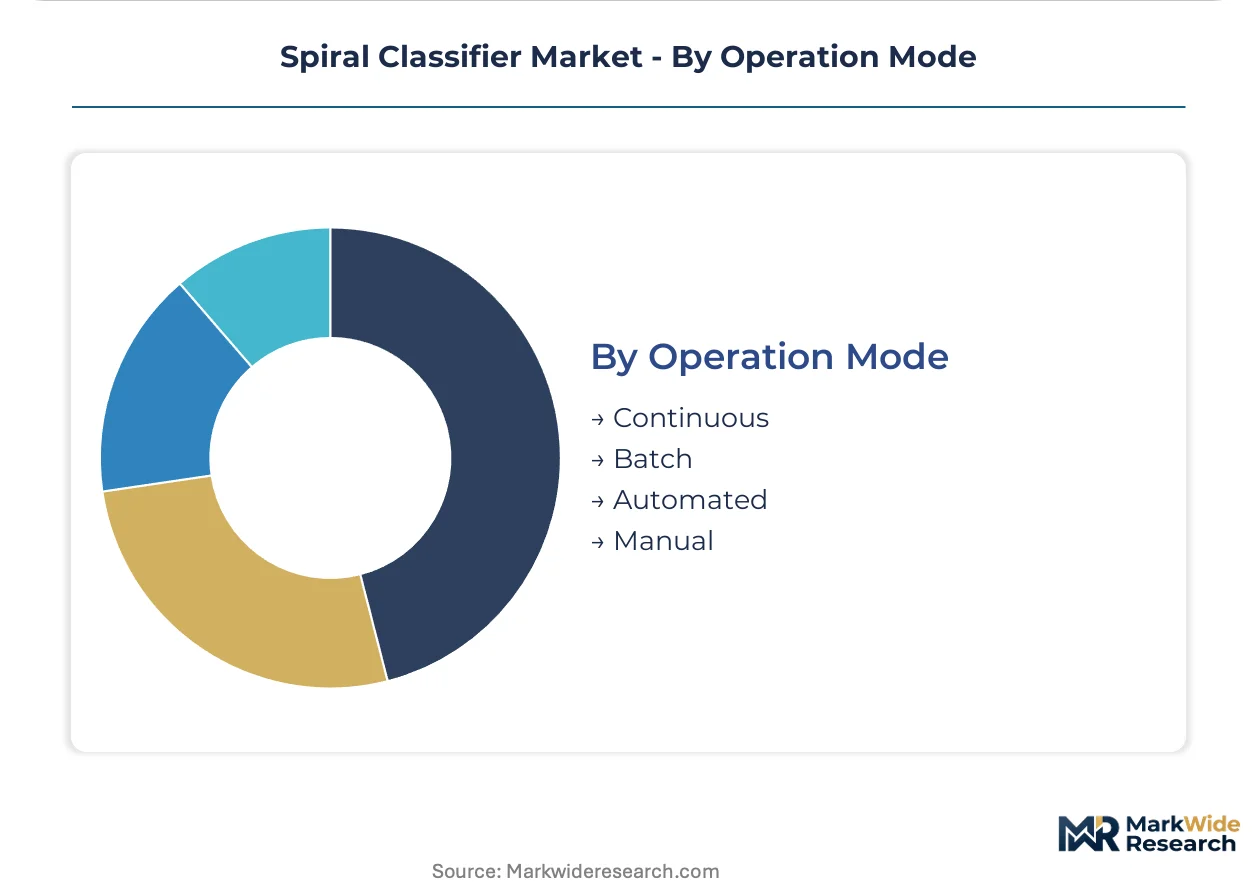
Operation Mode:
Automation intensity determines labor economics and process control precision, with capital deployment heaviest in sensor-integrated continuous systems.
- Continuous:Uninterrupted slurry feed matched to rotating screw speed maintains steady-state classification. Copper concentrators in Peru's Cerro Verde and Las Bambas operations specify these for integration with real-time particle size analyzers enabling closed-loop cut-point optimization.
- Automated:Variable-speed drives and machine vision systems adjust operating parameters without operator intervention.
- Batch:Discrete slurry charges process through timed cycles for laboratory or pilot-scale applications.
- Manual:Operator-controlled speed and feed adjustments persist in small-scale mining and maintenance-light installations.
Continuous systems dominate existing installations. Automated configurations are expanding most quickly as labor costs rise and sensor costs fall.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spiral classifier technology originated in European mining districts during the early twentieth century, with German and Scandinavian engineering firms pioneering the helical separation mechanisms that now dominate mineral beneficiation circuits worldwide. Contemporary procurement concentrates in iron ore corridors, copper-gold belts, and emerging lithium jurisdictions where abrasive slurry processing demands robust mechanical classification.
Australia
Western Australia's Pilbara iron ore operators drive the largest installed base of submerged spiral classifiers, processing high-tonnage coarse sand streams ahead of beneficiation. The country's state-based mine safety regulators enforce mandatory guarding and emergency-stop protocols on rotating classifier assemblies. Perth-based engineering clusters support dense aftermarket service networks across the Kalgoorlie and Newman mining hubs.
China
Domestic beneficiation facilities are upgrading classification equipment to meet tightening particulate emission thresholds under SAMR conformity assessment procedures. GB standards for mineral processing machinery now require parallel compliance alongside ISO 15236 for export-oriented manufacturers. Shandong and Henan provinces host the principal fabrication centers supplying both domestic tenders and Belt and Road mining projects.
Chile
High-altitude copper-gold concentrators in the Antofagasta and Atacama regions specify high-efficiency spiral classifiers for fine particle recovery ahead of flotation circuits. Chile's national mining regulator encloses strict mechanical safety standards for altitude-adjusted equipment performance. The Calama and Copiapó industrial corridors anchor South America's densest concentration of automated classification installations.
Brazil
The Carajás iron ore complex in Pará state standardizes on stationary spiral classifier architectures where ore body longevity exceeds equipment depreciation schedules. ANVISA-aligned industrial safety protocols govern rotating machinery in remote Amazonian installations. Belo Horizonte's mining engineering sector supplies technical services across the Minas Gerais iron quadrangle.
Argentina
Lithium brine evaporation projects in the Puna region's Salta and Jujuy provinces favor portable spiral classifier configurations where road access precludes heavy-lift infrastructure. The country's national mining secretary oversees equipment import regulations for critical minerals development. Catamarca's emerging salt flat corridor is attracting modular classification system deployments.
Spiral Classifier Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration and aftermarket service density, creating a tiered competitive structure in spiral classifier supply. The vendor base clusters around integrated minerals processing conglomerates, specialized wear-materials fabricators, and regional equipment assemblers serving price-sensitive procurement. Three archetypes dominate: full-line engineering houses bundling classification with grinding and flotation systems; component specialists concentrating on wear-liner innovation and extended service intervals; and emerging-market fabricators competing on delivered equipment cost. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as established players defend position in mature mining jurisdictions.
Among Nordic engineering conglomerates, Metso Outotec and FLSmidth & Co. A/S exemplify the full-line archetype, anchoring large-scale concentrator contracts through integrated minerals processing portfolios. Weir Group PLC occupies a position within the aftermarket-intensive tier, competing through dense local service networks rather than equipment cost leadership. These three entities represent distinct strategic postures: technology integration, wear-materials specialization, and service density respectively.
| Leading Market Players |
|---|
| Metso Outotec |
| FLSmidth & Co. A/S |
| Weir Group PLC |
| Multotec |
| Xinhai |
| Thyssenkrupp AG |
| Binder+Co |
| Henan Zhengzhou Mining Machinery |
| HOT Mining |
| Others |
Supply Flow & Price Mechanics
Concentrated welding and fabrication specialists in Shandong and Henan provinces anchor equipment manufacturing cost structures, with labor-cost differentials between Chinese fabrication centers and Nordic engineering hubs driving spreads between economy-tier and premium-tier spiral classifier procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated high-efficiency units from conventional submerged configurations and basic portable installations. Price differentiation rests on certification grade—ISO 15236 compliance versus domestic GB standard alignment—and aftermarket service bundling density. Pricing pressure stems from lower-cost Asian imports penetrating Western Australia's iron ore corridors. Greenfield lithium brine operators in South America exhibit highest price sensitivity; copper-gold concentrators in Chile's high-altitude belt demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Chinese fabrication centers to Australian mining hubs and South American salt flat regions shapes total delivered equipment economics. Manufacturing concentrates in China, Germany, and Finland. Specialty alloy supply for wear liners draws from South African manganese corridors and Australian chrome deposits. Single-source vulnerability concentrates in high-grade liner material supply chains. Distribution runs through OEM-direct channels for premium tiers and third-party mining equipment distributors for economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with beneficiation operators prioritizing fine particle recovery precision over capital cost minimization in copper-gold and critical minerals circuits.
For Market Incumbents: Extend service interval leadership through advanced wear-liner material R&D partnerships with specialty alloy suppliers. Deepen backward integration into helical screw casting capabilities to defend margin position against emerging Asian fabricators. Counter lower-cost imports by anchoring dense aftermarket networks in Western Australia's Pilbara and Chile's Antofagasta corridors. For New Entrants and Emerging Players: Mining engineering consultancies in Argentina's Puna region represent the most accessible channel partner type for portable configuration penetration. Target lithium brine evaporation projects where road access constraints preclude incumbent heavy-lift logistics. Pursue white-label supply agreements with modular plant integrators serving remote critical minerals developments. For Investors and Strategic Acquirers: Integrated minerals processing conglomerates are the most active acquirer in this space, seeking classification technology to complete beneficiation circuit portfolios. Five-to-ten-year viability favors component specialists with captive wear-materials technology. Monitor SAMR conformity assessment enforcement intensity as inflection signal for domestic Chinese supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wear Liner Production | Captive supply of high-manganese alloys insulates margin from South African chrome volatility. |
| Sensor-Augmented Classification System Launch | Machine vision integration with variable-speed drives automates cut-point tuning for copper concentrators. |
| Long-term Service Agreement with Pilbara Operators | Dense Perth-based technician networks lock out lower-cost Asian competitors in Western Australia. |
| Joint Venture with Lithium Brine Developers | Portable configuration partnerships penetrate Argentina's Salta and Jujuy salt flat corridors. |
| GB Standard Certification Investment | SAMR conformity assessment enables participation in Chinese domestic tender processes. |
Methodological Framework
Bottom-up mining operator procurement modeling reconciled against top-down equipment manufacturer shipment tracking forms the analytical core. Primary interviews with concentrator maintenance directors, beneficiation plant engineers, OEM procurement teams, and aftermarket service heads informed demand-side validation. Secondary sources include customs trade databases, mining company technical filings, state mine safety regulator equipment registration records, and mineral processing engineering association technical specifications.
Historical trendline analysis of installed base growth and replacement cycle timing anchored projection development across the analysis window. Segmentation dimensions modeled include product type efficiency tier, installation mobility class, end-use mineral category, and automation intensity level. CAGRs derived from equipment unit economics and average selling price trajectories. Forecast inputs incorporated iron ore corridor expansion timelines and lithium brine project development pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to critical minerals security policy shifts and Chinese emission standard enforcement intensity. Forecasts reflect documented assumptions regarding ore grade degradation trends and labor cost inflation in established mining jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market