
 North America Electro Hydraulic Power Steering Market | 2026-2036
North America Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electro Hydraulic Power Steering Market Outlook
Modular rack assist kits bundled with integrated motor controllers is repositioning how Tier-1 suppliers configure steering platforms for light truck programs. ZF Friedrichshafen AG anchors its North American footprint through captive hydraulic component production in Michigan. Nexteer Automotive differentiates via steering system integration depth spanning column through rack architectures. JTEKT Corporation leverages its joint venture manufacturing base to sustain supply continuity across US and Mexican assembly plants.
Electro hydraulic power steering combines an electric motor-driven hydraulic pump with rack-and-pinion or recirculating ball gear mechanisms to provide variable assist torque based on vehicle speed and steering angle. The system reduces parasitic engine load relative to conventional belt-driven hydraulic pumps, cutting fuel consumption in internal combustion and hybrid powertrains. Rack assist configurations dominate factory-installed volumes due to packaging efficiency in front-wheel-drive platforms. Advanced hydraulic systems with speed-sensitive valving command margin premiums in premium pickup and SUV segments. Column assist architectures retain share in retrofit and custom applications where installation access constraints favor dashboard-adjacent mounting.
NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and fail-safe performance across US vehicle classes. EPA fuel economy regulations and California Air Resources Board emissions frameworks incentivize electro hydraulic adoption as a compliance pathway for light truck fleets. Transport Canada Motor Vehicle Safety Regulations align with US standards, creating integrated North American certification pathways. Stakeholders must monitor electrification crossover timing as battery electric platforms eliminate hydraulic steering entirely, compressing the addressable window for hybrid electro hydraulic solutions.
Market Dynamics
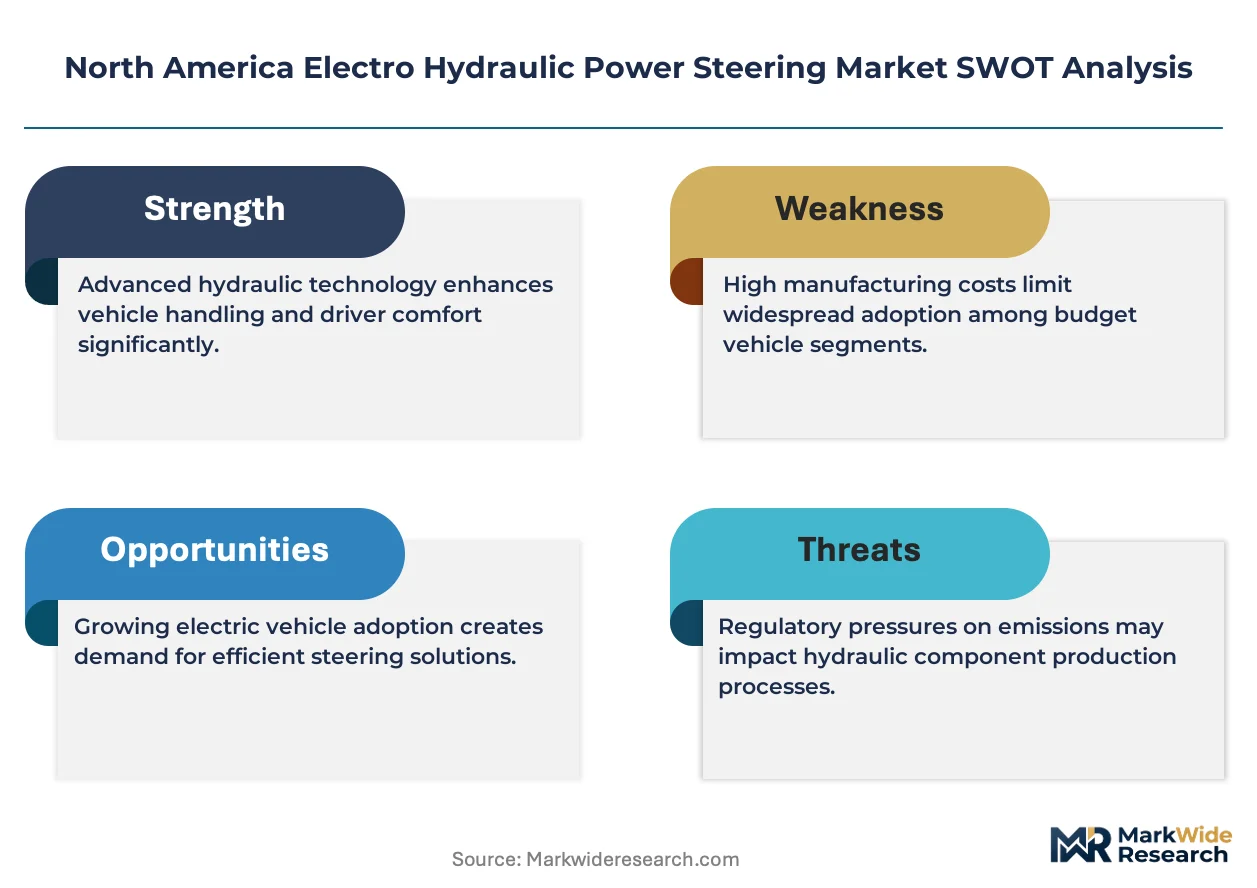
EPA fuel economy mandates and NHTSA safety standards are compressing the transition window for electro hydraulic steering, forcing suppliers to extract maximum efficiency from hybrid architectures before full electrification eliminates hydraulic systems entirely.
Growth Catalysts
- Corporate Average Fuel Economy standards:Light commercial vehicle fleets in the United States face tightening efficiency targets that electro hydraulic systems address through reduced parasitic engine load.
- Rack assist packaging efficiency:Front-wheel-drive platforms in Michigan and Ontario manufacturing corridors favor factory-installed rack configurations for space optimization.
- Transport Canada alignment with US regulations:Integrated North American certification pathways reduce compliance duplication costs for cross-border vehicle programs.
Market Restraints
- Electrification substitution threat:Battery electric platforms eliminate hydraulic steering entirely, compressing the addressable market window for hybrid solutions.
- Aluminum and rare earth input volatility:Electric motor components and lightweight rack housings face commodity price swings that destabilize supplier margins.
- Single-source hydraulic component concentration:Captive production facilities in Michigan create geographic supply risk during regional disruptions.
Strategic Opportunities
- Mexican assembly plant expansion:Joint venture manufacturing bases can sustain supply continuity across US-Mexico border production networks.
- Speed-sensitive valving premium segments:Advanced hydraulic systems command margin premiums in pickup and SUV categories where steering feel differentiation matters.
- Retrofit column assist channel:Dashboard-adjacent mounting architectures retain share in custom applications where installation access constraints block rack conversion.
Industry Challenges
- Mechatronics integration complexity:Combining electric motor controllers with hydraulic valving requires cross-functional engineering talent scarce in traditional steering shops.
- Fail-safe certification timelines:NHTSA Federal Motor Vehicle Safety Standards demand extensive validation cycles for steering system integrity under fault conditions.
- Legacy platform coexistence:Suppliers must maintain parallel hydraulic and full-electric development tracks while electrification timing remains uncertain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electro Hydraulic Power Steering Market |
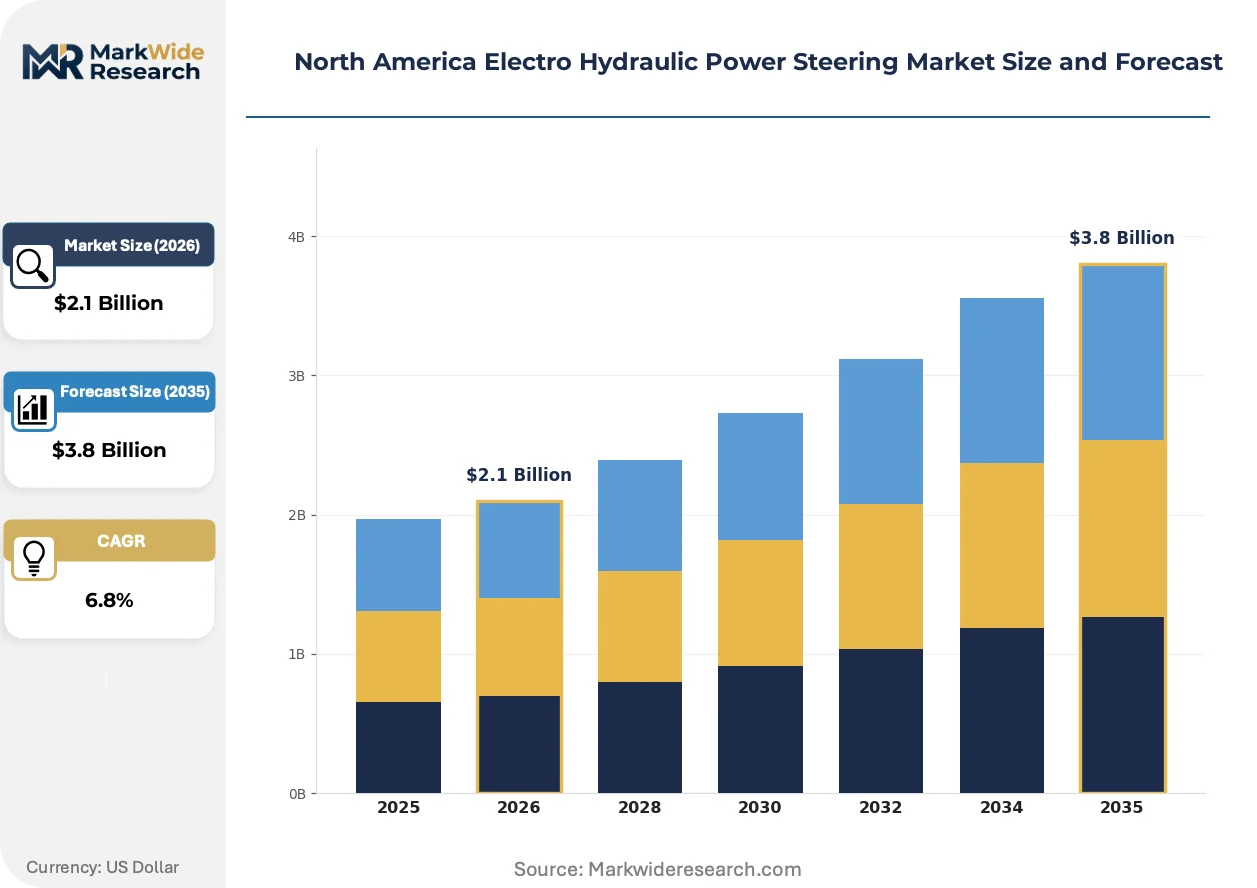
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Integrated Actuator, Motor Controller End User: Automakers, Aftermarket Providers, OEMs, Tier-1 Suppliers Technology: Conventional, Advanced Hydraulic Systems, Smart Steering, Articulated Control Installation: Factory-installed, Retrofits, Custom Applications, Modular Kits |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, ZF Friedrichshafen AG, NSK Ltd, Robert Bosch GmbH, Hyundai Mobis, Denso Corporation, Hitachi Astemo, Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electro Hydraulic Power Steering Market Strategic Shifts
Electro hydraulic architectures are undergoing rapid refinement as suppliers race to optimize efficiency and integration depth before battery electric platforms render hydraulic assistance obsolete.
Integrated motor controllers with modular rack assist kits are overtaking discrete component configurations in light truck programs. Tier-1 suppliers bundle hydraulic pumps, valving, and electronic control units into single subassemblies that reduce assembly line complexity. This consolidation is overtaking traditional column-mounted pump arrangements in front-wheel-drive platforms across Michigan and Ontario.
California Air Resources Board emissions frameworks are tightening compliance pathways for light truck fleets operating in the state. Manufacturers must demonstrate measurable fuel consumption reductions through verified powertrain technologies. Premium pickup and SUV segments respond with speed-sensitive valving investments that satisfy both regulatory thresholds and driver steering feel expectations.
Service unbundling is fragmenting traditional steering system procurement in aftermarket channels. Fleet operators now source hydraulic pumps, electronic controllers, and rack mechanisms from separate specialists rather than integrated system suppliers. This pattern concentrates in United States commercial vehicle retrofit markets where cost transparency outweighs single-source warranty convenience.
North America Electro Hydraulic Power Steering Market Segmentation
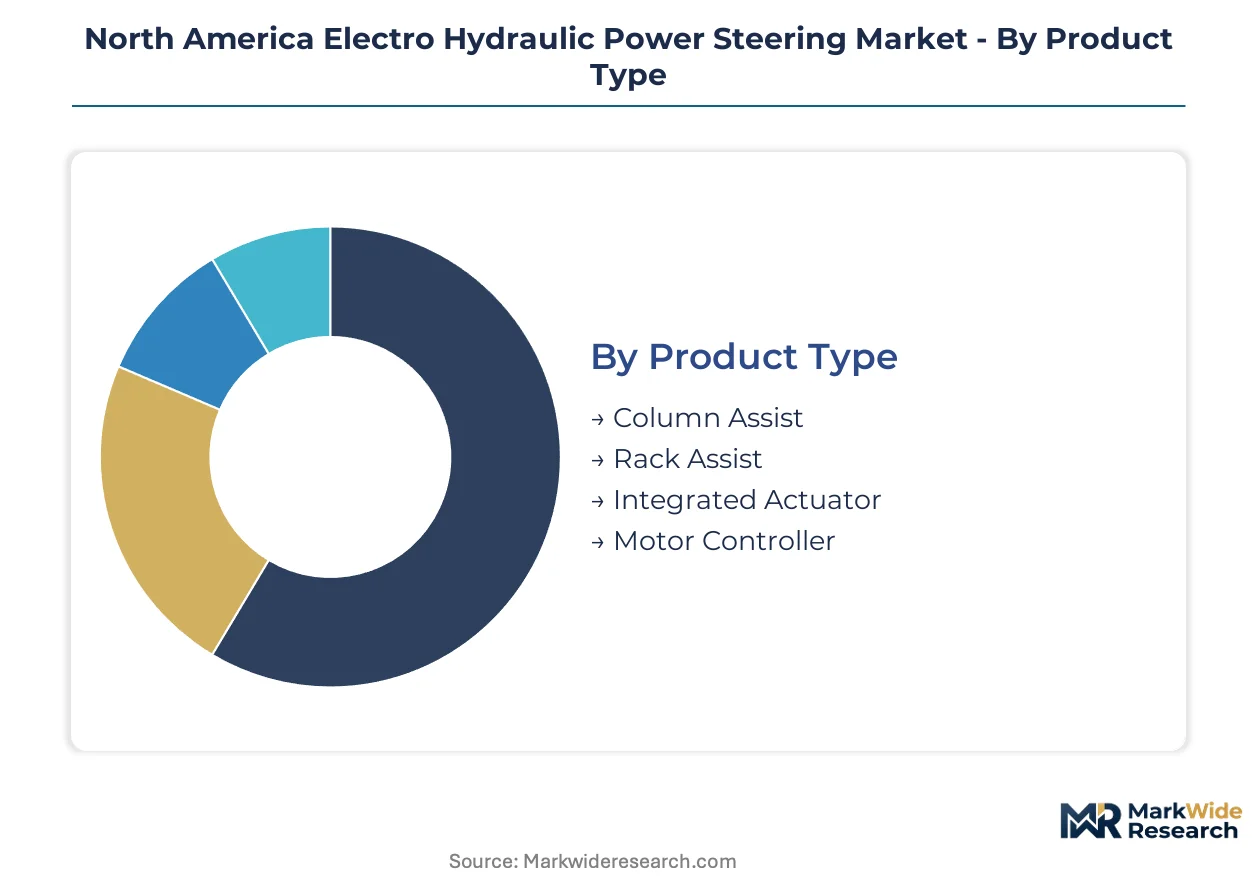
Electro hydraulic power steering systems fragment across four dimensions that determine pricing, certification pathways, and supplier engagement models. Product architecture dictates manufacturing location and integration depth. End-user category shapes procurement volume and technical support requirements.
Product Type:
Rack assist configurations command factory volumes while column architectures retain retrofit economics.
- Column Assist:Dashboard-adjacent mounting houses the electric motor and hydraulic pump assembly above the steering column. Demand concentrates in United States custom truck shops and Canadian fleet retrofitters where front-axle packaging constraints prevent rack conversion.
- Rack Assist:Integrated rack-and-pinion units embed hydraulic valving and motor controllers directly at the steering gear. Michigan and Ontario assembly plants favor this architecture for front-wheel-drive light trucks seeking CAFE compliance through parasitic load reduction.
- Integrated Actuator:Self-contained steering modules combining rack, motor, and controller in sealed housings.
- Motor Controller:Discrete electronic control units managing pump speed and valve timing.
Mature deployment sits with Rack Assist. Newer deployment is concentrated in Integrated Actuator configurations.
End User:
Procurement scale separates vehicle manufacturers from aftermarket channels.
- Automakers:Detroit Three and transplant manufacturers in Tennessee, Kentucky, and Mexico specify electro hydraulic systems for light truck platforms facing EPA fuel economy mandates. Their purchasing agreements span multi-year program lifecycles with stringent NHTSA fail-safe validation requirements.
- Tier-1 Suppliers:ZF Friedrichshafen AG, Nexteer Automotive, and JTEKT Corporation integrate electro hydraulic modules into complete steering columns and rack assemblies. Their engineering teams bridge hydraulic component sourcing with vehicle-level electronic architecture.
- Aftermarket Providers:Independent distributors and service chains serving United States commercial vehicle fleets.
- OEMs:Original equipment manufacturers outside traditional automaker structures, including specialty vehicle builders.
Volume concentration favors Automakers. Margin expansion is concentrated in Tier-1 Supplier integration contracts.
Technology:
Valving sophistication determines compliance tier and pricing band.
- Advanced Hydraulic Systems:Speed-sensitive valving and variable displacement pumps adjust assist torque based on vehicle speed, steering angle, and yaw rate. Premium pickup and SUV segments in Texas, California, and Alberta adopt these systems to satisfy CARB emissions frameworks while delivering differentiated steering feel.
- Smart Steering:Networked control architectures enabling lane-keeping assist and automated parking preconditioning.
- Conventional:Fixed-displacement pumps with mechanical valving.
- Articulated Control:Multi-axis hydraulic management for specialized commercial applications.
Regulatory compliance sits with Advanced Hydraulic Systems. Technology migration is concentrated in Smart Steering architectures.
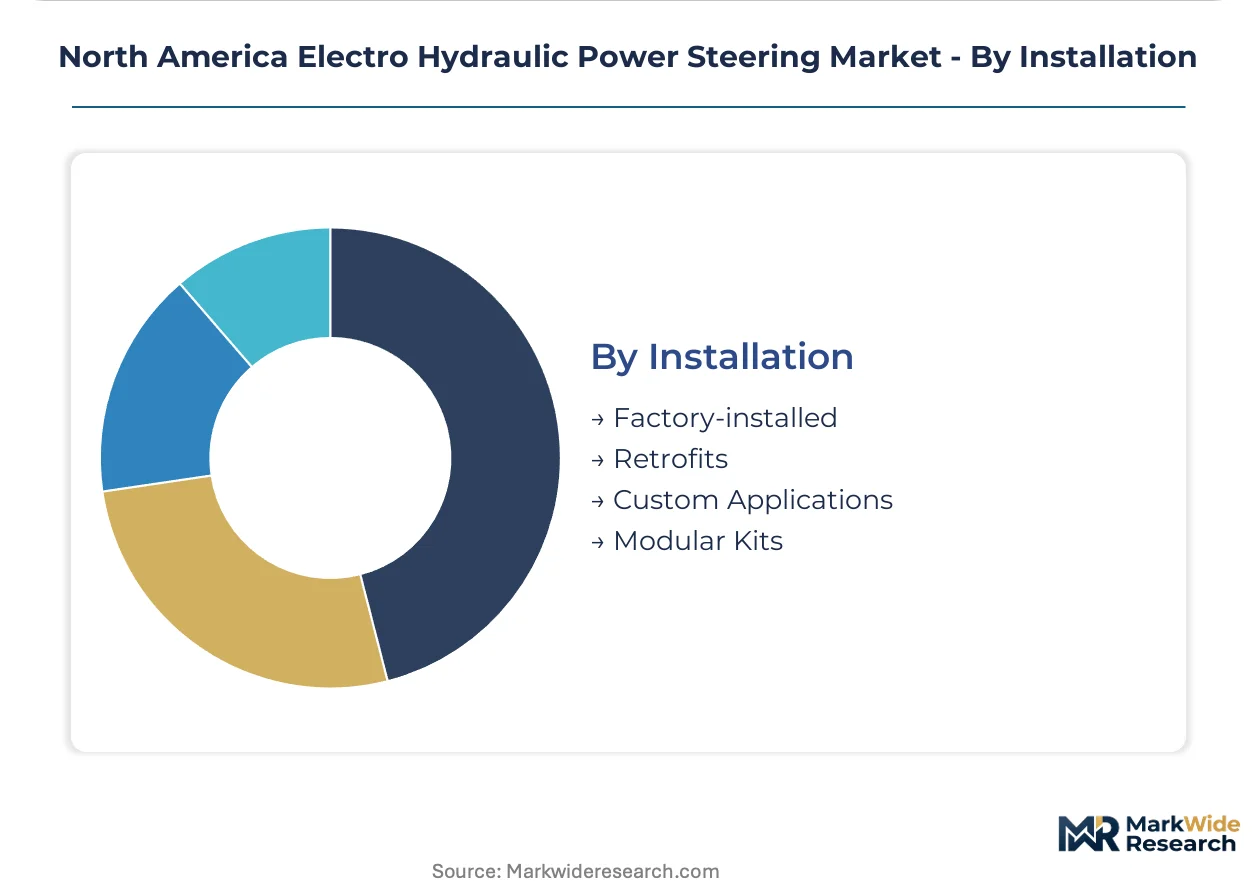
Installation:
Factory integration versus field deployment creates divergent supply chain economics.
- Factory-installed:Rack assist systems integrated during vehicle assembly at Michigan, Ontario, and Mexican plants. These configurations undergo full NHTSA Federal Motor Vehicle Safety Standards validation and carry manufacturer warranty coverage.
- Modular Kits:Pre-assembled pump, controller, and rack combinations enabling simplified dealer or fleet installation. United States light commercial vehicle operators favor these for mid-cycle efficiency upgrades without full platform redesign.
- Retrofits:Aftermarket conversions of conventional hydraulic systems.
- Custom Applications:Specialized configurations for off-highway or performance vehicles.
Certified volume sits with Factory-installed. Channel expansion is concentrated in Modular Kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the Great Lakes corridor while consumption distributes across the continent. Mexico's assembly plant expansion absorbs growing component volumes. Canadian regulatory alignment with US standards enables integrated cross-border supply chains.
United States
Light commercial vehicle fleets in Michigan and Ohio drive rack assist adoption to meet EPA Corporate Average Fuel Economy standards. NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity validation timelines. The Detroit Three automakers anchor factory-installed volumes in southeastern Michigan manufacturing clusters.
Canada
Ontario-based assembly plants serving North American truck programs source electro hydraulic modules from cross-border suppliers. Transport Canada Motor Vehicle Safety Regulations align with US NHTSA frameworks, eliminating certification duplication. The Windsor-Toronto manufacturing corridor concentrates Tier-1 integration facilities for front-wheel-drive platforms.
Mexico
Expanding light truck assembly in Nuevo León and Bajío Region creates demand for electro hydraulic steering components. Mexican automotive manufacturing incentives under the IMMEX program attract supplier joint ventures. JTEKT Corporation leverages its joint venture manufacturing base to sustain supply continuity across US and Mexican assembly plants.
North America Electro Hydraulic Power Steering Market Competitive Environment
The competitive structure tilts toward integrated system specialists with captive hydraulic component production. Three to five major suppliers control factory-installed volumes through multi-year purchasing agreements with Detroit Three and transplant manufacturers. The field separates into full-system integrators, hydraulic component specialists, and electric motor-controller suppliers. Capacity expansion and strategic partnerships dominate competitive moves as suppliers position for the electrification transition window.
Among full-system integrators, ZF Friedrichshafen AG and Nexteer Automotive occupy positions defined by steering system integration depth. JTEKT Corporation represents the joint venture manufacturing archetype sustaining supply continuity across US-Mexico border production networks. These three exemplify how Tier-1 suppliers bridge hydraulic component sourcing with vehicle-level electronic architecture.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Denso Corporation |
| Hitachi Astemo, Ltd. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned hydraulic component specialists in the Great Lakes corridor anchor Tier-1 supply relationships through captive production facilities, translating geographic concentration into pricing discipline that resists spot-market volatility. Their long-tenured OEM contracts in Michigan and Ontario insulate rack assist module pricing from commodity swings while reinforcing volume commitments that sustain margin stability across program lifecycles.
Pricing Analysis
Cost-down pressure on standard rack assist configurations accelerates because aluminum casting and rare earth magnet inputs face commodity volatility that Tier-1 suppliers struggle to pass through. Contract-based long-term offtake agreements dominate factory-installed volumes, with price differentiation resting on NHTSA certification tier and volume scale rather than brand premium. Fleet procurement teams at light commercial operators exhibit highest price sensitivity, while premium pickup segments absorb speed-sensitive valving premiums without volume elasticity.
Supply Chain Analysis
USMCA domestic-content mandates reshape sourcing patterns for electric motor controllers and precision-machined rack housings, pressuring suppliers to relocate subassembly steps from Asia to Mexico. Component flows draw from China for rare earth magnets, Germany for high-pressure hydraulic valves, and domestic Michigan facilities for rack gear machining. Single-source vulnerability concentrates in Michigan hydraulic pump casting operations, with distribution running through just-in-time sequenced delivery to assembly plants in Ontario and Nuevo León.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro hydraulic steering module capacity faces a structural ceiling as suppliers hesitate to expand hydraulic-focused footprints while battery electric platforms eliminate addressable demand, propping pricing power for incumbent integrators with secured OEM allocations.
For Market Incumbents: Deepen backward integration into aluminum die-casting and rare earth magnet sourcing to offset input volatility threatening rack assist margins. Secure multi-year platform commitments from Detroit Three light truck programs before electrification crossover accelerates, leveraging NHTSA validation timelines as a competitive moat against emerging electric steering specialists. For New Entrants and Emerging Players: Aftermarket distributors serving United States commercial vehicle retrofit channels represent the most penetrable entry vector, as fleet operators unbundle procurement across hydraulic pump, controller, and rack specialists. Target column assist architectures for custom truck shops in Texas and Alberta where front-axle packaging constraints block rack conversion and installation access premiums support margin capture. For Investors and Strategic Acquirers: JTEKT Corporation's joint venture manufacturing base expansion across US-Mexico border corridors is the leading indicator that supply continuity infrastructure retains strategic value through the electrification transition window. Position acquisition screening around Tier-1 suppliers with captive hydraulic production and validated NHTSA fail-safe certification pipelines, treating platform electrification announcements from major OEMs as the critical signal for long-term viability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering validation costs across light truck programs subject to EPA CAFE mandates. |
| Backward Integration | Captive aluminum casting and rare earth sourcing insulates margins from commodity volatility. |
| Joint Venture Manufacturing | IMMEX-compliant Mexican facilities sustain supply continuity across USMCA trade corridors. |
| Speed-Sensitive Valving Investment | Captures premium pricing in Texas and Alberta pickup segments facing CARB compliance thresholds. |
| Modular Kit Development | Enables mid-cycle fleet efficiency upgrades without full platform redesign engineering. |
Study Parameters
Document review covered SEC 10-K filings from steering system suppliers, NHTSA Federal Motor Vehicle Safety Standards validation databases, and EPA CAFE compliance reports, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distributors. Primary fieldwork engaged hydraulic component plant managers in Michigan, fleet maintenance directors at light commercial operators, and Transport Canada regulatory affairs specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, and USMCA trade flow statistics. Bottom-up volume builds and top-down market sizing triangulated across these inputs.
Historical shipment trajectories were cross-referenced against panel input from supplier sales executives to establish baseline momentum. The analytical framework segmented across vehicle class, propulsion architecture, and regional production cluster throughout the forecast period. CAGRs were derived from regression analysis of content-per-vehicle trends and platform electrification timelines. Forecast inputs incorporated OEM program lifecycle schedules, NHTSA safety standard revision pipelines, and rare earth commodity price scenarios.
Several conditions sit outside the modeled scope, including unannounced platform cancellations, sudden NHTSA regulatory reversals, and disruptive rare earth supply embargoes. Forecasts reflect documented assumptions about electrification crossover timing and USMCA content rule stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Powertrain Testing Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Engine Actuators Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Small Gas Engine Market
Powertrain
Transmission Control System Market
Powertrain
Automotive Half Shaft Market
Powertrain
Automotive Variable Discharge Oil Pump Market