
 Non-Glass Capacitive Sensors Market | 2026-2036
Non-Glass Capacitive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Glass Capacitive Sensors Market Analytics
Software-defined touch calibration is realigning how sensor vendors monetize hardware deployments. Apple Inc. leverages its ecosystem control to bundle firmware updates with sensor hardware across consumer devices. TPK Holdings Co. Ltd. anchors its revenue in manufacturing scale across Asian display supply chains. Cambrios Technologies Corporation specializes in silver nanowire formulations that compete on optical clarity against incumbent indium tin oxide alternatives.
Non-glass capacitive sensors detect proximity, touch, or position through electric field distortion using polymer, sapphire, or nanowire substrates rather than brittle glass, with typical dielectric constants ranging from 2 to 4 depending on base material. These sensors serve industrial and commercial purposes where mechanical flexibility, weight reduction, or impact resistance outweigh traditional glass performance. Touch sensors occupy the largest application share as smartphone and automotive display manufacturers abandon glass for curved or foldable form factors. Mutual-capacitance technology leads in precision multi-touch detection, while self-capacitance dominates cost-sensitive single-point applications. Wearable devices represent the fastest-growing application segment as fitness trackers and medical patches demand conformable, skin-contact-safe surfaces.
REACH substance restrictions in Europe and EPA chemical handling mandates in the United States shape material selection and disposal protocols for nanowire and polymer substrate production. China's GB standards and MIIT directives enforce local certification for capacitive components deployed in domestic automotive and consumer electronics manufacturing. Stakeholders must monitor evolving RoHS exemptions for indium-based materials and assess alternative conductor supply chains before committing to long-term substrate partnerships.
Market Dynamics
Automotive human-machine interface standardization is forcing substrate suppliers to abandon brittle glass in favor of polymer and nanowire alternatives that survive vibration, thermal cycling, and impact loads across vehicle lifecycles.
Growth Catalysts
- EV Display Integration:Electric vehicle manufacturers in China source locally produced non-glass capacitive sensors through domestic supply chains certified under MIIT directives for automotive electronics.
- REACH Material Substitution:European substance restrictions under ECHA frameworks are eliminating legacy glass-indium substrates from consumer electronics, redirecting procurement toward silver nanowire and polymer alternatives.
- Foldable Form Factor Adoption:Smartphone OEMs deploy mutual-capacitance sensors on flexible polymer bases to enable curved and foldable device architectures previously impossible with rigid glass.
Market Restraints
- Indium Supply Concentration:Refining and processing of indium tin oxide concentrates in Chinese smelters creates input cost volatility and geopolitical exposure for manufacturers still dependent on legacy conductor formulations.
- Optical Clarity Trade-offs:Polymer substrates exhibit higher haze and lower transmission coefficients than glass, limiting adoption in premium display segments where visual performance is non-negotiable.
- RoHS Exemption Uncertainty:Pending European Commission reviews of indium exemptions under Directive 2011/65/EU are freezing long-term substrate commitments as manufacturers await material compliance rulings.
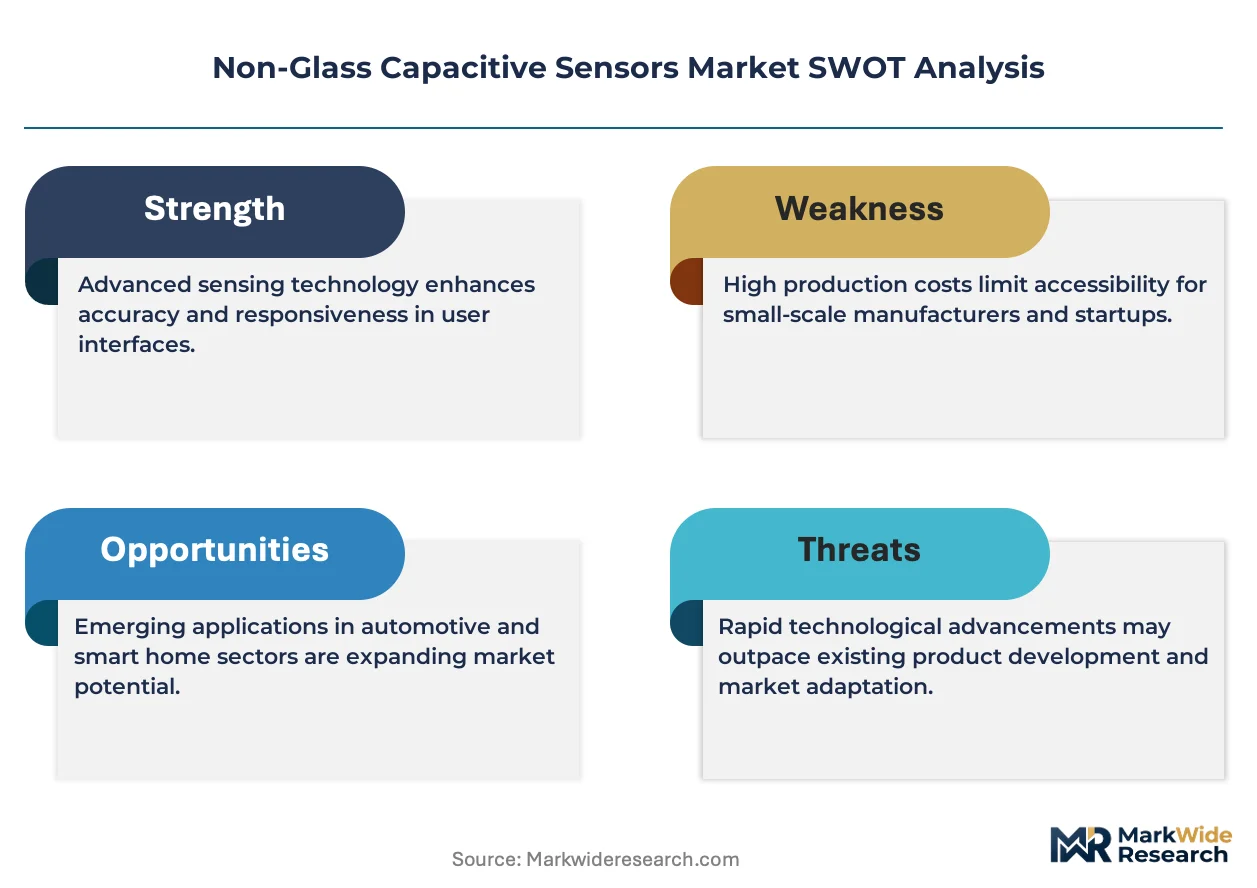
Strategic Opportunities
- Medical Wearable Expansion:Skin-contact-safe polymer sensors are penetrating continuous glucose monitors and cardiac patches where conformability and biocompatibility outweigh glass performance benchmarks.
- US IRA Clean Energy Credits:Domestic content requirements for electric vehicle components are incentivizing North American manufacturing of non-glass sensor substrates for automotive qualification.
- Silver Nanowire-Quantum Dot Convergence:Integration of Cambrios-style transparent conductors with emissive quantum dot layers is opening unified touch-display stacks for next-generation automotive and AR applications.
Industry Challenges
- Cleanroom Capital Intensity:Silver nanowire coating and patterning requires Class 1000 or better fabrication environments, demanding substantial upfront facility investment before yield stabilization.
- Multi-Regulatory Certification Lag:Simultaneous compliance with automotive AEC-Q200, medical ISO 13485, and consumer IEC 60950 standards extends product qualification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Glass Capacitive Sensors Market |
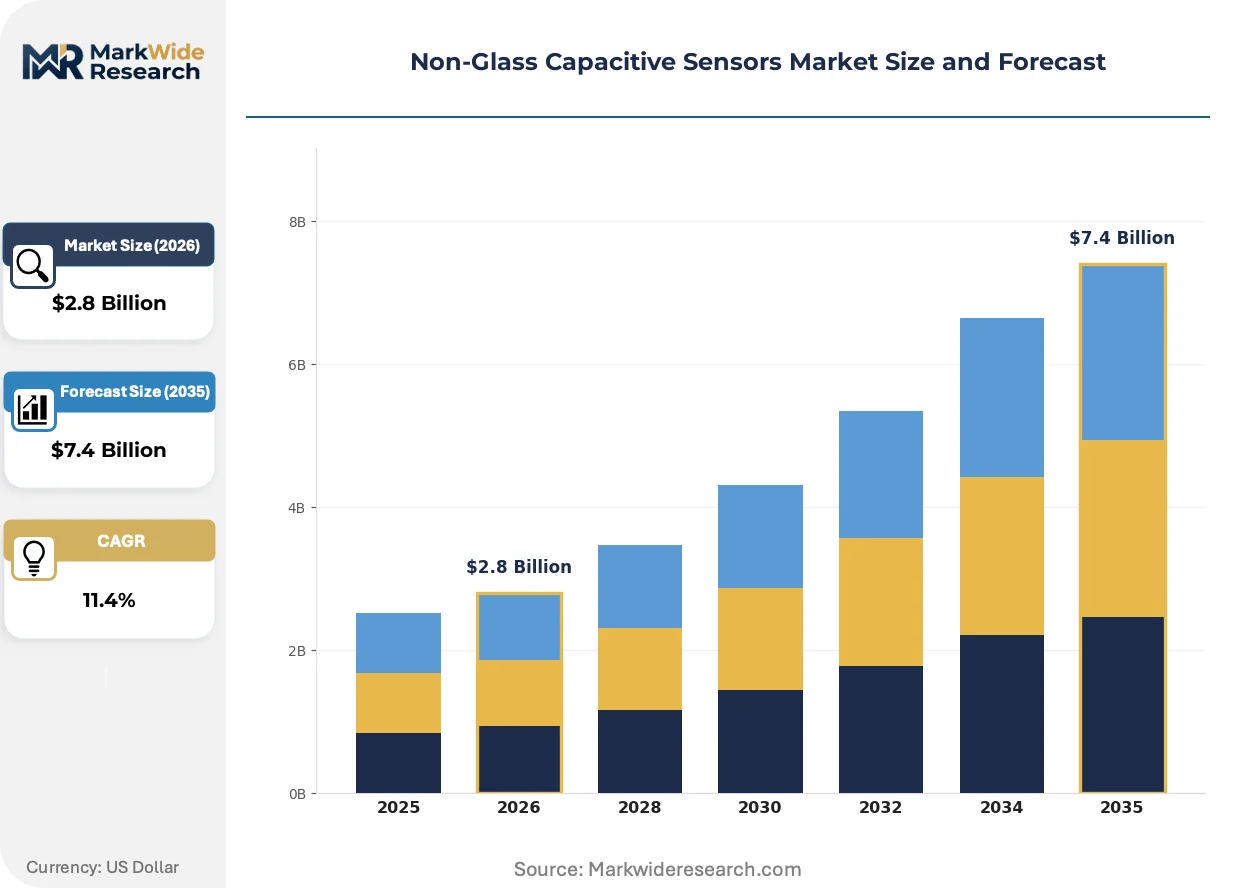
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touch Sensors, Proximity Sensors, Level Sensors, Position Sensors Technology: Self-Capacitance, Mutual-Capacitance, Active Capacitive, Passive Capacitive End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Application: Smart Appliances, Wearable Devices, Mobile Devices, Touchscreens |
| Companies Covered | Apple Inc., Cambrios Technologies Corporation, BASF SE, Canatu Ltd., Evonik Industries AG, General Electric Co., GT Advanced Technologies Inc., ILJIN Display Co. Ltd., TPK Holdings Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Glass Capacitive Sensors Market Evolving Landscape
Software-defined calibration architectures are decoupling sensor hardware from fixed performance profiles, enabling post-deployment optimization that extends product lifecycles and opens recurring revenue streams for substrate vendors.
Silver nanowire transparent conductors are electrifying the transition from indium tin oxide in large-format automotive displays. Tier-1 suppliers in Germany and Japan are qualifying nanowire-coated polycarbonate for curved instrument clusters. This substrate shift is electrifying price compression in the premium sensor tier as optical performance parity eliminates historical indium premiums.
EPA chemical handling mandates under TSCA Section 5 are tightening pre-manufacture notification requirements for nanoscale silver materials used in sensor production. US-based formulators must submit comprehensive toxicity and environmental fate data before commercialization. Medical device and automotive OEMs are responding by dual-sourcing from EPA-registered and EU-REACH-compliant suppliers to mitigate regulatory friction.
Automotive OEMs are consolidating touch sensor procurement through captive display module suppliers rather than direct substrate purchases. This channel compression is eliminating independent sensor vendors from Tier-1 supplier lists and concentrating volume with vertically integrated panel manufacturers in Korea and Taiwan. The restructuring is most visible in North American EV programs where single-source module contracts now bundle touch, display, and haptic feedback layers.
Non-Glass Capacitive Sensors Market Segmentation
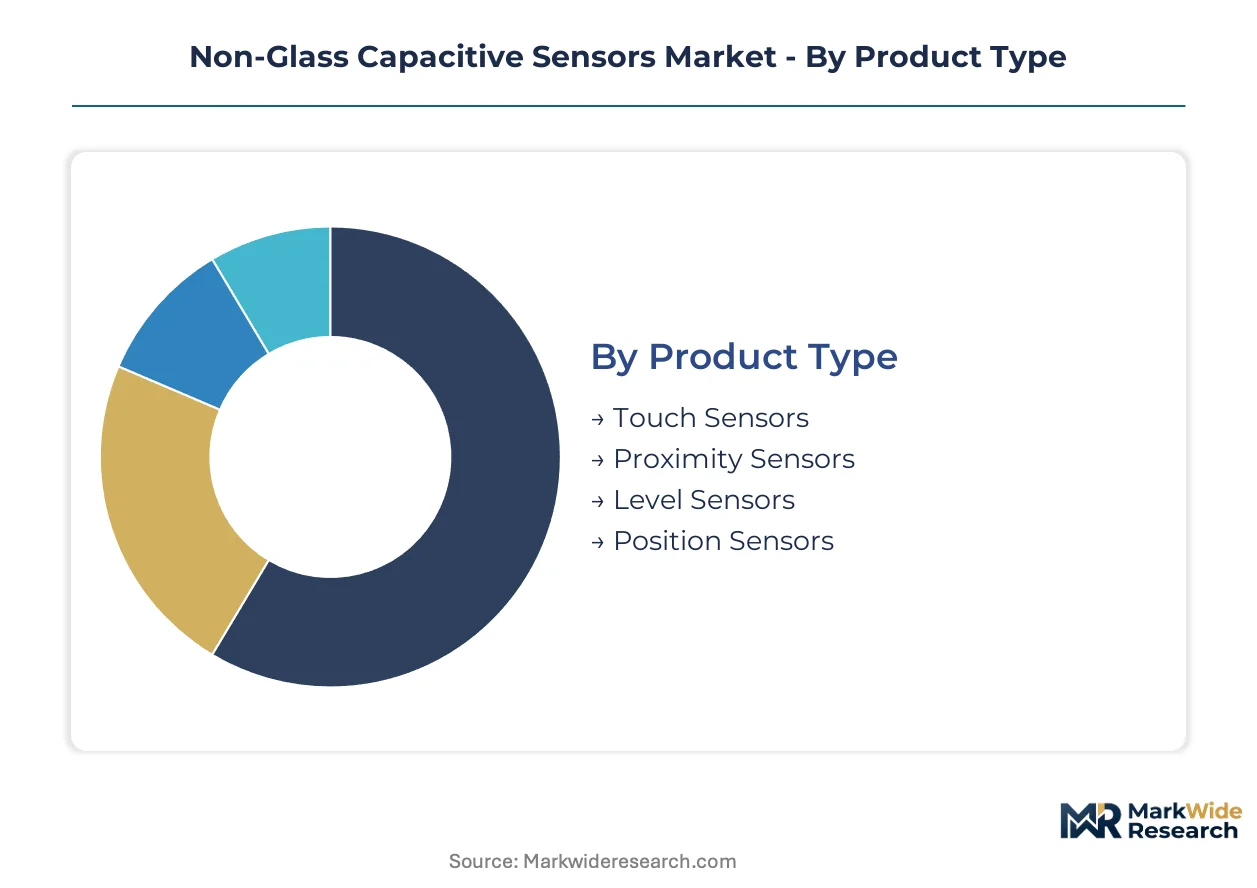
Non-glass capacitive sensors fragment across four distinct dimensions where substrate material, detection physics, and end-use environment dictate procurement priorities. Buyers evaluate dielectric performance, conformability requirements, and regulatory compliance before committing to sensor architecture.
Product Type:
Application complexity and surface geometry requirements determine which detection modality buyers prioritize for their specific deployment environment.
- Touch Sensors:These devices detect finger or stylus contact through capacitance change on polymer, sapphire, or nanowire substrates. Smartphone and automotive display manufacturers in China source these components through MIIT-certified domestic supply chains for curved and foldable form factors.
- Proximity Sensors:Operating through electric field distortion without physical contact, these sensors enable gesture recognition and wake-on-approach functionality. Industrial automation deployments in Germany favor these for machinery safety perimeters where mechanical durability outweighs precision requirements.
- Level Sensors:Capacitive level detection measures fluid or solid material height through dielectric constant variation. Food processing and chemical handling facilities specify polymer-housed variants to satisfy FDA and EPA chemical compatibility mandates.
- Position Sensors:Linear and angular position detection through capacitive coupling suits applications requiring non-contact measurement. Machine tool OEMs in Japan integrate these for precision motion control where glass fragility would introduce failure risk.
Volume sits with Touch Sensors; growth tilts toward Proximity Sensors.
Technology:
Detection precision requirements and multi-point capability needs split procurement between established mutual-capacitance architectures and cost-optimized alternatives.
- Self-Capacitance:Single-electrode detection measures capacitance between one plate and ground, offering simpler circuitry and lower unit cost. White goods manufacturers in India deploy these for basic button replacement in cost-constrained appliance interfaces.
- Mutual-Capacitance:Transmitter-receiver electrode pairs enable precise multi-touch coordinate mapping with superior signal-to-noise performance. Tier-1 automotive suppliers in Korea specify these for center-stack displays requiring simultaneous multi-finger gesture recognition.
- Active Capacitive:Excitation signal injection improves detection range and environmental immunity versus passive alternatives. Medical device manufacturers leverage these for through-barrier sensing in sterile packaging applications.
- Passive Capacitive:Unpowered detection relies on external field disturbance without dedicated excitation circuitry. Battery-powered IoT endpoints favor these for minimal standby current consumption.
Mutual-Capacitance commands premium pricing; Self-Capacitance expands most quickly in emerging appliance markets.
End User:
Certification burden and environmental stress specifications separate procurement patterns across vertical markets with divergent qualification timelines.
- Consumer Electronics:High-volume smartphone, tablet, and peripheral manufacturing demands optical clarity and mechanical flexibility for foldable architectures. Chinese OEMs source silver nanowire alternatives to glass-indium substrates through vertically integrated display module suppliers.
- Automotive:AEC-Q200 qualification, thermal cycling survival, and vibration immunity dominate specification requirements. European EV programs under ECHA REACH frameworks are eliminating legacy glass substrates from human-machine interface designs.
- Industrial Automation:Electromagnetic interference tolerance and IP-rated sealing take precedence over optical performance. Machine builders in the United States specify polymer-housed variants to satisfy OSHA machinery safety directives.
- Healthcare:ISO 13485 medical device certification and biocompatibility testing extend qualification cycles. Continuous glucose monitor and cardiac patch manufacturers favor skin-contact-safe polymer formulations.
Consumer Electronics anchors current volume; Healthcare demonstrates the steepest expansion trajectory on wearable device proliferation.
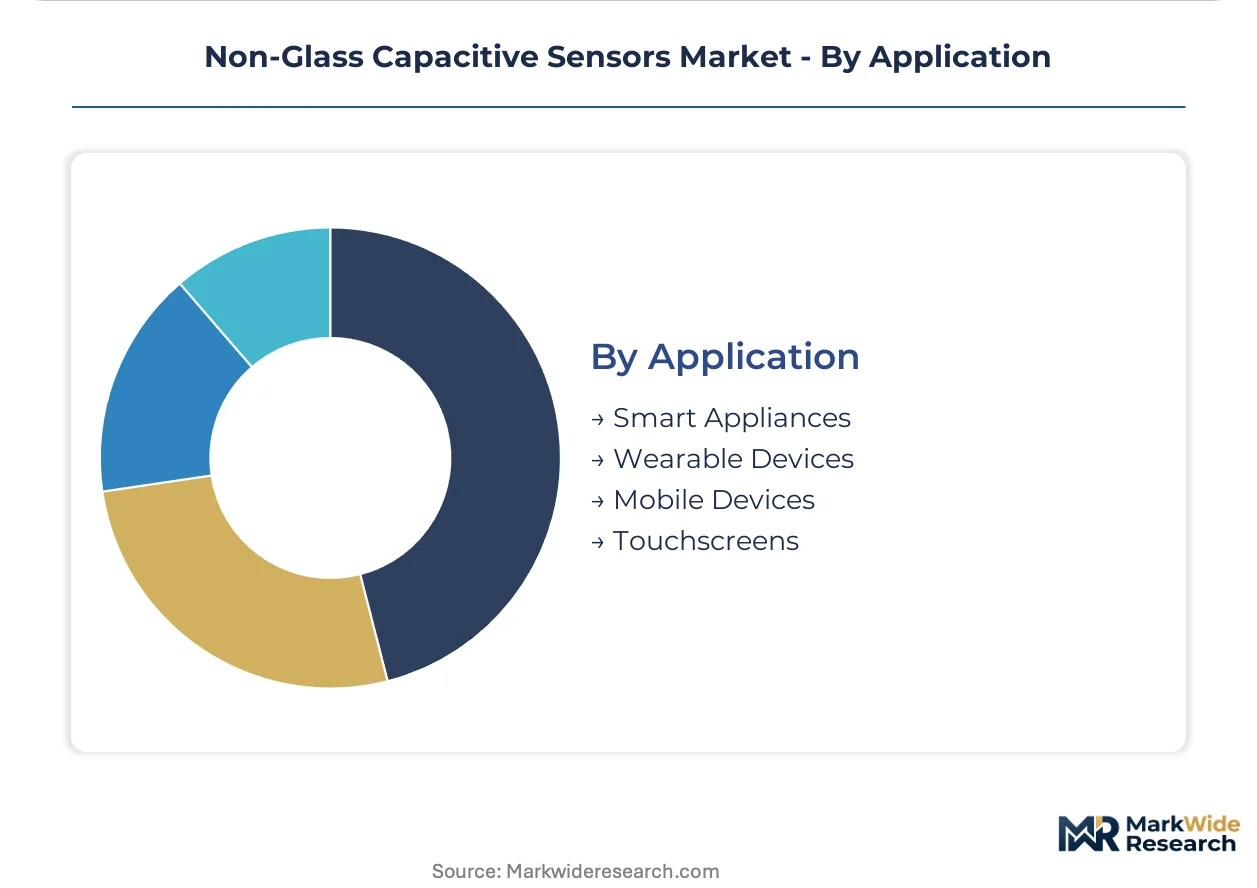
Application:
Surface area, curvature radius, and user interaction intensity shape substrate selection and electrode patterning decisions.
- Mobile Devices:Smartphone and tablet form factors demand high-resolution multi-touch on increasingly curved and foldable surfaces. Display panel manufacturers in Taiwan integrate touch layers directly into OLED stacks, compressing independent sensor vendor participation.
- Wearable Devices:Fitness trackers, smartwatches, and medical patches require extreme conformability and extended flex cycle survival. Korean and Chinese wearable OEMs are qualifying polymer substrates for skin-contact applications.
- Smart Appliances:Refrigerator, oven, and washing machine interfaces replace mechanical switches with capacitive control panels. Indian and Southeast Asian appliance manufacturers drive volume in cost-optimized self-capacitance implementations.
- Touchscreens:Large-format interactive displays for kiosks, whiteboards, and industrial terminals span diverse size and durability requirements. Automotive and commercial display integrators source these through captive module suppliers rather than direct substrate procurement.
Mobile Devices concentrate manufacturing scale; Wearable Devices gain share fastest on medical and fitness endpoint proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while consumption spreads across automotive and consumer electronics hubs in Europe and North America. China dominates substrate production through vertically integrated display supply chains. European demand accelerates as REACH compliance eliminates legacy glass-indium formulations from automotive human-machine interfaces.
China
Domestic EV manufacturers source non-glass capacitive sensors through MIIT-certified supply chains for curved instrument clusters and center-stack displays. GB standards enforcement requires local certification for automotive electronics deployment. The Yangtze River Delta anchors production, with Suzhou and Shanghai housing silver nanowire coating facilities serving Korean and Taiwanese display module integrators.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify polymer substrates for next-generation human-machine interfaces surviving thermal cycling and vibration loads. ECHA REACH substance restrictions are eliminating indium tin oxide from Tier-1 supplier qualification programs. Stuttgart's automotive cluster drives nanowire-coated polycarbonate adoption for curved instrument panels in premium EV architectures.
United States
Medical wearable manufacturers in Greater Boston and the San Francisco Bay Area demand skin-contact-safe polymer sensors for continuous glucose monitors and cardiac patches. EPA TSCA Section 5 mandates tighten pre-manufacture notification for nanoscale silver materials. The IRA clean energy credit framework incentivizes domestic substrate production for North American EV qualification.
South Korea
Display panel manufacturers in the Seoul Capital Area integrate touch layers directly into OLED stacks, compressing independent sensor vendor participation. MFDS medical device regulations shape biocompatibility requirements for wearable polymer formulations. Samsung and LG supply chains in Gyeonggi Province drive mutual-capacitance sensor volume for foldable smartphone architectures.
Japan
Machine tool OEMs in Nagoya and Osaka integrate capacitive position sensors for precision motion control where glass fragility introduces failure risk. METI industrial standards govern electromagnetic compatibility in factory automation deployments. The Chubu region's automotive electronics cluster qualifies polymer substrates for vibration-resistant human-machine interfaces in hybrid vehicle programs.
Non-Glass Capacitive Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the non-glass capacitive sensors market. Foundry-dependent substrate coaters face margin compression as captive display module suppliers internalize touch layer production. Three archetypes dominate: vertically integrated Asian display manufacturers, specialized silver nanowire formulators, and diversified materials conglomerates with polymer substrate portfolios. Capacity expansion in East Asian coating facilities and strategic partnerships between nanowire suppliers and automotive Tier-1s constitute the primary competitive vectors.
Among technology-specialist developers, Cambrios Technologies Corporation and Canatu Ltd. occupy positions anchored in transparent conductor formulations. TPK Holdings Co. Ltd. exemplifies the manufacturing-scale archetype across Asian display supply chains. Apple Inc. represents ecosystem-integrated hardware-firmware bundling. BASF SE and Evonik Industries AG sit within diversified chemical conglomerates leveraging polymer expertise for substrate material supply.
| Leading Market Players |
|---|
| Apple Inc. |
| Cambrios Technologies Corporation |
| BASF SE |
| Canatu Ltd. |
| Evonik Industries AG |
| General Electric Co. |
| GT Advanced Technologies Inc. |
| ILJIN Display Co. Ltd. |
| TPK Holdings Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Silver nanowire coating specialists in the Yangtze River Delta command wage premiums that widen pricing spreads between automotive-grade and consumer-grade sensor tiers. Labor-cost differentials between Suzhou cleanroom technicians and Southeast Asian assembly workers feed directly into tiered pricing structures across MIIT-certified supply chains.
Pricing Analysis
Price erosion across standard-grade polymer substrates traces to oversupply in Chinese coating capacity and aggressive quoting by domestic display module integrators. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 automotive certification from IEC consumer-grade and uncertified white-label supply. Certification grade and volume scale drive price differentiation, with OEMs qualifying dual sources extracting steeper discounts than single-source dependents. Consumer electronics buyers exhibit highest price sensitivity, while medical device manufacturers accept premiums for ISO 13485 traceability.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and US medical device manufacturers are forcing substrate coaters to qualify secondary silver nanowire formulators beyond primary Cambrios-style suppliers. Geographic supply concentrates in China, South Korea, and Taiwan, with raw material dependencies on silver bullion, PET substrate films, and photoresist chemicals. Single-source vulnerability in indium tin oxide legacy supply chains creates procurement risk as REACH deadlines accelerate material transitions. Distribution runs through captive display module suppliers rather than direct substrate procurement, compressing independent vendor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom capacity scarcity in Class 1000 nanowire coating facilities props sensor substrate pricing, constraining volume expansion for uncertified market entrants.
For Market Incumbents: Hedge against silver price volatility through long-term bullion contracts with London Metal Exchange-approved suppliers. Backward integration into PET substrate extrusion in Gyeonggi Province secures optical-grade film supply against Taiwanese petrochemical allocation cuts. Prioritize AEC-Q200 certification investment to defend automotive pricing premiums against emerging polymer competitors. For New Entrants and Emerging Players: Begin with medical wearable applications in Greater Boston and San Francisco Bay Area clusters where biocompatibility requirements limit incumbent participation. Skin-contact-safe polymer formulations for continuous glucose monitors represent the most penetrable white-space segment. Pursue FDA pre-submission pathways as primary go-to-market angle to differentiate from consumer-grade commodity suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with EPA-registered silver nanowire formulators given TSCA Section 5 compliance moats widening against unregistered competitors. Long-term viability favors specialists with dual REACH and EPA certification across the analysis window. Watch for RoHS exemption rulings on indium as inflection signal for legacy substrate obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silver Nanowire Capacity Expansion | East Asian coating facilities scaling output meet automotive qualification demand from Stuttgart OEM clusters. |
| Automotive Certification Investment | AEC-Q200 qualification opens Tier-1 supplier access for curved instrument cluster deployments. |
| Regulatory Dual-Registration | Simultaneous EPA TSCA and ECHA REACH compliance mitigates procurement friction for multinational OEMs. |
| Software-Defined Calibration Development | Firmware-update revenue streams extend hardware lifecycle monetization for substrate vendors. |
| Medical Wearable Biocompatibility Testing | ISO 10993 validation enables skin-contact sensor penetration in glucose monitoring patches. |
Research Methodology
Multi-period observation of silver nanowire coating capacity utilization, MIIT certification issuance rates, and automotive display module procurement patterns anchored the trend analysis, supplemented by interviews with cleanroom operations managers, Tier-1 automotive supplier procurement leads, display panel integration engineers, and medical device regulatory affairs specialists. Secondary validation drew from EPA TSCA pre-manufacture notification filings, ECHA REACH candidate list updates, SEC 10-K disclosures from listed sensor vendors, and Korean customs export data for transparent conductor films. Bottom-up unit shipment estimates triangulated against top-down display market value allocations.
The input-output matrix modeled sensor substrate demand across product type, detection technology, end-user vertical, and regional regulatory cluster dimensions. CAGRs derived from curve-fitting historical shipment trajectories against projected EV display integration rates and foldable smartphone adoption curves. Silver price volatility assumptions and cleanroom yield improvement curves fed sensitivity testing throughout the projection horizon.
RoHS exemption timeline revisions, EPA enforcement intensity fluctuations, and Chinese MIIT directive acceleration are the dominant revision risks to modeled outputs. Deviation in European Commission indium rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Force Sensor Market