
 Crown Block Market | 2026-2036
Crown Block Market Size, Share, and Industry Trends Forecast 2026-2036
Crown Block Market Outlook
Modular crown block packaging is recalibrating procurement patterns across drilling contractors. National Oilwell Varco leverages integrated mast-and-block systems to anchor its position in deepwater rig packages. Stewart & Stevenson competes through aftermarket service density across Texas and Oklahoma land operations. Baoji Oilfield Machinery dominates cost-engineered configurations for Chinese domestic rig builders.
A crown block is a stationary pulley assembly mounted at the top of a drilling mast or derrick, engineered to support multiple sheave wheels with rated load capacities typically spanning 250 to 750 short tons and designed to route drilling line in a block-and-tackle arrangement that suspends the traveling block and hook. Its primary function is to multiply mechanical advantage for hoisting drill strings, casing strings, and completion assemblies during rotary drilling operations. Conventional crown blocks retain volume leadership in land rig replacement cycles, though modular crown blocks are capturing margin pools through faster field assembly and reduced crane-time requirements. Wired crown blocks with integrated load-monitoring sensors are gaining traction in offshore drilling, where real-time tension data supports predictive maintenance programs and regulatory reporting obligations.
The American Petroleum Institute governs structural design and fatigue ratings through API 4F and API 8C specifications that dictate sheave groove geometry, bearing life calculations, and proof-load testing protocols for mast-mounted hoisting equipment. China's Ministry of Ecology and Environment enforces emissions and material traceability standards that affect foundry sourcing and heat-treatment documentation for domestic manufacturers. Stakeholders must monitor how API specification revisions and regional carbon-accounting requirements reshape supplier qualification timelines and capital allocation for fabrication capacity.
Market Dynamics
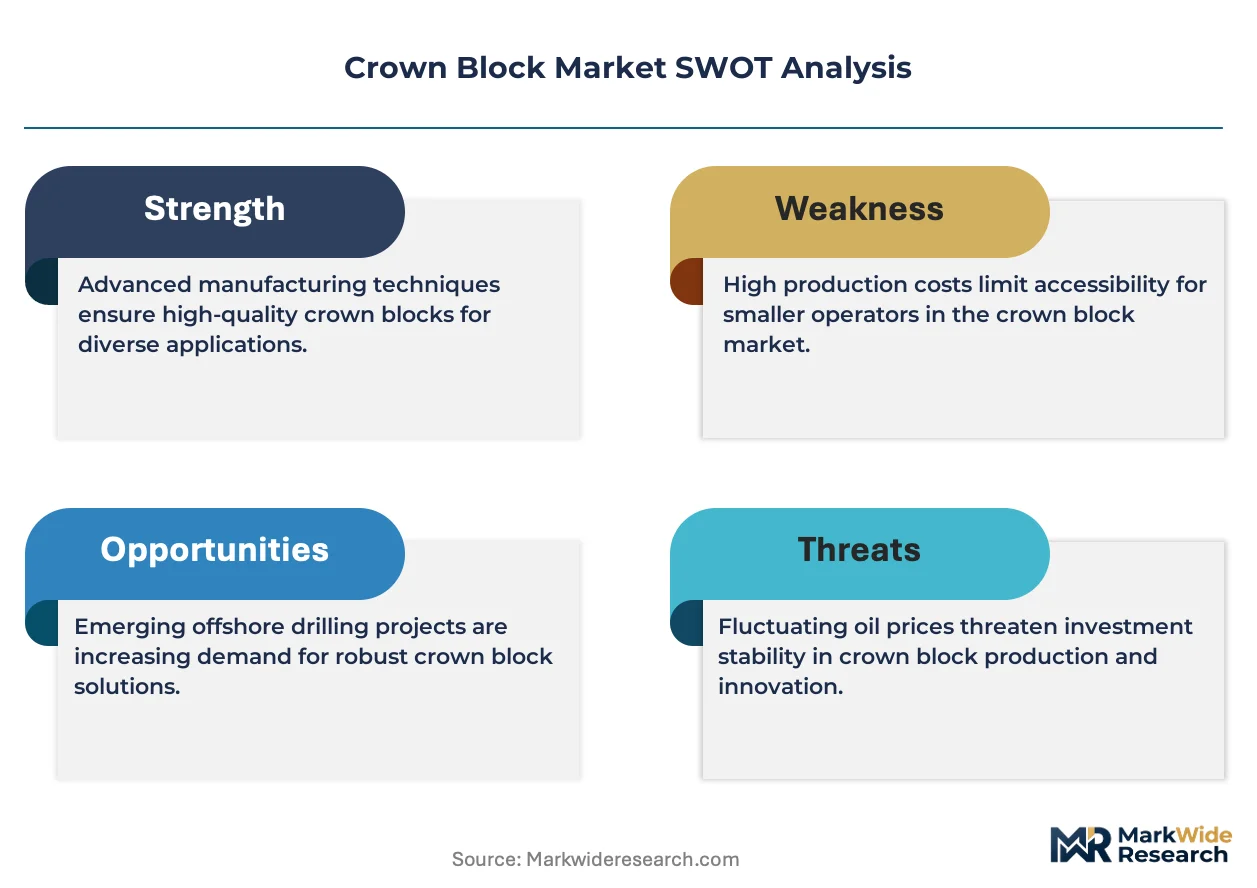
Modular crown block packaging is compressing field assembly timelines and displacing conventional welded-frame designs across land rig replacement cycles, while API 4F specification revisions and MEE emissions protocols in China simultaneously tighten material traceability requirements and heat-treatment documentation standards.
Growth Catalysts
- Offshore rig-retrofit programs:Deepwater drilling fleets are expanding crown block assembly upgrades to extend asset life and meet evolving load-rating requirements.
- API 8C proof-load testing protocols:Updated fatigue rating standards for mast-mounted hoisting equipment are mandating replacement of legacy sheave assemblies in active drilling corridors.
- Permian Basin drilling density:Sustained horizontal drilling activity across West Texas and southeastern New Mexico is concentrating demand for high-capacity crown block configurations.
Market Restraints
- Specialized alloy input volatility:Heat-treated steel forgings and high-grade bearing steels face price instability from concentrated foundry sourcing.
- Chinese domestic supply concentration:Cost-engineered crown block manufacturing clusters in Shaanxi province create dependency risk for budget-tier procurement.
- Structural fatigue limitations:Conventional welded-frame crown blocks face accelerated replacement cycles under extended-reach drilling loads.
Strategic Opportunities
- Wireline-integrated load monitoring:Sensor-embedded crown blocks enabling real-time tension data are penetrating offshore drilling contracts.
- Gulf Coast corridor aftermarket density:Service infrastructure gaps between Houston and New Orleans create white space for maintenance and refurbishment operations.
- MEE material traceability mandates:China's emissions documentation requirements favor suppliers with certified heat-treatment records and carbon-accounting systems.
Industry Challenges
- API 4F certification timeline compression:Revised structural specification testing protocols are extending supplier qualification periods for new fabrication entrants.
- Legacy mast integration complexity:Modular crown block retrofits face mechanical interface mismatches with existing derrick structures in active rig fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crown Block Market |
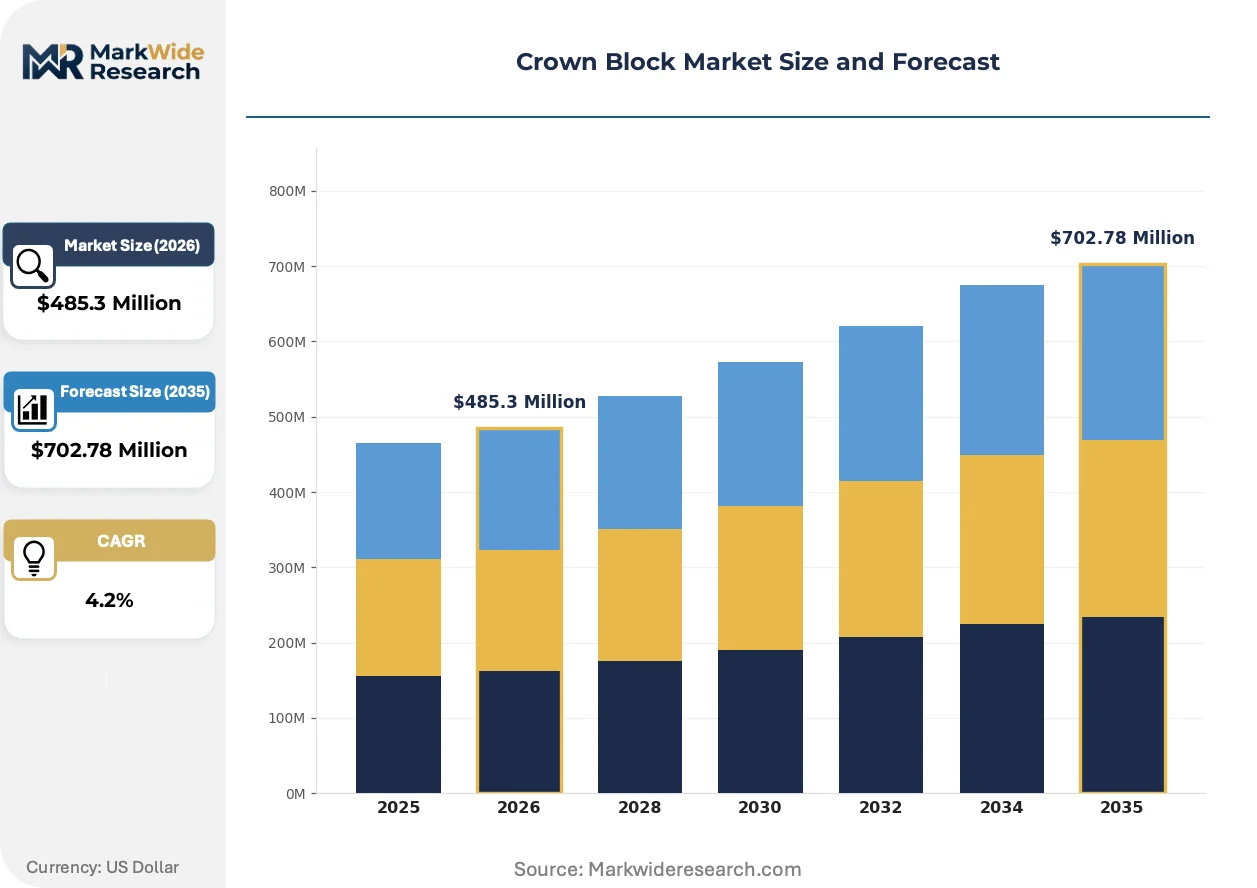
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $702.78 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Crown Blocks, Wired Crown Blocks, Roller Crown Blocks, Modular Crown Blocks Installation Type: Fixed Installation, Mobile Installation, Temporary Installation, Semi-permanent Installation Industry: Oil & Gas, Construction, Mining, Offshore Drilling Material Type: Steel, Aluminum, Composite, Others |
| Companies Covered | National Oilwell Varco, Stewart & Stevenson, Baoji Oilfield Machinery, American Block, Jereh Group, Nabors Industries, Alco Group, ZPEC, Lee C. Moore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crown Block Market Strategic Shifts
Wired sensor integration and modular field-assembly architectures are actively displacing conventional crown block designs across both offshore and land drilling operations, compressing procurement cycles while expanding predictive maintenance capabilities.
Modular crown block packaging with bolt-together frame sections is overtaking welded monolithic designs in land rig procurement. Drilling contractors in the Permian Basin and Mid-Continent region are specifying these configurations for 40-foot mast retrofits. The technology is compressing crane-time requirements from multi-day lifts to single-shift assemblies, enabling faster rig mobilization and reducing third-party heavy-lift dependencies.
API 4F specification revisions governing sheave groove geometry and bearing life calculations are mandating enhanced fatigue documentation for mast-mounted hoisting equipment. Domestic rig builders in the United States must now submit extended proof-load testing records to maintain equipment certification. Deepwater drilling contractors operating in the Gulf of Mexico are responding by accelerating replacement schedules for pre-2020 crown block assemblies to preempt compliance gaps.
Integrated load-monitoring systems are reshaping buyer specifications for offshore drilling packages. Real-time tension data transmission is displacing manual line inspection protocols in deepwater contracts. North Sea and Gulf of Mexico drilling operators are unbundling sensor maintenance from original equipment supply, creating dedicated service contracts for wired crown block calibration and data analytics.
Crown Block Market Segmentation
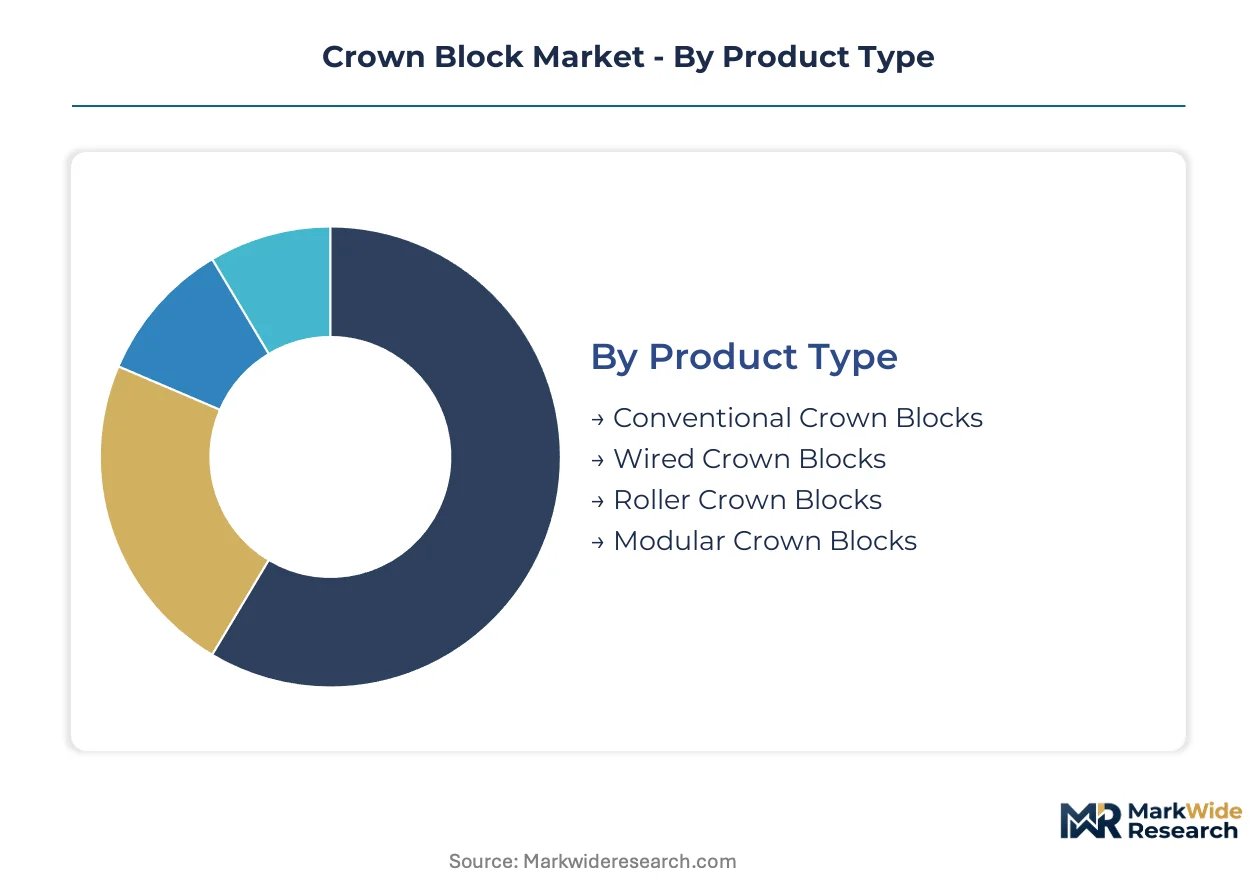
Crown block procurement patterns diverge sharply across product architectures and deployment contexts. Understanding these segment boundaries clarifies where specification pressures and margin compression concentrate most intensely.
Product Type:
Upgrade cycles and replacement timelines vary dramatically by structural design, with offshore operators accelerating retrofits while land contractors prioritize field-assembly speed.
- Conventional Crown Blocks:Welded monolithic frames with cast or fabricated sheave housings rated for 250 to 750 short tons. Demand concentrates in Permian Basin land rig replacement cycles, where API 8C fatigue documentation requirements are forcing accelerated retirement of pre-2020 welded assemblies.
- Wired Crown Blocks:Sensor-embedded configurations transmitting real-time tension data through integrated load cells and telemetry modules. Gulf of Mexico and North Sea drilling contractors specify these for predictive maintenance programs and regulatory reporting obligations.
- Roller Crown Blocks:Bearing-optimized designs reducing friction coefficients in high-cycle hoisting operations.
- Modular Crown Blocks:Bolt-together frame sections enabling single-shift field assembly without heavy-lift cranes.
Conventional crown blocks sit at the top of the volume ranking, with wired crown blocks climbing the fastest.
Installation Type:
Capital intensity and mobility requirements reshape procurement specifications, with drilling contractors balancing asset longevity against rig mobilization frequency.
- Fixed Installation:Permanently mounted assemblies integrated into mast superstructures during original rig construction. Deepwater drillships in the Gulf of Mexico specify these for 25-year asset life extensions under API 4F structural certification.
- Mobile Installation:Skid-mounted or trailer-transported configurations for pad drilling operations. West Texas drilling contractors favor these for 40-foot mast retrofits requiring rapid site-to-site relocation.
- Temporary Installation:Short-duration deployments for workover rigs and well intervention.
- Semi-permanent Installation:Extended-term mounting with planned relocation intervals of 12 to 24 months.
Mobile installations dominate active procurement, with fixed installations commanding the highest unit margins.
Industry:
End-use sector concentration determines specification stringency, with hydrocarbon extraction driving the bulk of rated-load and fatigue-documentation requirements.
- Oil & Gas:Rotary drilling and completion operations requiring API-certified mast-mounted hoisting equipment. Horizontal drilling density across the Permian Basin and Mid-Continent region sustains replacement demand for high-capacity configurations.
- Offshore Drilling:Deepwater and ultra-deepwater operations with integrated load-monitoring mandates. Real-time tension data transmission is displacing manual inspection protocols in North Sea and Gulf of Mexico contract specifications.
- Construction:Heavy-lift applications for infrastructure and industrial projects.
- Mining:Shaft sinking and vertical excavation operations.
Oil and gas applications anchor volume demand, with offshore drilling exhibiting the steepest specification escalation.
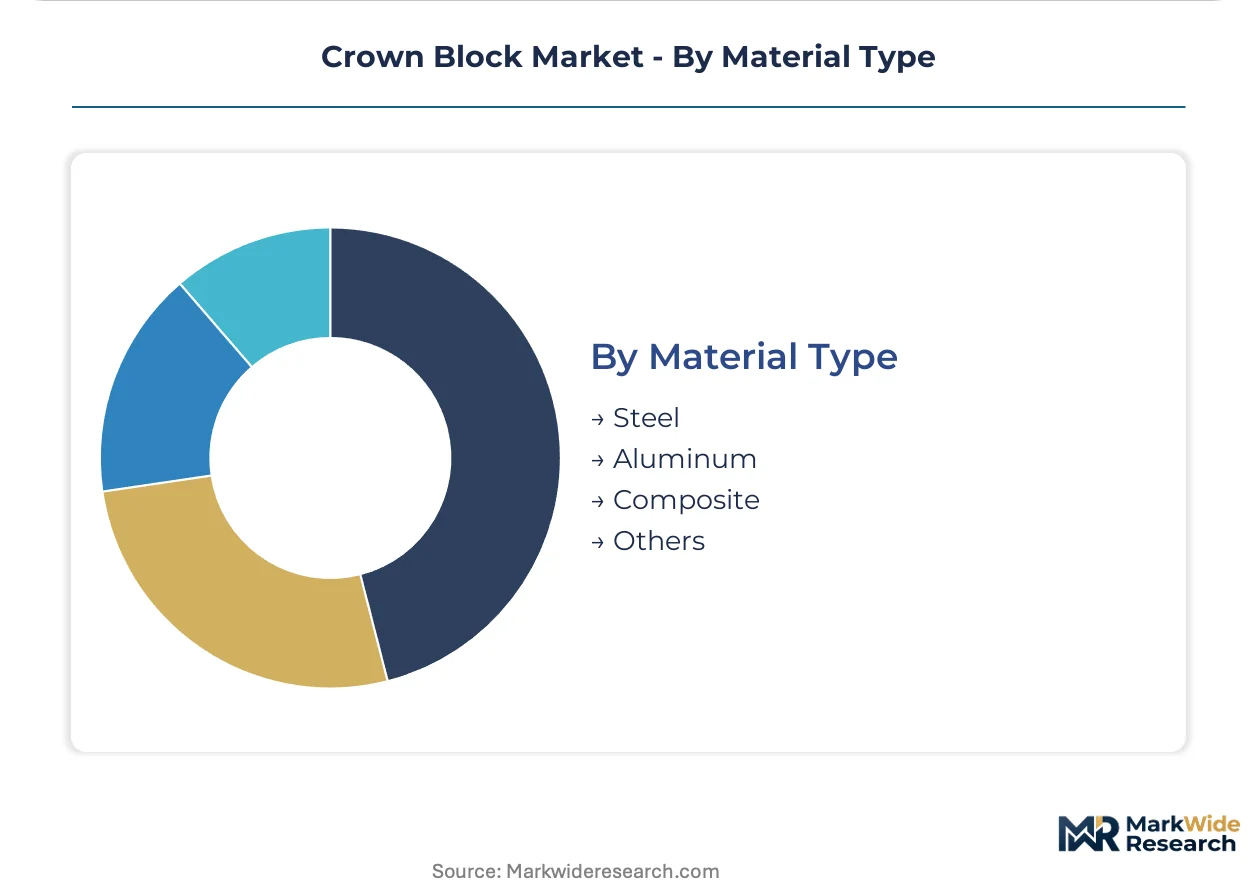
Material Type:
Foundry sourcing and heat-treatment documentation requirements are recalibrating material selection, with emissions traceability protocols favoring suppliers with certified supply chains.
- Steel:Heat-treated alloy forgings and high-grade bearing steels for load-bearing structural members. Chinese domestic rig builders source cost-engineered configurations from Shaanxi province foundries subject to MEE emissions documentation requirements.
- Aluminum:Lightweight alloys for mobile and temporary installations where transport weight constraints dominate.
- Composite:Fiber-reinforced polymer components for corrosion-resistant offshore applications.
- Others:Titanium and specialized alloys for extreme fatigue environments.
Steel retains volume leadership, with composite materials gaining share fastest in offshore specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The crown block industry traces its modern manufacturing lineage to early twentieth-century oilfield equipment fabrication centers in the United States, where derrick-mounted hoisting systems first achieved standardized production scale.
United States
Horizontal drilling density across the Permian Basin and Mid-Continent region sustains replacement demand for high-capacity crown block configurations. OSHA and API 4F structural specifications govern mast-mounted hoisting equipment certification. Houston anchors the Gulf Coast corridor where deepwater drilling contractors accelerate retrofit schedules for pre-2020 crown block assemblies.
China
Domestic rig builders source cost-engineered crown block configurations from Shaanxi province foundries serving shale gas development programs. MEE emissions documentation and material traceability standards tighten heat-treatment certification requirements. Baoji city clusters precision-machining capacity for API-certified export production.
Canada
Oil sands thermal drilling and northern conventional operations require cold-climate-rated crown block assemblies with extended fatigue documentation. Health Canada and provincial regulators align with API 8C proof-load testing protocols for mast-mounted equipment. Calgary concentrates engineering services for modular retrofit specifications.
Norway
North Sea deepwater drilling contractors specify wired crown blocks with integrated load-monitoring for predictive maintenance programs. Petroleum Safety Authority Norway enforces real-time tension data transmission for regulatory reporting compliance. Stavanger clusters offshore equipment refurbishment capacity serving aging platform infrastructure.
United Arab Emirates
ADNOC drilling expansion and regional rig fleet modernization drive demand for high-capacity fixed-installation crown blocks. Emirates Authority for Standardization and Metrology implements API-aligned certification requirements for imported mast-mounted hoisting equipment. Dubai Jebel Ali free zone concentrates aftermarket service infrastructure for Middle East and Africa drilling contractors.
Crown Block Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and aftermarket service density. The vendor base organizes into three functional tiers: integrated rig-package suppliers, specialized crown block fabricators, and regional aftermarket service providers. Strategic differentiation concentrates on API 4F certification speed and modular field-assembly capabilities. Capacity expansion and strategic partnerships represent the dominant competitive vectors as suppliers respond to specification escalation in offshore drilling contracts.
Within the integrated rig-package tier, National Oilwell Varco exemplifies the premium-position archetype through mast-and-block system bundling. Among North American land-focused fabricators, Stewart & Stevenson occupies a service-density position across Texas and Oklahoma operations. Baoji Oilfield Machinery represents the cost-engineered tier serving Chinese domestic rig builders with Shaanxi province manufacturing concentration.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Stewart & Stevenson |
| Baoji Oilfield Machinery |
| American Block |
| Jereh Group |
| Nabors Industries |
| Alco Group |
| ZPEC |
| Lee C. Moore |
| Others |
Value Chain & Pricing Dynamics
API 4F specification revisions mandating enhanced fatigue documentation for mast-mounted hoisting equipment are compressing supplier qualification timelines and forcing procurement teams toward certified fabricators with established heat-treatment records, elevating price premiums for compliant configurations while squeezing margin pools among undocumented foundries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API 4F-certified integrated mast-and-block systems from conventional welded assemblies and cost-engineered Shaanxi province configurations. Price differentiation rests on certification grade and aftermarket service bundling. Cost compression in economy-tier supply is intensifying because Chinese domestic rig builders consolidate procurement volumes. Land contractors in the Permian Basin exhibit highest price sensitivity; offshore drilling contractors in the Gulf of Mexico demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Refurbishment flows from pre-2020 welded-frame crown blocks are creating secondary material streams that feed remanufacturing operations in Houston and Calgary. Manufacturing gravity centers on the United States, China, and Norway. Supply chains draw from heat-treated alloy forgings, high-grade bearing steels, and sensor-embedded telemetry modules. Single-source vulnerability concentrates in Shaanxi province foundry clusters. Distribution runs through rig-package integrators and specialized aftermarket service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with API 8C proof-load testing protocols forcing replacement cycles that sustain demand regardless of drilling activity fluctuations.
For Market Incumbents: Anticipate margin compression from modular field-assembly competitors by deepening API 4F certification speed advantages and anchoring aftermarket service density across the Gulf Coast corridor. Threat substitution from wired sensor-integrated configurations demands accelerated load-monitoring system integration. Capacity addition in Houston-Jebel Ali service corridors represents the priority defensive lever. For New Entrants and Emerging Players: Launch via Gulf Coast corridor aftermarket refurbishment contracts where service infrastructure gaps between Houston and New Orleans create penetrable white space. The most penetrable segment lies in mobile installation retrofits for 40-foot mast configurations. Go-to-market positioning should emphasize single-shift field assembly capabilities against welded-frame replacement timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with modular crown block fabricators possessing certified heat-treatment documentation and established API 4F testing protocols. Long-term viability favors suppliers with backward integration into alloy forging capacity. The signal to watch is offshore drilling contract unbundling of sensor maintenance from original equipment supply.| Strategic Initiative | Industry Significance |
|---|---|
| API 4F Certification Acceleration | Compresses supplier qualification timelines for deepwater rig-package contracts. |
| Modular Field-Assembly Capacity Buildout | Reduces crane-time requirements for Permian Basin drilling contractors. |
| Wired Sensor Integration Partnership | Captures predictive maintenance contracts in North Sea regulatory environments. |
| Heat-Treatment Documentation Investment | Aligns with MEE emissions traceability mandates for Chinese domestic supply. |
| Gulf Coast Aftermarket Service Expansion | Closes infrastructure gaps between Houston and New Orleans refurbishment demand. |
Study Parameters
Direct dialogue with drilling contractors, rig-package procurement managers, aftermarket service heads, and API certification engineers grounded qualitative findings, cross-referenced with customs trade records, SEC equipment supplier filings, OSHA incident databases, and MEE emissions documentation. Secondary validation drew from foundry capacity surveys and rig fleet utilization reports. Bottom-up and top-down triangulation reconciled segment-level demand with aggregate market sizing.
Bottom-up modeling aggregated individual rig-retrofit programs and new-build mast configurations across product type, installation category, and end-use sector dimensions. Top-down validation applied energy sector capital expenditure patterns and drilling contractor fleet modernization schedules. CAGRs derived from regression analysis against rig count forecasts and replacement cycle assumptions. Industry-specific inputs incorporated API specification revision implementation timelines and MEE compliance phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility and regulatory enforcement intensity variations. Forecasts reflect assumptions regarding specification adoption rates and foundry capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Brazil Oil and Gas Midstream Market