
 Indonesia Oil and Gas Market | 2026-2036
Indonesia Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Oil and Gas Market Outlook
Modular refinery configurations and bundled upstream-downstream service packages is broadening buyer choice among Indonesian operators. Pertamina leverages its state-owned retail network and integrated refining footprint to anchor domestic supply security. MedcoEnergi competes through independent upstream specialization across mature and frontier basins. ExxonMobil sustains deepwater exploration leadership in the Kangean and Natuna regions through advanced seismic and drilling partnerships.
Indonesia oil and gas encompasses crude petroleum, natural gas, and condensate extraction together with processing, transport, and refining infrastructure spanning onshore, shallow-water, and deepwater environments; the sector functions as primary feedstock for power generation, petrochemical manufacturing, and transport fuel supply across the archipelago. Upstream activity dominates capital deployment given undeveloped reserves in frontier basins, while downstream refining faces structural margin pressure from aging infrastructure and import dependency for specification fuels. Enhanced Oil Recovery technology represents the fastest-growing service category as operators target recovery rates below regional averages in mature fields.
Indonesia's Ministry of Energy and Mineral Resources (MEMR) enforces production-sharing contract terms and fuel quality standards that shape operator investment timelines and equipment procurement decisions. BIS-equivalent technical standards and SKK Migas oversight of cost recovery mechanisms further constrain project economics and partner selection criteria. Stakeholders must monitor regulatory uncertainty around domestic market obligation rules and carbon pricing implementation as these mechanisms will determine field development sequencing and capital allocation priorities across the archipelago.
Market Dynamics
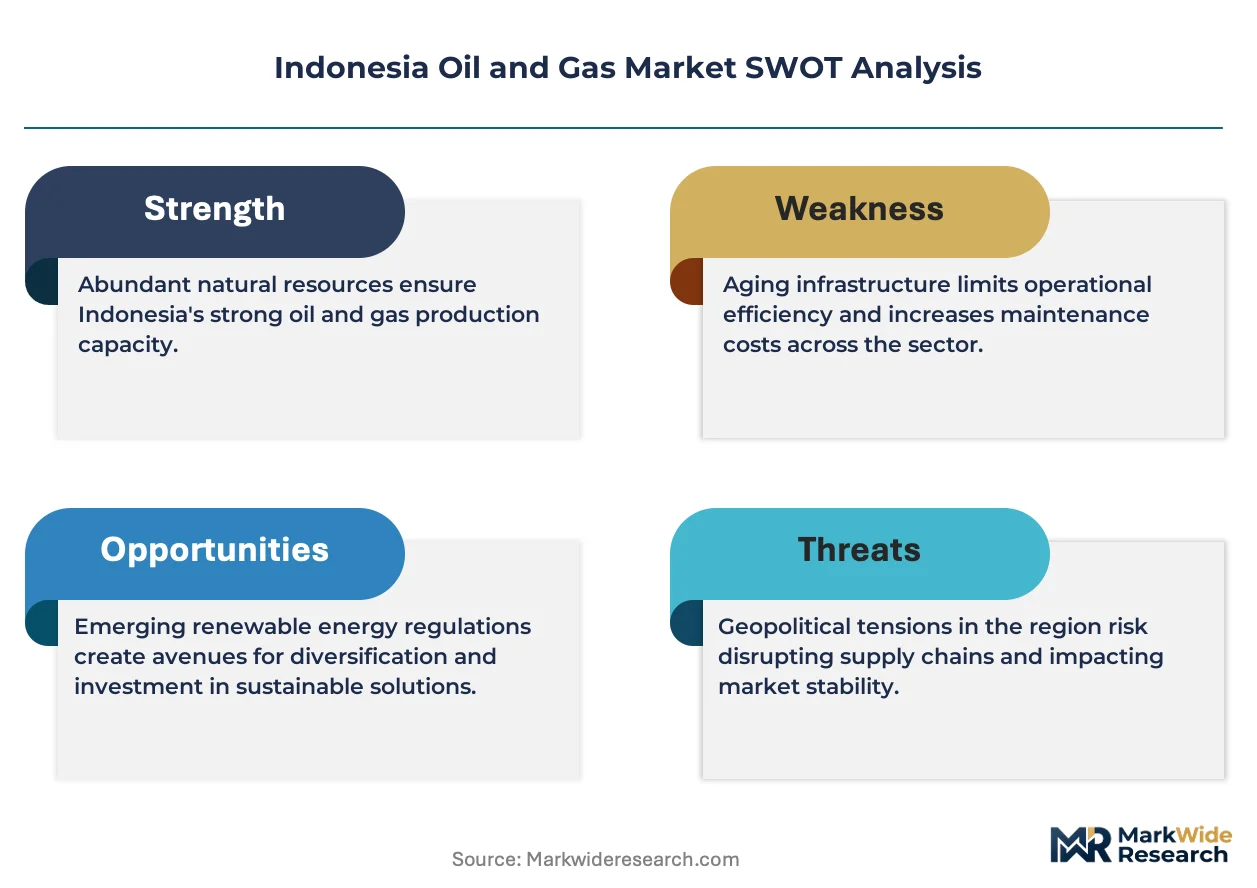
Indonesia's oil and gas sector faces a structural squeeze between declining crude output from mature Sumatran basins and MEMR-mandated fuel quality upgrades that require refinery reconfiguration. Operators must balance cost recovery timelines against domestic market obligations while frontier deepwater projects absorb disproportionate capital.
Growth Catalysts
- Enhanced Oil Recovery deployment:Polymer flooding and CO2 injection techniques are unlocking stranded reserves in Duri and Minas fields where natural decline rates exceed regional averages. SKK Migas cost recovery provisions incentivize tertiary recovery investments.
- Java-Bali industrial clustering:Petrochemical and power generation facilities concentrate fuel demand along the northern coastal corridor, creating predictable offtake volumes for refinery operators.
- MEMR Regulation No. 62/2020:Cleaner diesel and gasoline specifications are forcing infrastructure replacement that expands domestic refining capacity and reduces import dependency for specification fuels.
Market Restraints
- Import dependency for light sweet crude:Aging refineries require low-sulfur feedstocks that domestic heavy crude cannot satisfy, exposing margins to Singapore benchmark volatility and currency fluctuation.
- Frontier basin capital intensity:Natuna and Kangean deepwater developments require subsea production systems and floating facilities that strain project economics at current production-sharing contract terms.
- Carbon pricing uncertainty:Pending implementation of emissions trading mechanisms threatens to compress net present values for gas developments previously justified on lower-carbon credentials.
Strategic Opportunities
- East Kalimantan petrochemical integration:Greenfield refinery-petrochemical complexes can capture naphtha and propylene value chains currently served by Singapore and South Korean exporters.
- Carbon capture utilization and storage:Depleted oil fields offer geological sequestration capacity for industrial CO2 streams, creating revenue from emissions compliance markets and enhanced recovery.
- Small-scale LNG distribution:Islanded power and industrial loads in Maluku and Papua present demand for containerized and bunkered natural gas that pipeline networks cannot economically reach.
Industry Challenges
- Subsurface engineering talent scarcity:Reservoir simulation and geoscience expertise concentrates with international operators, constraining Pertamina and local independents in complex field development decisions.
- Legacy refinery asset integration:Cilacap and Balikpapan facilities require simultaneous turnaround coordination with new unit construction, risking supply disruptions during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Oil and Gas Market |
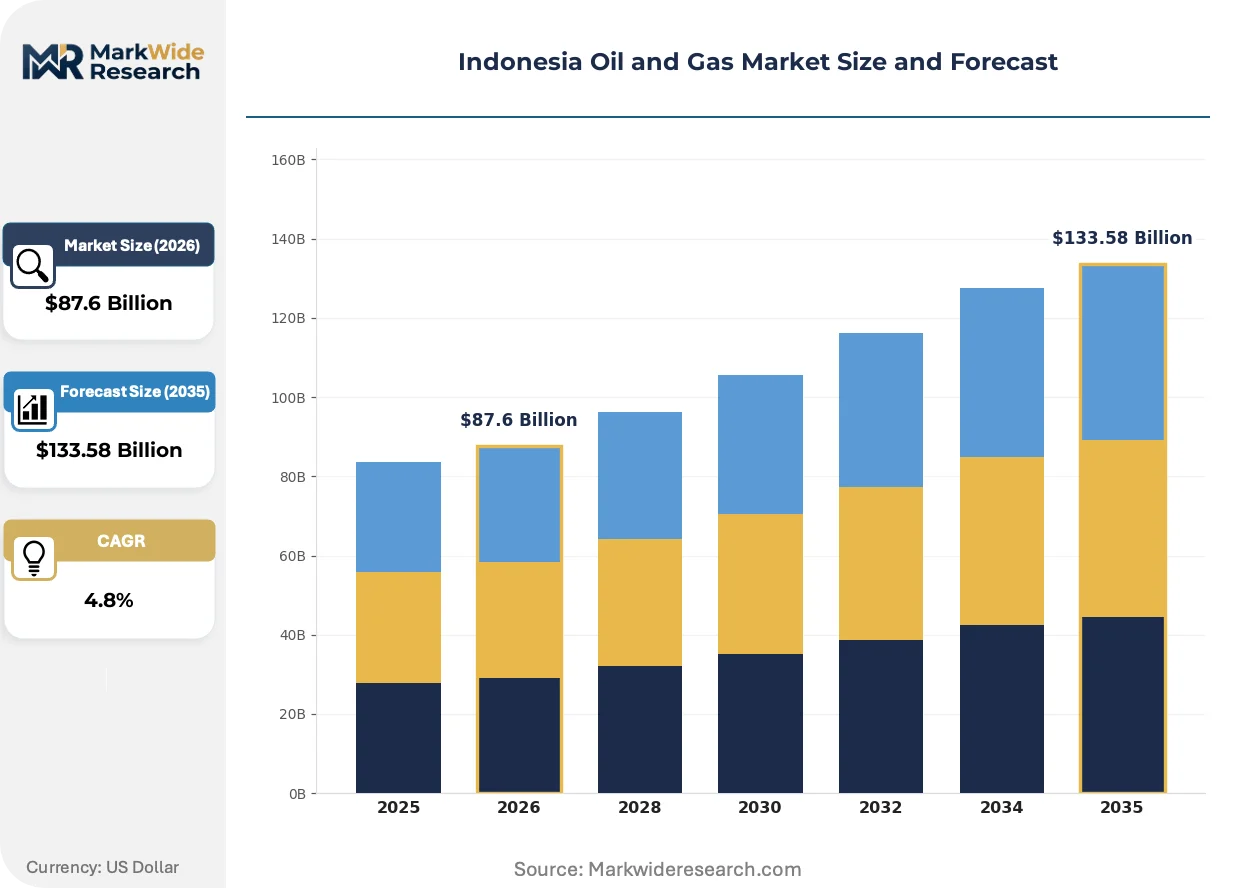
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Integrated Service Type: Exploration, Production, Refining, Distribution End User: Power Generation, Transportation, Industrial, Residential Technology: Seismic Survey, Drilling Systems, Refinery Technologies, Enhanced Oil Recovery |
| Companies Covered | MedcoEnergi, Petronas, Pertamina, Eni, ConocoPhillips, Chevron Pacific Indonesia, ExxonMobil, Inpex, TotalEnergies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Oil and Gas Market Strategic Shifts
Digital subsurface characterization and modular processing architectures are compressing field development timelines while regulatory emissions frameworks force fuel specification convergence. These shifts favor capital-light operators with flexible asset configurations.
Digital twin technology is expanding into reservoir management and production optimization across Indonesia's mature fields. Pertamina and international partners deploy real-time sensor networks and machine learning algorithms to predict equipment failures and optimize artificial lift schedules. This capability is expanding into contract structures that tie service provider compensation to production uplift rather than day-rate fees.
MEMR's domestic market obligation rules are tightening enforcement on gas allocation priority for power generation over liquefied natural gas export. The policy redirects supply toward state electricity utility offtake agreements and compresses marketing flexibility for operators in the Bontang and Tangguh liquefaction facilities. Gas developers are responding by negotiating integrated power purchase agreements that bundle upstream production with generation capacity.
Power sector procurement patterns favor long-term fuel supply agreements with price escalation clauses indexed to Indonesian coal benchmarks rather than oil-linked formulas. State-owned generators in the Java-Bali grid are consolidating supplier panels and demanding inventory management services that shift working capital burden to fuel providers. This concentration is most visible in industrial estate power purchase negotiations where single-source gas agreements replace multi-supplier competition.
Indonesia Oil and Gas Market Segmentation
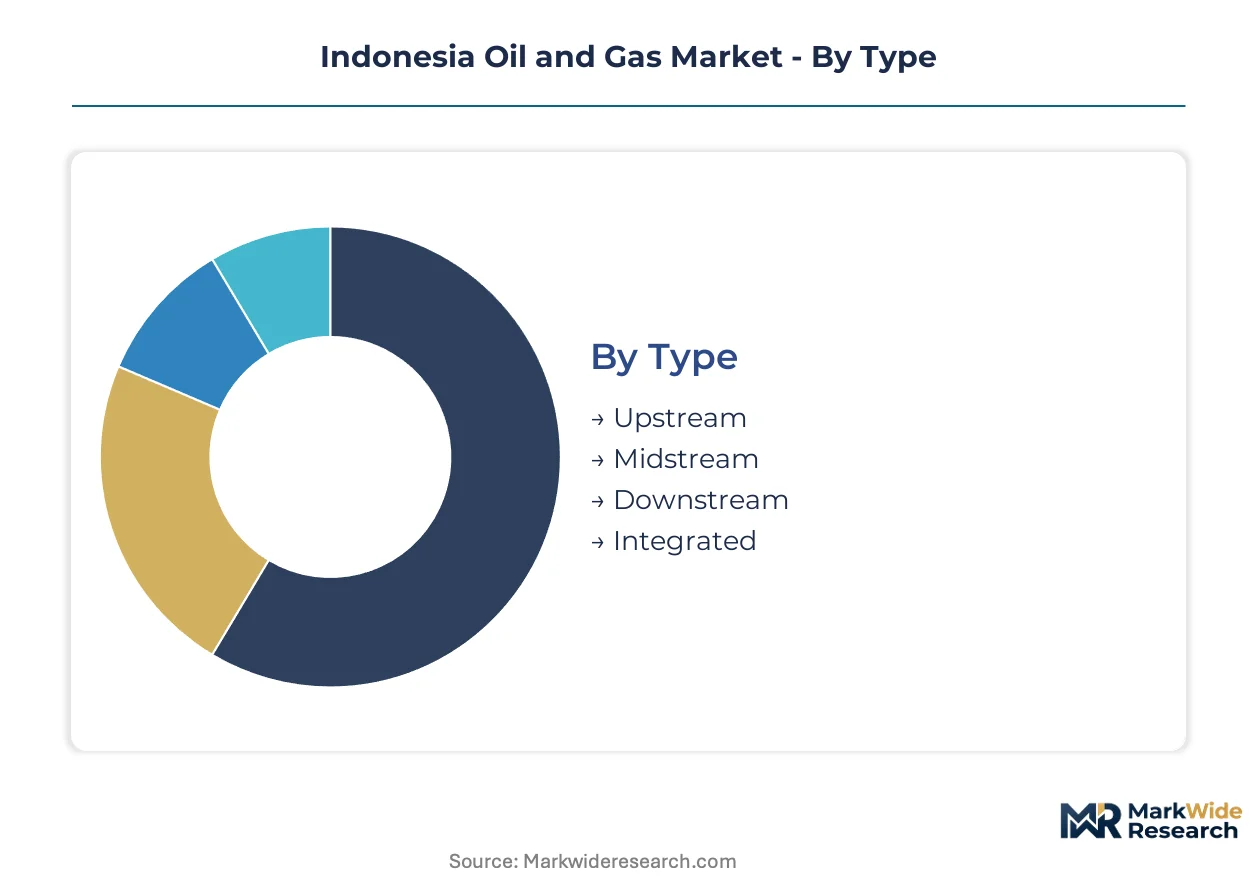
Segmentation reveals how capital flows concentrate across Indonesia's oil and gas value chain. Each dimension exposes distinct procurement patterns, regulatory exposure, and margin structures that shape operator strategy.
Type:
Upstream activity dominates capital deployment across the archipelago's producing basins.
- Upstream:Exploration and production operations span Sumatra's mature Duri and Minas fields, offshore Mahakam, and frontier Natuna deepwater blocks. SKK Migas cost recovery mechanisms and production-sharing contract terms determine project economics. Operators face natural decline rates exceeding regional averages in legacy fields.
- Midstream:Pipeline networks, storage terminals, and LNG liquefaction facilities bridge extraction and consumption centers. Bontang and Tangguh export terminals anchor Indonesia's position in Asian LNG supply. Domestic market obligation rules increasingly constrain export flexibility.
- Downstream:Refining capacity concentrates at Cilacap, Balikpapan, and Dumai facilities processing domestic heavy crude and imported light sweet feedstocks. MEMR Regulation No. 62/2020 mandates cleaner fuel specifications requiring unit upgrades.
- Integrated:State-owned Pertamina spans upstream concessions through retail distribution, capturing margin across the value chain. Vertical coordination reduces feedstock procurement risk for refining operations.
Upstream absorbs the bulk of installed capacity; midstream is expanding most quickly.
Service Type:
Service procurement patterns reflect field maturity and infrastructure replacement cycles.
- Exploration:3D seismic surveys and exploratory drilling target undrilled prospects in frontier Kangean and North Sumatra offshore basins. International operators deploy advanced subsea imaging to de-risk deepwater commitments.
- Production:Artificial lift systems, well intervention, and facility maintenance sustain output from aging fields. Digital twin deployment is compressing downtime intervals at Pertamina's mature assets.
- Refining:Hydrocracking, hydrotreating, and sulfur recovery unit upgrades respond to MEMR-mandated Euro 4-equivalent diesel and gasoline standards. Cilacap's residual fluid catalytic cracker expansion exemplifies capacity addition.
- Distribution:Bunkering infrastructure, retail network logistics, and industrial fuel delivery systems serve Java-Bali demand concentration. State electricity utility PLN procurement panels consolidate supplier relationships.
Production services command the largest contract value; refining services are climbing the fastest on regulatory-driven investment.
End User:
Demand concentration in Java-Bali shapes fuel allocation priorities and infrastructure investment.
- Power Generation:PLN and independent power producers consume gas and fuel oil for baseload and peaking capacity across the Java-Bali grid. Domestic market obligation rules prioritize utility offtake over LNG export.
- Transportation:Road freight, aviation, and maritime bunkering drive diesel and jet fuel consumption. Jakarta-Surabaya corridor logistics operators anchor diesel demand.
- Industrial:Petrochemical manufacturers, cement producers, and metal processors in East Java and Banten industrial estates purchase fuel oil and natural gas under long-term supply agreements.
- Residential:LPG distribution through subsidized canister networks reaches households beyond pipeline coverage. Pertamina's retail infrastructure dominates last-mile delivery.
Power generation absorbs the bulk of gas offtake; industrial demand is expanding most quickly on petrochemical capacity additions.
Technology:
Technology procurement concentrates on recovery enhancement and specification compliance.
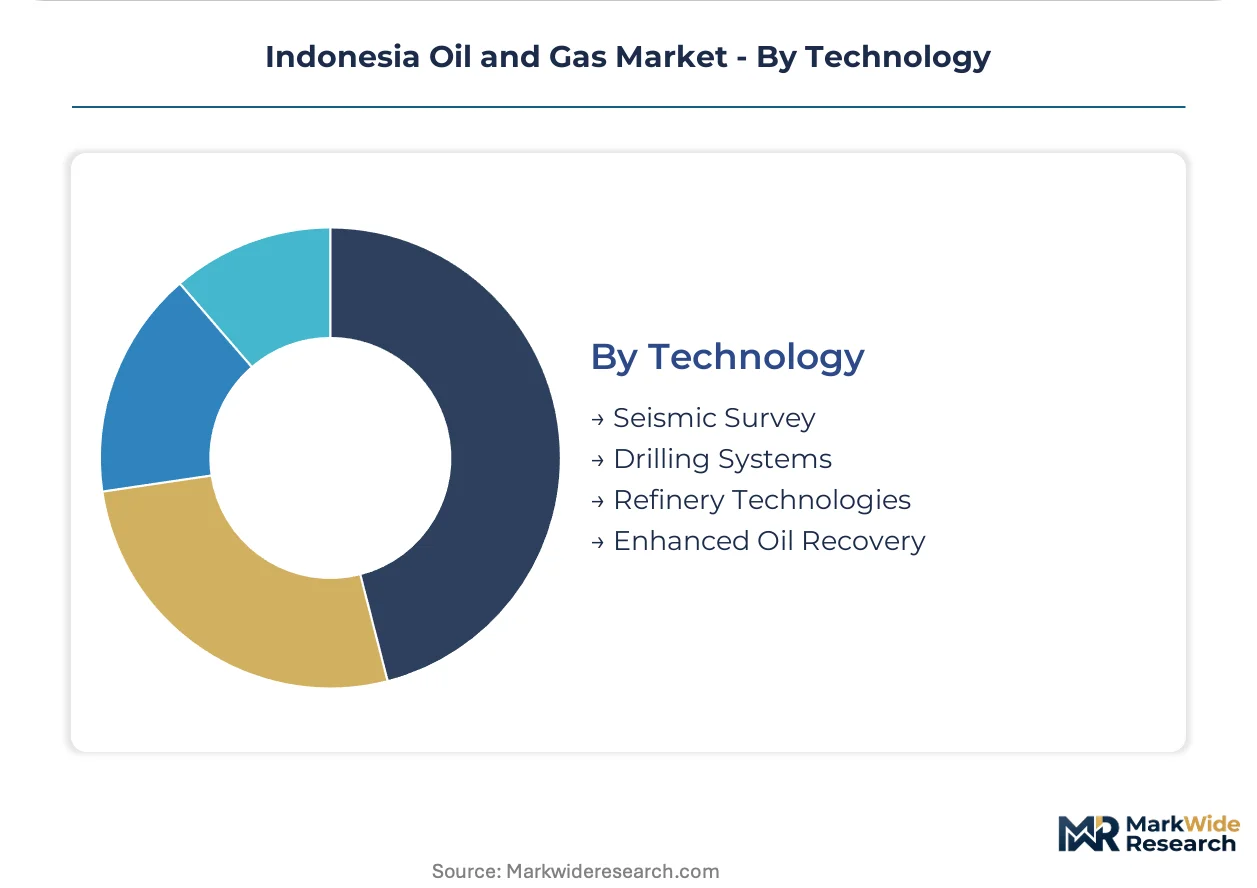
- Seismic Survey:Broadband marine seismic and onshore nodal acquisition systems illuminate complex carbonate and fractured basement reservoirs. ExxonMobil's Natuna deepwater campaigns deploy advanced imaging.
- Drilling Systems:Managed pressure drilling and extended-reach horizontal wells access bypassed pay zones in mature fields. Rig availability constraints periodically delay development timelines.
- Refinery Technologies:Residue upgrading, desulfurization, and octane enhancement units process heavier, higher-sulfur domestic crudes into specification products. Technology licensors compete on energy efficiency guarantees.
- Enhanced Oil Recovery:Polymer flooding, steam injection, and planned CO2-EOR target Duri field's substantial remaining oil in place. SKK Migas incentives accelerate tertiary recovery adoption.
Seismic and drilling systems absorb the bulk of exploration capital; enhanced oil recovery is gaining share fastest on mature field priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's oil and gas production concentrates in mature Sumatran basins and frontier deepwater blocks while consumption clusters in Java-Bali industrial corridors, creating persistent geographic imbalances that shape infrastructure investment priorities and fuel import dependency.
Sumatra
Duri and Minas fields in Riau province sustain heavy crude output through enhanced recovery programs. SKK Migas cost recovery provisions incentivize polymer flooding investments. Pekanbaru serves as the operational hub where Pertamina and international partners coordinate tertiary recovery campaigns.
Java-Bali
Industrial estates in Banten and East Java drive diesel and natural gas demand for petrochemical and power generation facilities. MEMR Regulation No. 62/2020 mandates cleaner fuel specifications. The Cilacap refinery complex processes domestic heavy crude alongside imported light sweet feedstocks.
Kalimantan
East Kalimantan hosts the Bontang LNG liquefaction facility and emerging refinery-petrochemical integration projects. Domestic market obligation rules redirect gas supply toward state utility offtake. Balikpapan anchors downstream infrastructure serving regional industrial demand.
Natuna Islands
Deepwater gas discoveries in the South China Sea require subsea production systems and floating facilities. ExxonMobil and Inpex hold exploration commitments in the Kangean block. Natuna's geographic isolation complicates pipeline economics and favors LNG export development.
Papua and Eastern Regions
Frontier basins in Papua and Maluku remain underexplored due to infrastructure gaps and security considerations. Small-scale LNG distribution offers alternative supply for islanded power loads. Tangguh facility operators negotiate integrated power purchase agreements bundling upstream production with generation capacity.
Indonesia Oil and Gas Market Competitive Environment
The competitive structure tilts toward state-anchored integrated operators with international specialists occupying frontier exploration niches. Pertamina dominates downstream refining and retail distribution through captive infrastructure. Two strategic archetypes define positioning: vertically integrated national champions leveraging regulatory preference and independent upstream specialists targeting cost recovery optimization. Competitive moves center on production-sharing contract renegotiation and downstream capacity expansion.
Within the integrated operator tier, Pertamina exemplifies state-backed vertical coordination spanning upstream concessions through retail distribution. Among international upstream specialists, ExxonMobil and MedcoEnergi occupy positions at opposite ends of the scale spectrum. ExxonMobil anchors deepwater exploration leadership through advanced seismic partnerships in frontier basins. MedcoEnergi represents independent domestic specialization across mature and frontier concessions. Eni, TotalEnergies, and ConocoPhillips sit within the mid-tier international cohort competing for production-sharing contract renewals.
| Leading Market Players |
|---|
| MedcoEnergi |
| Petronas |
| Pertamina |
| Eni |
| ConocoPhillips |
| Chevron Pacific Indonesia |
| ExxonMobil |
| Inpex |
| TotalEnergies |
| Others |
Value Chain & Pricing Dynamics
Singapore benchmark crude differentials cascade through Indonesia's refining network, compressing margins at Cilacap and Balikpapan facilities that process domestic heavy crude alongside imported light sweet feedstocks. MEMR Regulation No. 62/2020 mandates Euro 4-equivalent fuel specifications, forcing unit upgrades that pass through to industrial buyers in Java-Bali corridors.
Pricing Analysis
Margin tightening in downstream refining reflects feedstock import dependency and currency fluctuation exposure. Contract-based long-term offtake agreements dominate power generation procurement, with PLN panels indexing escalation clauses to Indonesian coal benchmarks rather than oil-linked formulas. Price differentiation hinges on sulfur content compliance and volume scale commitments. State electricity utilities exhibit highest price sensitivity due to consolidated procurement panels, while petrochemical operators absorb premium for specification certainty.
Supply Chain Analysis
Hub-and-spoke distribution patterns center on Balikpapan and Cilacap storage terminals, with coastal bunkering infrastructure serving Java-Bali industrial estates. Supply draws from Saudi Arabia, Nigeria, and Australia for light sweet crude that domestic heavy grades cannot satisfy. Subsea production systems and floating facilities for Natuna deepwater developments rest on specialized fabrication yards in Singapore and South Korea. Single-source vulnerability concentrates in subsea equipment procurement. Downstream distribution runs through Pertamina's captive retail network and PLN consolidated supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's oil and gas sector functions as a vertical-integration race where control over refining capacity and retail distribution determines margin capture. Players pursue downstream capacity addition to secure feedstock offtake and reduce Singapore benchmark exposure.
For Market Incumbents: Deepen tertiary recovery specialization in Duri and Minas fields through polymer flooding partnerships that SKK Migas cost recovery provisions incentivize. Anchor domestic supply security by expanding Cilacap residual fluid catalytic cracker capacity ahead of MEMR specification deadlines. Carbon pricing uncertainty threatens gas development net present values; integrate carbon capture utilization and storage into enhanced oil recovery contracts to capture emissions compliance revenue streams.
For New Entrants and Emerging Players: Enter via small-scale LNG distribution for islanded power loads in Maluku and Papua that pipeline networks cannot economically reach. Target containerized natural gas bunkering for industrial estates in Eastern regions where Tangguh facility operators seek integrated power purchase agreements. Bundle upstream production with generation capacity to bypass domestic market obligation constraints on export flexibility.
For Investors and Strategic Acquirers: Distressed-cycle entries favor independent upstream specialists with mature field portfolios in Sumatra basins where natural decline rates exceed regional averages. Long-term viability across the analysis window hinges on production-sharing contract renegotiation timing and refinery-petrochemical integration completion in East Kalimantan. Watch MEMR carbon pricing implementation announcements as inflection indicator for gas development capital allocation priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Deployment | Polymer flooding in Duri field unlocks stranded reserves under SKK Migas cost recovery incentives. |
| Refinery-Petrochemical Integration | East Kalimantan complexes capture naphtha value chains currently served by Singapore exporters. |
| Carbon Capture Utilization and Storage | Depleted oil fields offer geological sequestration for industrial CO2 streams and enhanced recovery revenue. |
| Small-Scale LNG Distribution | Containerized supply reaches Maluku and Papua islanded loads beyond pipeline economics. |
| Production-Sharing Contract Renegotiation | Cost recovery timeline adjustments determine frontier deepwater project viability in Natuna blocks. |
Study Parameters
Multi-period observation of production-sharing contract terms, refinery capacity utilization rates, and MEMR regulatory filing patterns anchored the trend analysis, supplemented by interviews with upstream project developers, refinery operations managers, SKK Migas cost recovery specialists, and PLN fuel procurement officers. Secondary validation drew from SKK Migas annual reports, MEMR regulation databases, IEA Southeast Asia energy outlooks, and customs crude import records. Bottom-up field-level production estimates and top-down sector value triangulation cross-checked forecast outputs.
Segment-weighting applied upstream, midstream, downstream, and integrated operator categories against service type, end user, and technology dimensions. Fuel source, project scale, and regional grid type further stratified the analytical framework across the projection horizon. CAGRs derived from historical production decline curves, refinery throughput expansion schedules, and industrial demand growth trajectories in Java-Bali corridors. Forecast inputs incorporated MEMR domestic market obligation enforcement patterns and cleaner fuel specification compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon pricing implementation delays or production-sharing contract renegotiation deadlocks. Forecasts reflect assumptions regarding SKK Migas cost recovery continuity and MEMR regulatory enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Drilling Services Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Crown Block Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Dissolvable Frac Plug Market