
 Commercial Vehicle Foundation Brakes Market | 2026-2036
Commercial Vehicle Foundation Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Foundation Brakes Market Outlook
Heavy-duty specification-tier upgrades is rotating demand toward advanced friction formulations and thermal-resistant drum assemblies. Meritor, Inc. anchors North American fleet retrofit programs with integrated air brake modules. Knorr-Bremse AG dominates European OEM supply chains through proprietary disc brake architectures. ZF Friedrichshafen AG leverages mechatronic actuation expertise to extend its position in automated braking integration.
Commercial vehicle foundation brakes are mechanical friction devices—typically comprising cast iron drums or ventilated rotors, bonded linings with non-asbestos organic or semi-metallic compositions, and S-cam or air-actuated mechanisms—engineered to decelerate and immobilize trucks, buses, and trailers under loaded operating conditions. Drum brakes retain substantial share in North American heavy-duty applications due to lower per-axle cost and established service infrastructure, though disc brakes are gaining penetration in European bus and premium truck platforms where thermal fade resistance commands priority. Fleet operators and OEMs represent divergent margin pools: fleet procurement emphasizes lifecycle cost and remanufacturing compatibility, while OEM channels prioritize weight reduction and electronic integration.
NHTSA's Federal Motor Vehicle Safety Standards and the EPA's Phase 3 emissions framework jointly shape brake system design through stopping-distance mandates and indirect fuel-efficiency incentives. The EU's F-Gas Regulation and ECE R90 homologation requirements constrain aftermarket friction material composition and cross-border parts circulation. Stakeholders must monitor regulatory divergence between North American and European thermal-performance test protocols when allocating R&D and homologation budgets.
Market Dynamics
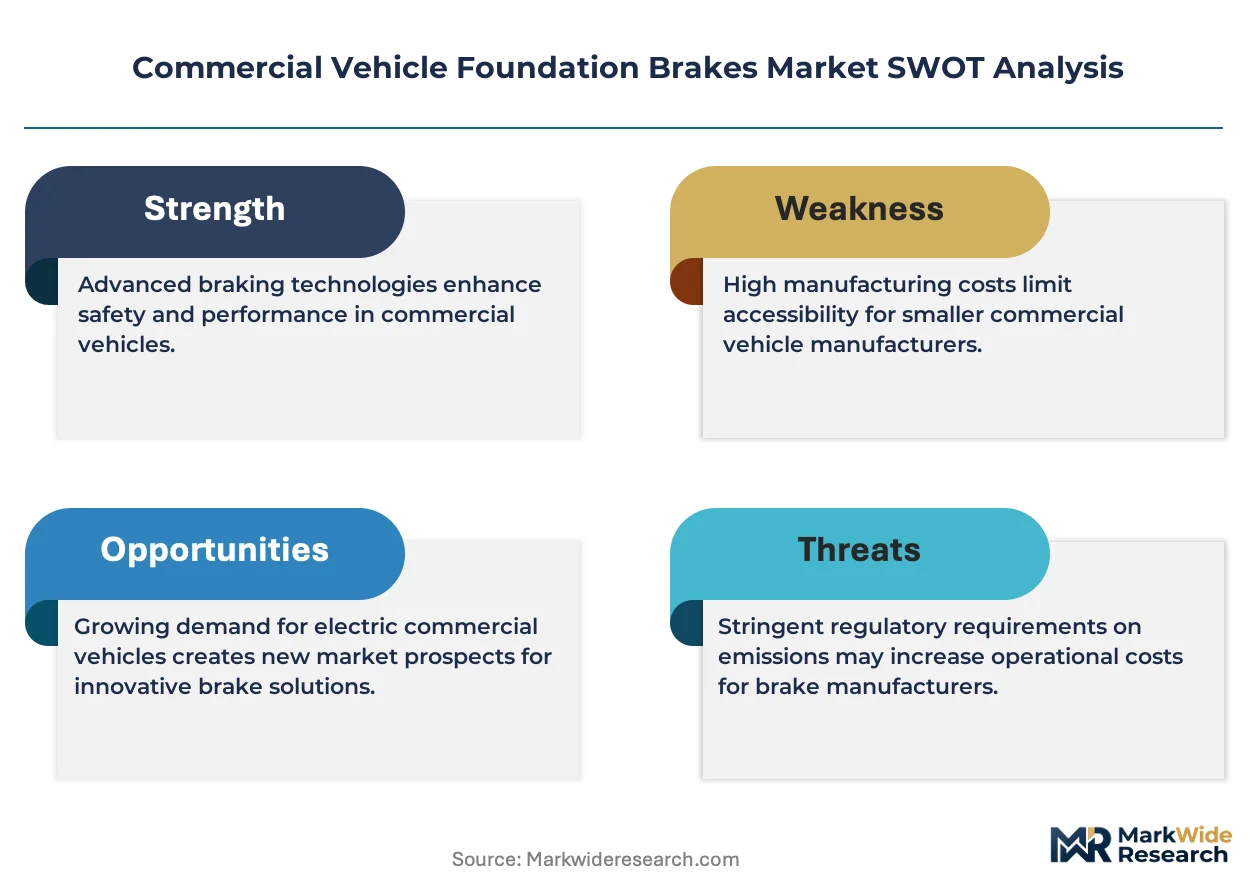
EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency mandates are compressing brake system design cycles, forcing simultaneous thermal-performance upgrades and weight-reduction targets across heavy-duty truck platforms.
Growth Catalysts
- Regulatory stringency:NHTSA stopping-distance mandates and EPA Phase 3 emissions frameworks are mandating friction material upgrades across Class 8 vehicle fleets.
- Fleet replacement cycles:Long-haul freight carriers operating heavy-duty trucks are accelerating brake system refresh schedules to preempt compliance penalties.
- Material science advances:Non-asbestos organic and semi-metallic formulations with enhanced thermal fade resistance are penetrating premium truck specifications.
Market Restraints
- Cast iron input volatility:Drum brake foundries face margin pressure from scrap metal price swings and energy-intensive smelting costs.
- Supply concentration:European OEM supply chains depend heavily on proprietary disc brake architectures from a narrow supplier base.
- Technical limitation:Air-actuated S-cam mechanisms in drum assemblies struggle to match disc brake thermal recovery rates under repeated high-load braking.
Strategic Opportunities
- Automated braking convergence:Integration of mechatronic actuation with electronic stability control systems opens retrofit potential in aging fleet vehicles.
- Remanufacturing channels:Fleet procurement emphasizing lifecycle cost is expanding secondary markets for rebuilt drum assemblies and relined friction components.
- Bus platform electrification:Urban transit authorities are specifying ventilated disc configurations with regenerative braking compatibility.
Industry Challenges
- Homologation timeline compression:ECE R90 certification requirements for aftermarket friction materials are extending product validation cycles.
- Legacy fleet integration:Electronic braking system retrofits face mechanical incompatibility with pneumatic architectures in pre-2010 vehicles.
- Technical workforce gaps:Air brake diagnostics and mechatronic troubleshooting skills are scarce among service technicians in rural maintenance depots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Foundation Brakes Market |
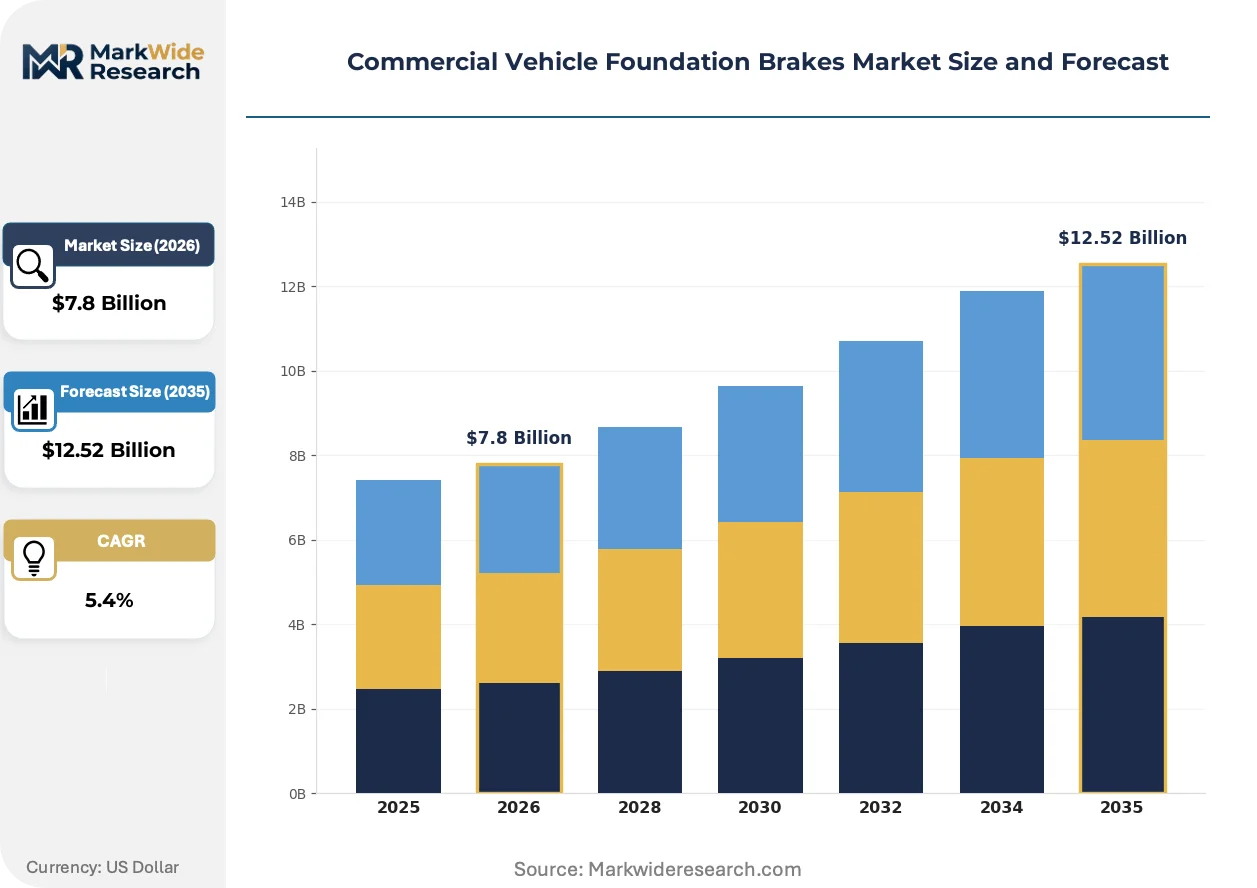
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Brakes, Disc Brakes, Air Brakes, Hydraulic Brakes Application: Heavy-Duty Trucks, Buses, Trailers, Construction Equipment End User: Fleet Operators, OEMs, Aftermarket Suppliers, Leasing Companies Installation Type: Original Equipment, Replacement, Retrofitting, Rebuilding |
| Companies Covered | ZF Friedrichshafen AG, Meritor, Inc., Knorr-Bremse AG, Continental AG, Robert Bosch GmbH, Brembo SpA, Akebono Brake Industry Co., Haldex, Nissin Kogyo Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Foundation Brakes Market Strategic Shifts
Foundation brake architectures are bifurcating between thermal-optimized disc systems for premium platforms and cost-engineered drum assemblies for volume heavy-duty applications. This divergence is reshaping R&D allocation and supplier specialization.
Ventilated disc brake configurations with composite rotor materials are supplanting traditional cast iron drums in European bus and premium truck segments. Fleet operators prioritizing thermal fade resistance are specifying these architectures despite per-axle cost premiums. The shift is compressing demand for conventional drum brake R&D while expanding mechatronic integration budgets.
EU F-Gas Regulation constraints on fluorinated greenhouse gases are forcing friction material suppliers to reformulate bonding agents and eliminate certain resin systems. Brake pad manufacturers serving cross-border aftermarket channels must now maintain separate inventory streams for EU-compliant and non-EU formulations. North American suppliers are monitoring these compositional precedents for potential EPA adoption.
Long-haul freight carriers are unbundling brake maintenance from full-service leasing contracts to capture remanufacturing economics directly. Third-party brake specialists are displacing OEM-affiliated service networks in high-mileage fleet accounts. This channel fragmentation is most pronounced among United States-based Class 8 operators managing internal maintenance shops.
Commercial Vehicle Foundation Brakes Market Segmentation
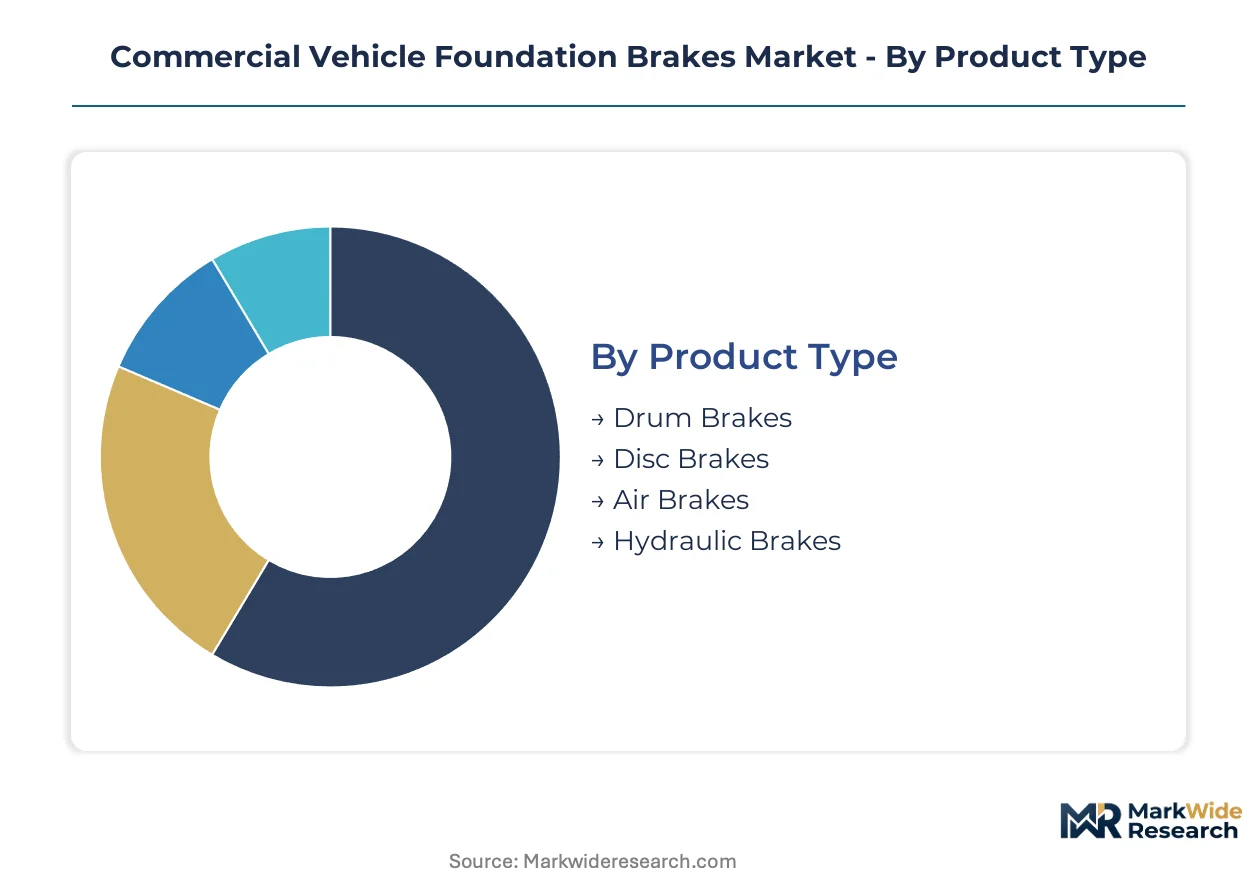
Foundation brake procurement patterns diverge sharply between OEM specification cycles and fleet-driven replacement demand. Understanding these segment boundaries clarifies where thermal-performance upgrades concentrate versus where cost-engineered volumes dominate procurement budgets.
Product Type:
EPA Phase 3 emissions frameworks and NHTSA stopping-distance mandates differentiate thermal-performance requirements across brake architectures, concentrating R&D investment where regulatory thresholds are tightest.
- Drum Brakes:Cast iron drum assemblies with S-cam actuation retain dominance in Class 8 heavy-duty applications due to lower per-axle cost and established remanufacturing infrastructure. Long-haul freight carriers operating in the United States specify these architectures for lifecycle cost control despite thermal fade limitations under repeated high-load braking.
- Disc Brakes:Ventilated rotor configurations with composite friction materials command premium positioning where thermal recovery rates determine specification. European bus platforms and North American premium truck segments specify these systems, driven by ECE R90 homologation requirements and urban transit authority procurement standards.
- Air Brakes:Pneumatic actuation systems serve as the dominant power transmission method for heavy-duty commercial vehicles across North American fleets.
- Hydraulic Brakes:Fluid-actuated mechanisms occupy lighter-duty commercial applications and specialized equipment categories outside long-haul freight.
Drum brakes handle the majority of throughput; disc brakes are expanding most quickly on share.
Application:
Operating duty cycles and load profiles determine brake specification intensity, with severe-service applications demanding advanced thermal management.
- Heavy-Duty Trucks:Class 8 vehicles operating at gross combination weights above 33,000 pounds require friction materials engineered for sustained downhill braking and thermal cycling. Fleet operators managing these assets prioritize remanufacturing compatibility and service interval predictability over absolute performance metrics.
- Buses:Urban transit platforms with stop-and-go duty cycles specify ventilated disc configurations with regenerative braking integration potential. Transit authorities in cities with steep topography mandate enhanced thermal fade resistance, compressing demand for conventional drum architectures.
- Trailers:Non-powered axles in combination vehicles require brake systems optimized for synchronization with tractor units and reduced maintenance access.
- Construction Equipment:Off-highway applications subject to contamination and irregular loading patterns utilize sealed drum assemblies and specialized friction formulations.
Heavy-duty trucks anchor procurement volumes; buses are gaining share fastest on electrification tailwinds.
End User:
Procurement authority fragmentation between factory-installed specification and post-sale channel control reshapes margin capture across the value chain.
- Fleet Operators:Asset owners managing internal maintenance shops unbundle brake service from full-service leases to capture remanufacturing economics directly. These stakeholders emphasize lifecycle cost modeling and relined friction component sourcing over OEM-branded replacement parts.
- OEMs:Vehicle manufacturers prioritize weight reduction and electronic integration compatibility in original specification, driving demand for mechatronic actuation and sensor-embedded brake modules.
- Aftermarket Suppliers:Independent distributors and jobbers serve fragmented repair shop networks with ECE R90-certified friction materials and rebuilt drum assemblies.
- Leasing Companies:Full-service lessors retain brake maintenance responsibility but face margin pressure from fleet self-maintenance trends.
Fleet operators command the largest share of replacement demand; aftermarket suppliers are climbing fastest on channel fragmentation.
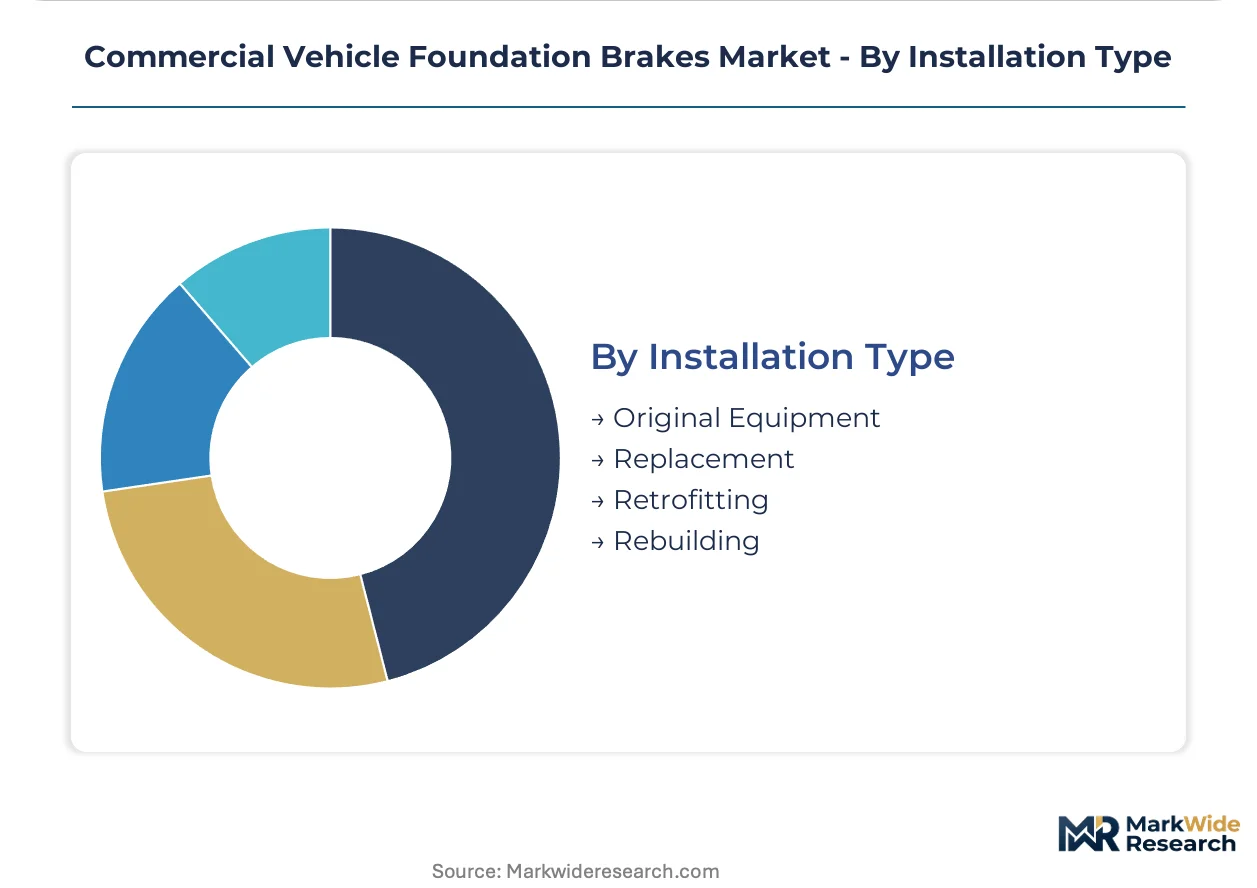
Installation Type:
Asset age distribution and regulatory compliance timelines determine whether brake expenditure flows to new specification or retrofit activity.
- Original Equipment:Factory-installed brake systems on new vehicle platforms incorporate electronic stability control integration and weight-optimized designs. OEM channels concentrate specification authority for automated braking convergence features.
- Replacement:In-service brake component exchange follows predictive maintenance schedules or failure-driven interventions, with friction materials and drum assemblies dominating part turnover.
- Retrofitting:Electronic braking system upgrades face mechanical incompatibility with pneumatic architectures in pre-2010 vehicles, limiting addressable fleet segments.
- Rebuilding:Remanufactured drum assemblies and relined shoes capture procurement preference where lifecycle cost modeling favors overhauled components versus new manufacture.
Replacement installations absorb the greatest volume; retrofitting presents the steepest expansion trajectory on automated braking convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement elasticity varies sharply by geography. United States buyers prioritize lifecycle cost over thermal performance, while German and Japanese specifications demand premium disc architectures regardless of per-axle premiums.
United States
Class 8 long-haul freight carriers dominate replacement demand, accelerating brake refresh schedules to preempt NHTSA compliance penalties. EPA Phase 3 greenhouse gas standards indirectly pressure friction material selection through fuel-efficiency incentives. Detroit-Warren corridor foundries supply cast iron drum assemblies to major fleet operators managing internal maintenance shops.
Germany
Premium truck OEMs specify ventilated disc configurations with composite friction materials for export markets. KBA type-approval requirements and EU F-Gas Regulation constraints shape bonding agent formulations. Stuttgart industrial cluster houses disc brake architecture specialists serving European bus platforms with regenerative braking compatibility.
China
Domestic heavy-duty truck production volumes drive drum brake throughput despite disc penetration in premium segments. MIIT fuel consumption standards and GB homologation protocols govern thermal performance testing. Shandong Province foundries concentrate cast iron drum manufacturing for both domestic fleet replacement and export aftermarket channels.
Japan
Urban transit authorities specify disc brake systems with enhanced thermal recovery for mountainous topography. METI energy efficiency guidelines influence brake system weight reduction targets in OEM specification. Aichi Prefecture manufacturing belt supplies mechatronic actuation components for automated braking integration programs.
India
Cost-engineered drum assemblies retain dominance across heavy-duty truck and bus segments serving price-sensitive fleet operators. BIS certification requirements and axle load norms govern friction material durability standards. Tamil Nadu automotive corridor hosts brake component suppliers targeting both domestic replacement demand and Southeast Asian export markets.
Commercial Vehicle Foundation Brakes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the foundation brake value chain. European and North American suppliers concentrate on mechatronic integration and thermal-optimized disc systems, while Asian manufacturers dominate volume drum brake production through scale-driven foundry operations. Three strategic archetypes define competitive positioning: integrated brake module suppliers, specialized friction material formulators, and remanufacturing channel operators. M&A activity targets electronic braking system capabilities, while capacity expansion concentrates in low-cost foundry regions serving aftermarket drum demand.
Within the integrated systems tier, ZF Friedrichshafen AG and Knorr-Bremse AG exemplify divergent geographic anchoring—German-based engineering against European OEM supply chain concentration. Meritor, Inc. occupies a position representing North American fleet retrofit program dominance. Continental AG and Robert Bosch GmbH sit within diversified automotive supplier conglomerates where brake systems represent one vertical among many.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Meritor, Inc. |
| Knorr-Bremse AG |
| Continental AG |
| Robert Bosch GmbH |
| Brembo SpA |
| Akebono Brake Industry Co. |
| Haldex |
| Nissin Kogyo Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for cast iron drum assemblies concentrate procurement leverage among United States long-haul fleets managing internal maintenance shops, compressing margin capture for foundries serving fragmented aftermarket channels. This lead-time band ties directly to how pricing power aggregates with buyers who can warehouse remanufactured components at scale.
Pricing Analysis
After-sales service revenue from relined friction shoes and rebuilt drum assemblies drives lifetime value capture for brake specialists serving North American Class 8 operators. Three-tier pricing structure across premium, standard, and economy levels separates ECE R90-certified formulations from non-certified alternatives and basic relined products. Cost compression in standard-grade drum assemblies is intensifying because Shandong Province foundries are expanding export capacity into aftermarket channels. Fleet operators with predictive maintenance programs exhibit lowest price sensitivity; independent repair shops in rural maintenance depots face acute margin pressure.
Supply Chain Analysis
Strait of Malacca transit risk for bonded friction material imports from Southeast Asian resin suppliers elevates inventory carrying costs for European aftermarket distributors. Geographic supply concentration centers on China for cast iron drum foundries, Germany for ventilated disc brake machining, and the United States for S-cam actuation hardware. Raw material dependencies rest on scrap metal feedstock for drum production, copper wire for pneumatic valve coils, and phenolic resin systems for friction bonding. Single-source vulnerability characterizes proprietary disc brake architectures from narrow European supplier bases. Distribution runs through OEM-affiliated service networks, independent jobber channels, and direct fleet procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American long-haul freight is shifting procurement leverage toward buyers who can unbundle brake maintenance from full-service leases and mandate relined component sourcing.
For Market Incumbents: Consolidate control over remanufacturing channels by acquiring regional brake specialists with established relining operations in the United States Midwest. Backward integration into phenolic resin formulation hedges against EU F-Gas Regulation constraints spreading to North American bonding agent specifications. Automated braking convergence threatens traditional pneumatic architectures; prioritize mechatronic actuation R&D partnerships with Aichi Prefecture component suppliers. For New Entrants and Emerging Players: Differentiate on thermal-performance certification for electrified bus platforms serving Japanese urban transit authorities with mountainous topography requirements. Target aftermarket friction material supply to fragmented independent repair networks in India's Tamil Nadu automotive corridor where OEM-affiliated service penetration remains shallow. Pursue white-label relining partnerships with third-party brake specialists displacing OEM networks in high-mileage United States fleet accounts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates where brake systems represent non-core verticals amid portfolio streamlining pressures. Five-to-ten year viability hinges on mechatronic integration capabilities rather than pure foundry scale. Monitor NHTSA automated braking mandates as inflection indicator for electronic braking system retrofit addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Friction Material Formulation | Captures margin from phenolic resin supply while hedging EU F-Gas regulatory spread. |
| Remanufacturing Channel Acquisition | Locks in fleet procurement preference for relined components over new manufacture. |
| Mechatronic Actuation Partnership | Secures automated braking convergence capability through Aichi Prefecture supplier ties. |
| ECE R90 Certification Investment | Enables cross-border aftermarket access for friction materials serving European bus platforms. |
| Predictive Maintenance Platform Development | Deepens fleet customer stickiness through brake wear monitoring and scheduled refresh algorithms. |
Study Parameters
The analysis maps drum brake foundry operations, disc brake machining centers, friction material formulation plants, and pneumatic actuation assembly facilities, each validated through fleet maintenance directors, aftermarket distributor procurement managers, OEM platform engineers, and remanufacturing facility operators. Primary interview intelligence triangulates against customs trade data for cast iron component flows, EPA Phase 3 regulatory filings, NHTSA stopping-distance compliance records, and vehicle production databases from IHS Markit. Bottom-up unit economics for brake system content per vehicle class reconcile with top-down market sizing across replacement frequency models.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include brake architecture type, vehicle application class, procurement channel authority, and regional regulatory cluster alignment. CAGRs derive from replacement cycle acceleration curves tied to EPA Phase 3 compliance timelines and fleet age distribution analysis. Industry-specific forecast inputs incorporate scrap metal price volatility indices and ECE R90 homologation timeline compression effects.
Material uncertainties — regulatory divergence between North American and European thermal-performance test protocols, sudden scrap metal feedstock price spikes, and automated braking mandate acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about fleet operator maintenance behavior and OEM specification continuity. Practitioners should keep alternative scenarios live as EPA Phase 3 enforcement intensity and mechatronic integration cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Three-Wheeler Market